
 Fresh Fish Market | 2026-2036
Fresh Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Fish Market Intelligence
The EU IUU Regulation is shifting procurement standards across European import channels, compelling suppliers to demonstrate full vessel-to-retail traceability. Trident Seafoods leverages its Alaska-based vertical integration to sustain certified catch documentation for EU buyers. Thai Union Group anchors its competitive position through controlled supply chains across the Pacific and Indian Oceans. Mowi dominates Atlantic salmon farming with integrated hatchery-to-harvest operations that meet stringent third-party sustainability protocols.
Fresh fish comprises unprocessed or minimally processed aquatic species maintained on ice or in chilled conditions from catch to point of sale, with core quality parameters including histamine levels below 50 ppm, flesh temperature at 0-4°C, and time-from-harvest metrics under 72 hours for premium grades. Salmon and tuna command the highest margin pools within product type segmentation due to established sushi and sashimi demand in Asia-Pacific and North American urban centers. Online distribution channels represent the fastest-expanding route as direct-to-consumer platforms bypass traditional wholesale layers, though retail and wholesale still occupy the dominant volume share across developed markets.
The US FDA enforces Hazard Analysis Critical Control Point protocols for seafood safety, while the EU EMA and EFSA coordinate maximum residue limits for contaminants in wild and farmed species. Japan's METI oversees cold chain standards that directly shape market access for imported fresh fish into Tokyo's Tsukiji Outer Market and Osaka's central wholesale hubs. Stakeholders must monitor evolving traceability mandates and species-specific quota negotiations as regulatory fragmentation intensifies between major import jurisdictions.
Market Dynamics
The EU IUU Regulation's traceability mandates are restructuring procurement relationships across European import channels, forcing vessel-level documentation that smaller operators cannot supply. This regulatory pressure concentrates buying power among vertically integrated suppliers with certified cold-chain custody from catch to retail.
Growth Catalysts
- Urban protein transition:Chinese metropolitan consumers are shifting from carbohydrate-heavy diets toward fresh seafood proteins, with premium sashimi-grade species commanding sustained demand in Shanghai and Shenzhen wholesale markets.
- EU IUU Regulation enforcement:The European Union's illegal, unreported, and unregulated fishing framework is tightening import documentation requirements, creating competitive advantage for suppliers with verified catch certificates and blockchain-tracked provenance systems.
- Direct-to-consumer platforms:E-commerce channels are bypassing traditional wholesale auction layers, enabling fishery cooperatives and regional distributors to reach retail buyers without intermediary margin extraction.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly compress operating margins for wild-catch fleets, particularly affecting small-scale operators in the Pacific Northwest and North Atlantic who lack fuel hedging capacity.
- Atlantic salmon supply concentration:Norwegian and Chilean farming operations control the majority of premium-grade Atlantic salmon biomass, creating price-setting power that limits buyer negotiation leverage.
- Frozen substitute proximity:Blast-frozen tuna and salmon products stored at minus sixty degrees Celsius offer extended shelf life and lower spoilage risk, pressuring fresh-format pricing in cost-sensitive foodservice segments.
Strategic Opportunities
- Indian domestic cold-chain buildout:India's expanding refrigerated logistics infrastructure creates first-mover advantage for species-diverse suppliers targeting Mumbai, Chennai, and Bangalore metropolitan wholesale markets.
- Carbon accounting integration:The EU Green Deal's embodied emissions tracking requirements favor suppliers with documented low-carbon harvesting methods, enabling premium positioning for pole-and-line caught tuna and recirculating aquaculture systems.
- Blockchain-IoT convergence:Combined distributed ledger and sensor technologies enable real-time temperature and location verification, satisfying Japanese METI import standards while reducing insurance premiums for cross-Pacific shipments.
Industry Challenges
- HACCP certification timelines:US FDA Hazard Analysis Critical Control Point approval processes for new processing facilities extend twelve to eighteen months, delaying market entry for emerging suppliers targeting American foodservice contracts.
- Histamine testing capacity:Laboratory throughput constraints for scombroid toxin verification create bottlenecks at major import gateways, particularly affecting tuna and mackerel shipments during peak seasonal volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Fish Market |
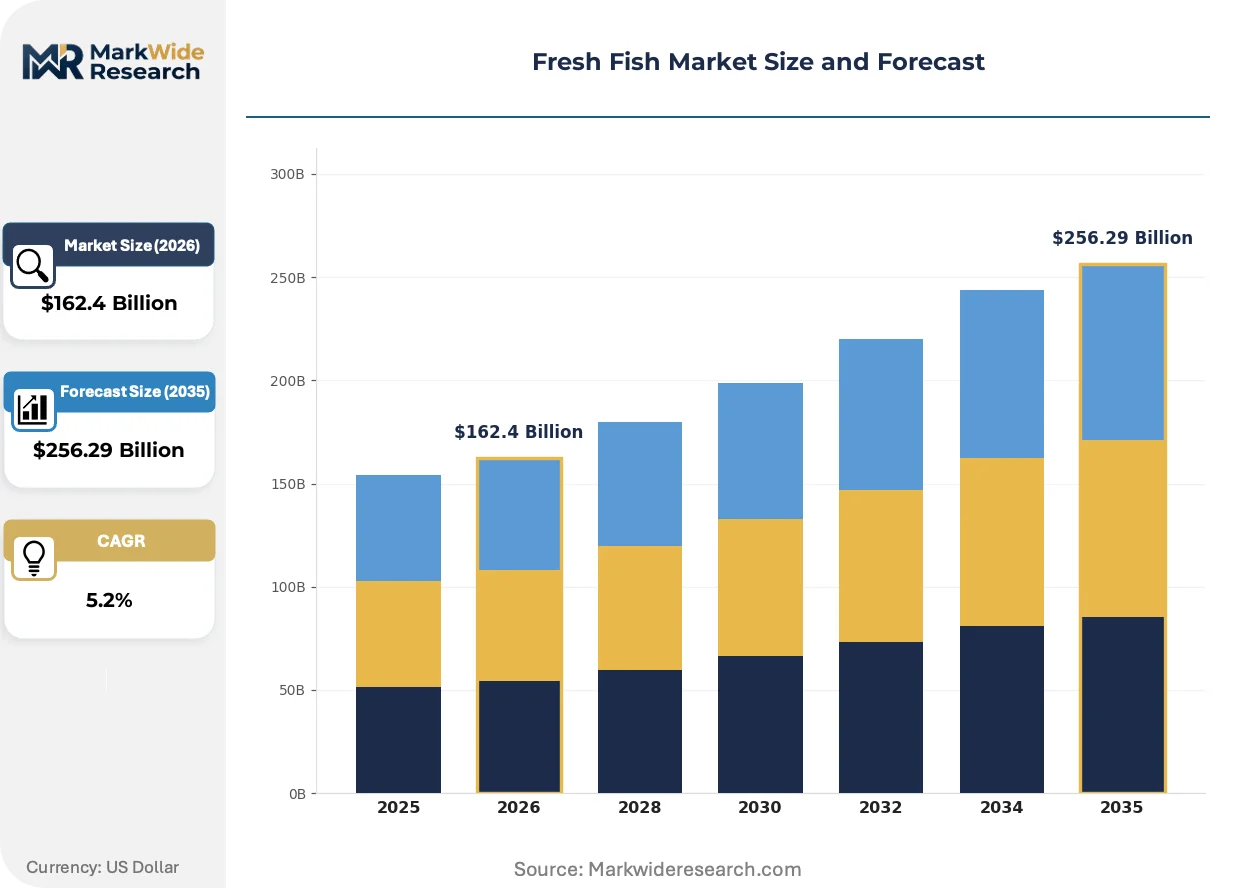
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $256.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon, Tuna, Tilapia, Cod Distribution Channel: Retail, Wholesale, Online, Direct Packaging Type: Vacuum Sealed, Ice Packed, Styrofoam, Canned Customer Type: Restaurants, Supermarkets, Distributors, Consumers |
| Companies Covered | Trident Seafoods, Thai Union Group, High Liner Foods, Clearwater Seafoods, Pacific Seafood Group, Red Chamber, Mowi, Lerøy, Sysco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Fish Market Strategic Shifts & Innovations
Digital traceability infrastructure and alternative protein positioning are actively restructuring competitive advantage in fresh fish supply chains. These developments compress traditional information asymmetries between harvesters and end-buyers.
Blockchain-based provenance tracking is decentralizing quality verification away from centralized auction houses and toward distributed ledger networks accessible to downstream buyers. Major Japanese supermarket chains and North American sushi distributors are adopting these systems to satisfy corporate sustainability reporting requirements. This technology is decentralizing the information advantage that traditional Tsukiji-style wholesale intermediaries previously held over retail and foodservice purchasers.
The EU Green Deal's carbon border adjustment mechanisms are tightening embodied emissions documentation for seafood imports into European markets. Farmed salmon operations with documented renewable energy inputs and wild-catch fleets with fuel-efficient vessel designs gain preferential market access. Norwegian and Scottish suppliers with certified low-carbon production methods are securing long-term supply contracts with EU retail banners ahead of full mechanism implementation.
Urban consumers in Asia-Pacific metropolitan centers are rotating consumption patterns toward species previously considered secondary, driven by sustainability concerns and price sensitivity around bluefin tuna and Atlantic salmon. Mackerel, sardine, and domestic aquaculture species are displacing premium imports in Tokyo and Seoul restaurant procurement. This rotation is most visible in fast-casual dining segments where menu engineering prioritizes cost stability and local sourcing credentials over established luxury positioning.
Fresh Fish Market Segmentation
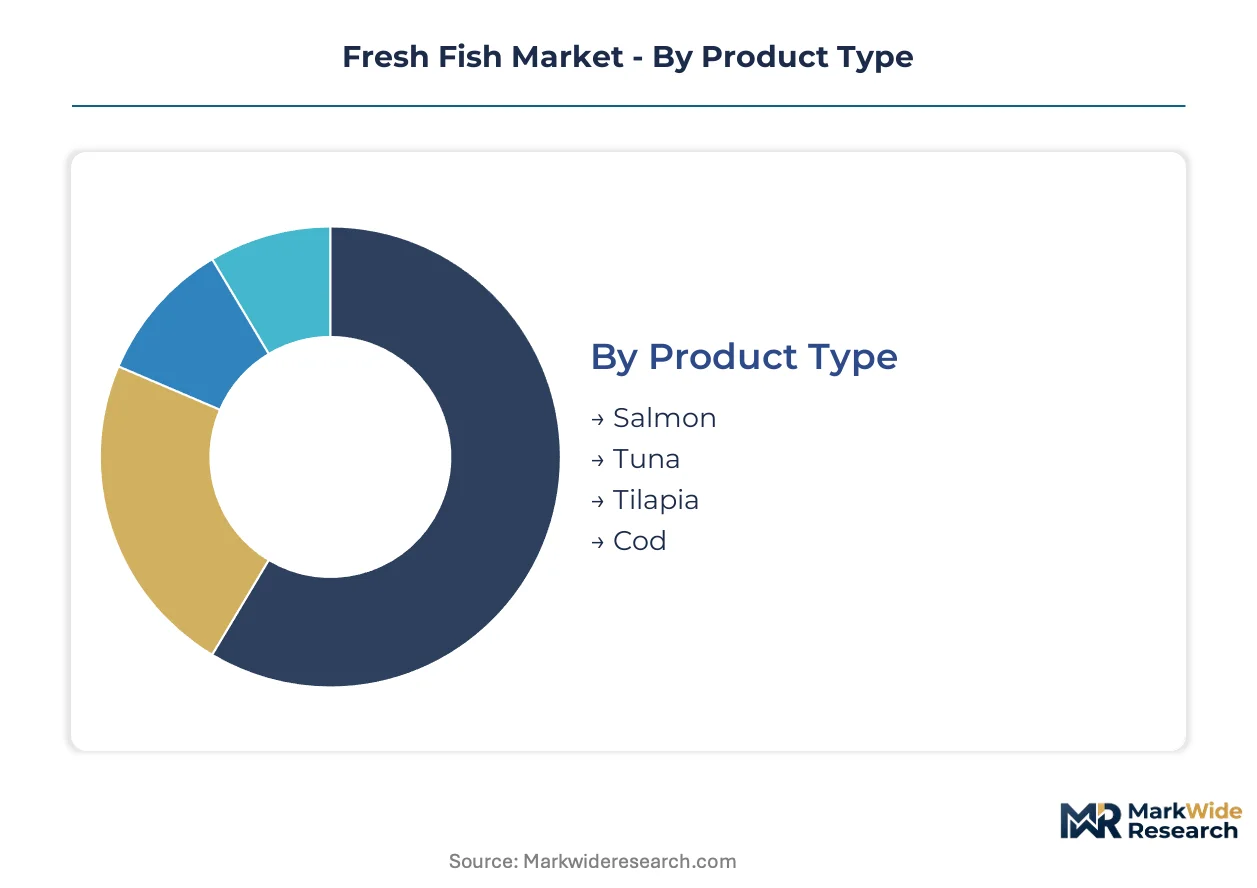
Fresh fish procurement patterns diverge sharply across buyer categories, with temperature tolerance, volume scale, and regulatory documentation requirements creating distinct purchasing behaviors. Suppliers configure cold-chain infrastructure and certification protocols around these segment-specific demands rather than applying uniform service models.
Product Type:
Margin capture and shelf-life sensitivity separate buyers in this category, with premium-grade species commanding dedicated handling protocols and extended documentation trails.
- Salmon:Farmed Atlantic and Pacific varieties dominate high-value foodservice contracts, with flesh color grading (SalmoFan scores 23-34) and harvest-to-retail timelines under 72 hours defining premium positioning. Norwegian and Chilean farming operations supply the majority of biomass for EU and North American sushi distributors, where HACCP-certified processing unlocks restaurant chain procurement.
- Tuna:Sashimi-grade bluefin and yellowfin species require histamine testing below 50 ppm and core temperatures maintained at 0-4°C through vessel-to-retail custody chains. Japanese METI import standards and EU IUU Regulation traceability mandates concentrate buying power among vertically integrated suppliers with blockchain-tracked provenance systems.
- Tilapia:Fresh-format tilapia serves cost-sensitive retail and foodservice segments in emerging markets, with Chinese and Indonesian aquaculture operations supplying volume-driven wholesale channels.
- Cod:North Atlantic and Pacific wild-catch cod supports breaded and fresh-filet processing, with MSC certification increasingly required by EU and North American retail banners.
Volume sits with salmon and tuna; growth tilts toward tilapia in price-sensitive Asian and Latin American urban markets.
Distribution Channel:
Channel selection reflects buyer scale and cold-chain control requirements, with large-volume operators bypassing intermediary layers while smaller buyers depend on aggregated logistics.
- Retail:Supermarket banners and fishmonger chains dominate developed-market volume, with EU retailers enforcing EU IUU Regulation-compliant documentation and carbon footprint disclosures under the EU Green Deal.
- Wholesale:Tsukiji-style auction houses and regional distribution hubs aggregate catch from multiple vessels, though blockchain-IoT convergence is eroding their information advantage over downstream buyers.
- Online:Direct-to-consumer platforms are climbing the fastest, enabling fishery cooperatives to reach urban consumers without wholesale margin extraction, particularly in Chinese metropolitan markets.
- Direct:Contract arrangements between large farming operations and restaurant chains eliminate intermediary handling, with Mowi and Thai Union Group leveraging captive supply relationships.
Wholesale still handles the greatest tonnage; online channels are gaining share fastest among urban consumers seeking traceability transparency.
Packaging Type:
Shelf-life extension and temperature maintenance capabilities determine packaging selection, with premium formats justifying cost through reduced spoilage and insurance premiums.
- Vacuum Sealed:Modified atmosphere packaging extends retail shelf life to 7-10 days, supporting supermarket distribution in Germany, France, and Japan where consumers prioritize convenience.
- Ice Packed:Traditional flake-ice coverage maintains 0-4°C core temperatures for 48-72 hours, serving restaurant and wholesale buyers with rapid inventory turnover.
- Styrofoam:Insulated containers with gel packs enable cross-border e-commerce fulfillment, though EU single-use plastic regulations are pressuring format transition.
- Canned:Heat-sterilized preservation excludes this format from strict fresh fish definitions, limiting relevance to adjacent shelf-stable categories.
Ice packed remains the workhorse for foodservice; vacuum sealed is expanding most quickly in premium retail.
Customer Type:
Purchasing scale and quality specification intensity separate buyers, with institutional operators demanding certified supply chains while individual consumers prioritize accessibility.
- Restaurants:Sushi and fine-dining establishments specify sashimi-grade species with vessel-level traceability, with EU and Japanese buyers requiring catch documentation compliant with IUU and METI standards.
- Supermarkets:Retail banners consolidate volume through centralized procurement, with Carrefour, Tesco, and Aeon enforcing sustainability certifications and carbon accounting disclosures.
- Distributors:Regional aggregators serve smaller retail and foodservice accounts, with margin compression from direct-to-consumer platforms forcing consolidation.
- Consumers:Individual purchasers through farmers' markets and subscription services represent the smallest volume segment but the highest per-kilogram margin pool.
Restaurants and supermarkets absorb the majority of volume; consumer-direct channels show the steepest expansion trajectory among digitally enabled urban populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Tsukiji Outer Market and Osaka's central wholesale hubs anchor fresh fish import volumes, with Japanese METI cold chain standards directly shaping vessel-to-retail custody protocols across Pacific supply routes.
United States
Seattle and Boston metropolitan clusters drive procurement for sushi-grade salmon and tuna, with restaurant chains and foodservice operators expanding species-diverse menus. US FDA Hazard Analysis Critical Control Point protocols enforce seafood safety standards for processing facilities. The Pacific Northwest wild-catch fleet concentrates in Alaska-based operations supplying certified catch documentation.
China
Shanghai and Shenzhen wholesale markets absorb premium sashimi-grade species as urban consumers shift toward protein-rich diets. The country's national food safety regulator enforces cold chain standards for imported aquatic products. Yangtze River Delta distribution hubs connect Pacific catch to interior metropolitan retail channels.
Norway
Bergen and Trondheim farming operations control Atlantic salmon biomass for EU and North American buyers. EU Green Deal carbon border adjustment mechanisms favor documented low-carbon production methods. Scottish and Norwegian suppliers secure long-term retail contracts through certified renewable energy inputs.
Japan
Tokyo and Osaka metropolitan consumers rotate toward mackerel and sardine species amid sustainability concerns around bluefin tuna. METI import standards require vessel-level traceability documentation for cross-Pacific shipments. Fast-casual dining segments in Kansai and Kanto regions prioritize local sourcing credentials.
India
Mumbai, Chennai, and Bangalore metropolitan wholesale markets attract species-diverse suppliers as refrigerated logistics infrastructure expands. The Food Safety and Standards Authority of India oversees cold chain compliance for domestic distribution. Western and Eastern coastal landing sites connect to interior urban demand through emerging direct-to-consumer platforms.
Fresh Fish Market Key Industry Players
The competitive structure tilts toward vertically integrated aquaculture operations with certified sustainability protocols. Wild-catch specialists and farmed salmon producers occupy distinct margin tiers, with scale advantages concentrating among operators controlling hatchery-to-harvest custody chains. Strategic archetypes include Alaska-based integrated harvesters, Pacific-Indian Ocean supply chain controllers, and Atlantic salmon farming operations with third-party certification. Competitive moves center on M&A consolidation of processing assets and geographic expansion of direct-to-consumer platforms.
Among Alaska-based integrated harvesters, Trident Seafoods occupies a position exemplifying certified catch documentation for EU buyers. Thai Union Group represents the supply chain controller archetype across Pacific and Indian Ocean sourcing networks. Mowi anchors the Atlantic salmon farming tier with integrated hatchery-to-harvest operations meeting stringent sustainability protocols.
| Leading Market Players |
|---|
| Trident Seafoods |
| Thai Union Group |
| High Liner Foods |
| Clearwater Seafoods |
| Pacific Seafood Group |
| Red Chamber |
| Mowi |
| Lerøy |
| Sysco Corporation |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's embodied emissions tracking requirements gate both qualified supply and premium-tier pricing access, as Norwegian and Scottish suppliers with certified low-carbon production methods secure long-term retail contracts ahead of full mechanism implementation.
Pricing Analysis
Harvest-to-retail timeline anchors value-based pricing, with flesh temperature maintenance and histamine certification creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EU IUU Regulation-compliant documentation and SalmoFan color grading scores. Cost compression in foodservice segments intensifies because blast-frozen substitutes offer extended shelf life. Volume-scale buyers at restaurant chains exhibit lowest price sensitivity; individual consumers through direct-to-consumer platforms show highest.
Supply Chain Analysis
Japan's METI local-content standards for vessel-level traceability documentation are reshaping sourcing toward domestic landing verification and blockchain-tracked custody chains. Supply concentrates in Norway, Chile, and Alaska for Atlantic salmon and Pacific wild-catch species. Operations draw from diesel fuel, flake ice, and specialized refrigerated containers. Single-source vulnerability runs through Norwegian-Chilean farming duopoly control of premium salmon biomass. Distribution runs through Tsukiji-style auction houses and direct contract arrangements between farming operations and retail banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU IUU Regulation creates a formidable cost-of-compliance barrier that entrenches vertically integrated incumbents with certified catch documentation while excluding smaller vessel operators from European import channels.
For Market Incumbents: Hedge against blockchain-IoT convergence eroding information advantages by deepening backward integration into hatchery-to-harvest custody chains and acquiring regional cold-chain logistics assets in Indian metropolitan markets. Fuel cost volatility and direct-to-consumer platform proliferation threaten traditional wholesale margin extraction. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for fishery cooperatives and regional distributors to bypass Tsukiji-style auction intermediaries and reach urban consumers in Chinese and Indian metropolitan markets. Target species-diverse offerings with documented sustainability credentials to differentiate against established frozen-format competitors. For Investors and Strategic Acquirers: EU Green Deal implementation timeline acceleration is the leading indicator that carbon-accounting infrastructure will separate acquisition-ready targets from stranded asset risk over the medium-term horizon. Prioritize Atlantic salmon farming operations with certified renewable energy inputs and pole-and-line tuna harvesters with documented low-carbon methods. Watch for blockchain-IoT convergence adoption rates at Japanese METI import gateways as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Buildout | Refrigerated logistics expansion in Mumbai and Bangalore unlocks interior metropolitan market access for species-diverse suppliers. |
| Blockchain-IoT Integration | Combined distributed ledger and sensor technologies satisfy Japanese METI standards while reducing cross-Pacific shipment insurance premiums. |
| Carbon Certification Investment | Documented low-carbon harvesting methods secure preferential EU retail banner positioning under Green Deal mechanisms. |
| Direct-to-Consumer Platform Launch | Bypassing wholesale auction layers enables fishery cooperatives to capture retail margin pools in Chinese urban markets. |
| Backward Integration into Hatchery Operations | Captive supply of salmon smolts insulates farming operations from Norwegian-Chilean biomass price-setting power. |
Research Approach
Trade flow databases, EU IUU Regulation enforcement records, and Japanese METI cold chain compliance filings formed the secondary backbone, supplemented by customs data and sustainability certification registries. Primary fieldwork engaged seafood procurement directors at EU retail banners, vessel operators in Alaska and Norway, cold-chain logistics providers in India, and regulatory affairs specialists at aquaculture operations. Bottom-up and top-down triangulation validated volume estimates across product type and distribution channel segments.
Bottom-up modeling anchored the analytical framework, with top-down macroeconomic cross-checks applied across the projection horizon. Segmentation dimensions included product type, distribution channel, packaging format, and customer category, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from trend extrapolation of historical trade volumes and elasticity-adjusted demand projections. Forecast inputs incorporated fuel cost indices, EU Green Deal implementation schedules, and cold-chain infrastructure development timelines in emerging Asian markets.
Inputs from Japanese METI compliance filings and EU IUU enforcement databases were available through the study window; gaps in real-time blockchain-IoT adoption metrics at wholesale auction houses introduce uncertainty bands around traceability technology penetration forecasts. Forecasts reflect documented assumptions regarding regulatory implementation pace and infrastructure investment commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Mussel Extract Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Asian Sea Bass Market
Seafood
Food Clamshells Market
Seafood
Shellfish Extract Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Japan Frozen Seafood Market
Seafood
Sea Bream Market
Seafood
Global Smoked Fish Market
Seafood
Middle East Seafood Market
Seafood
Cod Fish Market
Seafood
Dried Scallop Market
Seafood
Global Seafood Market
Seafood
China Crustaceans Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
GCC Seafood Market