
 Natural Colostrum Supplements Market | 2026-2036
Natural Colostrum Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Colostrum Supplements Market Foresight
Asset-light contract manufacturing and white-label leasing arrangements is fragmenting competitive dynamics among smaller entrants. PanTheryx leverages captive dairy herd partnerships across the American Midwest to secure raw material consistency. Glanbia plc anchors its position through backward integration into grass-fed bovine sourcing. NOW Foods competes on pharmacy shelf presence and third-party certification density.
Natural colostrum supplements are concentrated bioactive preparations derived from the pre-milk secretions of mammals, typically standardized for immunoglobulin G content exceeding 20% by dry weight and processed via low-temperature spray drying to preserve antibody activity. These formulations serve primarily as immune-modulatory and gut-barrier-support inputs for human consumption. Powder formats dominate volume throughput due to bulk manufacturing economies and blending flexibility in sports nutrition applications. Capsule segments sustain premium positioning through dose precision and portability. The immune support application category leads value generation as post-acute health awareness drives physician-adjacent recommendation patterns.
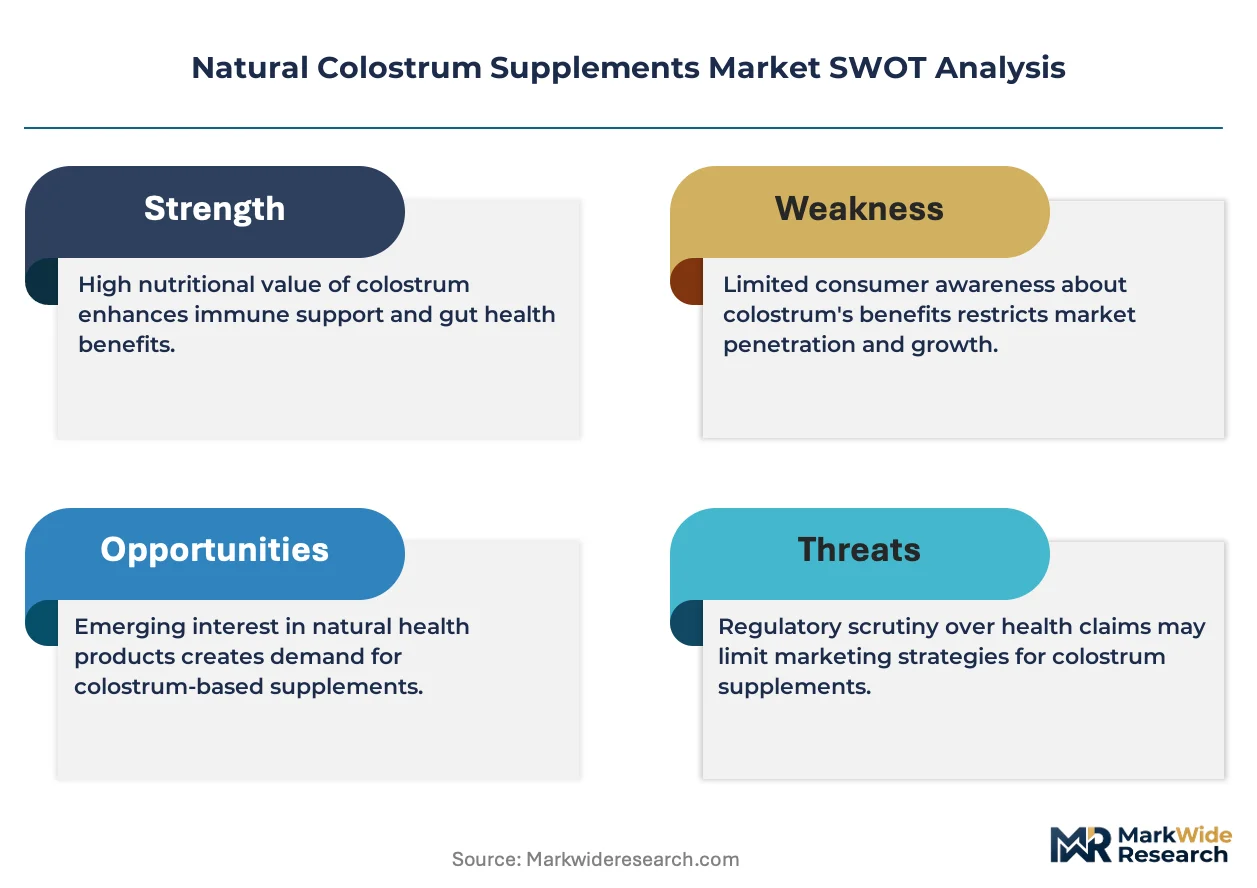
The FDA exercises oversight through New Dietary Ingredient notifications and Current Good Manufacturing Practice enforcement, while the EMA and EFSA coordinate novel food assessments for colostrum-derived ingredients entering European commerce. These frameworks elevate compliance costs but simultaneously filter substandard suppliers and reinforce quality-based purchasing criteria among institutional buyers. Stakeholders must monitor evolving substantiation requirements for structure-function claims as regulatory scrutiny intensifies across major demand centers.
Market Dynamics
Captive dairy herd partnerships are consolidating upstream control over immunoglobulin-rich raw material streams, forcing mid-scale processors toward contract manufacturing or white-label leasing to remain viable.
Growth Catalysts
- Post-acute immune awareness:Physician-adjacent recommendation patterns in sports medicine and functional medicine clinics are pulling colostrum into recovery protocols for elite athletes.
- FDA NDI pathway maturation:The notification framework is filtering substandard entrants and reinforcing quality-based purchasing criteria among institutional supplement buyers.
- Low-temperature spray drying:This processing technology preserves antibody bioactivity above 20% IgG by dry weight, unlocking premium positioning in gut-barrier and immune-modulatory applications.
Market Restraints
- Seasonal colostrum availability:Bovine calving cycles concentrate raw material harvests into narrow windows, creating inventory financing pressures and price volatility.
- German-Swiss supply concentration:Colostrum BioTec GmbH and SwissBioColostrum AG anchor European supply chains, creating geographic single-point-of-failure exposure.
- Plant-based protein substitution:Pea and rice protein isolates with added prebiotic fibers are capturing gut-health positioning at lower price points in mass-market channels.
Strategic Opportunities
- Pediatric and geriatric underpenetration:Immune support applications for children and aging populations remain clinically validated but commercially undeveloped in North American pharmacy channels.
- Capsule format portability:Precision-dosed unit packaging addresses travel and workplace consumption occasions that bulk powders cannot serve.
- EFSA novel food assessments:The harmonized European framework creates a regulatory tailwind for standardized colostrum ingredients seeking cross-border commerce.
Industry Challenges
- Immunoglobulin assay standardization:Inconsistent IgG measurement methodologies across laboratories create quality disputes between suppliers and contract manufacturers.
- CGMP compliance timeline:FDA enforcement of Current Good Manufacturing Practice requirements demands 18-24 month facility qualification periods that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Colostrum Supplements Market |
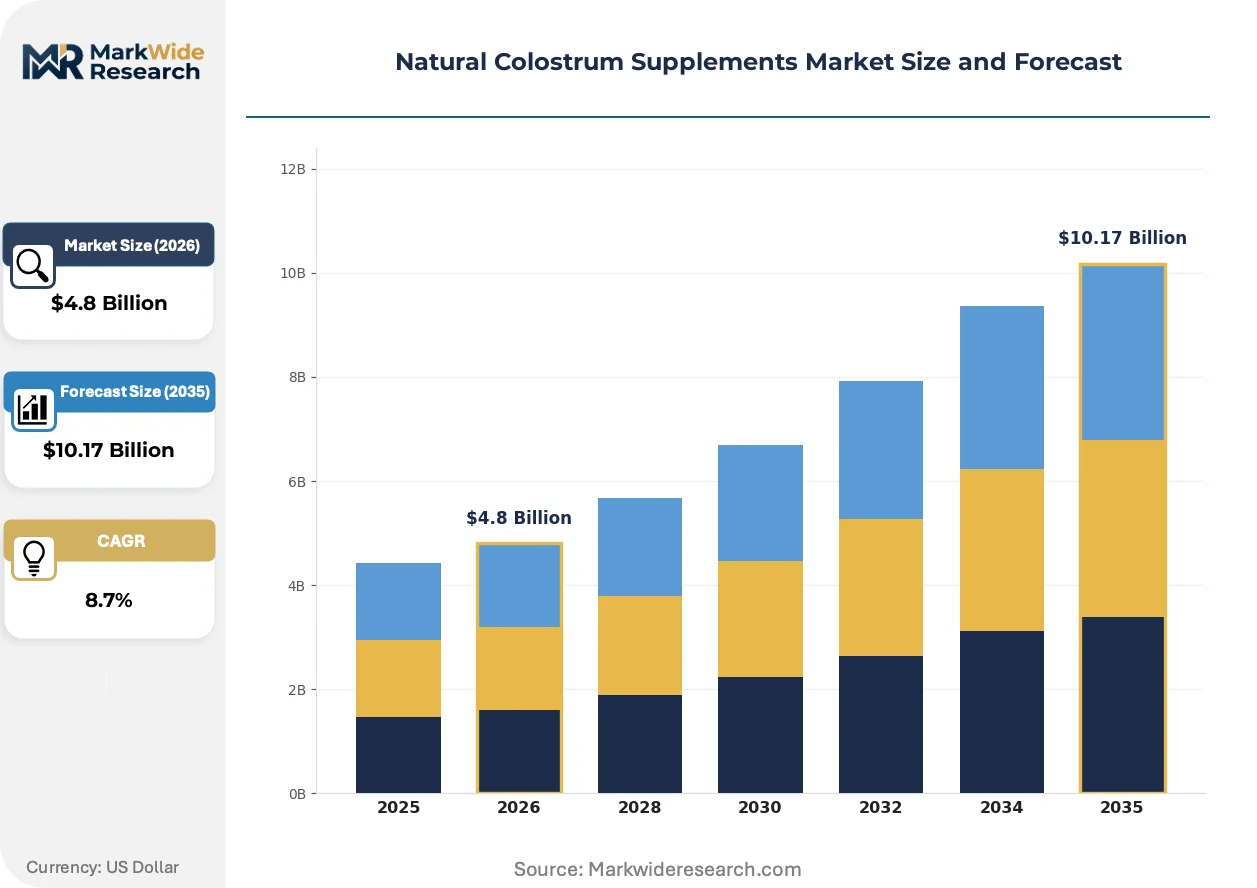
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid, Softgels Source: Cow, Goat, Sheep, Buffalo Application: Health, Sports Nutrition, Immune Support, Digestive Health Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | PanTheryx, Vital Proteins, Glanbia plc, Biostrum Nutritech Pvt Ltd, Colostrum BioTec GmbH, APS BioGroup, NOW Foods, Fonterra Co-operative Group, SwissBioColostrum AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Colostrum Supplements Market Shifts & Advancements
Near-infrared spectroscopy and blockchain traceability are digitizing quality assurance workflows, compressing batch release timelines while elevating transparency expectations among institutional buyers.
Blockchain-enabled supply chain verification is digitizing the documentation of herd health, calving dates, and cold-chain integrity from farm to finished product. Sports nutrition procurement teams at professional athletic organizations are mandating this data layer in supplier qualification. The technology is digitizing what was previously paper-based audit trails, collapsing due diligence cycles from weeks to hours.
The FDA's intensified scrutiny of structure-function claim substantiation is elevating clinical trial investment thresholds for immune support positioning. Firms must now generate peer-reviewed efficacy data to defend label language against warning letter risk. Powder formats targeting institutional buyers face the highest compliance burden, as bulk purchasers demand indemnification against regulatory action.
Direct-to-practitioner distribution is displacing traditional wholesale channels for premium colostrum formulations. Functional medicine clinicians and sports dietitians are consolidating purchase authority previously fragmented across retail consumers. Germany exhibits the most pronounced channel shift, where practitioner-exclusive brands command 40% price premiums over mass-market equivalents through consultation-based recommendation.
Natural Colostrum Supplements Market Segmentation
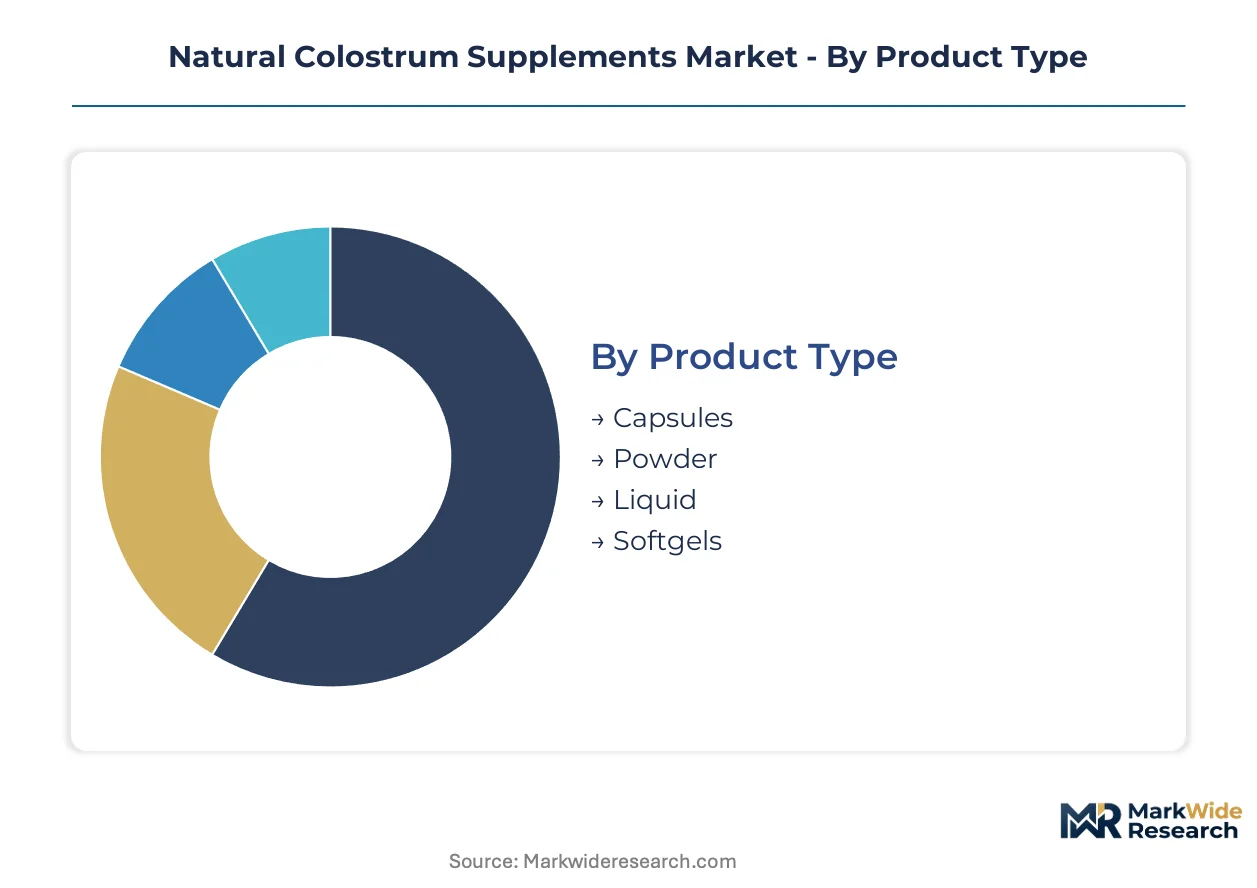
Format selection dictates manufacturing investment and margin structure in colostrum supplements. Powder formats exploit bulk economies while capsules capture precision-dosed premiums. Each segment carries distinct regulatory burdens and shelf-life constraints that shape competitive positioning.
Product Type:
Cost tier stratification separates bulk institutional buyers from premium retail consumers across delivery formats.
- Powder:Bulk dry formulations standardized above 20% immunoglobulin G content serve sports nutrition blending operations and functional food manufacturers. Demand concentrates in American Midwest dairy belt processing facilities where captive herd partnerships secure raw material consistency. Low-temperature spray drying preserves antibody bioactivity but requires substantial capital equipment.
- Capsules:Precision-dosed unit packaging addresses travel and workplace consumption occasions with measured immunoglobulin delivery. German pharmacy channels and US practitioner-exclusive distribution models sustain 40% price premiums over mass-market equivalents through consultation-based recommendation authority.
- Liquid:Ready-to-dose formulations target pediatric and geriatric populations with swallowing difficulties, though cold-chain requirements limit distribution reach.
- Softgels:Lipid-suspended colostrum extracts offer taste masking and extended shelf stability for mass-market retail placement.
Powder commands the established base. The steepest expansion runs through Capsule precision-dosing formats.
Source:
Supply geography and immunoglobulin concentration profiles differentiate mammalian-derived raw material streams.
- Cow:Bovine colostrum dominates commercial throughput with immunoglobulin G concentrations exceeding 100 mg/mL in first-milking harvests. PanTheryx and Glanbia plc anchor procurement through Midwest US grass-fed herd partnerships and backward integration into captive dairy operations.
- Goat:Smaller fat globule size and reduced allergenic protein profiles position caprine sources for pediatric formulations and sensitive digestive applications in European specialist channels.
- Sheep:Ovine-derived preparations concentrate in Mediterranean traditional medicine markets with localized processing infrastructure in Greece and Italy.
- Buffalo:Water buffalo colostrum supplies South Asian regional markets where indigenous dairy systems support small-batch artisanal production.
Cow-derived material commands the established base. The steepest expansion runs through Goat pediatric-targeted positioning.
Application:
End-use specification determines clinical substantiation requirements and channel access permissions.
- Immune Support:Immunoglobulin-rich formulations targeting post-acute recovery protocols drive physician-adjacent recommendation patterns in sports medicine clinics. FDA structure-function claim scrutiny demands peer-reviewed efficacy data for label language defense.
- Sports Nutrition:Elite athletic recovery programs now mandate bovine-derived colostrum for gut-barrier integrity during high-training-load periods. Professional procurement teams require blockchain-enabled supply chain verification.
- Digestive Health:Gut-barrier support applications compete with plant-based protein isolates and prebiotic fibers at lower price points in mass-market channels.
- Health:General wellness positioning faces the highest substitution pressure from commoditized immune ingredients.
Immune Support commands the established base. The steepest expansion runs through Sports Nutrition institutional procurement.
Distribution Channel:
Customer type and purchase authority fragmentation shape margin capture and brand positioning.
- Online Retail:Direct-to-consumer platforms enable subscription models and practitioner-branded exclusives with compressed intermediation costs.
- Health Stores:NOW Foods competes through third-party certification density and shelf presence in US natural products retail.
- Pharmacies:German pharmacy channels exhibit the most pronounced practitioner-exclusive brand concentration with consultation-based authority sustaining premium positioning.
- Supermarkets:Mass-market placement demands price competitiveness against plant-based alternatives with limited margin for quality differentiation.
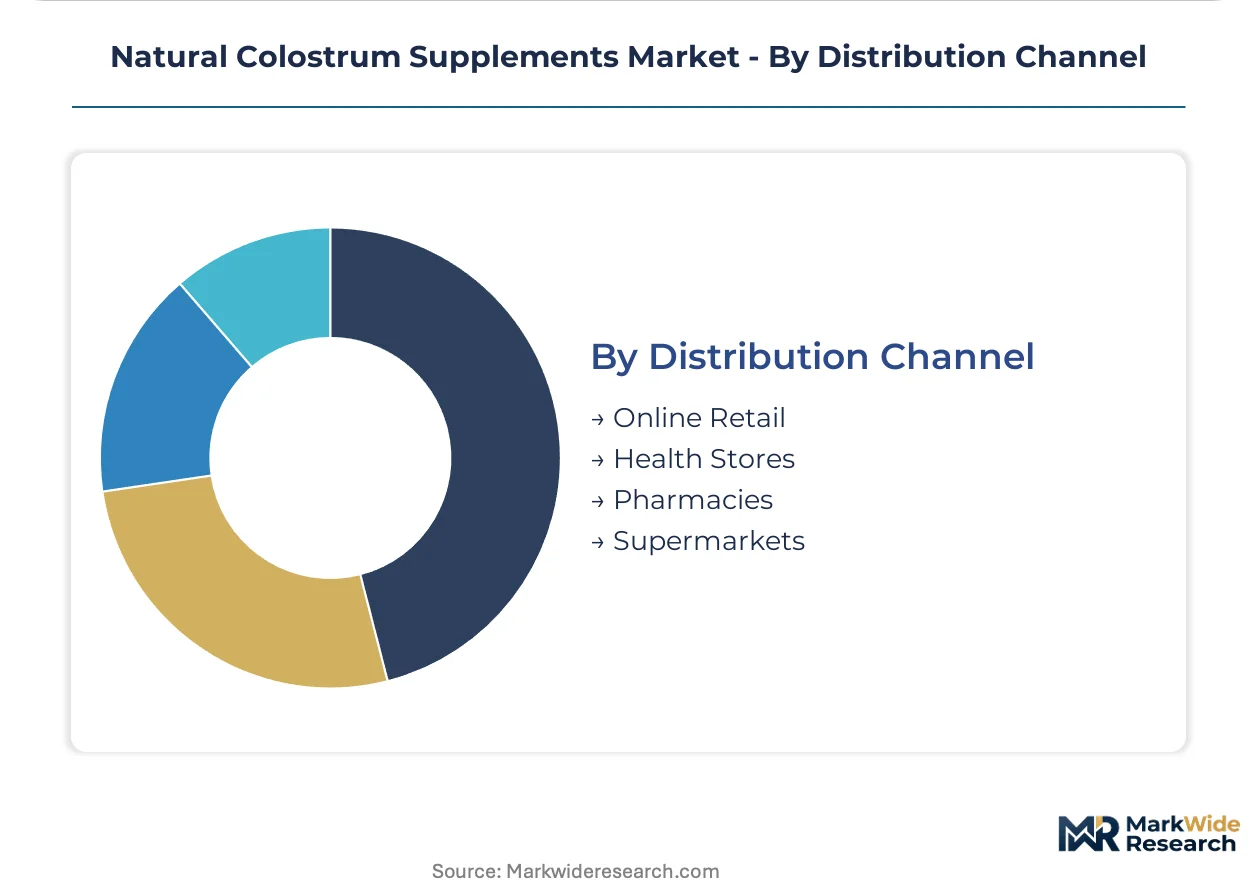
Health Stores command the established base. The steepest expansion runs through Online Retail direct-to-practitioner models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA structure-function claim enforcement and EFSA novel food assessments are redirecting capital toward compliant manufacturing jurisdictions. The analysis tracks five national markets where regulatory clarity and dairy infrastructure concentrate competitive positioning.
United States
Elite athletic procurement teams mandate bovine-derived colostrum for recovery protocols across professional sports franchises. FDA Current Good Manufacturing Practice enforcement demands 18-24 month facility qualification timelines that strain working capital for mid-scale entrants. PanTheryx leverages captive dairy herd partnerships across the American Midwest to secure raw material consistency.
Germany
Practitioner-exclusive brands command 40% price premiums over mass-market equivalents through consultation-based recommendation authority. EFSA novel food assessments create regulatory tailwinds for standardized ingredients seeking cross-border commerce within the European Union. Colostrum BioTec GmbH anchors European supply chains from processing facilities in the southern dairy belt.
Switzerland
Swissmedic oversight elevates quality-based purchasing criteria among institutional supplement buyers filtering substandard entrants. SwissBioColostrum AG maintains specialized processing infrastructure for immunoglobulin-rich formulations targeting pharmacy channels. The Basel-Zurich corridor concentrates colostrum R&D alongside precision nutrition manufacturing clusters.
India
FSSAI dietary supplement regulations are maturing to align with Codex Alimentarius standards for immunoglobulin assay methodologies. Biostrum Nutritech Pvt Ltd operates from dairy-intensive states where indigenous water buffalo systems support small-batch artisanal production. Maharashtra and Gujarat host emerging contract manufacturing capacity for export-oriented formulations.
Australia
TGA therapeutic goods oversight shapes substantiation requirements for immune-modulatory positioning in pharmacy-adjacent channels. Sports medicine clinics in Sydney and Melbourne are adopting post-acute recovery protocols previously established in North American athletic programs. Queensland dairy regions supply grass-fed bovine raw materials to domestic processors.
Natural Colostrum Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into three strategic archetypes: dairy-integrated multinationals with backward integration into captive herd operations, pure-play colostrum specialists with regional pharmacy dominance, and contract manufacturers serving white-label demand. Competitive moves concentrate on M&A for dairy supply access and blockchain-enabled traceability partnerships that satisfy institutional procurement mandates.
Among dairy-integrated multinationals, Glanbia plc and Fonterra Co-operative Group exemplify the scale-driven archetype through grass-fed sourcing control. PanTheryx occupies a specialist position within the North American market, while Colostrum BioTec GmbH anchors European supply infrastructure. NOW Foods represents the pharmacy shelf-presence vector competing through third-party certification density.
| Leading Market Players |
|---|
| PanTheryx |
| Vital Proteins |
| Glanbia plc |
| Biostrum Nutritech Pvt Ltd |
| Colostrum BioTec GmbH |
| APS BioGroup |
| NOW Foods |
| Fonterra Co-operative Group |
| SwissBioColostrum AG |
| Others |
Supply & Pricing Matrix
Bavaria's dairy processing corridor concentrates immunoglobulin-standardized colostrum capacity, translating raw material scarcity into sustained premium capture for pharmacy-grade formulations. Midwest American captive herd partnerships anchor institutional powder supply, while seasonal calving compression creates inventory financing leverage that favors backward-integrated processors with working capital depth.
Pricing Analysis
Certification level creates the primary spread between mass-market and practitioner-exclusive tiers. Three-tier pricing structure across premium, standard, and economy levels segments by IgG assay standardization and blockchain traceability documentation. Cost compression in bulk powder channels is intensifying because plant-based protein isolates capture gut-health positioning at lower price points. Mass-market retail buyers exhibit highest price sensitivity, while sports medicine procurement teams prioritize indemnification against regulatory action over unit cost.
Supply Chain Analysis
PanTheryx and Glanbia plc hold captive dairy herd capacity across the American Midwest and Irish grass-fed corridors. Raw material streams draw from first-milking bovine harvests concentrated in Germany, Switzerland, and the United States. Single-source vulnerability runs through German-Swiss processing infrastructure where Colostrum BioTec GmbH and SwissBioColostrum AG anchor European immunoglobulin supply. Distribution runs through direct-to-practitioner channels displacing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural colostrum supplements sit in early-cycle expansion as post-acute immune awareness pulls physician-adjacent recommendation patterns into sports medicine and functional medicine clinics.
For Market Incumbents: Pre-empt plant-based protein substitution by deepening IgG assay standardization investments and blockchain-enabled traceability partnerships that satisfy institutional procurement mandates. Lock in captive dairy herd expansion across American Midwest corridors before mid-scale processors recover contract manufacturing viability. Certification density in German pharmacy channels represents the priority defensive perimeter. For New Entrants and Emerging Players: Build out pediatric and geriatric formulation white space in North American pharmacy channels where immune support applications remain clinically validated but commercially undeveloped. Capsule precision-dosing formats for travel and workplace consumption occasions offer the most penetrable entry vector. Pursue EFSA novel food assessment alignment to unlock cross-border European commerce. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA NDI pathway maturation and EFSA novel food assessments filter substandard entrants while elevating quality-based purchasing criteria. Acquisition targets should concentrate on dairy-integrated specialists with backward integration into grass-fed sourcing and existing practitioner channel relationships. Monitor blockchain traceability mandate adoption rates among professional athletic procurement teams as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Dairy Herd Expansion | PanTheryx-style Midwest partnerships secure raw material consistency against seasonal availability compression. |
| Blockchain Traceability Implementation | Sports nutrition procurement teams mandate this data layer for supplier qualification cycles. |
| EFSA Novel Food Assessment Alignment | Harmonized European framework creates regulatory tailwind for standardized cross-border ingredients. |
| Direct-to-Practitioner Channel Development | German pharmacy models demonstrate 40% price premium capture through consultation-based authority. |
| Low-Temperature Spray Drying Capacity Addition | Preserves antibody bioactivity above 20% IgG for premium gut-barrier positioning. |
Research Methodology
Cross-validation between primary interviews with sports dietitians, functional medicine clinicians, supplement procurement managers, and dairy processing executives anchors the qualitative findings. Secondary validation draws from FDA New Dietary Ingredient notifications, EFSA novel food assessment databases, SEC 10-K filings of publicly traded nutrition companies, and customs records of colostrum powder trade flows. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Calibration against historical IgG standardization adoption curves and sports nutrition procurement pattern shifts shapes the analytical framework. Segmentation dimensions span product format, mammalian source, application category, and distribution channel archetype. CAGRs derive from regression against immunoglobulin assay methodology maturation and practitioner recommendation velocity indices.
Practitioners should monitor EFSA assessment timeline acceleration and FDA structure-function claim enforcement intensity for early signals of regulatory revision. Quarterly review of blockchain traceability mandate penetration among professional athletic organizations and seasonal colostrum spot price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Meal Replacement Products OEM Market