
 Fish Nutrition Market | 2026-2036
Fish Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Nutrition Market Foresight
The divergence between premium and commodity tiers is hardening around protein source traceability and omega-3 density specifications. Cargill leverages its integrated supply chain to dominate North American soy-based feed formulations. BioMar Group anchors its position through specialized marine protein R&D in Northern Europe. Nutreco N.V. differentiates via precision nutrition platforms serving Atlantic salmon producers.
Fish nutrition encompasses formulated feeds, supplements, and functional additives engineered to meet species-specific protein, lipid, vitamin, and mineral requirements across aquatic life stages. Extruded feeds achieve gelatinization rates exceeding 85 percent, enabling controlled nutrient release and improved digestibility for carnivorous and omnivorous species. Pellets command the largest volume share across commercial aquaculture, while microencapsulation technology captures expanding margin pools in larval and ornamental applications. Aquaculture farms represent the dominant application channel, though hatcheries are gaining structural importance as broodstock nutrition protocols tighten.
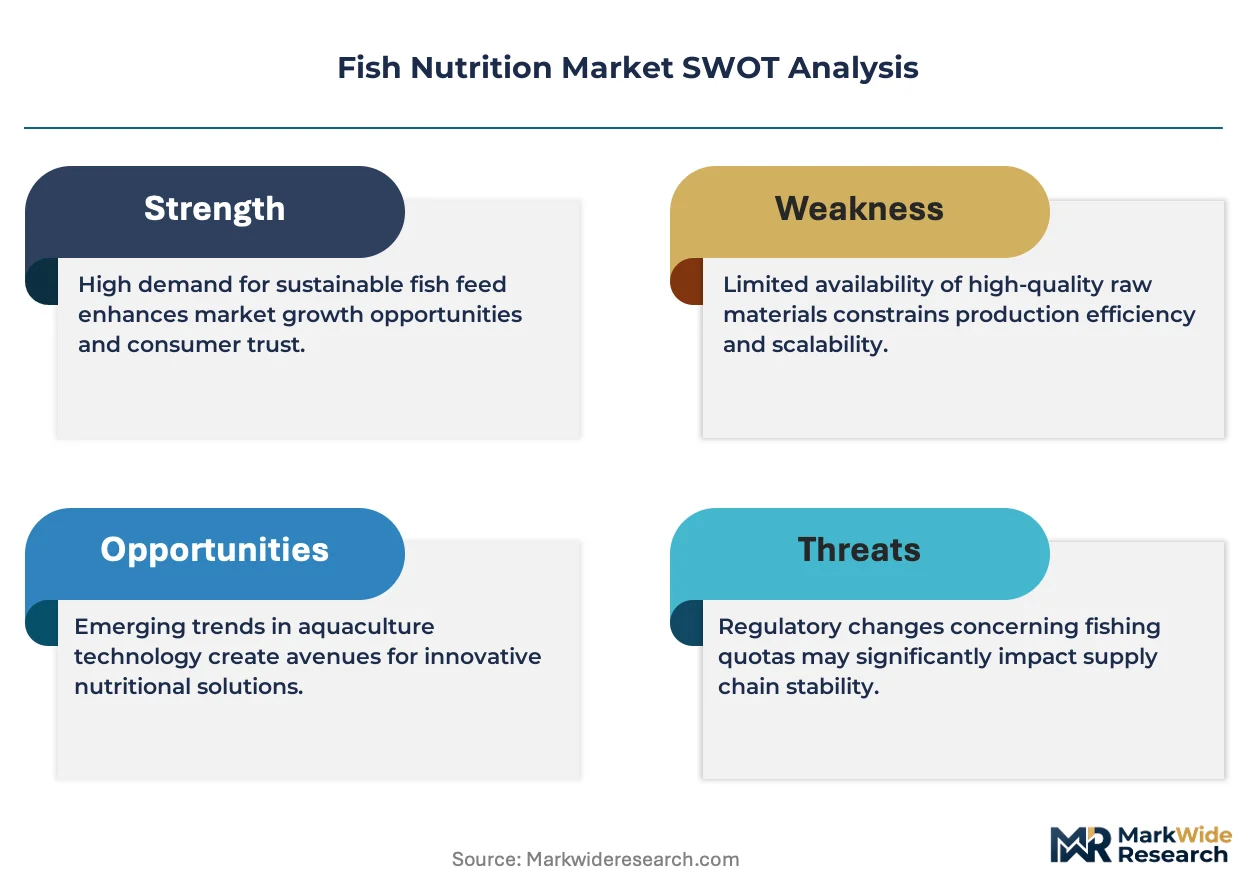
The EU Green Deal and REACH frameworks restrict marine ingredient sourcing, pushing reformulation toward alternative proteins and microbial biomass. FDA and EFSA standards on feed contaminants and additive approvals shape product registration timelines and market access conditions. Stakeholders must monitor regulatory divergence between jurisdictions as ingredient innovation outpaces harmonized approval pathways.
Market Dynamics
The EU Green Deal's sustainable aquaculture provisions are forcing wholesale reformulation of marine ingredient sourcing, compressing traditional supply chains while accelerating microbial protein and single-cell oil adoption across Atlantic salmon and shrimp operations.
Growth Catalysts
- Precision-formulated feeds:Norwegian aquaculture farms deploy species-specific nutrient protocols that optimize feed conversion ratios and reduce environmental discharge.
- REACH framework restrictions:The EU's tightening contaminant thresholds for marine ingredients push manufacturers toward certified alternative protein streams and traceable supply chains.
- Mekong Delta farming clusters:Vietnam's concentrated shrimp and pangasius production generates concentrated demand for extruded feeds and functional additives.
Market Restraints
- Marine ingredient volatility:Wild-caught fishmeal and fish oil face quota constraints from North Atlantic and Southeast Pacific fisheries, compressing margin predictability.
- Microbial biomass scale-up:Industrial fermentation capacity for single-cell proteins remains concentrated in Northern Europe, creating supply bottlenecks for global reformulation.
- EFSA additive timelines:Novel ingredient approvals stretch 18-36 months, freezing commercialization of insect meal and algal oil innovations.
Strategic Opportunities
- Ornamental and larval microencapsulation:Hatchery demand for precision-dosed live feed replacements opens premium pricing tiers in specialized marine protein R&D.
- India's aquaculture expansion:FSSAI feed safety standards and PLI scheme incentives for cold-chain infrastructure unlock shrimp and carp nutrition penetration.
- Biofloc and recirculating aquaculture systems:Closed-loop production in urban and peri-urban zones creates demand for water-quality-optimized formulations with reduced nitrogen load.
Industry Challenges
- Broodstock nutrition expertise:Qualified formulators capable of optimizing larval survival rates through micronutrient timing remain scarce across Southeast Asian hatcheries.
- Multi-jurisdiction registration:Divergent FDA, EFSA, and NMPA contaminant standards force parallel testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Nutrition Market |
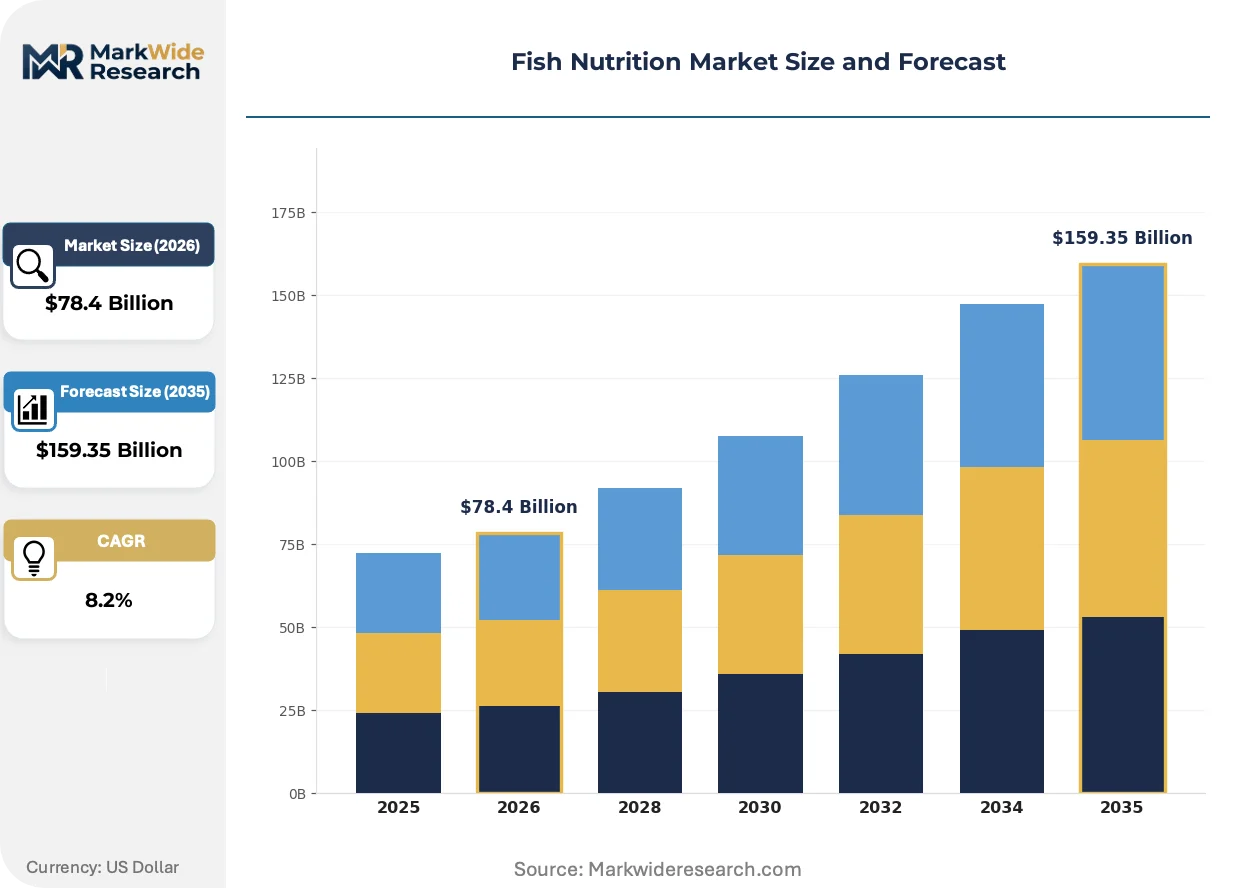
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $159.35 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Extruded Feeds, Crumbles, Flakes, Powdered Supplements Application: Aquaculture Farms, Hatcheries, Ornamental Fish Breeding, Research Institutions, Fish Processing Units End User: Commercial Feed Manufacturers, Aquafeed Traders, Fish Farmers, Specialty Feed Providers Formulation Technology: Encapsulation, Microencapsulation, Coating, Pelletizing, Extrusion Technology |
| Companies Covered | Cargill, Nutreco N.V., BioMar Group, Charoen Pokphand Foods, Alltech, ADM, Evonik, Omega Protein Corporation, Austevoll Seafood ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Nutrition Market Shifts & Advancements
Formulation science is pivoting from commodity bulk feeds toward functional nutrition platforms that modulate immune response, gut microbiome, and fillet quality through precise molecular interventions.
Single-cell protein fermentation derived from methanotrophic bacteria is electrifying alternative ingredient supply, enabling Atlantic salmon producers to sever dependence on marine protein without compromising omega-3 density. Norwegian and Chilean farms are scaling adoption from pilot to commercial volumes within 24-month windows. This technology is compressing the premium-commodity price spread for certified sustainable feeds.
REACH authorization requirements for ethoxyquin and other synthetic antioxidants are forcing antioxidant reformulation toward natural tocopherol and rosemary extract blends. Manufacturers serving EU-bound salmon and trout operations face 12-18 month reformulation cycles to maintain market access. Northern European compounders are responding by backward integrating into botanical extraction partnerships.
Integrated multi-trophic aquaculture procurement is displacing standalone feed purchasing across Vietnamese and Indonesian shrimp cooperatives. Buyers now contract for nutrition-plus-extension-service bundles that bundle feed supply with water quality monitoring and disease diagnostics. This bundling concentrates purchasing power among vertically integrated cooperatives in the Mekong Delta and Java Sea production zones.
Fish Nutrition Market Segmentation
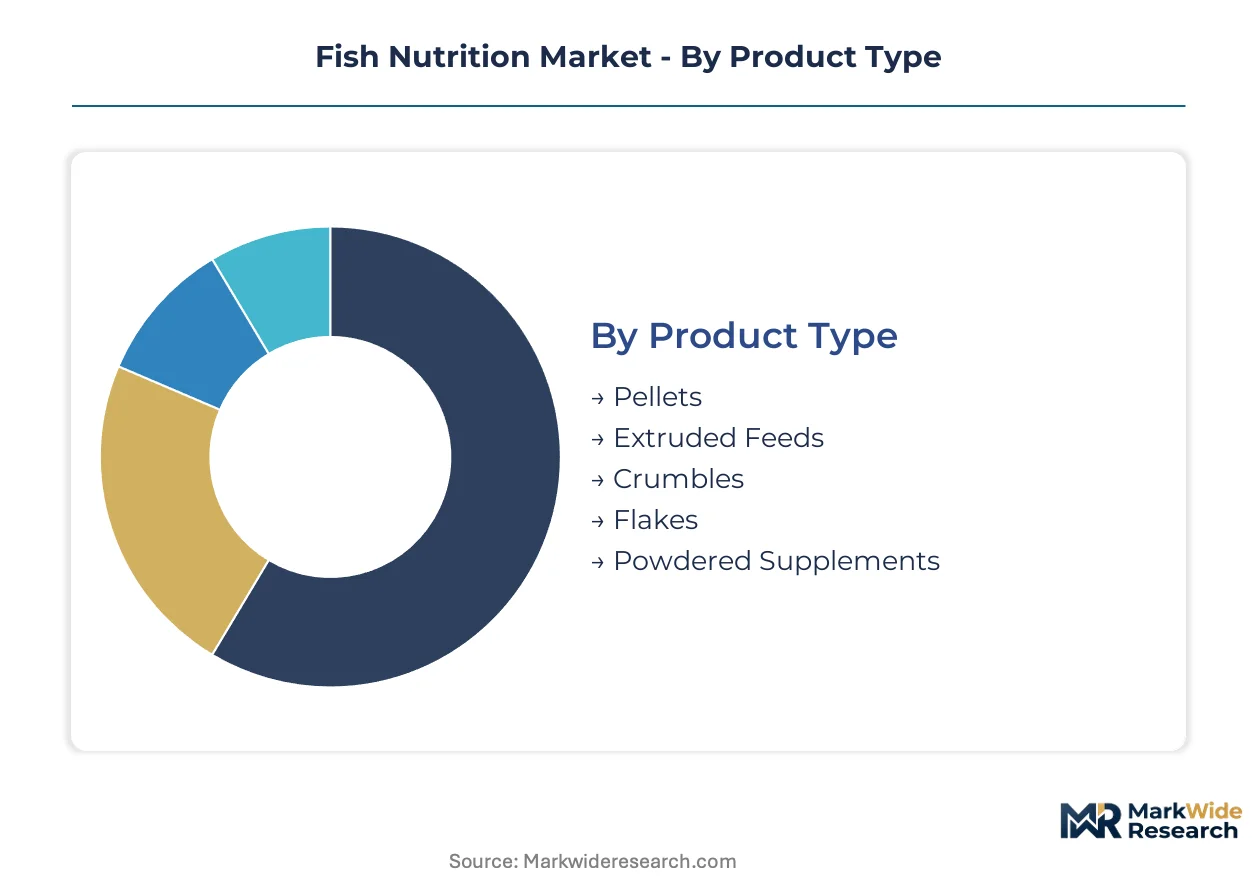
Species-specific nutritional requirements and production system constraints drive distinct formulation choices across the fish nutrition landscape. Understanding how product formats, application contexts, and delivery technologies align with operational needs enables targeted positioning for compounders and additive suppliers.
Product Type:
Aquaculture operators upgrade feed formats based on species feeding behavior, water stability requirements, and mechanized distribution infrastructure.
- Pellets:Compressed cylindrical feeds with adjustable sinking rates serve seabass, seabream, and carp operations across Mediterranean and Asian pond systems. Mekong Delta farming clusters deploy high-density sinking pellets for pangasius cage culture, where mechanical feeders demand uniform particle durability.
- Extruded Feeds:Thermomechanical processing achieves starch gelatinization above 85 percent, creating buoyant or slow-sinking matrices for salmonids and shrimp. Norwegian farms leverage precision-extruded diets to optimize feed conversion ratios while minimizing nutrient discharge under strict fjord environmental permits.
- Crumbles:Fragmented extrudate sized for juvenile fish transition from starter microdiets to grower feeds.
- Flakes:Thin compressed layers serve ornamental species and small-scale hatchery operations requiring visual feeding monitoring.
- Powdered Supplements:Fine-ground mineral and vitamin premixes integrate into on-farm feed milling or top-dressing protocols.
Pellets sit at the top of the volume ranking, with extruded feeds climbing the fastest as precision aquaculture expands.
Application:
Production stage determines nutritional specification intensity, with early life phases commanding premium formulation complexity.
- Aquaculture Farms:Grow-out operations across Chilean salmon concessions and Vietnamese shrimp ponds consume bulk compound feeds where cost-per-kilogram and feed conversion efficiency dominate procurement criteria. Integrated multi-trophic systems in Indonesia increasingly specify nitrogen-optimized formulations to maintain water quality in intensive ponds.
- Hatcheries:Broodstock conditioning and larval rearing demand micronutrient precision for egg quality and survival rates. Northern European salmon hatcheries invest in live feed replacement diets using microencapsulated marine proteins to reduce dependency on rotifer and Artemia cultures.
- Ornamental Fish Breeding:Discus, koi, and marine aquarium species require color-enhancing carotenoid formulations and specialized particle sizes.
- Research Institutions:Experimental diets with defined nutrient matrices support nutritional physiology studies and new ingredient validation.
- Fish Processing Units:Byproduct streams from filleting operations enter rendering chains for fishmeal and oil recovery, closing nutrient loops.
Aquaculture Farms anchor absolute tonnage demand, though Hatcheries generate the steepest margin expansion trajectory.
End User:
Channel structure concentrates purchasing power among vertically integrated operators while fragmenting across smallholder cooperatives.
- Commercial Feed Manufacturers:Industrial compounders in Norway, Chile, and Thailand operate continuous extrusion lines supplying branded grower diets to contracted farming operations. Scale economies and backward integration into marine protein refining define competitive position.
- Aquafeed Traders:Distributors across India's Andhra Pradesh and Vietnam's Mekong Delta aggregate demand from dispersed shrimp farmers, bundling credit, extension services, and logistics.
- Fish Farmers:Direct procurement of bulk feeds or on-farm mixing using commercial premixes characterizes small-to-medium carp and tilapia operations.
- Specialty Feed Providers:Niche suppliers serve ornamental breeders and high-value marine finfish hatcheries with customized micronutrient protocols.
Commercial Feed Manufacturers command the largest volume share, with Aquafeed Traders gaining structural importance in fragmented Asian production zones.
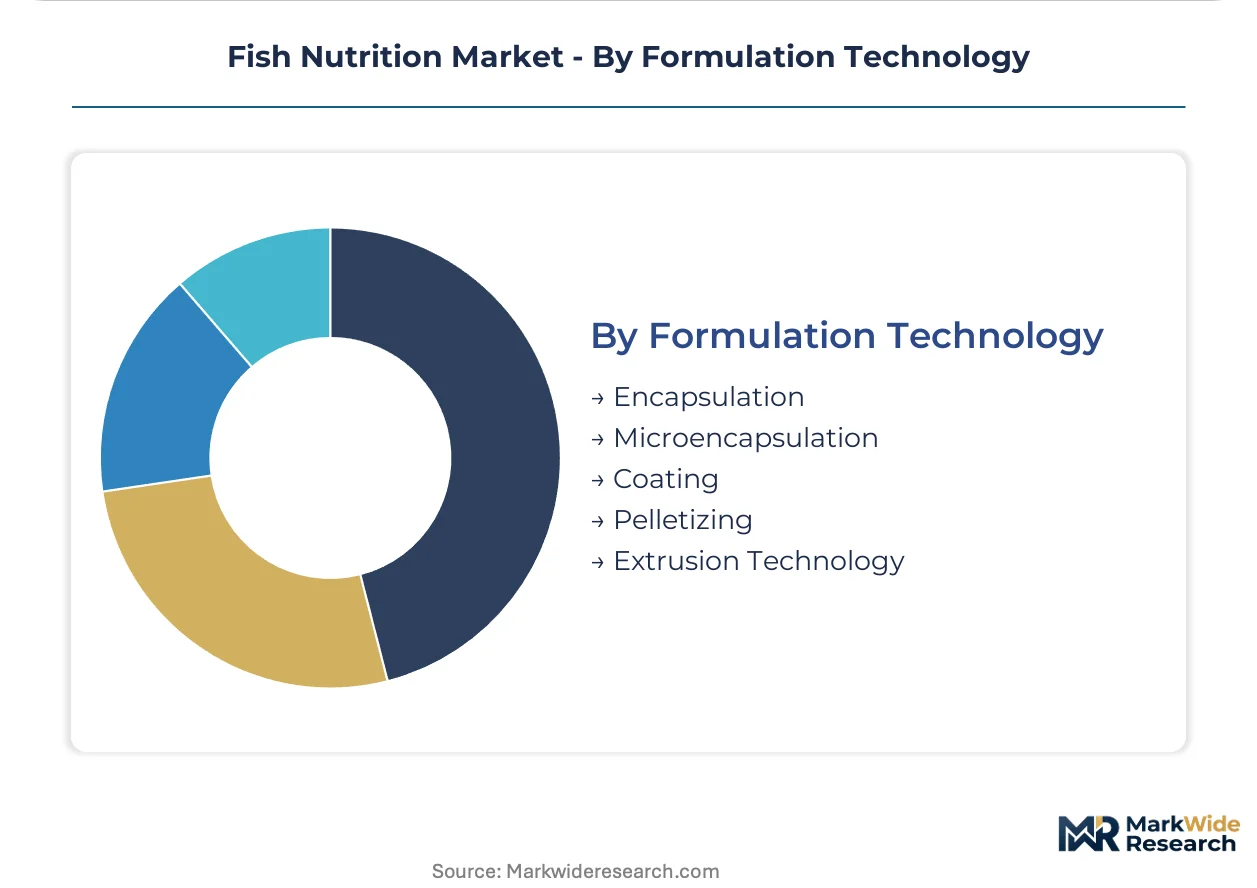
Formulation Technology:
Processing innovation unlocks ingredient functionality while meeting regulatory constraints on additive stability and release kinetics.
- Encapsulation:Lipid or polymer matrices protect heat-sensitive vitamins and probiotics during extrusion, enabling post-pelleting application. EFSA authorization timelines for novel encapsulants stretch commercialization cycles.
- Microencapsulation:Sub-millimeter particle engineering delivers precise nutrient dosing for larval fish with underdeveloped digestive systems. Marine hatcheries in Spain and Japan adopt spray-dried microcapsules as Artemia replacements.
- Coating:Post-extrusion lipid and attractant application enhances palatability and reduces feed waste in high-density shrimp ponds.
- Pelletizing:Cold compression of mash feeds serves species with lower digestibility requirements and on-farm mixing operations.
- Extrusion Technology:High-shear thermomechanical processing remains the dominant platform for commercial aquaculture, with twin-screw systems enabling flexible inclusion of alternative proteins and microbial biomass.
Extrusion Technology dominates installed capacity, with Microencapsulation expanding most quickly in premium hatchery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine protein formulators and aquaculture nutrition scientists concentrate in Norway's fjord regions, Chile's salmon concessions, and Vietnam's Mekong Delta farming clusters, anchoring global feed innovation capacity.
Norway
Atlantic salmon producers in Bergen and Trondheim deploy precision-formulated extruded feeds to optimize feed conversion ratios under strict fjord environmental permits. The EU Green Deal's REACH framework restrictions on marine ingredient sourcing force Norwegian compounders toward certified alternative protein streams and microbial biomass adoption. Tromsø-based research clusters pioneer single-cell protein fermentation from methanotrophic bacteria for commercial salmon operations.
Chile
Salmon farming concessions in the Los Lagos and Aysén regions generate concentrated demand for species-specific grower diets with controlled nutrient release profiles. Chile's national fisheries service enforces residue monitoring programs that align with FDA import requirements for fillet contaminants. Puerto Montt anchors the southern production zone where integrated multi-trophic aquaculture procurement is displacing standalone feed purchasing across cooperative operations.
Vietnam
Shrimp and pangasius producers in the Mekong Delta's Cần Thơ and An Giang provinces consume high-density sinking pellets for cage culture systems with mechanical feeding infrastructure. Vietnam's Ministry of Agriculture and Rural Development implements feed safety standards through the National Agro-Forestry-Fisheries Quality Assurance Department. Bạc Liêu farming clusters are scaling adoption of nutrition-plus-extension-service bundles that combine feed supply with water quality monitoring.
United States
Catfish operations in Mississippi's Delta region and hybrid striped bass farms in the Mid-Atlantic source soy-based formulations from domestic compounders with integrated supply chains. FDA feed contaminant standards and additive approval timelines shape product registration requirements for manufacturers serving US aquaculture. Thad Cochran National Warmwater Aquaculture Center in Stoneville anchors federal research into alternative protein validation for pond-raised species.
India
Shrimp hatcheries in Andhra Pradesh's Nellore and Krishna districts and carp producers in West Bengal's Nadia region drive demand for extruded grower feeds and larval microdiets. FSSAI feed safety standards and PLI scheme incentives for cold-chain infrastructure unlock nutrition penetration across fragmented farming operations. Kochi's Marine Products Export Development Authority coordinates quality certification for export-oriented aquafeed procurement in the southwestern coastal belt.
Fish Nutrition Market Competitive Landscape
Top-tier vendors anchor integrated supply chains spanning marine protein refining to precision extrusion, while mid-tier specialists occupy niche formulation segments. The vendor base stratifies across three functional tiers: diversified agribusiness conglomerates with captive ingredient sourcing, marine-focused compounders with hatchery specialization, and regional distributors bundling credit with extension services. Dominant competitive moves include backward integration into alternative protein fermentation capacity and geographic expansion through aquafeed trading partnerships in fragmented Asian production zones.
Within the diversified agribusiness tier, Cargill and ADM represent supply-chain-integrated compounders with North American soy-based formulation dominance. Marine-specialist compounders exemplified by BioMar Group and Nutreco N.V. occupy positions emphasizing precision nutrition platforms and Northern European marine protein R&D. Among Asian integrated food conglomerates, Charoen Pokphand Foods anchors a position spanning feed manufacturing through downstream aquaculture operations.
| Leading Market Players |
|---|
| Cargill |
| Nutreco N.V. |
| BioMar Group |
| Charoen Pokphand Foods |
| Alltech |
| ADM |
| Evonik |
| Omega Protein Corporation |
| Austevoll Seafood ASA |
| Others |
Supply & Pricing Matrix
Family-owned Norwegian compounders and Chilean cooperatives anchor feed pricing discipline through captive marine protein refining and long-term offtake contracts with salmon farming concessions. Their concentrated ownership structures enable coordinated margin defense against alternative protein entrants while transmitting EU regulatory compliance costs into premium tier pricing.
Pricing Analysis
Bundled nutrition-plus-extension-service contracts in Vietnam's Mekong Delta farming clusters command 15-20 percent premiums over standalone feed purchasing. Three-tier pricing structure across premium, standard, and economy levels separates certified sustainable feeds with full traceability from commodity bulk formulations. Cost compression in standard-tier extruded feeds is intensifying because of microbial biomass scale-up bottlenecks in Northern Europe. Smallholder shrimp cooperatives in Indonesia and India exhibit the highest price sensitivity, while Atlantic salmon producers in Norway prioritize feed conversion efficiency over unit cost.
Supply Chain Analysis
Direct-to-farm channels handle Norwegian and Chilean salmon concession demand through vertically integrated compounders with captive marine protein refining. Raw material sourcing draws from Peruvian anchovy fisheries, North Atlantic fishmeal processors, and Brazilian soy crushing operations. Single-source vulnerability concentrates in methanotrophic bacteria fermentation capacity, with commercial-scale production tethered to Norwegian and Dutch bioreactor installations. Distribution runs through aquafeed traders aggregating fragmented Asian smallholder demand in Vietnam's Cần Thơ and India's Andhra Pradesh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal REACH restrictions on marine ingredient sourcing are accelerating reformulation R&D budgets across Atlantic salmon supply chains.
For Market Incumbents: Anchor defensive positioning through backward integration into single-cell protein fermentation capacity in Norway and the Netherlands. Secure exclusive offtake agreements with methanotrophic bacteria developers before commercial scale-up completes. Cargill and BioMar Group must defend against Asian trading house entrants bundling credit with extension services in Vietnamese shrimp cooperatives. For New Entrants and Emerging Players: Aquafeed traders with cold-chain logistics capabilities represent the most viable channel partnership for penetrating India's fragmented Andhra Pradesh and West Bengal farming zones. Target larval microencapsulation diets for marine finfish hatcheries in Spain and Japan, where live feed replacement demand outpaces qualified supplier capacity. Lead with precision-dosed micronutrient protocols rather than commodity bulk formulations. For Investors and Strategic Acquirers: Diversified agribusiness conglomerates with captive soy processing are the most active acquirer in this space, seeking marine-specialist compounders to complete aquaculture nutrition portfolios. Acquisition targets should display hatchery formulation expertise and EFSA-authorized encapsulant portfolios. Monitor EFSA additive approval timelines for insect meal and algal oil as inflection indicators for alternative protein valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Biomass | Norwegian compounders secure captive single-cell protein supply independent of marine ingredient quotas. |
| EFSA Novel Food Authorization | Approved insect meal and algal oil unlocks premium pricing for certified sustainable feed tiers. |
| Integrated Multi-Trophic Procurement Bundles | Vietnamese cooperatives consolidate purchasing power through nutrition-plus-extension-service contracts. |
| Larval Microencapsulation Capacity Expansion | Spanish and Japanese hatcheries reduce Artemia dependency with precision-dosed replacement diets. |
| REACH-Compliant Antioxidant Reformulation | Natural tocopherol blends replace ethoxyquin to maintain EU market access for salmon feeds. |
Research Methodology
Coverage spans Norway, Chile, Vietnam, India, and the United States, with primary inputs from each anchoring regional demand calibration. The research combines structured interviews with compounder R&D directors, salmon farming concession managers, Mekong Delta aquafeed traders, and FSSAI regulatory affairs specialists with secondary validation from EU Green Deal implementation documents, EFSA novel food registers, and FAO aquaculture production statistics. Bottom-up tonnage estimates across species-specific feed conversion ratios triangulate against top-down market value projections.
Granularity-level modeling distinguishes extruded feeds, pellets, and microencapsulated larval diets by species application and formulation technology across the projection horizon. Segmentation dimensions include product format, production stage, end-user channel structure, and processing technology. CAGRs derive from fitted growth curves applied to base-year volume estimates, with sensitivity analysis around fishmeal price volatility and microbial protein adoption rates.
Revisions become necessary when EFSA accelerates or delays novel ingredient approval timelines, when North Atlantic fishery quotas shift substantially, or when Indian PLI scheme incentives alter cold-chain infrastructure buildout pace. Forecasts reflect documented assumptions regarding regulatory harmonization progress and alternative protein scale-up timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Herring Market
Seafood
Octopus Market
Seafood
Wild Pollock Market
Seafood
Oyster Meal Market
Seafood
Lobster Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Dry-Packaged Scallops Market
Seafood
Food Clamshells Market
Seafood
Surimi Market
Seafood
Sea Biscuits Market
Seafood
Europe Lobster Market
Seafood
Sea Bream Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Processed Seafood Market
Seafood
Halibut Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market