
 Electroactive Polymers (EAP) Market | 2026-2036
Electroactive Polymers (EAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Electroactive Polymers (EAP) Market Foresight
Medical robotics is rebalancing the end-use vertical mix as surgical actuator procurement outpaces traditional automotive damping contracts. Solvay leverages fluoropolymer expertise to anchor high-purity ionic polymer supply for implantable devices. Parker Hannifin competes through integrated motion systems that bundle EAP actuators with precision control electronics. BASF sustains R&D intensity in dielectric polymer formulations for industrial sensor arrays.
Electroactive polymers are macromolecular materials that exhibit dimensional or property changes in response to applied electric fields, with dielectric elastomers typically operating at voltages above one kilovolt and achieving strains exceeding ten percent. Their primary commercial purpose lies in transduction—converting electrical signals into mechanical work for actuation, sensing, and energy harvesting across electromechanical systems. Conductive polymers command mature volume positions in antistatic and electromagnetic shielding applications, while dielectric polymers capture expanding share in soft robotics and haptic interfaces where high strain response justifies premium positioning. Ionic polymers retain niche but defensible margin pools in biomedical micro-actuators where biocompatibility certification creates supply scarcity.
EPA material safety standards and FDA biocompatibility frameworks govern implantable and wearable EAP applications in the United States, while REACH and RoHS compliance in the European Union restricts residual monomer content and hazardous additive use in consumer-facing products. ISO 10993 biological evaluation protocols further condition market access for healthcare-grade polymer suppliers across both jurisdictions. Stakeholders must monitor evolving regulatory convergence between medical device and chemical safety regimes to anticipate certification cost shifts and supply qualification timelines.
Market Dynamics
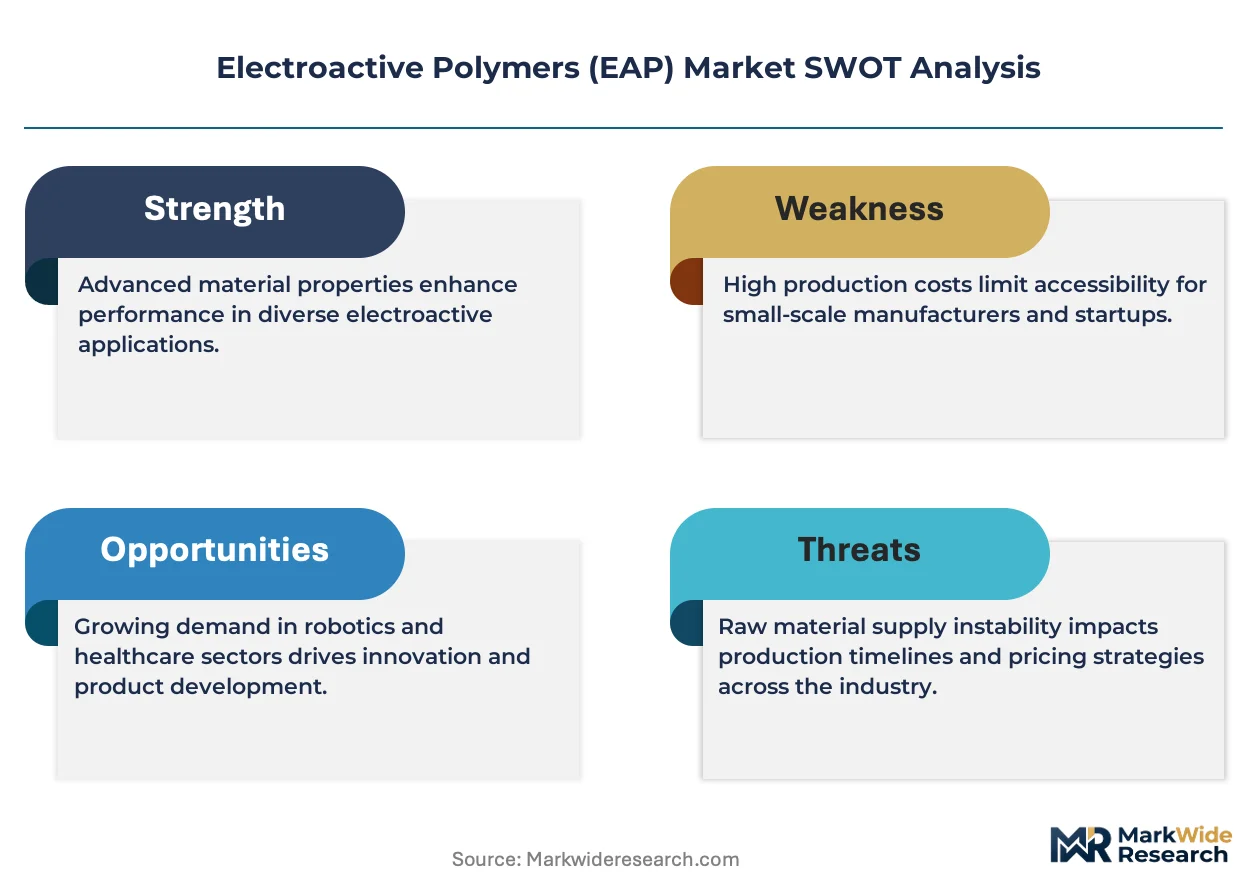
Medical robotics procurement is compressing actuator qualification timelines while REACH and FDA biocompatibility frameworks simultaneously extend polymer certification cycles, creating a structural tension between speed-to-market and compliance depth.
Growth Catalysts
- Minimally invasive surgical tool demand:Medical device manufacturers in Germany's Stuttgart-Mannheim corridor are scaling dielectric elastomer procurement for precision actuation in robotic surgical platforms.
- REACH compliance thresholds:ECHA's tightening residual monomer limits for implantable-grade polymers are filtering out commodity suppliers and concentrating margin with certified specialty producers.
- Dielectric elastomer strain performance:Materials achieving above-ten-percent strain at reduced voltage profiles are capturing share in soft robotics and haptic interface development.
Market Restraints
- High-voltage operation requirements:Dielectric elastomer actuators requiring above-one-kilovolt drive electronics impose substantial power conditioning costs and safety system complexity.
- Biocompatibility certification scarcity:ISO 10993-compliant ionic polymer supply concentrates among limited specialty chemical producers with multi-year qualification backlogs.
- Piezoelectric ceramic substitution:Mature piezo actuator technology retains cost advantages in precision positioning applications below millimeter-scale displacement requirements.
Strategic Opportunities
- Biomedical micro-actuator white space:Implantable drug delivery and microsurgical instruments represent underpenetrated demand for ionic polymer transducers with certified biocompatibility profiles.
- Industrial sensor array expansion:Dielectric polymer formulations for distributed strain sensing in structural health monitoring are displacing conventional resistive gauge networks.
- EU Green Deal material mandates:RoHS-aligned additive restrictions are creating preference for halogen-free conductive polymer formulations in consumer electronics shielding applications.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous FDA 510(k) and EMA MDR pathway navigation extends product launch timelines by eighteen to thirty-six months for implantable EAP devices.
- Cross-functional talent scarcity:Polymer chemists with combined electromechanical transduction and regulatory submission expertise command premium compensation and limit R&D team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroactive Polymers (EAP) Market |
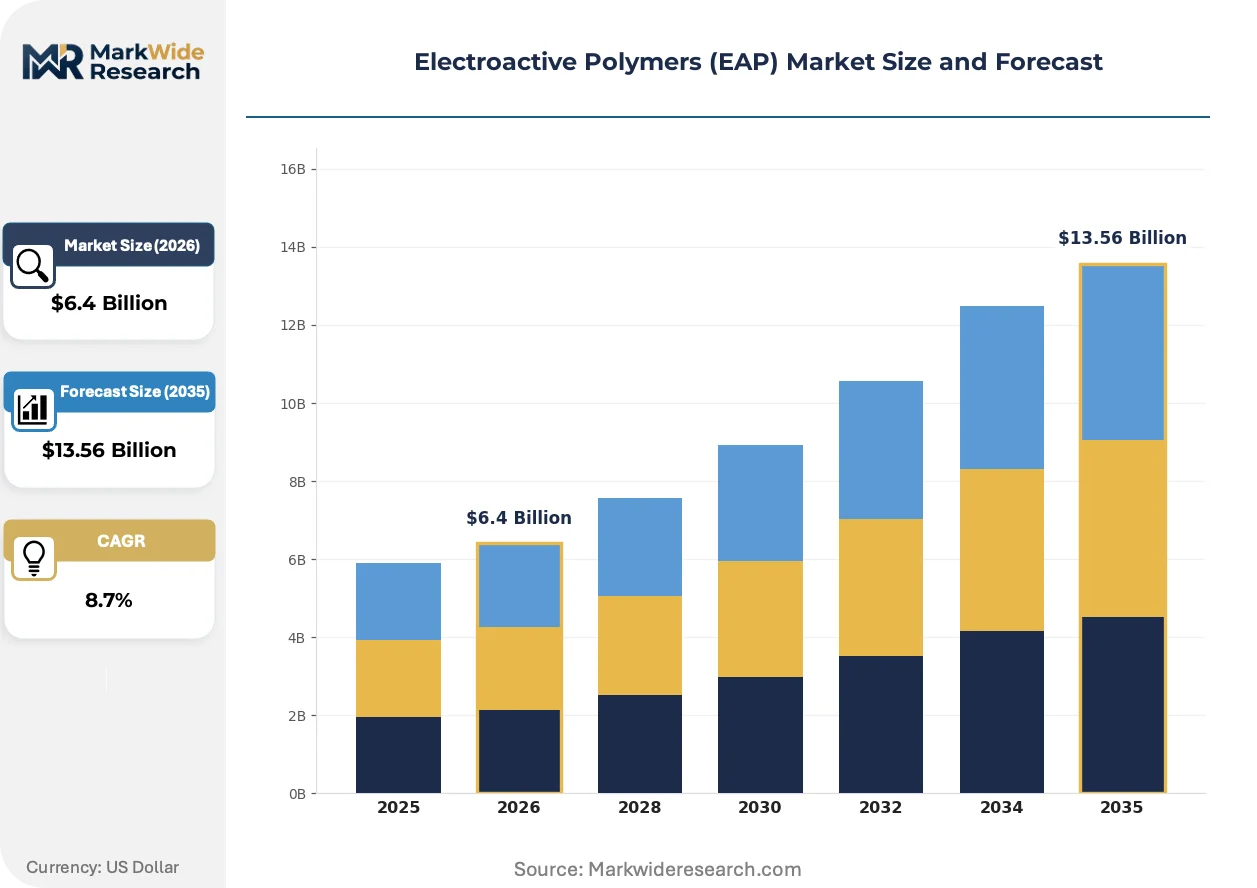
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionic Polymers, Conductive Polymers, Dielectric Polymers, Shape Memory Polymers Application: Actuators, Sensors, Artificial Muscles, Damping Materials End User: Aerospace, Automotive, Robotics, Healthcare Technology: 3D Printing, Coating, Injection Molding, Hybrid Systems |
| Companies Covered | Solvay, 3M, Parker Hannifin, BASF, DuPont de Nemours, Arkema, Merck, Evonik Industries, Agfa-Gevaert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroactive Polymers (EAP) Market Shifts & Advancements
Electroactive polymer development is bifurcating between high-performance medical-grade specialization and cost-optimized industrial sensor deployment, with regulatory convergence forcing simultaneous compliance investments across both tracks.
Dielectric elastomer composites with carbon nanotube electrode configurations are expanding into soft robotics and wearable haptic systems. Automotive seating suppliers and surgical simulator manufacturers are piloting these materials for proprioceptive feedback applications. The technology is expanding into territory previously dominated by pneumatic artificial muscles and electromagnetic solenoids, compressing the addressable market for legacy actuator architectures.
REACH Annex XVII restrictions on phthalate plasticizers and residual monomer content are forcing reformulation of legacy ionic polymer membranes. ECHA's 2023-2024 substance evaluation wave has flagged several quaternary ammonium compounds common in ionic EAP electrolyte layers. Medical-grade suppliers with pre-validated alternative chemistries are capturing displaced volume from commodity producers facing substance authorization deadlines.
Device OEMs are consolidating actuator procurement through qualified supplier programs rather than spot-market purchasing. Tier-one medical robotics firms in Germany and the United States are requiring multi-year supply agreements with embedded regulatory update clauses. This pattern is most pronounced in minimally invasive surgical tool manufacturing, where FDA master file cross-referencing locks in polymer supplier relationships across product generations.
Electroactive Polymers (EAP) Market Segmentation
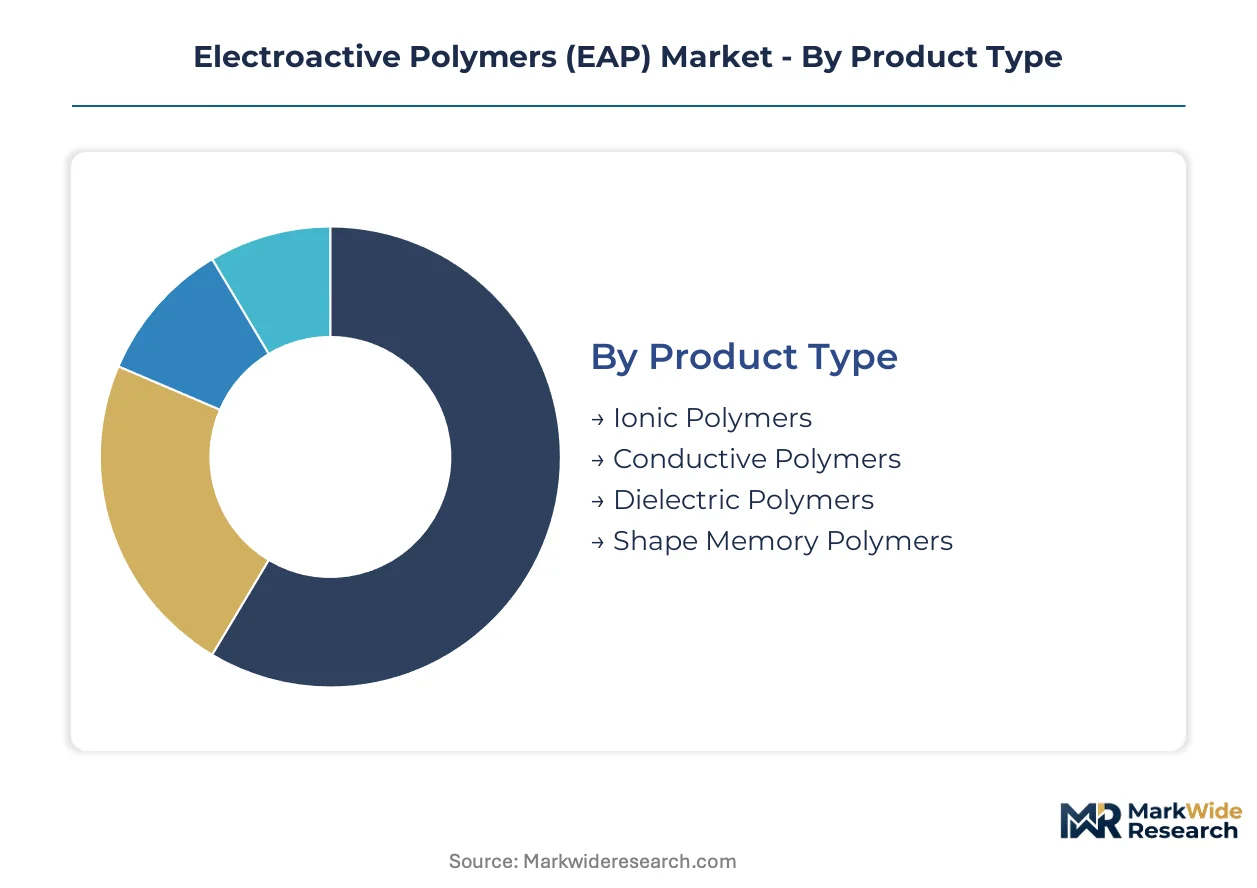
Electroactive polymer procurement decisions hinge on voltage-strain tradeoffs, biocompatibility certification status, and integration complexity with legacy electromechanical systems. Segmentation reveals where margin concentrates versus where volume scales.
Product Type:
Upgrade cycles in surgical robotics and soft automation are displacing legacy actuator materials with strain-optimized polymer formulations.
- Ionic Polymers:These materials operate through ion mobility in hydrated electrolyte matrices, achieving low-voltage actuation below five volts. Demand clusters in Stuttgart's medical device corridor for implantable micro-actuators where ISO 10993 certification creates supply scarcity. FDA biocompatibility master file cross-referencing locks in multi-year supplier relationships.
- Dielectric Polymers:Elastomer films with compliant electrodes achieve strains exceeding ten percent at kilovolt-scale fields. Robotic surgical platform manufacturers in Germany and the United States are scaling procurement for haptic feedback systems. High-voltage drive electronics remain the primary adoption constraint.
- Conductive Polymers:Mature volume positions in antistatic packaging and electromagnetic shielding applications. REACH RoHS-aligned additive restrictions are forcing halogen-free reformulation.
- Shape Memory Polymers:Thermal-electric dual responsiveness serves niche deployment in deployable aerospace structures and adaptive medical stents.
Conductive polymers sit at the top of the volume ranking, with dielectric polymers climbing the fastest.
Application:
Cost tier differentiation separates precision medical applications from industrial commodity deployments.
- Actuators:Primary transduction function converting electrical signals to mechanical displacement. Minimally invasive surgical tool manufacturers command premium pricing for sub-millimeter precision.
- Sensors:Distributed strain sensing in structural health monitoring is displacing resistive gauge networks across civil infrastructure and wind turbine blade applications.
- Artificial Muscles:Pneumatic artificial muscle substitution in soft robotics and prosthetic systems. Automotive seating suppliers pilot proprioceptive feedback integration.
- Damping Materials:Vibration suppression in precision manufacturing equipment and aerospace secondary structures. Mature pricing with limited differentiation.
Actuator applications hold the revenue concentration, with sensor deployment expanding most quickly.
End User:
Customer type determines certification burden and procurement timeline intensity.
- Healthcare:Implantable and surgical applications impose FDA 510(k) and EMA MDR dual pathway navigation. Germany's precision engineering corridor anchors European demand.
- Robotics:Soft robotics and haptic interface development drive dielectric elastomer consumption. Tier-one firms require qualified supplier programs with embedded regulatory update clauses.
- Automotive:Seating feedback systems and active aerodynamic elements represent emerging demand pockets. Piezoelectric ceramic substitution pressure persists in precision positioning below millimeter scale.
- Aerospace:Deployable structures and adaptive morphing surfaces command performance premiums. Qualification cycles extend procurement timelines substantially.
Healthcare commands the steepest pricing tier, with robotics gaining share fastest.
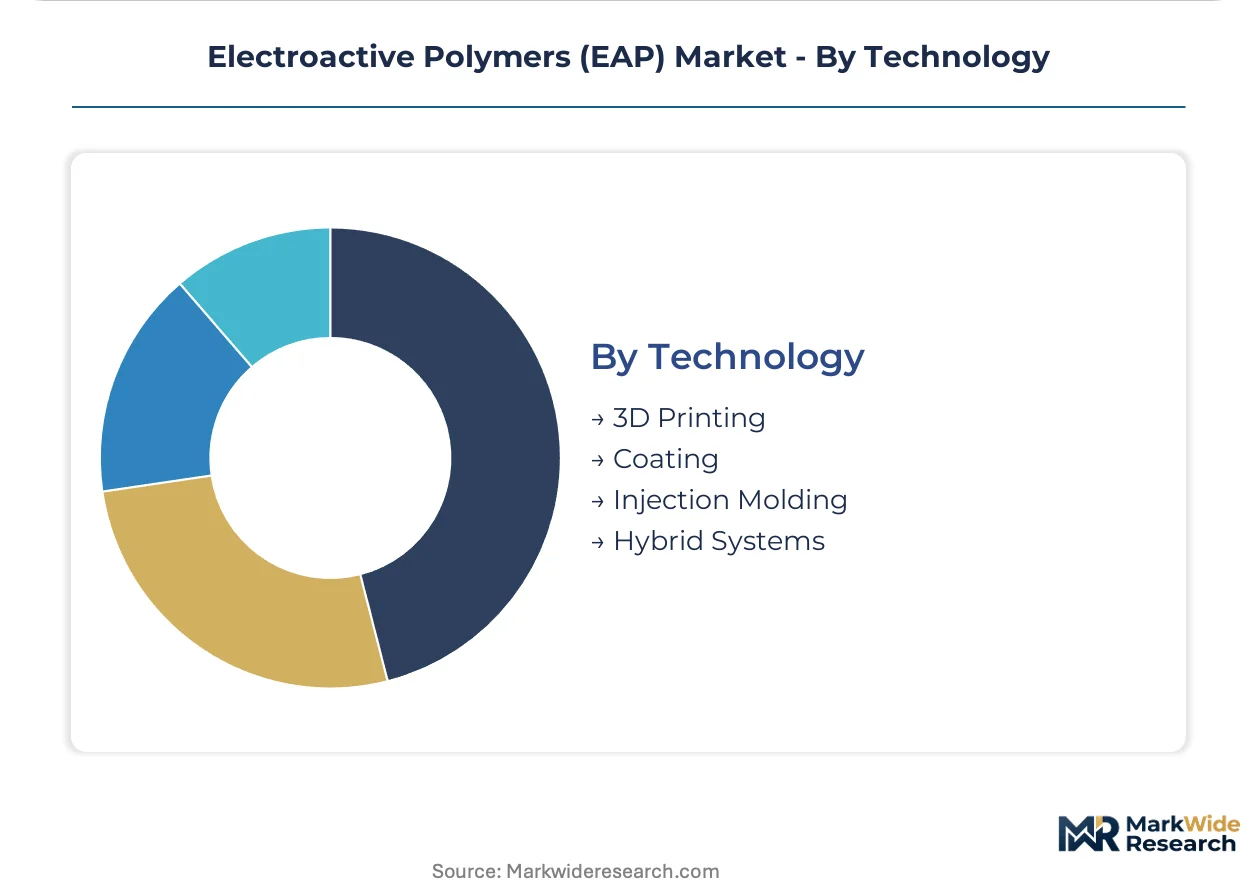
Technology:
Manufacturing process selection determines geometric complexity limits and electrode integration fidelity.
- Injection Molding:High-volume production of dielectric elastomer actuators with embedded electrode geometries. Scales cost-effectively for automotive and consumer applications.
- 3D Printing:Enables gradient property distribution and complex internal channeling for ionic polymer micro-actuators. Medical device prototyping and patient-specific implant fabrication.
- Coating:Thin-film deposition for compliant electrode layers and protective encapsulation. Critical for achieving consistent field distribution.
- Hybrid Systems:Multi-process integration combining molded substrates with printed functional layers. Emerging approach for next-generation surgical instruments.
Injection molding dominates current volume, with 3D printing representing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping EAP production geography as specialty polymer manufacturers migrate toward jurisdictions with harmonized certification pathways and concentrated end-use demand. Cost-of-compliance gaps between fragmented national regimes and unified regional frameworks are accelerating supplier relocation decisions.
United States
FDA 510(k) clearance timelines for implantable EAP devices compress procurement cycles for surgical robotics OEMs in Massachusetts and California. EPA material safety standards govern residual monomer thresholds in wearable applications. Boston's Route 128 corridor anchors medical device prototyping clusters where ionic polymer suppliers co-locate with catheter manufacturers.
Germany
EMA MDR pathway navigation and REACH Annex XVII compliance create dual-certification premiums for Stuttgart-based precision engineering suppliers. ECHA substance evaluation waves are disqualifying commodity ionic polymer producers from implantable-grade supply. The Mannheim-Stuttgart corridor concentrates dielectric elastomer procurement for minimally invasive surgical platforms.
China
NMPA medical device registration reforms are accelerating market access for certified EAP suppliers serving domestic surgical robotics manufacturers. MIIT industrial standards for high-voltage dielectric materials align with GB certification requirements for automotive haptic systems. Yangtze River Delta manufacturing zones host injection molding capacity for consumer electronics shielding applications.
Japan
PMDA biocompatibility frameworks for implantable polymers maintain stringent qualification barriers that favor established specialty chemical producers. METI funding programs for soft robotics R&D are expanding dielectric elastomer demand in Osaka-Kobe industrial zones. Kansai region precision equipment manufacturers are qualifying domestic ionic polymer sources for micro-actuator integration.
Switzerland
Swissmedic medical device regulations and REACH-aligned chemical safety standards create premium certification environments for high-purity polymer supply. ISO 10993 testing infrastructure in Basel supports implantable-grade material validation for cross-border EU market access. Swiss specialty chemical producers leverage dual jurisdiction expertise to anchor European medical EAP supply.
Electroactive Polymers (EAP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade ionic polymer supply concentrating among certified specialty chemical houses while industrial dielectric elastomer production fragments across regional compounders. Three archetypes dominate: fluoropolymer-anchored high-purity suppliers, integrated motion system bundlers, and dielectric formulation specialists. M&A activity targets regulatory certification assets, and capacity expansion focuses on qualified medical-grade production lines.
Within the high-purity specialty tier, Solvay and DuPont de Nemours occupy positions anchored by fluoropolymer expertise and materials science depth. Parker Hannifin exemplifies the integrated systems archetype, bundling actuator hardware with control electronics. BASF represents the formulation-intensive segment, sustaining R&D investment in dielectric polymer architectures. These three patterns—materials purity, system integration, and formulation innovation—capture distinct margin pools across the EAP value chain.
| Leading Market Players |
|---|
| Solvay |
| 3M |
| Parker Hannifin |
| BASF |
| DuPont de Nemours |
| Arkema |
| Merck |
| Evonik Industries |
| Agfa-Gevaert |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialty polymer houses in Germany and Switzerland anchor implantable-grade EAP supply, translating multi-generational certification expertise into pricing power that resists commodity erosion. Their concentrated ownership structures prioritize margin defense over volume capture, tightening supply availability for medical robotics OEMs while sustaining premium positioning against integrated chemical conglomerates.
Pricing Analysis
Distributor margins on ionic polymer membranes absorb ISO 10993 qualification costs before reaching catheter manufacturers in Boston's Route 128 corridor. Contract-based long-term offtake agreements dominate, with pricing stratifying across implantable-certified, industrial-grade, and consumer-electronics tiers. Cost compression in conductive polymer shielding reflects halogen-free reformulation mandates from REACH RoHS alignment. Automotive seating suppliers exhibit highest price sensitivity, while surgical robotics OEMs accept premium positioning for sub-millimeter precision actuation.
Supply Chain Analysis
Certification backlogs at FDA and EMA gatekeepers fragment supply concentration across Germany, Switzerland, and the United States for medical-grade material. Fluoropolymer precursors, carbon nanotube electrode formulations, and quaternary ammonium electrolyte compounds constitute critical input dependencies. Single-source vulnerability concentrates in ECHA-compliant ionic polymer membrane production. Distribution runs through qualified supplier programs with embedded regulatory update clauses rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electroactive Polymers market compounds steadily as surgical robotics procurement institutionalizes multi-year supply agreements with regulatory continuity provisions. This contractual anchoring insulates specialty producers from cyclical demand swings.
For Market Incumbents: Extend certification asset portfolios into adjacent biocompatibility frameworks before ECHA substance evaluation waves disqualify legacy electrolyte chemistries. Deepen upstream control over fluoropolymer precursor supply to defend margin position against integrated motion system bundlers. Lock in FDA master file cross-referencing with tier-one surgical robotics OEMs across product generations. For New Entrants and Emerging Players: Carbon nanotube electrode integration expertise offers entry traction into dielectric elastomer composites for soft robotics prototyping. Target haptic feedback development programs at automotive seating suppliers and surgical simulator manufacturers lacking qualified polymer sources. Pursue co-development partnerships with 3D printing service bureaus serving patient-specific implant fabrication. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade dielectric compounders facing REACH reformulation costs without medical certification optionality. Five-to-ten-year viability favors targets with pre-validated alternative chemistries for ionic polymer electrolyte layers. Watch ECHA substance authorization deadline announcements as inflection signals for supply displacement volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Cross-Referencing | Locks polymer suppliers into multi-generational surgical instrument programs with Boston and Stuttgart OEMs. |
| Backward Integration into Fluoropolymer Precursors | Secures high-purity ionic polymer supply margins against Solvay and DuPont de Nemours positioning. |
| Halogen-Free Conductive Polymer Reformulation | Aligns electromagnetic shielding output with EU Green Deal RoHS mandates for consumer electronics. |
| 3D Printing Process Qualification | Enables patient-specific micro-actuator geometries for implantable drug delivery catheter manufacturers. |
| EMA MDR Dual-Pathway Certification | Opens Stuttgart-Mannheim corridor access for implantable-grade dielectric elastomer surgical platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer chemists, regulatory affairs leads at medical device OEMs, GPO contracts managers, and EMA notified body representatives with secondary validation. FDA 510(k) filings, ECHA substance evaluation databases, ISO 10993 test house reports, and SEC chemical segment disclosures anchored data triangulation alongside customs trade flows for fluoropolymer precursors. Bottom-up polymer procurement modeling and top-down surgical robotics platform deployment estimates converged through iterative reconciliation.
Historical reference periods anchored growth rate derivation across the projection horizon, with segmentation modeling spanning product type, application function, end-user industry, and manufacturing process technology. Voltage-strain performance thresholds, biocompatibility certification status tiers, and integration complexity with legacy electromechanical systems shaped demand elasticity assumptions. CAGRs emerged from curve-fitting across disclosed capacity expansion timelines and qualified supplier program announcements.
The model holds under stable regulatory convergence between FDA and EMA frameworks; deviation in ECHA substance authorization timelines or NMPA registration reform acceleration would shift supply concentration assumptions. Forecasts embed qualification backlog persistence and REACH Annex XVII enforcement intensity as core assumptions. A model refresh is warranted upon material change in surgical robotics OEM procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Alginate Films Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Silicone Gel Market