
 Hydrolysis Stable Polyester Films Market | 2026-2036
Hydrolysis Stable Polyester Films Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolysis Stable Polyester Films Market Foresight
Copolymer modification with cyclohexane dimethanol is tilting formulation strategies toward PETG variants that withstand prolonged hot-water exposure. Toray Industries sustains technology leadership through integrated resin-to-film manufacturing in Japan. Mitsubishi Chemical Corporation leverages proprietary catalyst systems to anchor premium positioning in electronics-grade films. BASF SE competes on backward integration into specialty monomers for hydrolysis-resistant copolyesters.
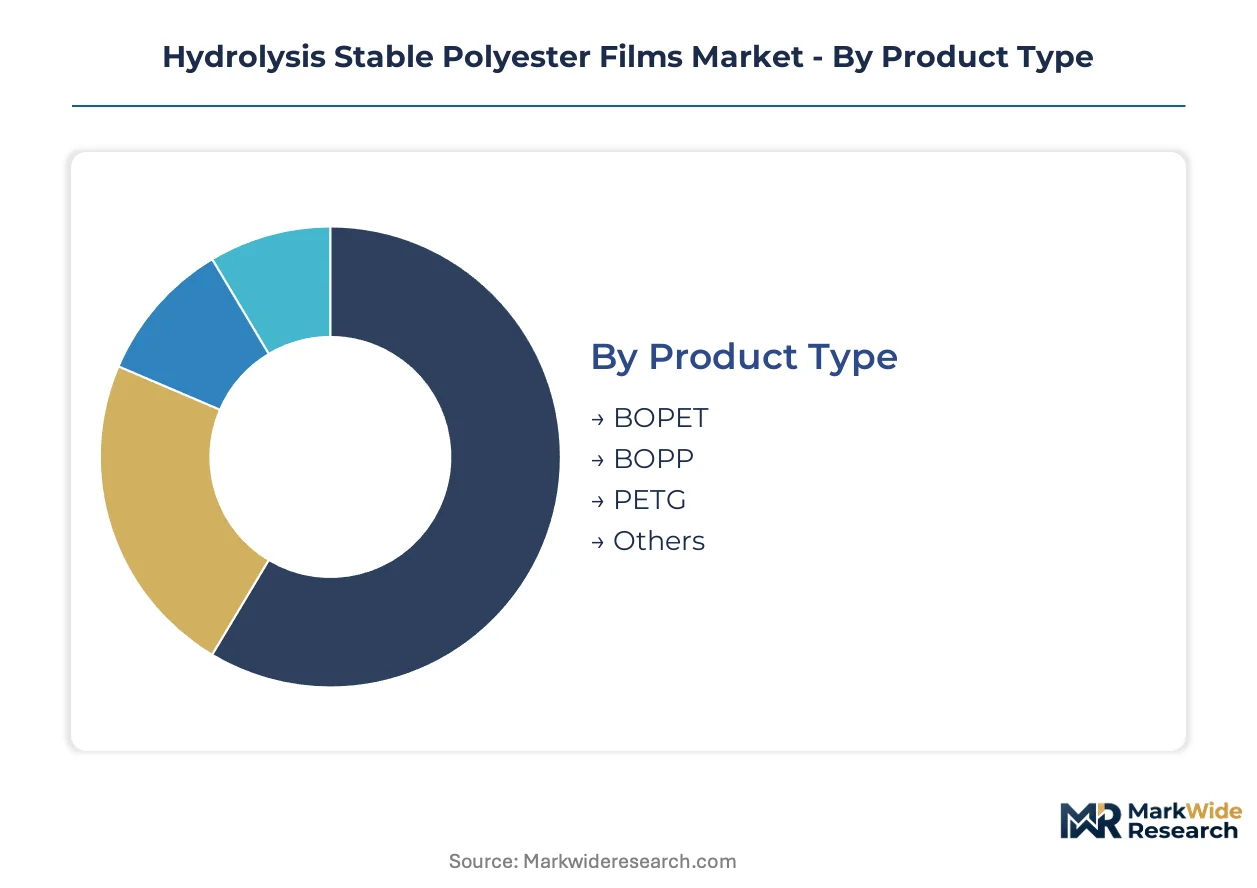
Hydrolysis stable polyester films are biaxially oriented or cast polyethylene terephthalate formulations engineered with modified glycol units or stabilizer packages to resist molecular chain scission in humid environments above 60°C, serving primarily as dimensional substrates and moisture barriers in applications requiring decade-long service life. BOPET occupies the dominant volume position due to mature biaxial stretching infrastructure and broad converter familiarity, while PETG captures the fastest expansion as automotive battery manufacturers specify its superior thermoformability and hydrolytic endurance for thermal runaway barriers. Coextrusion technology leads margin pools by enabling functional layering of hydrolysis-resistant skins over cost-optimized cores.
REACH restricts phthalate-based plasticizers and mandates full substance registration for imported film formulations into Europe, while the F-Gas Regulation phases down fluorinated blowing agents used in certain lamination processes. Japan's METI enforces JIS standards for electrical insulation films that explicitly specify hydrolysis resistance testing protocols. Stakeholders must monitor evolving battery safety codes across automotive OEMs, as these private specifications increasingly override generic polymer standards in supplier qualification decisions.
Market Dynamics
Automotive electrification is compressing qualification timelines for hydrolysis-stable films as battery OEMs demand decade-long service warranties in humid thermal environments. Tier suppliers now face parallel certification tracks against OEM proprietary standards alongside legacy JIS and REACH compliance frameworks.
Growth Catalysts
- Battery Thermal Barrier Mandates:Electric vehicle OEMs specify hydrolysis-resistant PETG films for thermal runaway protection between pouch cells. Germany's KBA safety directives now reference these materials in type-approval documentation.
- REACH Chemical Restrictions:Phased limitations on phthalate plasticizers in conventional polyester films push converters toward copolyester alternatives with inherent hydrolytic stability.
- Japan's METI Electrical Standards:Revised JIS C 2318 protocols explicitly require hydrolysis resistance testing for films in humid-location electrical equipment.
Market Restraints
- Cyclohexane Dimethanol Supply Concentration:CHDM feedstock for PETG variants depends on Asian petrochemical complexes, exposing European compounders to freight and tariff volatility.
- F-Gas Regulation Lamination Constraints:Fluorinated blowing agents used in certain film bonding processes face phasedown under EU rules, forcing process requalification.
- Fluoropolymer Substitution Threat:ETFE and FEP films offer superior hydrolytic endurance in extreme battery applications, though at substantially higher unit cost.
Strategic Opportunities
- Underpenetrated US Battery Corridor:Southeast Asian and Korean film suppliers have limited presence in Michigan and Tennessee EV manufacturing clusters despite proximity to Ford and GM battery plants.
- CSRD-Driven Material Traceability:European corporate sustainability reporting requirements create demand for certified-recyclate hydrolysis-stable films with full substance documentation.
- Coextrusion-Sensor Convergence:Integration of printed temperature sensors within multilayer hydrolysis-resistant films enables real-time battery health monitoring.
Industry Challenges
- OEM Proprietary Certification Timelines:Volkswagen, BMW, and Mercedes-Benz maintain non-harmonized hydrolysis test protocols, forcing suppliers to duplicate validation studies.
- Specialized Extrusion Talent Scarcity:Biaxial stretching operators with hydrolysis-stabilizer dosing expertise concentrate in Japan and Germany, limiting new entrant capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolysis Stable Polyester Films Market |
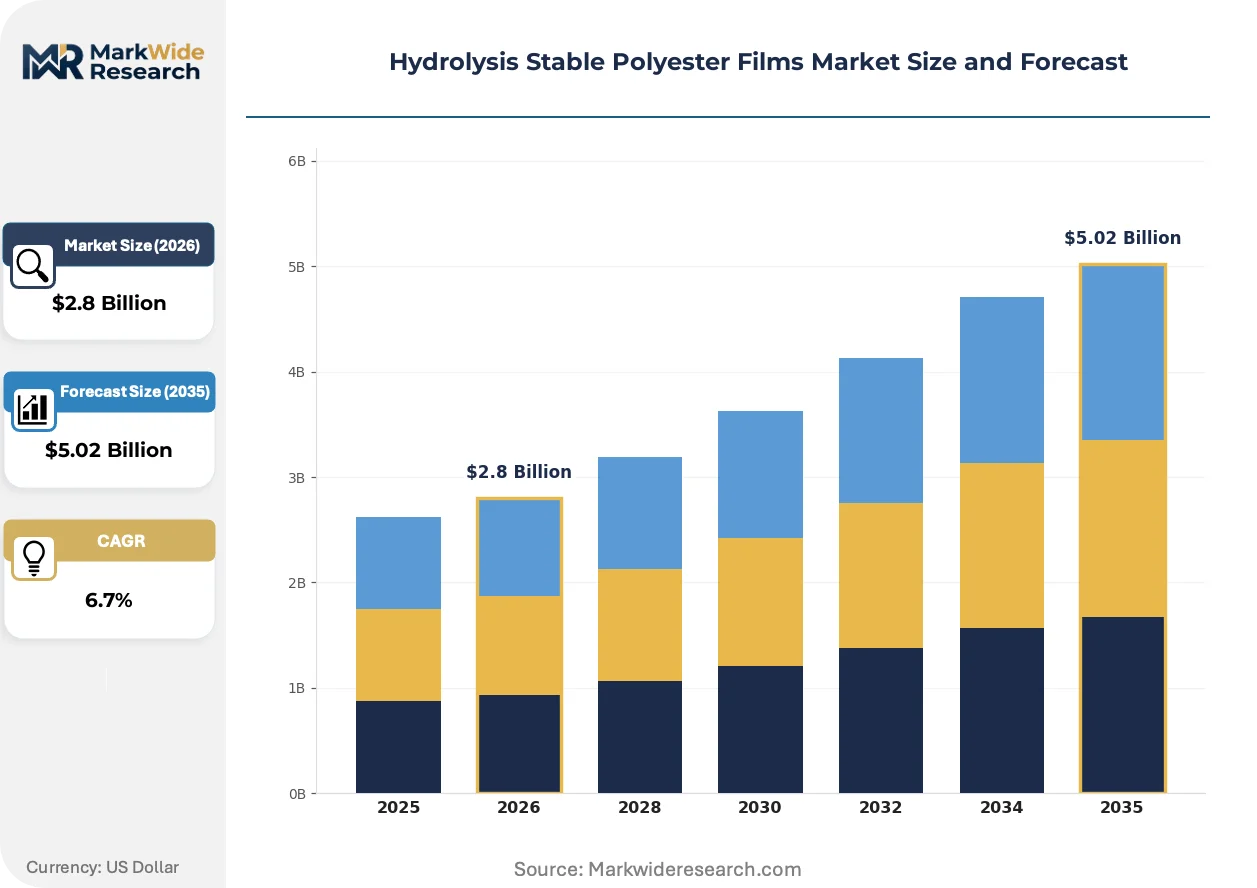
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BOPET, BOPP, PETG, Others Application: Packaging, Electronics, Automotive, Industrial End User: Food & Beverage, Healthcare, Consumer Goods, Personal Care Technology: Coextrusion, Lamination, Extrusion, Casting |
| Companies Covered | BASF SE, Clariant AG, Evonik Industries AG, Solvay SA, Lanxess AG, Toray Industries, Inc., Mitsubishi Chemical Corporation, Polyplex Corporation Limited, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolysis Stable Polyester Films Market Shifts & Advancements
Formulation chemistry and manufacturing process control are converging to extend service life predictions while compressing qualification cycles for next-generation battery architectures.
Coextruded structures with hydrolysis-resistant skin layers over recycled PET cores are collapsing the cost-performance tradeoff that previously separated premium electronics-grade films from industrial packaging alternatives. Korean battery manufacturers specify these constructions for non-critical barrier applications. The technology is collapsing price premiums for mid-tier thermal management applications.
Europe's F-Gas Regulation is accelerating solvent-based and thermal lamination process redevelopment. Converter investments in aqueous adhesive systems now dominate capital allocation discussions in Germany's industrial corridor. Battery pack assemblers in Stuttgart and Munich are qualifying these alternative bonding methods ahead of regulatory deadlines.
Specification authority is migrating from polymer standards bodies to automotive OEM battery safety teams. Tier suppliers now negotiate directly with BMW and Mercedes-Benz materials engineers rather than referencing generic ISO or JIS protocols. This behavioral shift concentrates in Germany's automotive engineering clusters where private standards override public certification.
Hydrolysis Stable Polyester Films Market Segmentation
Hydrolysis stable polyester films serve radically different performance requirements across battery thermal barriers, medical packaging, and industrial moisture shields. Segmentation reveals how formulation chemistry and manufacturing process selection map to distinct value pools and qualification timelines.
Product Type:
Use-case spectrum spans commodity moisture barriers to precision-engineered electrical substrates with decade-long service guarantees.
- BOPET:Biaxially oriented polyethylene terephthalate dominates installed capacity with mature stretching infrastructure and broad converter familiarity. Battery pack manufacturers in Germany's industrial corridor specify BOPET for cost-optimized cell wrapping where dimensional stability under cyclic humidity matters more than thermoformability.
- PETG:Glycol-modified copolyesters incorporate cyclohexane dimethanol units that suppress crystallization and extend hydrolytic endurance in hot-water environments. Automotive OEMs in Stuttgart and Munich mandate PETG for thermal runaway barriers between pouch cells due to superior thermoformability and compliance with KBA safety directives.
- BOPP:Biaxially oriented polypropylene offers lower moisture transmission rates at reduced cost but sacrifices hydrolytic stability above 60°C, limiting adoption to ambient packaging applications.
- Others:Cast PET and specialty copolyesters serve niche medical packaging segments requiring sterilization resistance.
Established volume favors BOPET; emerging adoption favors PETG.
Application:
Application mix reflects diverging certification intensity from automotive safety mandates to commodity packaging conversion.
- Automotive:Electric vehicle battery architectures drive the steepest specification escalation. Thermal runaway barriers between pouch cells demand hydrolysis-resistant films with documented decade-long performance in humid thermal cycling, per BMW and Mercedes-Benz proprietary protocols.
- Electronics:Flexible printed circuit substrates and display protection films require JIS C 2318 compliance for humid-location electrical equipment. Japanese METI enforcement of revised testing protocols compresses supplier qualification timelines.
- Packaging:Food and pharmaceutical barrier applications prioritize cost efficiency over extended hydrolytic endurance, with converters favoring standard PET grades where shelf-life requirements permit.
- Industrial:Protective masking and release films for composite manufacturing tolerate shorter service life expectations.
Automotive commands premium pricing; packaging anchors volume scale.
End User:
End-user concentration determines whether procurement prioritizes traceability documentation or conversion economics.
- Healthcare:Medical device manufacturers and pharmaceutical packagers demand full REACH substance registration and CSRD-aligned material traceability. German converters report accelerating requests for certified-recyclate hydrolysis-stable films with complete documentation chains.
- Food & Beverage:Extended shelf-life packaging for retort pouches and hot-fill applications specifies hydrolysis-resistant grades where conventional polyester films suffer chain scission. European phthalate restrictions under REACH push converters toward copolyester alternatives.
- Consumer Goods:Electronics and appliance manufacturers reference JIS standards for internal component protection.
- Personal Care:Cosmetic packaging applications favor clarity and printability over hydrolytic endurance.
Healthcare drives compliance premiums; food and beverage sustains baseline demand.
Technology:
Process selection determines functional layering capability and capital intensity for hydrolysis stabilization.
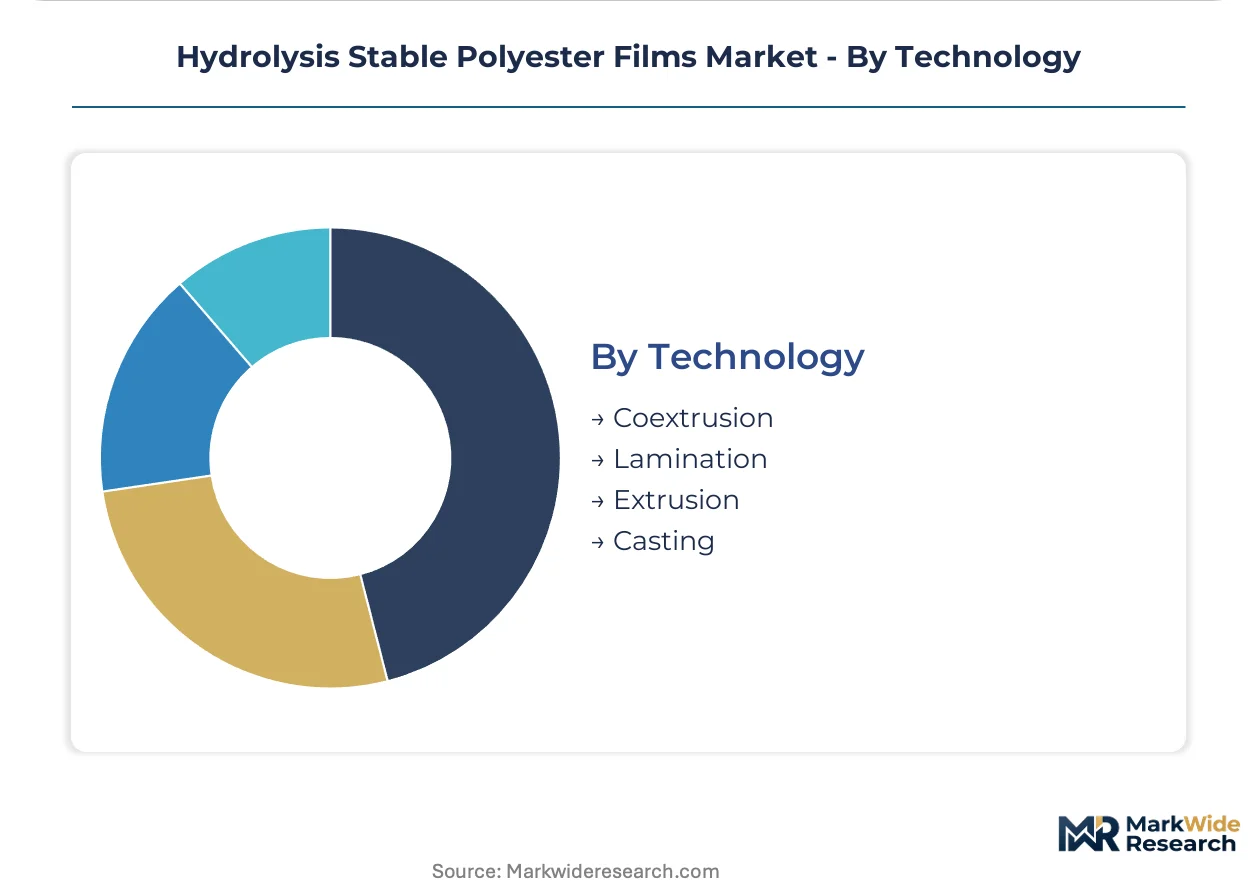
- Coextrusion:Multilayer extrusion enables functional skin layers of hydrolysis-resistant copolyester over cost-optimized recycled PET cores. Korean battery manufacturers specify these constructions for non-critical barrier applications, collapsing price premiums for mid-tier thermal management.
- Lamination:Adhesive bonding of dissimilar films faces process requalification pressure from Europe's F-Gas Regulation phasing down fluorinated blowing agents. German converters in Stuttgart and Munich dominate capital allocation toward aqueous adhesive system investments.
- Extrusion:Single-layer cast and blown film lines serve commodity packaging with limited hydrolysis stabilization.
- Casting:Chill-roll casting produces optical-grade films for display applications with precise thickness control.
Coextrusion captures margin expansion; lamination faces regulatory-driven reinvestment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery OEM procurement teams in Germany, Japan, South Korea, and the United States dominate specification authority for hydrolysis-stable films, with converter networks clustering around automotive engineering centers and petrochemical feedstock corridors.
Germany
Stuttgart and Munich house BMW and Mercedes-Benz battery safety engineering teams that enforce proprietary hydrolysis test protocols. The KBA references these materials in type-approval documentation for electric vehicle thermal barriers. BASF SE anchors backward integration into specialty monomers at its Ludwigshafen complex.
Japan
METI's revised JIS C 2318 protocols mandate hydrolysis resistance testing for humid-location electrical equipment. Toray Industries operates integrated resin-to-film manufacturing in Shiga Prefecture. Mitsubishi Chemical Corporation leverages proprietary catalyst systems for electronics-grade film production in Yokkaichi.
South Korea
LG Energy Solution and Samsung SDI battery plants in Ochang and Ulsan specify coextruded PETG constructions for non-critical thermal barriers. Domestic compounders face CHDM feedstock dependence on Asian petrochemical complexes. The Busan-Ulsan industrial corridor concentrates biaxial stretching capacity.
United States
Ford and GM battery manufacturing clusters in Michigan and Tennessee attract limited Southeast Asian and Korean film supplier presence. NHTSA safety guidelines for battery thermal management influence material selection. The Southeast automotive corridor remains underpenetrated by established Asian converters.
China
CATL and BYD battery gigafactories in Ningde and Shenzhen drive domestic PETG demand for pouch cell barriers. GB standards for electrical insulation films incorporate hydrolysis resistance benchmarks. The Yangtze River Delta concentrates casting and biaxial orientation capacity for display-grade substrates.
Hydrolysis Stable Polyester Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated petrochemical conglomerates with captive resin production anchor the premium segment, while regional converters with biaxial stretching expertise serve mid-tier industrial applications. The competitive landscape rewards backward integration into specialty monomers and coextrusion technology licensing. Capacity expansion and strategic partnerships with battery OEMs represent the dominant competitive moves.
Among German chemical conglomerates, BASF SE and Evonik Industries AG exemplify the backward-integrated archetype with upstream control over hydrolysis-resistant copolyester chemistry. Japanese industrial groups Toray Industries, Inc. and Mitsubishi Chemical Corporation occupy positions defined by integrated manufacturing from resin synthesis through film orientation. These players represent the technology-leadership tier where proprietary catalyst systems and JIS certification dominance create qualification barriers.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Evonik Industries AG |
| Solvay SA |
| Lanxess AG |
| Toray Industries, Inc. |
| Mitsubishi Chemical Corporation |
| Polyplex Corporation Limited |
| Jindal Poly Films Limited |
| Others |
Supply & Pricing Matrix
Asian petrochemical complexes producing cyclohexane dimethanol concentrate upstream margin capture, forcing European compounders to absorb freight volatility while battery OEMs in Stuttgart and Munich negotiate fixed-price contracts for thermal barrier films.
Pricing Analysis
Cost-plus contracts with CHDM indexation dominate procurement between German automotive OEMs and film suppliers, with pricing stratifying across JIS-certified electronics grades, KBA-referenced automotive tiers, and industrial packaging alternatives. Price differentiation centers on hydrolysis test protocol compliance and volume scale, with OEM proprietary certification adding substantial premiums. Cost compression in mid-tier coextruded constructions is intensifying because Korean battery manufacturers qualify recycled-core alternatives. Packaging converters show highest price sensitivity, while automotive safety engineers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between South Korean compounders and European automotive OEMs dominates supply chain risk planning as CHDM feedstock flows from Chinese and Japanese petrochemical corridors. Raw material dependencies center on purified terephthalic acid, ethylene glycol, and cyclohexane dimethanol monomer streams. Single-source vulnerability concentrates in specialized catalyst systems held by Mitsubishi Chemical and proprietary coextrusion technology licensing. Distribution runs through converter networks clustered around Germany's industrial corridor, Japan's Shiga Prefecture, and Korea's Busan-Ulsan corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification is disrupting qualification timelines as battery OEMs compress decade-long warranty documentation into 18-month certification cycles, creating structural advantage for incumbents with validated resin-to-film infrastructure.
For Market Incumbents: Pre-empt fluoropolymer substitution threats by accelerating coextruded PETG thermal barrier validation against BMW and Mercedes-Benz proprietary protocols. Secure captive CHDM supply through long-term offtake agreements with Asian petrochemical complexes. Defend margin pools by licensing coextrusion technology to qualified converters rather than ceding volume to unlicensed competitors.
For New Entrants and Emerging Players: Pursue underpenetrated positions in Michigan and Tennessee EV manufacturing clusters where Ford and GM battery plants lack proximate Asian converter presence. Target aqueous adhesive lamination process redevelopment demanded by Europe's F-Gas Regulation phasedown. Enter through coextrusion equipment partnerships with Korean battery manufacturers seeking non-critical barrier alternatives.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters possessing biaxial stretching infrastructure but lacking backward integration into specialty monomers. Five-to-ten year viability hinges on certification depth against migrating OEM proprietary standards rather than legacy JIS compliance. Monitor KBA type-approval documentation referencing hydrolysis-resistant films as inflection signal for premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CHDM Monomers | BASF's Ludwigshafen complex anchors European supply security against Asian freight volatility. |
| Coextrusion Technology Licensing | Toray's integrated Shiga Prefecture operations create qualification barriers for unlicensed converters. |
| Aqueous Adhesive Lamination Investment | Stuttgart and Munich converters dominate capital allocation ahead of F-Gas Regulation deadlines. |
| OEM Proprietary Protocol Certification | BMW and Mercedes-Benz battery safety teams override generic polymer standards in supplier decisions. |
| Certified-Recyclate Film Development | German healthcare demand for CSRD-aligned traceability creates compliance premium capture opportunity. |
Research Methodology
Desk research of customs trade data, SEC chemical company filings, and METI regulatory notices preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, biaxial stretching plant operators, and aqueous adhesive system developers. Secondary validation drew from KBA type-approval databases, REACH substance registration records, and Korean battery manufacturer specification sheets. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Assumptions held fixed include continuation of Europe's F-Gas Regulation phasedown trajectory and METI enforcement of revised JIS C 2318 protocols, while battery OEM proprietary standard migration rates and CHDM supply expansion timelines were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type tier, application certification intensity, end-user traceability requirements, and coextrusion technology adoption. CAGRs were derived from installed capacity expansion announcements cross-referenced against battery thermal barrier specification volumes.
Sensitivities concentrate around OEM proprietary protocol harmonization failure, CHDM supply disruption from Asian petrochemical complex maintenance cycles, and fluoropolymer cost reduction trajectories enabling substitution in extreme battery applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market