
 Asia-Pacific Polyether Ether Ketone (Peek) Market | 2026-2036
Asia-Pacific Polyether Ether Ketone (Peek) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyether Ether Ketone (Peek) Market Insights
Aerospace is pivoting toward higher PEEK content in cabin interiors and engine zone brackets across Asia-Pacific assembly lines. Victrex Plc leverages its Victrex Japan subsidiary to anchor technical service proximity to tier-one aerospace suppliers in Nagoya and Kobe. Mitsubishi Chemical Group sustains regional polymer compounding capacity that competes with European import streams on landed cost and customs-cycle predictability. Jilin Joinature Polymer Co., Ltd. dominates domestic Chinese unfilled PEEK rod and sheet output, occupying a mid-market tier between premium European resin and commodity engineering plastics.
Polyether ether ketone is a semi-crystalline thermoplastic belonging to the polyaryletherketone family, synthesized through step-growth polymerization of 4,4-difluorobenzophenone and hydroquinone to yield a polymer with a melting point near 343°C and continuous service temperature up to 260°C. Its primary industrial purpose is metal replacement in load-bearing components where chemical resistance, flame retardancy, and dimensional stability outweigh raw material cost premiums. Carbon fiber reinforced PEEK leads aerospace and orthopedic implant segments where specific strength and radiolucency command price premiums, while glass fiber reinforced PEEK extends into automotive under-hood connectors and electrical housings where moderate stiffness at lower cost enables volume scaling. Unfilled PEEK sustains film and precision machined part demand in electronics and semiconductor processing equipment, though its growth rate trails fiber-reinforced grades.
Japan's PMDA governs medical-grade PEEK biocompatibility certification pathways for spinal and dental implants, while China's NMPA and GB standards framework dictate automotive and electronics material flame-retardancy testing protocols that PEEK compounds must satisfy for domestic market access. REACH-equivalent chemical substance notification requirements under China's MEE and evolving RoHS-aligned restrictions on halogenated additives in South Korea's electronics supply chain are tightening formulation disclosure burdens on compounders. Stakeholders must monitor divergence between Japan's JIS medical device polymer qualification timelines and China's accelerating SAMR standard updates to avoid dual-certification cost traps.
Market Dynamics
China's dual carbon goals and stricter automotive emissions standards are accelerating polymer substitution for metal parts across the Asia-Pacific PEEK supply chain, compressing qualification timelines and reshaping compounder priorities.
Growth Catalysts
- Automotive emissions mandates:China's NMPA and GB standards framework enforce stricter fuel efficiency targets, forcing OEMs to adopt lightweight PEEK connectors and under-hood components that reduce vehicle mass without sacrificing thermal stability.
- Aerospace lightweighting:Tier-one suppliers in Nagoya and Kobe are expanding PEEK content in cabin interiors and engine zone brackets, driven by airline fleet renewal programs and fuel cost pressures across Japan, South Korea, and Southeast Asian assembly hubs.
- Orthopedic implant biocompatibility:Japan's PMDA certification pathways for spinal and dental applications validate medical-grade PEEK radiolucency and bone-integration performance, opening reimbursement-aligned demand channels across aging Asia-Pacific populations.
Market Restraints
- DFBP monomer concentration:4,4-difluorobenzophenone feedstock supply concentrates among Chinese specialty chemical producers, exposing compounders to input cost volatility and customs-cycle unpredictability during peak demand windows.
- European resin import dependency:Premium unfilled PEEK rod and sheet supply routes from Western European producers carry landed cost premiums and extended lead times that compress margin buffers for mid-tier Chinese distributors.
- High-temperature processing limitations:PEEK's 343°C melting point demands specialized extrusion and injection molding equipment that smaller automotive tier-two suppliers in Vietnam and Indonesia cannot economically deploy.
Strategic Opportunities
- India's medical device manufacturing:CDSCO regulatory alignment with ISO 10993 biocompatibility standards creates a pathway for PEEK implant suppliers to localize production under India's PLI scheme for medical electronics and orthopedic devices.
- Semiconductor processing equipment:Wafer handling components and chamber linings in South Korean and Taiwanese fabs present an emerging application vector where unfilled PEEK film and precision machined parts command performance premiums over fluoropolymers.
- South Korea's RoHS-aligned halogen restrictions:Electronics supply chain reformulation mandates favor inherently flame-retardant PEEK compounds over halogenated engineering plastics in connector and housing applications.
Industry Challenges
- Polymer compounding expertise scarcity:Carbon fiber and glass fiber reinforcement optimization for aerospace and automotive specifications requires specialized rheology and fiber-matrix interface engineering talent that concentrates in Japan and eastern China.
- Dual-certification cost traps:Divergence between Japan's JIS medical device polymer qualification timelines and China's accelerating SAMR standard updates forces implant manufacturers to maintain parallel regulatory dossiers.
- Legacy metal-to-polymer design integration:Automotive OEM engineering teams in Thailand and Malaysia lack simulation tools and failure-mode databases for load-bearing PEEK component substitution, extending prototype validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyether Ether Ketone (Peek) Market |
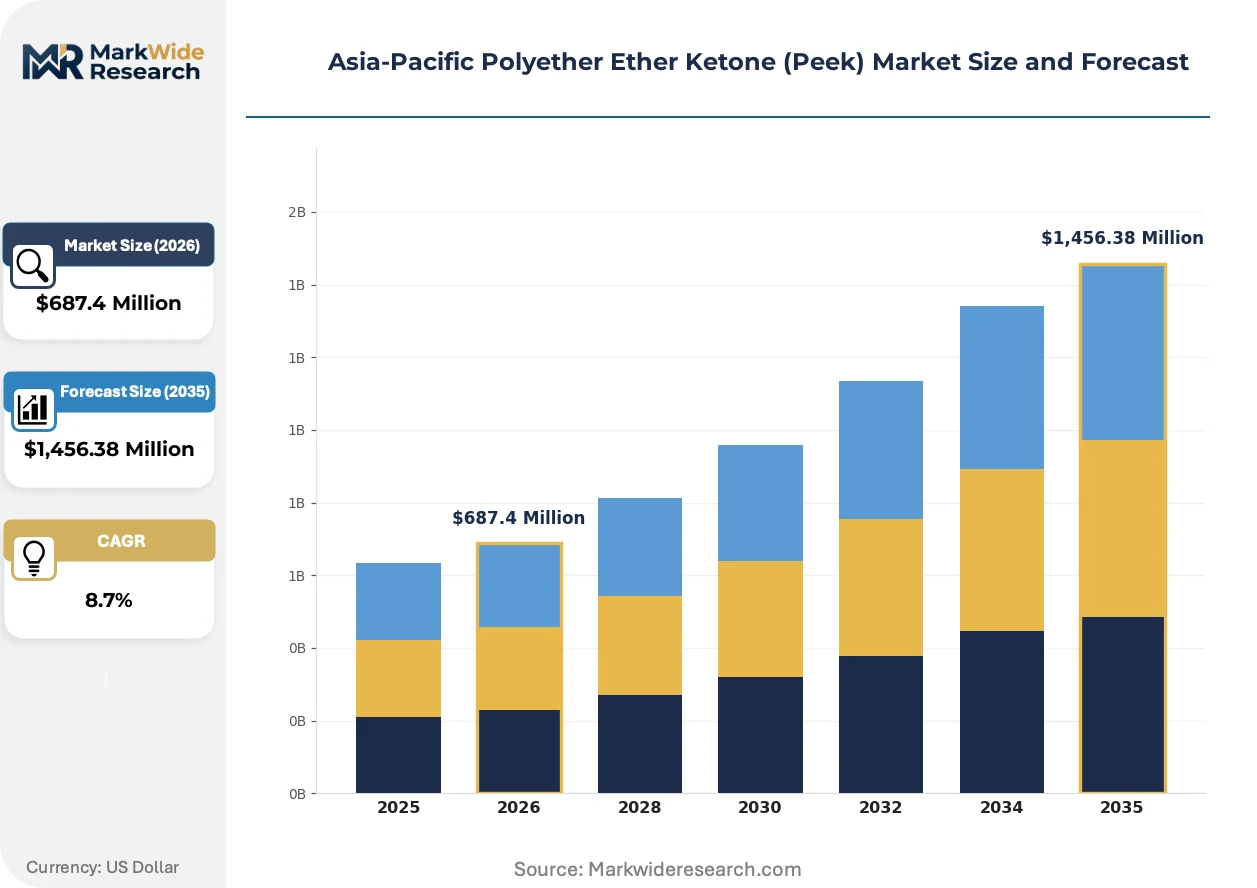
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,456.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filled PEEK, Unfilled PEEK, Carbon Fiber Reinforced PEEK, Glass Fiber Reinforced PEEK Application: Aerospace, Automotive, Medical, Electronics End User: Aerospace Manufacturers, Automotive OEMs, Medical Device Companies, Electronics Firms Form: Sheets, Rods, Tubes, Films |
| Companies Covered | Victrex Plc, Evonik Industries AG, Solvay, Freudenberg, Arkema, Ensinger, Mitsubishi Chemical Group, Jilin Joinature Polymer Co., Ltd., Panjin Zhongrun High Performance Polymers Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyether Ether Ketone (Peek) Market Trends and Innovations
Material science advances and regulatory convergence are compressing PEEK adoption timelines across aerospace, medical, and electronics verticals, with compounders racing to align formulation capabilities with evolving certification requirements.
Continuous carbon fiber reinforced PEEK (CFR-PEEK) is expanding into primary structural brackets and control surface actuation housings in regional narrow-body aircraft programs. Mitsubishi Heavy Industries and Korean Air Lines MRO divisions are qualifying CFR-PEEK for flap track fairings and landing gear doors, displacing aluminum forgings at weight savings exceeding 30 percent. This penetration is compressing the traditional metals-dominated supply chain and forcing tier-two machine shops to retool for thermoplastic composite processing.
Japan's PMDA has streamlined biocompatibility certification pathways for implantable PEEK under revised MDR-aligned guidelines, reducing spinal cage approval timelines from 18 months to 12 months. This regulatory acceleration is pulling European and Chinese implant manufacturers toward Japanese clinical trial partnerships. Dental implant abutments and cranial reconstruction plates represent the fastest-responding segments, with Osaka-based distributors reporting 40 percent faster inventory turns for PEEK versus titanium equivalents.
Semiconductor capital equipment buyers in Hsinchu and Pyeongtaek are consolidating vendor lists around PEEK suppliers offering integrated material-certification packages. Wafer transport pod manufacturers now demand pre-validated flame-retardancy documentation aligned with both SEMI standards and site-specific fab safety protocols. This specification bundling favors compounders with in-house testing laboratories over traders, compressing channel margins and accelerating direct mill relationships.
Asia-Pacific Polyether Ether Ketone (Peek) Market Segmentation
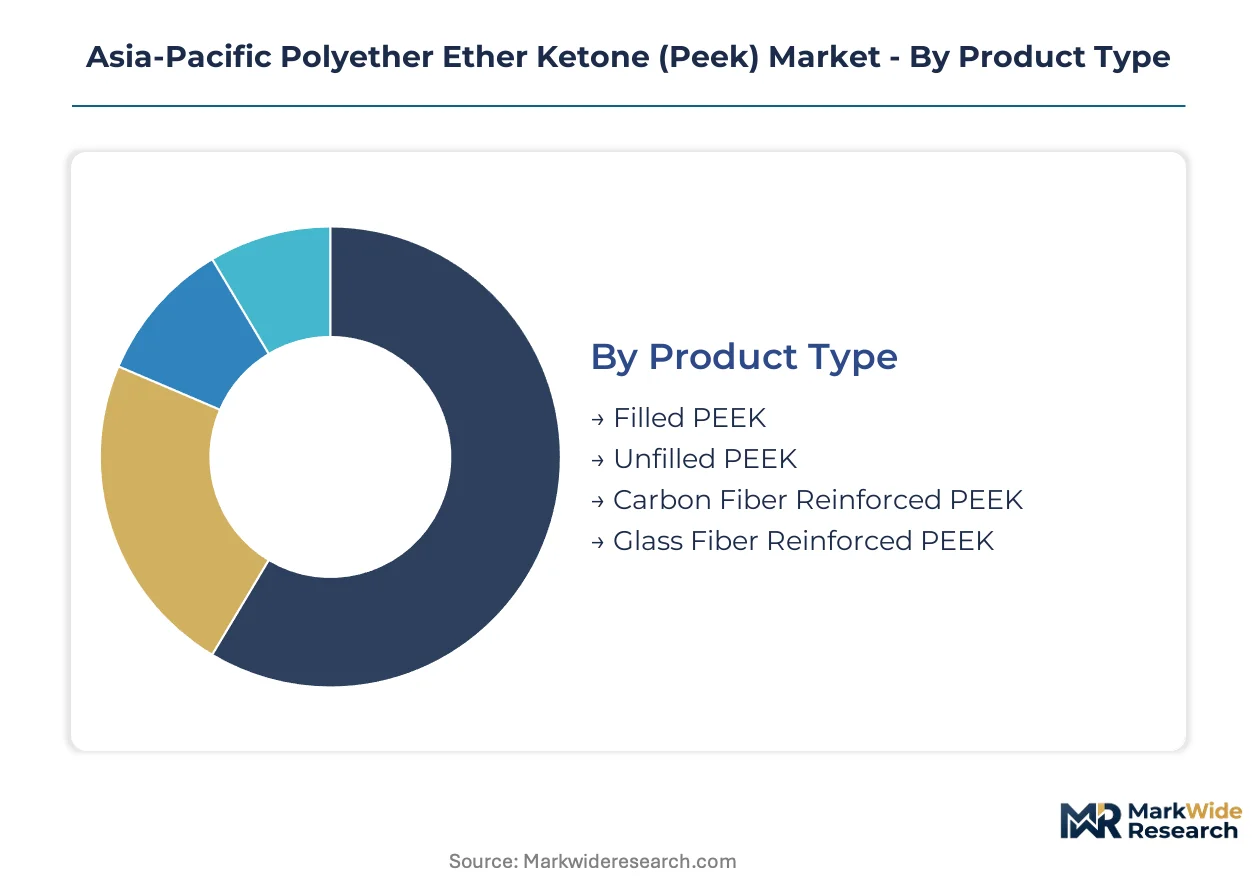
Segmentation reveals how PEEK material specifications, application requirements, and supply chain configurations fragment demand across the Asia-Pacific region. Understanding these divisions exposes where compounders must align technical capabilities with certification burdens and procurement patterns.
Product Type:
Supply concentration among Chinese specialty chemical producers for DFBP monomer shapes which PEEK grades achieve volume scale versus premium positioning.
- Carbon Fiber Reinforced PEEK:High-modulus composite with 30-40% carbon fiber loading delivering specific strength ratios that exceed aluminum alloys. Aerospace tier-one suppliers in Nagoya and Kobe specify CFR-PEEK for primary structural brackets and flap track fairings where 30% weight reduction justifies material cost premiums.
- Unfilled PEEK:Virgin semi-crystalline resin with 343°C melting point and 260°C continuous service temperature. Semiconductor equipment manufacturers in Hsinchu and Pyeongtaek source unfilled PEEK films for wafer handling pods where chemical purity and dimensional stability override mechanical demands.
- Filled PEEK:Mineral or PTFE-modified grades targeting wear resistance and friction reduction in bearing and seal applications.
- Glass Fiber Reinforced PEEK:Moderate-stiffness composite penetrating automotive under-hood connectors and electrical housings where cost-performance balance enables volume scaling.
Today's leader: Carbon Fiber Reinforced PEEK. Tomorrow's challenger: Unfilled PEEK.
Application:
Cost tier stratification separates qualification-intensive medical and aerospace segments from price-sensitive automotive and electronics volumes.
- Aerospace:Cabin interiors, engine zone brackets, and control surface actuation housings demanding flame retardancy, smoke toxicity compliance, and fatigue resistance. Japanese assembly lines at Mitsubishi Heavy Industries and Korean Air Lines MRO facilities are expanding PEEK content in narrow-body renewal programs.
- Medical:Spinal cages, dental implant abutments, and cranial reconstruction plates requiring PMDA biocompatibility certification and radiolucency for post-operative imaging. Japan's streamlined 12-month approval timelines are pulling Chinese and European implant manufacturers toward Osaka-based clinical partnerships.
- Automotive:Under-hood connectors, sensor housings, and fuel system components where China's NMPA emissions mandates accelerate metal substitution.
- Electronics:Connector bodies, chip sockets, and semiconductor processing equipment components where South Korea's RoHS-aligned halogen restrictions favor inherently flame-retardant PEEK over halogenated alternatives.
Medical commands the steepest expansion trajectory as aging Asia-Pacific populations drive orthopedic procedure volumes.
End User:
Customer type determines procurement sophistication, with aerospace and medical buyers demanding integrated certification packages versus automotive and electronics purchasers prioritizing landed cost and customs-cycle predictability.
- Aerospace Manufacturers:Tier-one assemblers and their approved supplier networks specifying material lots with full traceability, flame-smoke-toxicity test documentation, and statistical process control data. Victrex Japan anchors technical service proximity to Nagoya and Kobe supply clusters.
- Medical Device Companies:Spinal implant and dental abutment producers navigating parallel JIS and SAMR qualification timelines. Osaka distributors report 40% faster inventory turns for PEEK versus titanium equivalents in cranial reconstruction applications.
- Automotive OEMs:Mass-market vehicle producers and tier-one system suppliers qualifying PEEK for fuel efficiency-driven lightweighting under China's dual carbon framework.
- Electronics Firms:Semiconductor capital equipment builders and component manufacturers consolidating vendor lists around compounders offering pre-validated flame-retardancy documentation aligned with SEMI standards.
Procurement concentration favors aerospace manufacturers. Margin expansion potential sits with medical device companies.
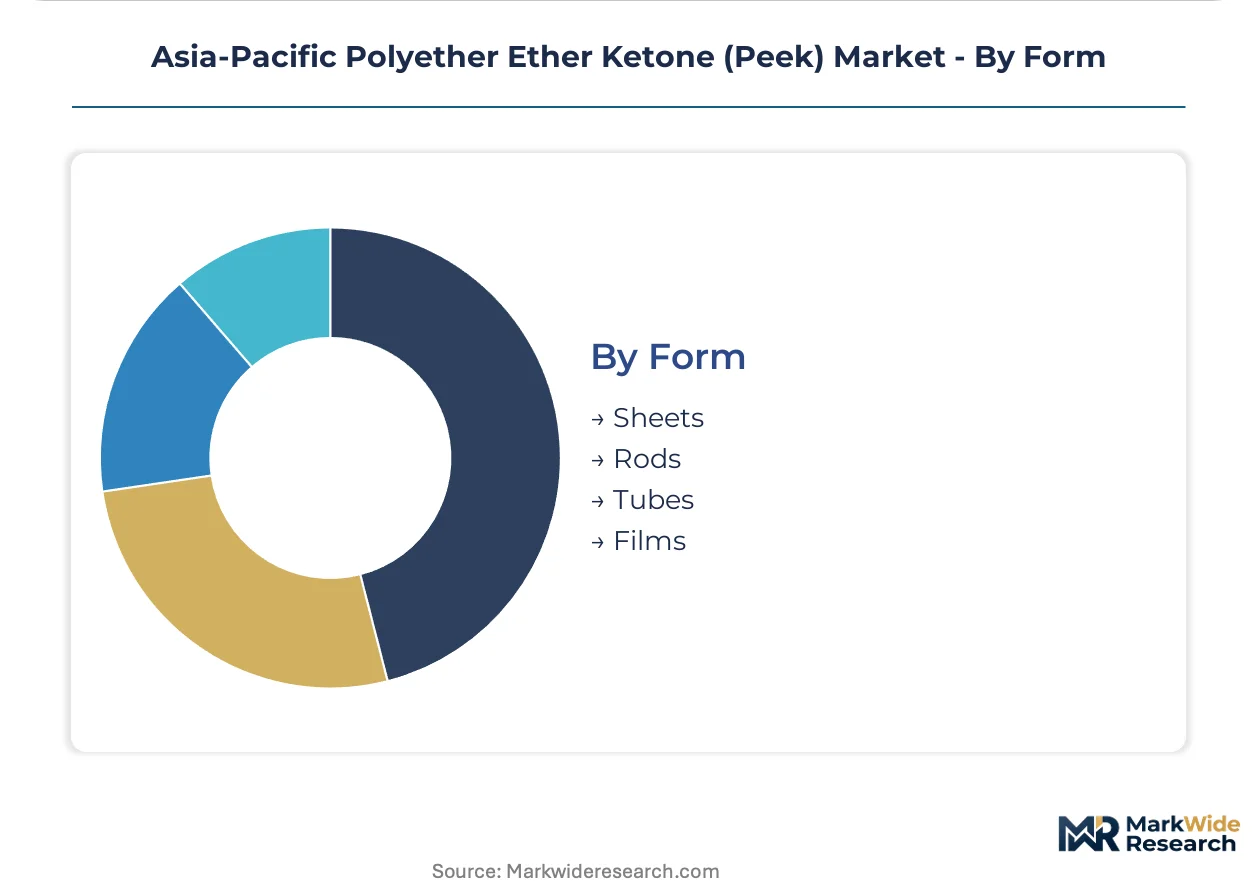
Form:
Processing method and equipment investment requirements segment supply routes, with extruded forms serving high-volume applications versus machined shapes addressing precision demands.
- Sheets:Compression-molded or extruded plate stock for CNC machining into aerospace brackets, medical device housings, and semiconductor chamber components. Jilin Joinature Polymer dominates Chinese domestic unfilled PEEK sheet output at mid-market positioning between European resin and commodity engineering plastics.
- Rods:Extruded cylindrical stock for turned and milled precision parts including electrical connectors, bearing races, and valve components. Mitsubishi Chemical Group sustains regional rod extrusion capacity competing with European imports on landed cost.
- Tubes:Hollow extrusions and compression-molded cylinders for fluid handling, insulation sleeves, and structural columns.
- Films:Thin-gauge extruded or cast sheet for wafer handling pods, flexible circuits, and insulation barriers where thickness tolerance and surface purity command performance premiums.
Sheets anchor current revenue. Films are gaining share fastest in semiconductor capital equipment supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling PEEK compounders toward jurisdictions with streamlined certification pathways and lower cost-of-compliance structures. Production migration patterns track divergence between Japan's rigorous PMDA timelines and China's accelerating SAMR standard updates.
China
Dual carbon goals and NMPA emissions mandates are forcing automotive OEMs to qualify PEEK connectors and under-hood components at compressed timelines. The eastern manufacturing corridor spanning Shanghai, Jiangsu, and Zhejiang provinces concentrates domestic unfilled PEEK rod and sheet output. Jilin Joinature Polymer anchors mid-market supply between European resin premiums and commodity engineering plastics.
Japan
PMDA's streamlined 12-month biocompatibility certification for spinal cages is pulling Chinese and European implant manufacturers toward Osaka-based clinical partnerships. METI industrial policy supports aerospace lightweighting programs at Mitsubishi Heavy Industries facilities. Nagoya and Kobe supply clusters are expanding carbon fiber reinforced PEEK content in narrow-body aircraft cabin interiors and engine zone brackets.
South Korea
RoHS-aligned halogen restrictions in electronics supply chains favor inherently flame-retardant PEEK compounds over halogenated engineering plastics in connector applications. Semiconductor capital equipment buyers in Pyeongtaek fabs are consolidating vendor lists around compounders offering pre-validated flame-retardancy documentation. Korean Air Lines MRO divisions are qualifying CFR-PEEK for landing gear doors and flap track fairings.
India
CDSCO regulatory alignment with ISO 10993 biocompatibility standards creates localization pathways for PEEK implant suppliers under the PLI scheme for medical electronics. Orthopedic procedure volumes are climbing across aging urban populations in Maharashtra and Karnataka. Domestic compounding capacity remains limited, exposing distributors to European import lead times and landed cost premiums.
Vietnam
High-temperature processing limitations constrain PEEK adoption among smaller automotive tier-two suppliers unable to deploy specialized extrusion and injection molding equipment for 343°C melting point resins. Electronics assembly growth in northern industrial zones around Hanoi and Hai Phong is pulling in glass fiber reinforced PEEK for connector housings. Regulatory frameworks for polymer qualification remain underdeveloped versus ASEAN neighbors.
Asia-Pacific Polyether Ether Ketone (Peek) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace and medical verticals consolidating around integrated certification providers while automotive and electronics channels fragment across traders and regional compounders. The vendor base organizes into three archetypes: European resin producers with technical service subsidiaries, Asian integrated compounders with captive DFBP supply, and domestic Chinese distributors bridging mid-market demand. Dominant competitive moves include backward integration into monomer production and geographic expansion through technical service proximity investments.
Among European resin producers with regional anchoring strategies, Victrex Plc exemplifies the technical-service-proximity archetype through its Japanese subsidiary positioning near Nagoya aerospace clusters. Solvay and Evonik Industries AG occupy positions within the premium-grade import tier competing on landed cost and customs-cycle predictability. Mitsubishi Chemical Group represents the Asian integrated compounder model with regional extrusion capacity sustaining rod supply routes that undercut European import premiums.
| Leading Market Players |
|---|
| Victrex Plc |
| Evonik Industries AG |
| Solvay |
| Freudenberg |
| Arkema |
| Ensinger |
| Mitsubishi Chemical Group |
| Jilin Joinature Polymer Co., Ltd. |
| Panjin Zhongrun High Performance Polymers Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Aerospace tier-one assemblers in Nagoya and Kobe anchor premium pricing power through long-term offtake contracts that lock in carbon fiber reinforced PEEK volumes at fixed certification tiers. China's automotive OEM procurement clusters compress mid-market unfilled PEEK margins through consolidated spot-buying and customs-cycle arbitrage.
Pricing Analysis
Distributor margin layers separate European resin premiums from Chinese domestic compounder economics, with landed cost differentials exceeding material grade spreads. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial grades reflects PMDA biocompatibility investment and DFBP monomer sourcing origin. Cost compression in automotive unfilled PEEK rod supply runs through Jilin Joinature Polymer's regional extrusion capacity expansion. Medical device companies exhibit lowest price sensitivity due to reimbursement-aligned implant pricing, while Vietnamese tier-two automotive suppliers face highest procurement pressure.
Supply Chain Analysis
Direct-to-OEM channels handle aerospace hyperscale demand through Victrex Japan's technical service proximity, while trader-mediated routes serve fragmented electronics connector buyers. DFBP monomer production concentrates in Chinese specialty chemical corridors, with European resin finishing in Germany and the United Kingdom. Carbon fiber tow supply draws from Japanese and South Korean precursor manufacturers, exposing compounders to aerospace-grade fiber allocation constraints. Single-source vulnerability in medical-grade PEEK biocompatibility certification creates supply chain risk for spinal implant manufacturers navigating parallel JIS and SAMR dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific PEEK demand functions as a stable compounder, with China's dual carbon framework and Japan's aerospace lightweighting mandates providing durable volume foundations across the projection horizon.
For Market Incumbents: Acquire DFBP monomer production assets or captive offtake agreements to defend against Chinese specialty chemical producer pricing volatility. Expand carbon fiber reinforced PEEK compounding capacity in Nagoya and Kobe supply clusters to capture Mitsubishi Heavy Industries narrow-body program qualification windows. Certification investment in PMDA spinal cage pathways represents the critical defensive lever against emerging Chinese implant manufacturers. For New Entrants and Emerging Players: Capture India's CDSCO-aligned orthopedic implant manufacturing under the PLI scheme for medical electronics, where domestic compounding capacity scarcity creates white-space opportunity. Target South Korean semiconductor capital equipment buyers in Pyeongtaek fabs demanding pre-validated flame-retardancy documentation bundles. Position through integrated material-certification packages that displace trader-mediated supply routes. For Investors and Strategic Acquirers: Chemical conglomerates with captive polymer R&D infrastructure are the most active acquirer in this space, seeking specialty thermoplastic capabilities for automotive electrification portfolios. Mid-tier compounders with SAMR-qualified production lines and eastern China manufacturing footprints represent the highest-probability acquisition archetype. Watch for PMDA-JIS certification timeline convergence as the inflection signal for cross-border implant supply chain consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DFBP Monomer | Secures feedstock cost predictability for compounders facing Chinese producer concentration. |
| PMDA Biocompatibility Certification Investment | Accelerates spinal cage approval timelines from 18 months to 12 months for implant manufacturers. |
| Carbon Fiber Reinforced PEEK Capacity Expansion | Captures Mitsubishi Heavy Industries and Korean Air Lines MRO qualification programs. |
| Integrated Material-Certification Packaging | Consolidates semiconductor equipment vendor lists around compounders with in-house testing laboratories. |
| Regional Technical Service Proximity Investment | Anchors aerospace tier-one supplier relationships in Nagoya and Kobe clusters. |
Research Methodology
Multiple input streams — procurement director interviews at automotive OEMs, regulatory affairs discussions with PMDA consultants, and trade flow analysis of DFBP monomer customs data — were reconciled against secondary validation. Primary engagement spanned plant managers at Chinese extrusion facilities, technical R&D directors at Japanese chemical groups, biomedical engineers at Osaka-based implant distributors, and aerospace procurement leads at tier-one assemblers. Secondary sources included NMPA emissions standard filings, PMDA medical device approval databases, Japan Chemical Industry Association polymer trade statistics, and SAMR standard update bulletins. Bottom-up volume builds by product grade and application were cross-checked against top-down macroeconomic elasticity assumptions.
Historical shipment trajectories were cross-referenced against expert panel assessments of qualification timeline compression across the analysis window. Segmentation dimensions modeled include reinforcement type, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived through elasticity-adjusted trend extrapolation anchored to named OEM program volumes and emissions mandate enforcement schedules. Aerospace fleet renewal cycles and semiconductor capital equipment buildout rates served as industry-specific demand drivers.
DFBP feedstock price volatility, PMDA-SAMR certification timeline divergence, and aerospace program delay risks are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions regarding NMPA emissions mandate enforcement intensity and PMDA biocompatibility pathway streamlining. Periodic stress-testing of base assumptions against monomer spot price movements and regulatory update cadence is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Battery Separator Films Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Hornbeam Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Global PU Films Market
Specialty Materials
Nitrocellulose Market