
 Gutta-Percha Market | 2026-2036
Gutta-Percha Market Size, Share, and Industry Trends Forecast 2026-2036
Gutta-Percha Market Intelligence
Biodegradable polymer engineering is tilting gutta-percha formulations away from pure natural latex derivatives toward modified and biodegradable variants. VDW GmbH leverages its German manufacturing base to sustain precision extrusion capabilities for endodontic points. DiaDent Group International anchors Asian supply chains through controlled raw material sourcing. Kerr Dental differentiates via proprietary synthetic compounding that reduces batch-to-batch variability.
Gutta-percha is the trans-isomer of polyisoprene, a thermoplastic latex derived from Palaquium gutta trees, characterized by low thermal conductivity, excellent electrical resistance, and reversible softening at 65–70°C that enables thermoplastic obturation techniques. Dental procedures occupy the dominant application slot, with natural gutta-percha commanding established clinician trust while modified gutta-percha captures fastest-growing share through enhanced flow characteristics. Biodegradable gutta-percha represents an emerging margin pool as regulators tighten scrutiny on persistent synthetic polymers in medical waste streams.
FDA 510(k) pathways govern U.S. dental device clearance, while EMA MDR requirements and REACH chemical registrations shape European product formulations and market access conditions. ISO 6876 standards for root canal sealing materials establish global baseline performance criteria that manufacturers must satisfy for cross-border commercialization. Stakeholders must monitor evolving biodegradability certification schemes and polymer substitution mandates that will determine which formulation categories retain market access.
Market Dynamics
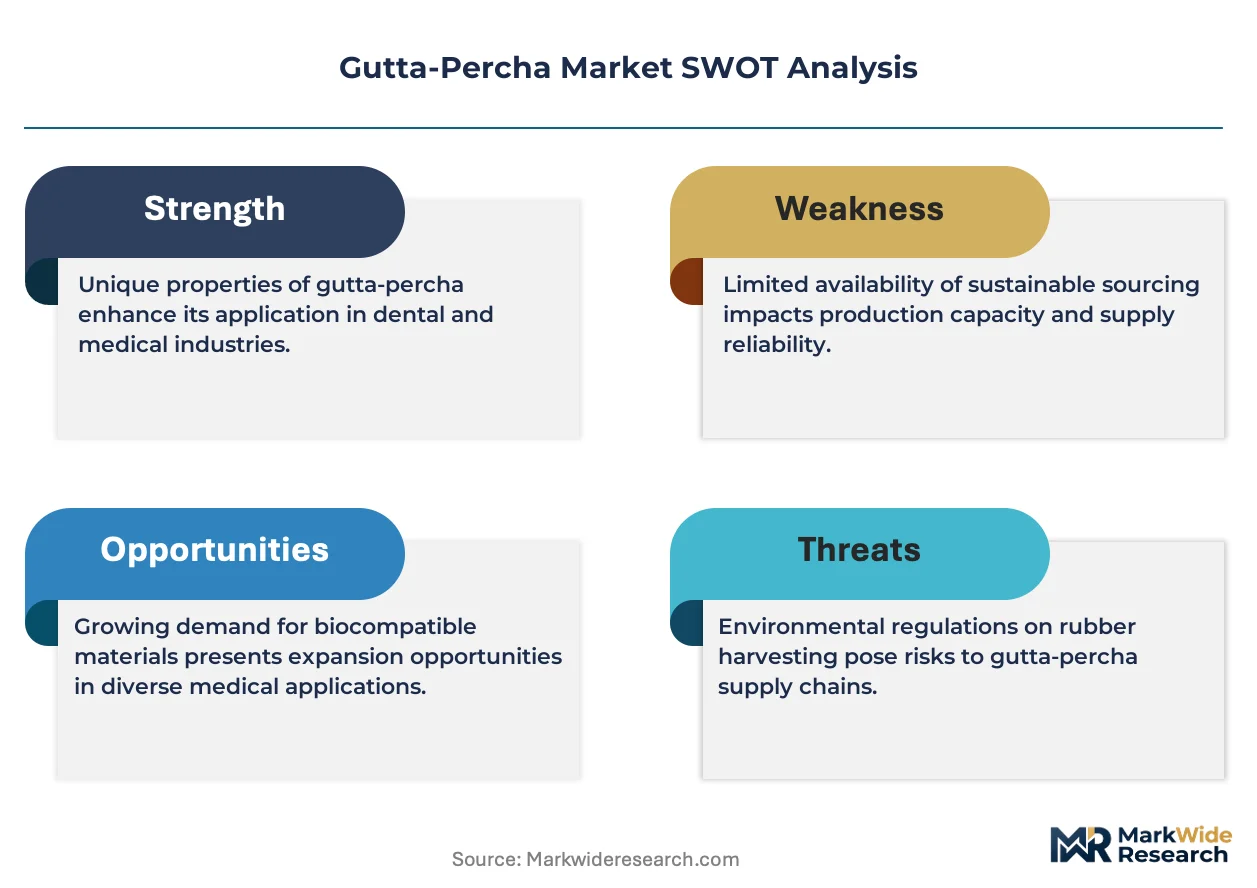
The gutta-percha market pivots on REACH-driven formulation substitution as European chemical registrations force manufacturers toward synthetic and biodegradable polymer alternatives that satisfy endodontic performance standards.
Growth Catalysts
- EMA MDR compliance pathways:European dental device regulations mandate biocompatible obturation materials, accelerating clinician migration from legacy sealers to certified gutta-percha points.
- Thermoplastic obturation techniques:Warm vertical compaction and continuous wave methods exploit gutta-percha's reversible softening properties, expanding procedural adoption in specialized dental clinics.
- German manufacturing concentration:Precision extrusion capabilities anchored in Baden-Württemberg supply chains enable consistent dimensional tolerance for ISO 6876-compliant products.
Market Restraints
- Palaquium gutta latex supply volatility:Natural rubber harvest fluctuations in Southeast Asian plantations create raw material price instability that compresses margin predictability.
- Batch-to-batch consistency limitations:Natural polyisoprene variability forces manufacturers into costly sorting and blending protocols to meet clinical performance thresholds.
- Bioceramic sealer substitution:Mineral trioxide aggregate and calcium silicate-based alternatives capture obturation share in select endodontic applications.
Strategic Opportunities
- Biodegradable certification schemes:Emerging medical waste stream regulations in Germany and France create first-mover advantage for compostable gutta-percha formulations.
- Warm obturation device convergence:Integration with electronic apex locators and cordless obturation systems opens bundled equipment-material revenue streams.
- Specialized dental distributor channels:Direct-to-clinic platforms bypass traditional dental dealer networks, capturing margin and preference data simultaneously.
Industry Challenges
- Polymer engineering talent scarcity:Formulation chemists with combined expertise in thermoplastic behavior and dental biocompatibility remain concentrated in German and Swiss industrial clusters.
- ISO 6876 certification timelines:Extended testing protocols for dimensional stability and sealing ability delay product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gutta-Percha Market |
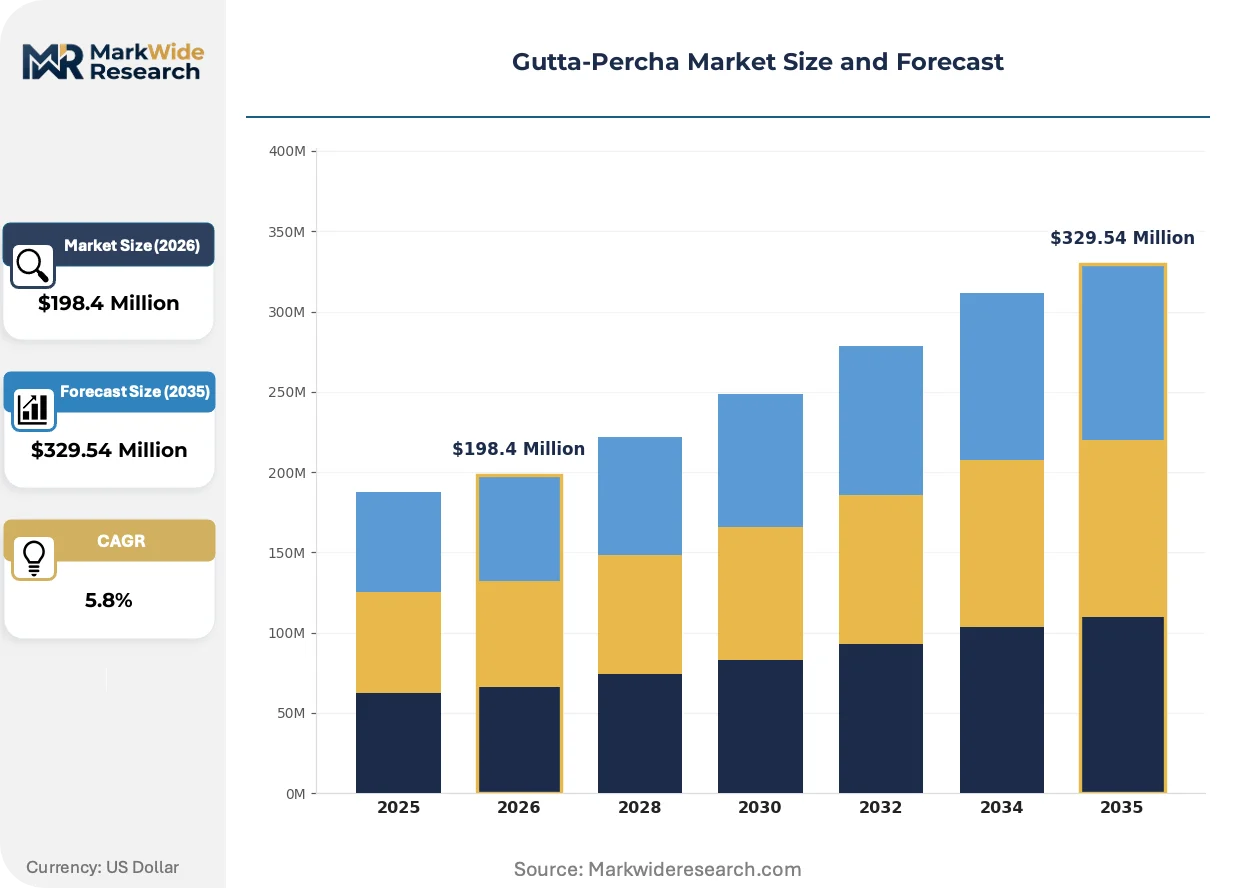
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $329.54 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gutta-Percha, Synthetic Gutta-Percha, Modified Gutta-Percha, Biodegradable Gutta-Percha Application: Dental Procedures, Cable Insulation, Hydraulic Seals, Medical Devices End User: Dental Clinics, Healthcare Institutions, Construction Industry, Electronics Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Ultradent Products, VDW GmbH, Dentsply Sirona, META BIOMED, FKG Dentaire SA, Coltene Whaledent, DiaDent Group International, Ivoclar Vivadent, Kerr Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gutta-Percha Market Strategic Shifts & Innovations
Synthetic compounding and digital manufacturing methods are restructuring how gutta-percha formulations achieve clinical consistency while regulatory pressure accelerates biodegradability research.
Modified gutta-percha incorporating zinc oxide and wax plasticizers is virtualizing traditional natural latex dominance in premium endodontic segments. Large dental service organizations in the United States specify synthetic formulations to reduce procedural variability. This virtualization compresses the addressable market for unmodified natural gutta-percha to cost-sensitive procurement channels.
REACH chemical registration requirements in Europe force reformulation of conventional additives and plasticizers used in gutta-percha compounding. Manufacturers must submit extensive toxicological dossiers for zinc oxide and resin components. German formulators lead adaptation efforts, converting registration burden into competitive differentiation through early compliance.
Clinician procurement patterns favor pre-sterilized single-use obturation points over bulk packaging that requires in-practice sterilization cycles. Dental clinics in France and the United Kingdom accelerate this transition to reduce cross-contamination protocols and labor overhead. Specialized dental distributors capture volume by bundling sterile points with complementary endodontic instruments.
Gutta-Percha Market Segmentation
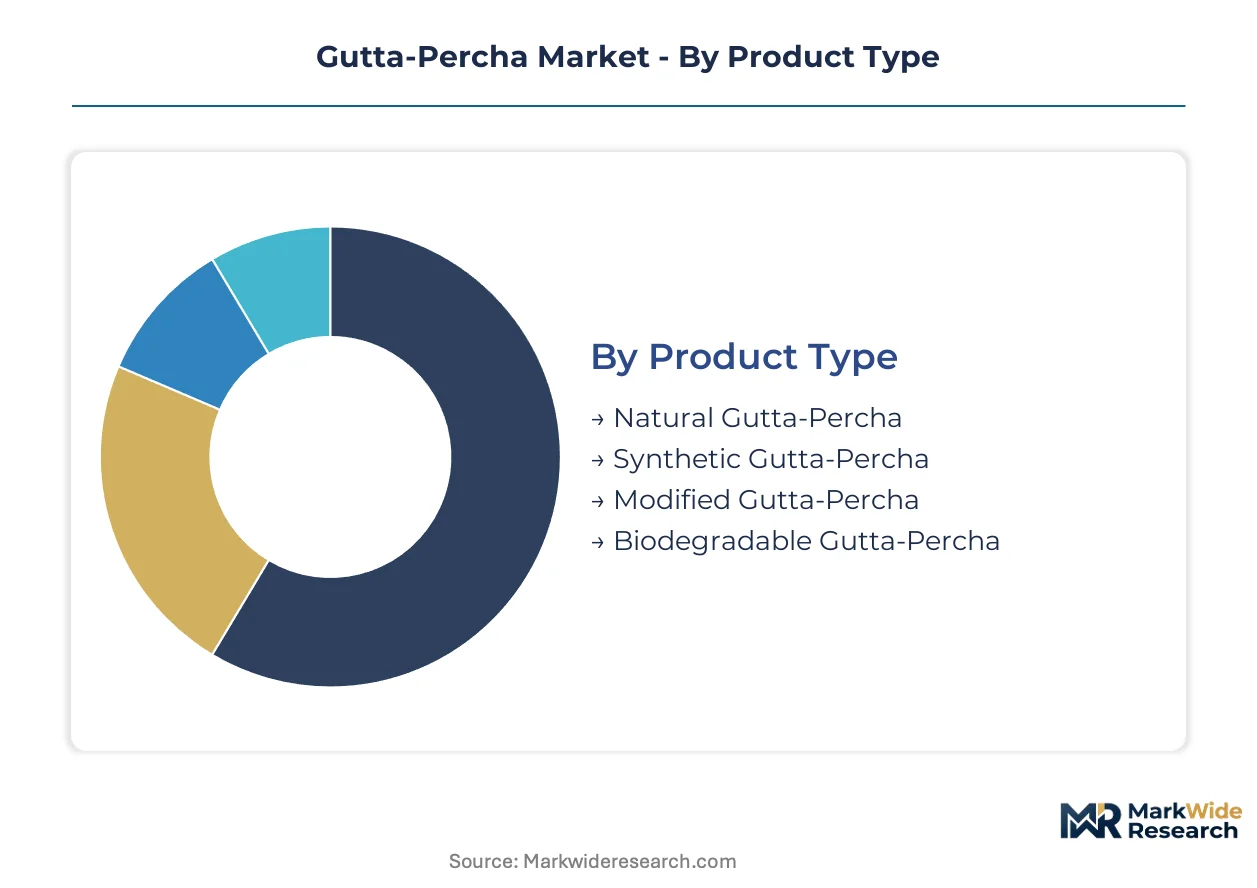
Endodontic supply chains require distinct service models across formulation categories, with biodegradable variants demanding technical consultation while natural grades compete on transactional efficiency. Segmentation reveals how formulation chemistry, procedural application, and procurement channel preferences reshape margin structures and competitive positioning.
Product Type:
After-sales service intensity varies sharply across formulation categories, with synthetic and biodegradable grades requiring formulation support and certification documentation that natural grades rarely demand.
- Natural Gutta-Percha:Derived from Palaquium gutta latex, this trans-polyisoprene formulation exhibits reversible thermoplastic softening at 65–70°C that enables warm vertical compaction techniques. Demand concentrates in German dental clinics where clinician familiarity with legacy obturation protocols sustains procurement volumes despite batch variability constraints.
- Synthetic Gutta-Percha:Manufactured through controlled polymerization of isoprene monomers, this category delivers dimensional tolerances within ISO 6876 specifications with minimal lot-to-lot deviation. Procurement is shifting toward large United States dental service organizations that specify synthetic grades to standardize procedural outcomes across multi-site practices.
- Modified Gutta-Percha:Incorporates zinc oxide, wax plasticizers, and resin additives to enhance flow characteristics during thermoplastic obturation.
- Biodegradable Gutta-Percha:Emerging formulations designed for compostable degradation under medical waste stream regulations in France and Germany.
By volume, natural gutta-percha leads. By growth pace, biodegradable formulations are expanding most quickly.
Application:
Application segmentation tracks how thermoplastic properties and electrical insulation characteristics match distinct performance requirements across end-use sectors.
- Dental Procedures:Root canal obturation exploits reversible softening for warm vertical compaction and continuous wave techniques. Demand concentrates in specialized endodontic clinics across Germany, France, and the United Kingdom where thermoplastic methods displace cold lateral compaction protocols.
- Cable Insulation:High electrical resistance and low thermal conductivity suit submarine power transmission and telecommunications cabling. Procurement is shifting toward synthetic formulations that satisfy REACH additive restrictions for European infrastructure projects.
- Hydraulic Seals:Resilience under pressure and chemical inertness serve industrial fluid systems.
- Medical Devices:Biocompatibility profile supports specialized catheter components and surgical instrument coatings.
Dental applications dominate current volume. Cable insulation is climbing the fastest as offshore wind infrastructure expands.
End User:
End user categories reflect divergent procurement sophistication, with healthcare institutions demanding certification documentation that construction buyers rarely require.
- Dental Clinics:Independent practices and dental service organizations procure pre-sterilized obturation points with ISO 6876 compliance certificates. Demand concentrates in German Baden-Württemberg manufacturing clusters where VDW GmbH and Coltene Whaledent anchor specialized supply relationships.
- Healthcare Institutions:Hospital systems and academic medical centers specify synthetic formulations with complete toxicological dossiers for REACH compliance.
- Construction Industry:Infrastructure contractors source cable insulation grades for power transmission projects.
- Electronics Manufacturers:Telecommunications and automotive wiring harness producers procure insulation compounds.
Dental clinics lead by procurement volume. Healthcare institutions are gaining share fastest as hospital consolidation accelerates.
Distribution Channel:
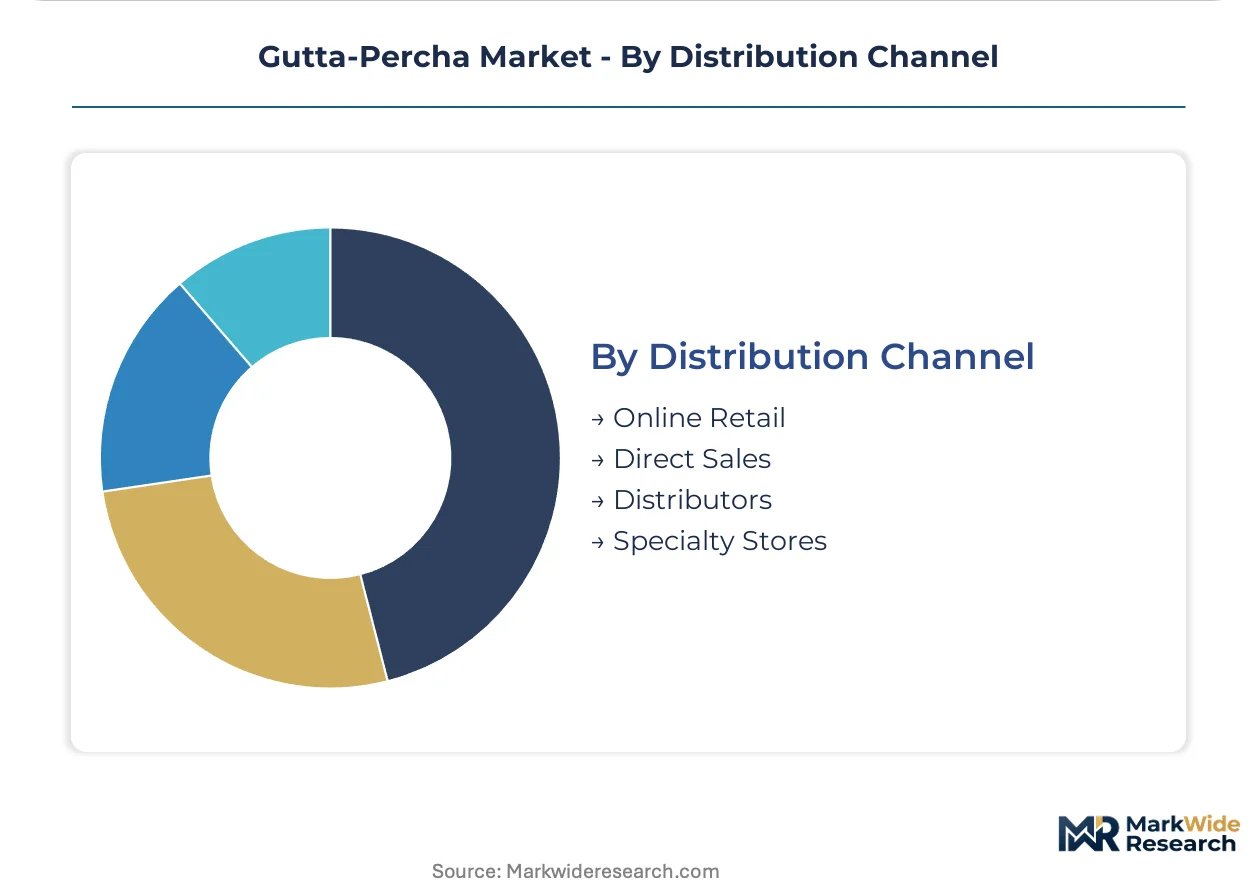
Channel segmentation reveals how sterilization requirements and technical consultation needs reshape logistics economics across customer tiers.
- Direct Sales:Manufacturers maintain field technical service for large dental service organizations and hospital systems requiring formulation customization. Procurement is shifting toward direct-to-clinic platforms that bypass traditional dealer networks in the United States and United Kingdom.
- Distributors:Specialized dental and medical supply intermediaries bundle obturation points with complementary endodontic instruments. Demand concentrates in German distributor networks serving Baden-Württemberg precision manufacturing clusters.
- Online Retail:E-commerce platforms serve cost-sensitive independent dental practices with standard-grade natural formulations.
- Specialty Stores:Regional dental supply depots provide same-day availability for emergency procurement.
Distributors lead by transaction volume. Direct sales are expanding most quickly as large accounts consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian Palaquium gutta plantations supply raw latex to German precision extrusion facilities, creating a trade corridor that underpins endodontic point manufacturing across European dental markets.
United States
FDA 510(k) clearance pathways govern dental device market entry, with large dental service organizations consolidating procurement around standardized synthetic formulations. Warm vertical compaction techniques spread through specialized endodontic clinics in Texas and California. Kerr Dental anchors supply relationships with multi-site practice networks seeking batch-to-batch consistency.
Germany
EMA MDR compliance mandates drive clinician migration toward certified biocompatible obturation materials, accelerating synthetic gutta-percha adoption. REACH chemical registrations force reformulation of zinc oxide and resin additives used in compounding. Baden-Württemberg manufacturing clusters host VDW GmbH and Coltene Whaledent precision extrusion operations serving ISO 6876 specifications.
France
ANSM biocompatibility requirements tighten scrutiny on persistent synthetic polymers in medical waste streams, creating demand for biodegradable formulations. Pre-sterilized single-use obturation points displace bulk packaging in Paris and Lyon dental clinics. Specialized distributors bundle sterile points with endodontic instruments to reduce cross-contamination protocols.
Japan
PMDA dental material approvals emphasize thermoplastic performance standards for warm obturation techniques. METI industrial policy supports polymer engineering talent development for modified gutta-percha formulations. Osaka-based manufacturing maintains precision extrusion capabilities serving domestic endodontic specialists and export markets.
China
NMPA medical device registration requirements shape import conditions for foreign-manufactured obturation points. Domestic cable insulation demand expands with offshore wind infrastructure projects along coastal provinces. Synthetic formulation development accelerates as manufacturers seek alternatives to natural latex supply volatility from Southeast Asian sources.
Gutta-Percha Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. German and Swiss industrial clusters concentrate polymer engineering expertise for thermoplastic dental applications. Three archetypes dominate: precision extrusion specialists with ISO certification depth, synthetic compounding innovators reducing batch variability, and integrated dental equipment manufacturers bundling obturation materials with delivery systems. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure raw material access and distributor relationships.
Among German precision manufacturers, VDW GmbH and Coltene Whaledent exemplify the extrusion-specialist archetype anchored in Baden-Württemberg industrial infrastructure. Kerr Dental occupies a position representing synthetic formulation innovation within North American supply chains. These three companies illustrate how geographic clustering around regulatory expertise and polymer engineering talent creates defensible market positions.
| Leading Market Players |
|---|
| Ultradent Products |
| VDW GmbH |
| Dentsply Sirona |
| META BIOMED |
| FKG Dentaire SA |
| Coltene Whaledent |
| DiaDent Group International |
| Ivoclar Vivadent |
| Kerr Dental |
| Others |
Cost & Logistics Intelligence
Undercapacity in Southeast Asian latex processing facilities is compressing raw material availability and amplifying pricing power for integrated German manufacturers who control precision extrusion capacity. This utilization asymmetry rewards backward-linked players while forcing spot-market buyers into premium procurement positions.
Pricing Analysis
The natural-to-synthetic formulation pricing gap widens as batch consistency premiums escalate, with unmodified Palaquium-derived grades trading at substantial discounts to ISO 6876-certified synthetic compounds. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with REACH-compliant formulations commanding measurable premiums over legacy grades. Cost compression in natural gutta-percha is intensifying because harvest volatility forces processors into costly blending protocols. Large dental service organizations exhibit lowest price sensitivity due to standardization mandates, while independent clinics in cost-sensitive markets drive aggressive spot-market negotiation.
Supply Chain Analysis
Upstream Palaquium gutta latex harvests concentrate in Indonesian and Malaysian plantations, with secondary sourcing from Thai smallholder networks. Formulation chemistry rests on zinc oxide compounding, resin additives, and controlled isoprene polymerization feedstocks. Single-source vulnerability in Baden-Württemberg precision extrusion equipment creates bottleneck exposure for manufacturers seeking ISO certification. Distribution runs through specialized dental supply intermediaries who bundle sterile obturation points with complementary endodontic instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gutta-percha market sits in early-cycle expansion as biodegradable certification schemes unlock premium positioning in European medical waste streams. Warm obturation technique penetration in specialized clinics accelerates material throughput per procedure.
For Market Incumbents: Entrench ISO 6876 certification depth as a competitive moat against bioceramic sealer substitution threats. Deepen backward integration into controlled isoprene polymerization to neutralize natural latex supply volatility. Anchor capacity expansion in Baden-Württemberg clusters to exploit polymer engineering talent scarcity. For New Entrants and Emerging Players: Biodegradable formulation white space in French and German dental clinics represents the most penetrable entry point for differentiated positioning. Pre-sterilized single-use obturation points for mid-tier United States dental service organizations offer secondary beachhead opportunity. Direct-to-clinic platform deployment bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic compounding facilities as REACH registration requirements escalate fixed compliance costs. Five-to-ten year viability favors precision extrusion specialists with certification depth over commodity natural latex processors. Monitor biodegradable certification scheme adoption rates in German hospital systems as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Feedstocks | Synthetic formulation players secure supply certainty against Palaquium harvest volatility. |
| Biodegradable Certification Pathway | Early compliance with emerging French and German medical waste regulations captures premium positioning. |
| Precision Extrusion Capacity Expansion | Baden-Württemberg manufacturing clusters deepen ISO 6876 compliance capabilities. |
| Direct-to-Clinic Platform Launch | Bypass traditional dental distributor networks to capture margin and preference data. |
| Warm Obturation Device Convergence | Bundled equipment-material offerings lock in procedural standardization across dental service organizations. |
Research Approach
Operator-level perspectives from endodontic specialists, dental procurement managers, polymer formulation chemists, and specialized distributor principals anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EMA MDR registration databases, ISO standards documentation, and customs trade records. Bottom-up procedure volume estimates and top-down dental market sizing were triangulated to constrain forecast variance.
Scenario-bracketing around regulatory acceleration and biodegradable adoption curves bounded the projection envelope across the analysis window. Segmentation modeling incorporated formulation chemistry, procedural application, procurement channel, and geographic regulatory cluster dimensions. CAGRs were derived from trend extrapolation of warm obturation technique diffusion and synthetic formulation substitution rates.
Stress conditions across Palaquium gutta harvest yields, REACH registration timelines, and bioceramic sealer competitive intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinician technique migration and certification scheme adoption. Cross-checking against hospital procurement database trends and dental service organization contract disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Polyimide Films Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Special Graphite Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Asia-Pacific Green Sic Market