
 Global Shape Memory Alloys Market | 2026-2036
Global Shape Memory Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shape Memory Alloys Market Foresight
ASTM F2063 qualification for surgical implant-grade nitinol is collapsing the supplier base to a handful of certified melt shops. Furukawa Electric leverages its integrated titanium sponge-to-wire capability to dominate Japanese medical supply chains. Johnson Matthey sustains European market presence through its specialized vacuum arc remelting capacity in the United Kingdom. Dynalloy competes aggressively on copper-based alloy formulations for industrial actuation applications.
Shape memory alloys are metallic materials that recover a predetermined shape upon heating above a characteristic transformation temperature, typically engineered around specific austenite finish points between 20°C and 110°C depending on nickel titanium composition ratios. Their primary commercial purpose centers on solid-state actuation, superelastic energy absorption, and constrained recovery force generation across medical, aerospace, and automation systems. Nickel titanium alloys command the dominant margin pool due to biocompatibility premiums and processing complexity barriers, while copper-based variants occupy cost-sensitive industrial niches with lower transformation temperature precision. Wire form factors lead volume shipments through catheter and guidewire demand, though tube segments are gaining fastest in structural stent applications.
FDA enforces stringent device master file requirements for nitinol implants under 21 CFR Part 820 quality system regulations, effectively filtering out uncertified raw material suppliers. EMA's MDR framework extends this scrutiny through mandatory notified body involvement for all implantable shape memory devices sold in Europe. Japan's PMDA maintains similarly rigorous material lot tracking standards that favor established domestic producers. Stakeholders must monitor evolving ISO 5832-11 revisions for nickel titanium surgical alloy specifications as these standards increasingly dictate procurement eligibility across major medical device markets.
Market Dynamics
ASTM F2063 qualification requirements for surgical implant-grade nitinol are collapsing the certified supplier base to a handful of specialized melt shops, creating acute supply concentration and pricing power asymmetries across medical device supply chains.
Growth Catalysts
- EU Medical Device Regulation:Tightened material traceability mandates for implantable components are forcing device manufacturers toward pre-qualified nitinol suppliers, accelerating consolidation around certified production networks in Germany and the United Kingdom.
- Minimally invasive surgery expansion:Cardiovascular catheter and structural stent applications are pulling wire and tube form factors through precision engineering clusters around Stuttgart and Munich.
- Copper-based alloy innovation:Industrial automation systems are adopting lower-cost shape memory actuators for thermal management and clamping mechanisms in manufacturing equipment.
Market Restraints
- Titanium sponge volatility:Raw material input costs for nickel titanium alloys fluctuate with sponge supply concentrated in a limited number of primary producers.
- Vacuum arc remelting scarcity:Specialized VAR capacity for medical-grade nitinol concentrates in Japan, the United Kingdom, and select United States facilities, creating geographic supply risk.
- Polymer actuator substitution:Electroactive polymers and hydraulic micro-actuators are capturing cost-sensitive industrial positioning applications below 50°C transformation thresholds.
Strategic Opportunities
- South Korean medical device manufacturing:MFDS regulatory alignment with ISO 5832-11 is opening procurement eligibility for certified nitinol suppliers serving the expanding domestic stent production base.
- Aerospace morphing structures:Wing and engine nozzle applications are converging with additive manufacturing to enable complex geometries previously impossible through conventional wire drawing.
- Japan PMDA lot tracking standards:Domestic producers with integrated titanium sponge-to-wire capability are capturing premium positioning through compliance-driven supply security guarantees.
Industry Challenges
- Vacuum metallurgy expertise scarcity:Qualified engineers for controlled atmosphere melting and thermomechanical processing of nitinol are concentrated among retiring cohorts at established producers.
- Device master file timeline compression:FDA 21 CFR Part 820 compliance for new implant designs requires 18-36 month certification cycles that strain working capital for mid-scale device developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shape Memory Alloys Market |
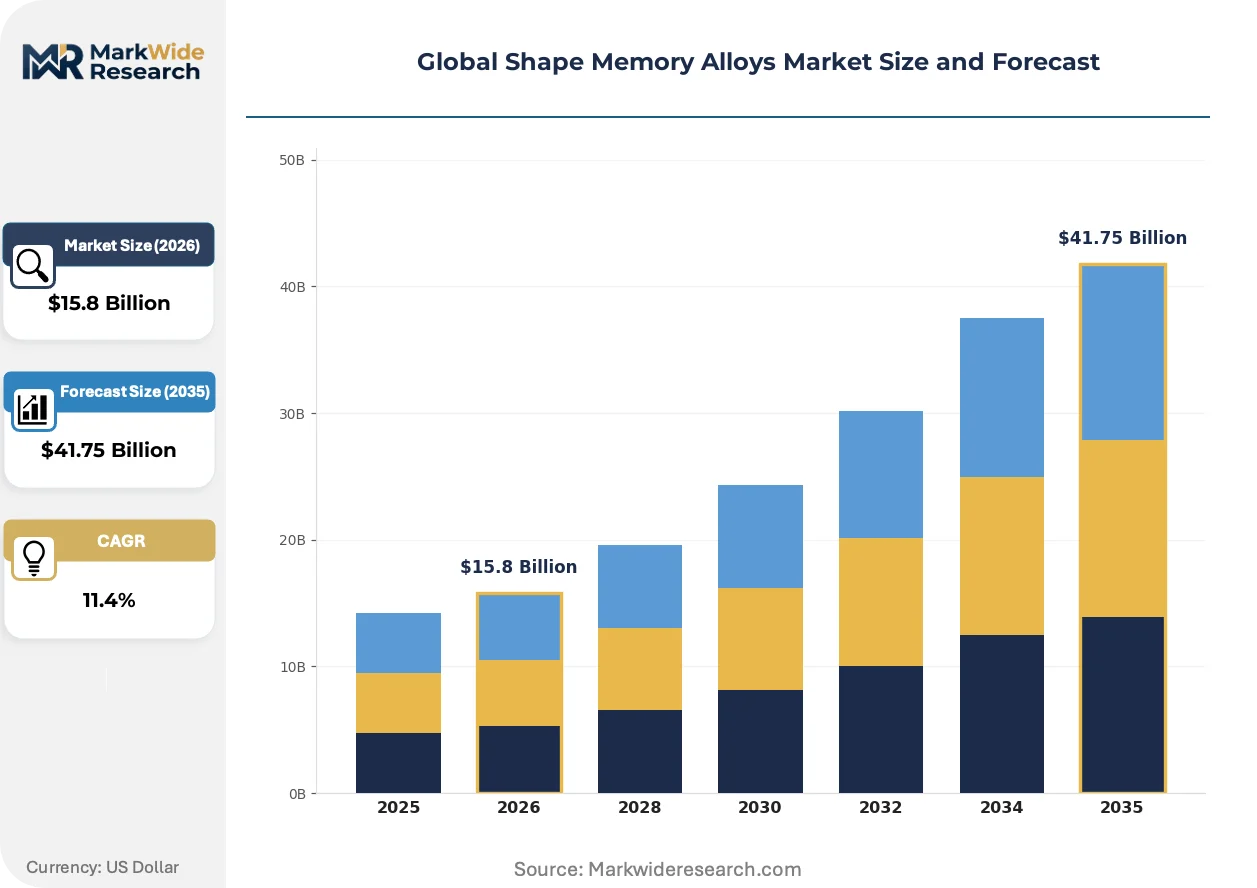
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Alloy Type: Nickel Titanium, Copper Zinc Aluminum, Copper Aluminum Nickel, Iron Manganese Silicon Application Sector: Orthodontics, Aerospace Components, Robotics, Safety Devices End User Industry: Medical Device Manufacturers, Aerospace Engineers, Automation Firms, Protective Equipment Makers Form Factor: Wire, Sheet, Tube, Foil |
| Companies Covered | Furukawa Electric, Dynalloy, Johnson Matthey, Fort Wayne Metals, Nippon Seisen, ATI, Nippon Steel Corporation, Memry Corporation, SAES Getters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shape Memory Alloys Market Shifts & Advancements
Additive manufacturing of complex nitinol lattice structures is dissolving traditional form factor constraints, enabling patient-specific orthopedic implants and next-generation cardiovascular devices that wire drawing cannot produce.
Laser powder bed fusion of nickel titanium is supplanting conventional wire drawing for structural stent geometries requiring variable porosity along the device length. Medtronic and Boston Scientific procurement teams are qualifying additively manufactured stent platforms for peripheral vascular applications. This fabrication shift is compressing lead times for prototype iterations while elevating surface finish and fatigue performance requirements beyond current ASTM specifications.
EMA's MDR framework extension through mandatory notified body involvement for all implantable shape memory devices is elevating documentation burdens for European market entry. Small and mid-scale device manufacturers are outsourcing regulatory affairs functions to specialized consultancies rather than building internal competency. Tube form factor suppliers with existing CE-marked device master files are capturing disproportionate share of new product development partnerships.
Japanese medical device OEMs are consolidating raw material procurement through multi-year offtake agreements with domestic integrated producers rather than spot market purchasing. This contractual shift locks in volume commitments and quality assurance protocols that exclude non-domestic suppliers from premium tier supply chains. The behavior is most visible in Tokyo and Osaka metropolitan manufacturing corridors serving cardiovascular and orthodontic device export markets.
Global Shape Memory Alloys Market Segmentation
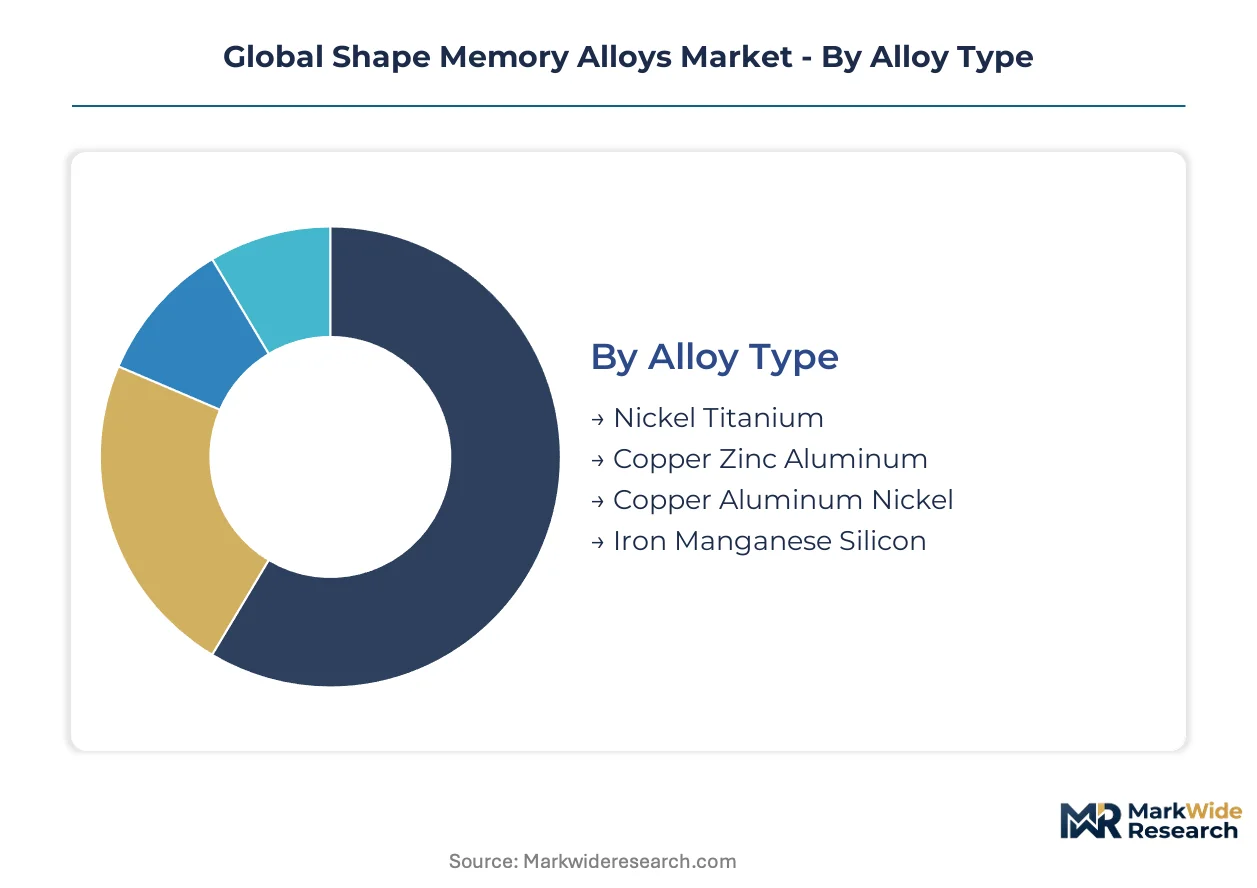
Segmentation in shape memory alloys reveals how technical specifications and regulatory requirements fragment procurement across medical, aerospace, and industrial channels. Each alloy type and form factor carries distinct certification burdens that filter supplier eligibility differently.
Alloy Type:
Nickel titanium dominates export-led medical supply chains through biocompatibility premiums, while copper-based variants serve cost-sensitive domestic industrial automation markets.
- Nickel Titanium:Engineered around precise austenite finish points between 20°C and 110°C through controlled nickel-to-titanium ratios. Cardiovascular stent and guidewire demand in Germany's Stuttgart precision clusters pulls premium-grade material through certified melt shops.
- Copper Zinc Aluminum:Lower transformation temperature precision suits thermal actuation and clamping mechanisms. Industrial equipment OEMs in Japan's Osaka manufacturing corridor specify this grade for cost-constrained automation systems.
- Copper Aluminum Nickel:Offers intermediate performance between nitinol and copper-zinc-aluminum formulations. Found in safety-critical industrial applications requiring repeatable cycling behavior.
- Iron Manganese Silicon:Emerging alternative for heavy-duty actuation where biocompatibility is irrelevant. Magnetic properties enable hybrid electromechanical systems in robotics applications.
Nickel titanium commands the established base. The steepest expansion runs through copper-based formulations capturing industrial automation share.
Application Sector:
Medical applications concentrate procurement through regulated device master files, while aerospace and robotics segments emphasize performance-to-weight optimization.
- Orthodontics:Archwire and bracket systems leverage superelastic energy absorption for constant low-force tooth movement. FDA 21 CFR Part 820 compliance filters raw material sourcing to ASTM F2063-certified suppliers serving North American dental device OEMs.
- Aerospace Components:Morphing wing structures and engine nozzle actuators demand fatigue-resistant nitinol with precise transformation windows. Additive manufacturing qualification at European tier-one suppliers is dissolving traditional wire-drawing constraints.
- Robotics:Solid-state actuation replaces motor-and-gearbox assemblies in compact manipulation systems. Thermal management challenges limit deployment to controlled-environment manufacturing cells.
- Safety Devices:Fire suppression actuators and thermal release mechanisms exploit constrained recovery force generation. Copper-based alloys dominate this price-sensitive segment.
Orthodontics anchors volume through established regulatory pathways. Aerospace morphing structures are climbing the fastest as additive manufacturing matures.
End User Industry:
Medical device manufacturers consolidate procurement through multi-year offtake agreements, while automation firms operate on spot-market flexibility.
- Medical Device Manufacturers:Implantable component requirements under EU MDR and Japan PMDA lot-tracking standards favor integrated titanium sponge-to-wire suppliers with captive VAR capacity.
- Aerospace Engineers:Prime contractors specify material lots with full chemical and mechanical traceability for flight-critical applications. Qualification cycles extend 18-36 months.
- Automation Firms:Industrial actuation demand prioritizes cost-per-cycle economics over transformation temperature precision. Copper-based alloys capture this segment.
- Protective Equipment Makers:Thermal response applications in fire safety and industrial shutdown systems specify lower-grade shape memory alloys with minimal processing overhead.
Medical device manufacturers concentrate the premium tier. Automation firms are gaining share fastest as factory robotics deployment accelerates.
Form Factor:
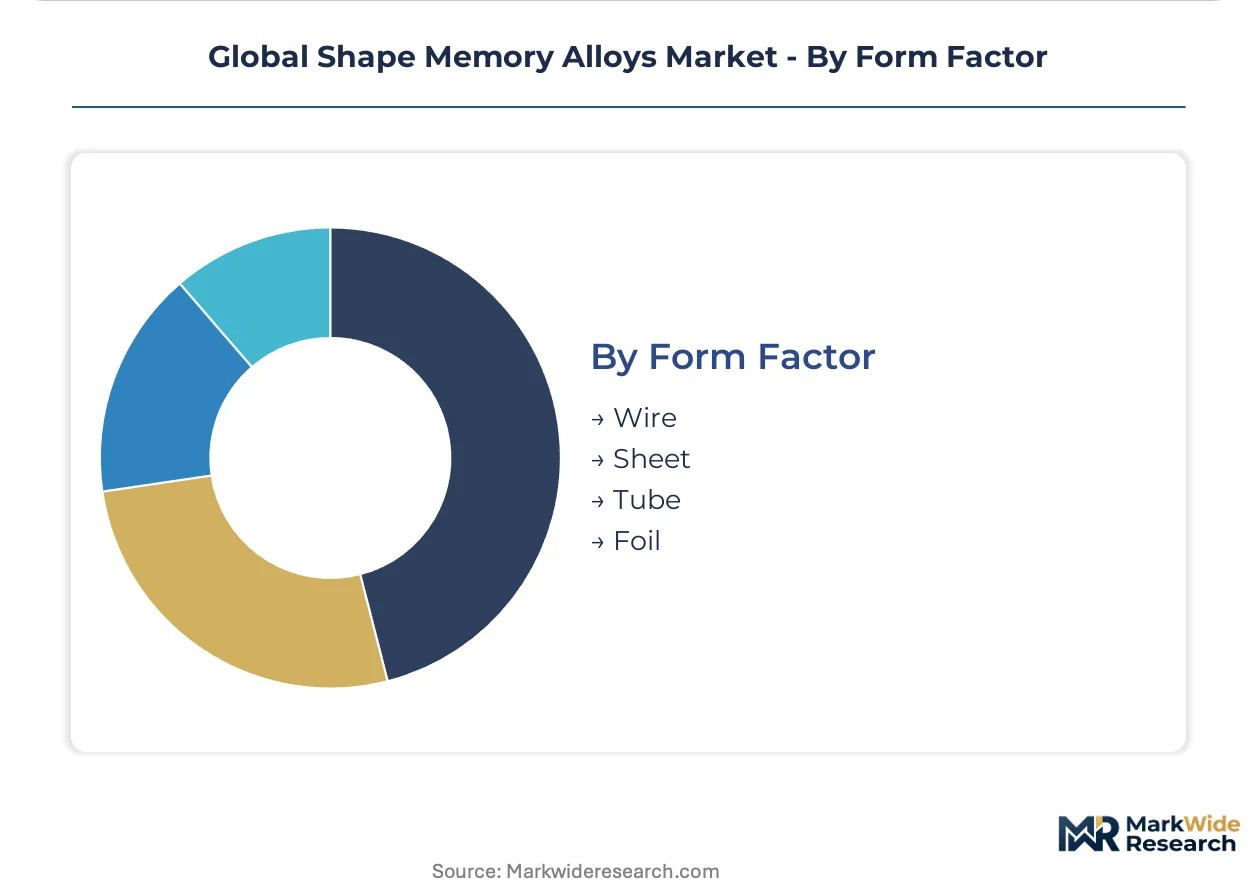
Wire and tube configurations split between export-driven cardiovascular device supply chains and domestic industrial actuator markets.
- Wire:Dominant shipment volume through catheter and guidewire demand. Precision drawing to sub-millimeter diameters requires specialized thermomechanical processing expertise concentrated in Japan, the United Kingdom, and Germany.
- Tube:Structural stent platforms and orthopedic implants require variable wall thickness along device length. Laser powder bed fusion is supplanting conventional drawing for complex geometries.
- Sheet:Limited deployment in thermal actuation panels and morphing aerospace surfaces. Forming challenges restrict adoption relative to wire and tube.
- Foil:Micro-actuation and MEMS integration applications. Thickness control below 50 micrometers demands specialized rolling mills.
Wire commands the established base. Tube is climbing the fastest as stent geometries complexify beyond conventional fabrication limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device OEMs in Germany, Japan, and the United States concentrate procurement through certified nitinol suppliers with captive vacuum arc remelting capacity. Aerospace prime contractors in France and the United Kingdom are qualifying additive manufacturing platforms for morphing structures.
United States
FDA 21 CFR Part 820 quality system regulations filter raw material sourcing to ASTM F2063-certified melt shops. Device master file timelines extend 18-36 months for new implant designs. Fort Wayne, Indiana hosts precision wire drawing operations serving cardiovascular catheter manufacturers.
Germany
EU Medical Device Regulation mandates tighten material traceability for implantable components. Stuttgart and Munich precision engineering clusters pull premium-grade nitinol through certified production networks. Notified body involvement elevates documentation burdens for market entry.
Japan
PMDA lot-tracking standards favor integrated titanium sponge-to-wire suppliers with domestic VAR capacity. Tokyo and Osaka metropolitan manufacturing corridors serve cardiovascular and orthodontic device export markets. Multi-year offtake agreements lock in volume commitments and quality protocols.
United Kingdom
Specialized vacuum arc remelting capacity sustains European market presence for medical-grade nitinol. EMA MDR framework extension requires mandatory notified body involvement for all implantable shape memory devices. Regulatory affairs functions are migrating to specialized consultancies.
South Korea
MFDS regulatory alignment with ISO 5832-11 opens procurement eligibility for certified nitinol suppliers. Domestic stent production base is expanding manufacturing capacity for cardiovascular applications. Seoul-based device OEMs are consolidating supplier qualification programs.
Global Shape Memory Alloys Market Competitive Landscape
Player mix skews toward integrated metallurgical specialists with captive titanium sponge-to-wire capability and certified medical-grade processing infrastructure. The supplier base concentrates around a handful of qualified melt shops with ASTM F2063 qualification. Two strategic archetypes dominate: vertically integrated Japanese and European producers with full metallurgical control, and North American precision fabricators with specialized thermomechanical processing expertise. Competitive moves center on multi-year offtake agreements locking in volume commitments, and additive manufacturing qualification for complex stent geometries beyond conventional wire drawing limits.
Within the integrated metallurgical tier, Furukawa Electric exemplifies the Japanese model of captive titanium sponge supply and vacuum arc remelting capacity. Johnson Matthey occupies a position representing European vacuum metallurgy specialization with United Kingdom-based VAR operations. Among North American precision fabricators, Dynalloy anchors the copper-based alloy segment for industrial actuation applications. Fort Wayne Metals sits within the medical-grade wire drawing specialization serving FDA-regulated device supply chains. These three names represent the archetype spectrum: integrated primary producer, regional metallurgical specialist, and application-specific fabricator.
| Leading Market Players |
|---|
| Furukawa Electric |
| Dynalloy |
| Johnson Matthey |
| Fort Wayne Metals |
| Nippon Seisen |
| ATI |
| Nippon Steel Corporation |
| Memry Corporation |
| SAES Getters |
| Others |
Supply & Pricing Matrix
Polymer actuator substitution for sub-50°C thermal applications is redrawing procurement geography toward East Asian resin compounders while compressing margin structures for copper-based shape memory alloy producers serving cost-sensitive industrial automation tiers.
Pricing Analysis
Cost-plus contracts indexed to titanium sponge benchmarks dominate nickel titanium procurement, with medical-grade nitinol carrying ASTM F2063 certification premiums against industrial copper-aluminum-nickel grades. Price differentiation rests on vacuum arc remelting capacity scarcity and lot-traceability depth required under Japan PMDA and EU MDR frameworks. Pricing pressure stems from electroactive polymer incursion into clamping and thermal management niches below 50°C transformation thresholds. Automation firms exhibit highest price sensitivity, while cardiovascular device OEMs absorb premiums for biocompatibility assurance and regulatory documentation packages.
Supply Chain Analysis
Strait of Hormuz titanium concentrate transit underwrites sponge supply security for Japanese and European integrated producers, with chokepoint exposure elevating inventory carrying costs across certified melt shops. Primary titanium sponge production concentrates in China, Russia, and Japan, while vacuum arc remelting capacity clusters in Japan, the United Kingdom, and select United States facilities. Supply chain risk centers on single-source dependency for medical-grade VAR processing and geopolitical friction affecting sponge feedstock flows. Distribution runs through precision wire drawing specialists in Fort Wayne, Stuttgart, and Tokyo serving catheter and guidewire OEMs with qualified device master files.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroactive polymer and hydraulic micro-actuator substitution threatens industrial positioning applications, compelling incumbents to fortify medical-grade certification moats and accelerate additive manufacturing qualification for geometries polymers cannot replicate.
For Market Incumbents: Shield ASTM F2063-certified capacity through captive titanium sponge sourcing and multi-year offtake agreements locking in cardiovascular OEM volume. Deepen backward integration into vacuum arc remelting to offset VAR engineer scarcity and geographic concentration risk. Prioritize laser powder bed fusion qualification for patient-specific orthopedic implants beyond wire-drawing limits. For New Entrants and Emerging Players: Anchor in South Korean stent manufacturing corridors where MFDS regulatory alignment with ISO 5832-11 opens procurement eligibility without incumbent relationship density. Target copper-based alloy formulations for factory robotics thermal actuation where cost-per-cycle economics favor new suppliers. Pursue regulatory affairs outsourcing partnerships to compress FDA 21 CFR Part 820 compliance timelines. For Investors and Strategic Acquirers: EU MDR notified body mandate reshapes the acquisition landscape toward tube-form factor suppliers with existing CE-marked device master files and documented lot-traceability protocols. Five-to-ten year viability favors integrated metallurgical specialists with captive sponge-to-wire capability over precision fabricators exposed to raw material volatility. Monitor ISO 5832-11 revision trajectory as signal for procurement eligibility shifts across major medical device markets.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F2063 Certification Investment | Collapses qualified supplier base to certified melt shops, concentrating pricing power among Japanese and European integrated producers. |
| Additive Manufacturing Qualification | Enables complex lattice geometries for stent and orthopedic applications beyond conventional wire drawing constraints. |
| Multi-Year Offtake Agreements | Locks in volume commitments with Tokyo and Osaka cardiovascular OEMs, excluding spot-market competitors from premium tiers. |
| Regulatory Affairs Outsourcing | Compresses EMA MDR documentation burdens for mid-scale device developers entering European implantable markets. |
| Copper-Based Alloy Formulation | Captures industrial automation share where transformation temperature precision requirements relax below medical-grade thresholds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR notified body registrations, and titanium sponge trade flow data. Interviews with vacuum metallurgy engineers, cardiovascular device procurement directors, and precision wire drawing operators informed supply chain concentration assessments. Secondary validation drew from ASTM F2063 certification registries, Japan PMDA lot-tracking disclosure summaries, and German precision engineering cluster employment data. Bottom-up alloy consumption estimates triangulated against top-down medical device production forecasts.
Segmentation dimensions modeled include alloy type, form factor, application sector, and end-user industry across the projection horizon. Value outputs reflect price realization by certification tier and captive versus merchant VAR sourcing structure. Volume trajectories incorporate catheter and guidewire demand from Stuttgart and Munich precision clusters, structural stent platform adoption, and industrial automation actuator deployment. CAGRs derive from regression against historical titanium sponge price elasticity and medical device OEM capital expenditure cycles.
Material uncertainties — titanium sponge supply disruption, ISO 5832-11 specification revision, and polymer actuator performance advancement — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and qualified metallurgical engineer availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Cermet Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Tungsten Titanium Carbide Market