
 Global Shape Memory Materials Market | 2026-2036
Global Shape Memory Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shape Memory Materials Market Foresight
Aftermarket service revenue for shape memory alloy component refurbishment is rewriting profitability expectations across the supply base. BASF SE leverages its polymer science heritage to anchor positions in shape memory polymer formulations for automotive and consumer applications. SAES Getters specializes in high-purity metal alloy production, sustaining margins through backward integration into vacuum metallurgy processes. Nippon Steel Corporation dominates bulk nitinol wire output, controlling access to aerospace-qualified material streams in Asia.
Shape memory materials are metallic alloys and polymers that recover predetermined shapes upon exposure to thermal, magnetic, or electrical stimuli, typically exhibiting transformation temperatures between −100°C and 100°C depending on composition; nitinol alloys containing near-equiatomic nickel and titanium dominate medical applications due to superelasticity and biocompatibility. Nickel titanium alloys lead revenue contribution due to entrenched surgical device demand, while shape memory polymer technology represents the fastest-expanding segment as injection-moldable formats displace metal in consumer electronics housings. Wire and tube forms capture disproportionate margin pools because precision drawing and surface finishing require captive process knowledge that commodity producers cannot replicate.
FDA quality system regulation and EU MDR conformity requirements are elevating documentation burdens for nitinol suppliers seeking medical device market access, while REACH chemical registration in Europe constrains novel copper-aluminum-nickel formulations. Japan's PMDA and METI coordinate standards for robotic actuator materials, creating divergent certification pathways that fragment product development timelines. Stakeholders must monitor regulatory harmonization progress between FDA and PMDA pilot programs to anticipate whether unified testing protocols will consolidate supplier qualification costs or perpetuate regional specialization.
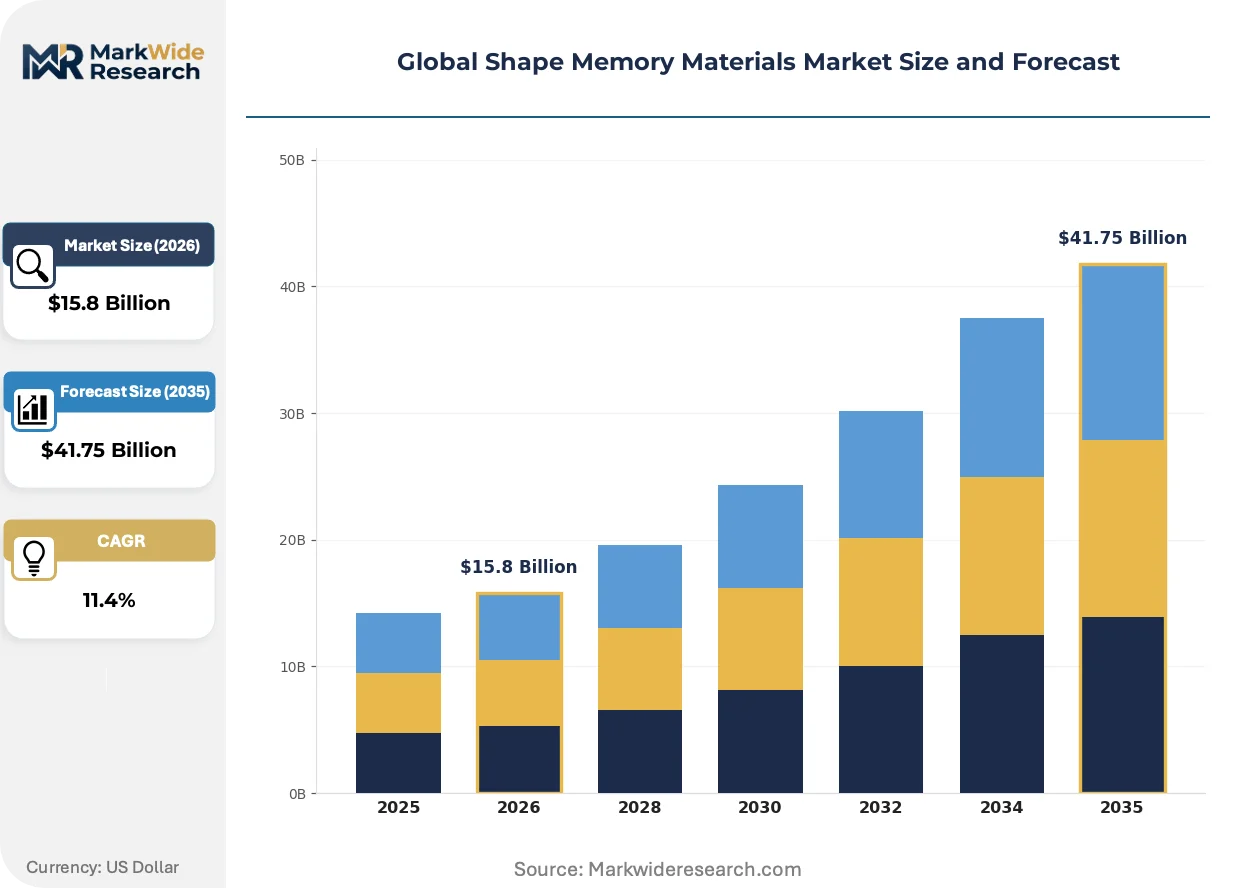
Market Dynamics
Medical device procurement clusters in Massachusetts, Baden-Württemberg, and Osaka Prefecture are consolidating purchasing power around qualified nitinol suppliers, compressing margins for non-specialized producers while rewarding backward-integrated alloy manufacturers with captive vacuum metallurgy capabilities.
Growth Catalysts
- EU MDR traceability mandates:Tightened material documentation requirements under the Medical Device Regulation are filtering out commodity suppliers and concentrating procurement among certified nitinol producers with batch-level pedigree systems.
- Minimally invasive surgical tool expansion:United States and German medical device manufacturers are expanding nickel-titanium alloy procurement for catheter-based and laparoscopic instruments requiring superelastic performance.
- Injection-moldable shape memory polymers:Displace metal in consumer electronics housings as BASF SE and polymer compounders scale thermoplastic polyurethane formulations with programmable transformation temperatures.
Market Restraints
- High-purity nickel price volatility:Vacuum arc remelting feedstock costs fluctuate with LME nickel pricing, squeezing margin pools for wire and tube producers without long-term offtake agreements.
- Baden-Württemberg supply concentration:Precision drawing and surface finishing capabilities cluster with SAES Getters and specialized German metallurgists, creating bottleneck risk for aerospace-qualified material streams.
- Biocompatibility certification timelines:FDA quality system regulation and PMDA coordination requirements extend product qualification cycles to 18-24 months for novel copper-aluminum-nickel formulations.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory alignment with ISO standards and PLI scheme incentives attract nitinol component fabrication for export to Middle Eastern and African markets.
- Robotic actuator materials in Japan:METI and PMDA coordinated standards for surgical robotics create certified demand pathways for high-cycle fatigue nitinol wire in precision drive systems.
- Additive manufacturing convergence:Laser powder bed fusion of pre-alloyed nitinol powder enables patient-specific orthopedic implants with topology-optimized compliance gradients.
Industry Challenges
- Vacuum metallurgy talent scarcity:Skilled technicians capable of electron beam melting and plasma arc melting of reactive metals command premium compensation in Massachusetts and Osaka Prefecture clusters.
- REACH registration burdens:ECHA chemical substance registration for novel ternary alloys requires toxicological dossiers that delay European market entry by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shape Memory Materials Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Nickel Titanium, Copper Aluminum Nickel, Iron Manganese Silicon, Copper Zinc Aluminum, Titanium Nickel Copper Form: Wire, Sheet, Foil, Powder, Film, Tube Technology: Thermo-Mechanical, Magnetic Shape Memory, Hydro-Actuated, Electroactive, Shape Memory Polymer Application: Aerospace Components, Robotics Actuators, Medical Devices, Consumer Electronics, Civil Engineering, Eyewear Frames |
| Companies Covered | BASF SE, Covestro AG, ATI, Nippon Steel Corporation, SAES Getters, SMP Technologies Inc, Johnson Matthey, Furukawa Electric Co., Ltd., Fort Wayne Metals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shape Memory Materials Market Shifts & Advancements
Active materials engineering is collapsing traditional boundaries between metallic and polymer shape recovery systems, with thermal programming capabilities now spanning −100°C to 100°C transformation windows across alloy and polymer platforms.
Additive manufacturing of pre-alloyed nitinol powder is collapsing lead times for patient-specific medical implants from months to weeks. Orthopedic device manufacturers in Massachusetts are adopting laser powder bed fusion for spinal spacer cages with programmed stiffness gradients. The technology is collapsing the distinction between standard catalog components and custom-engineered solutions.
Japan's PMDA and METI coordination on robotic actuator material standards is compressing development timelines for surgical automation suppliers. The framework mandates fatigue testing protocols that diverge from FDA requirements, fragmenting product qualification pathways. Asian surgical robotics manufacturers are responding with dual-track certification strategies.
Aftermarket refurbishment contracts for surgical instrument nitinol components are displacing traditional replacement purchasing in German hospital procurement. Baden-Württemberg medical device service providers now capture recurring revenue through surface reconditioning and shape recovery restoration. The model concentrates in high-volume catheter labs where instrument turnover cycles compress.
Global Shape Memory Materials Market Segmentation
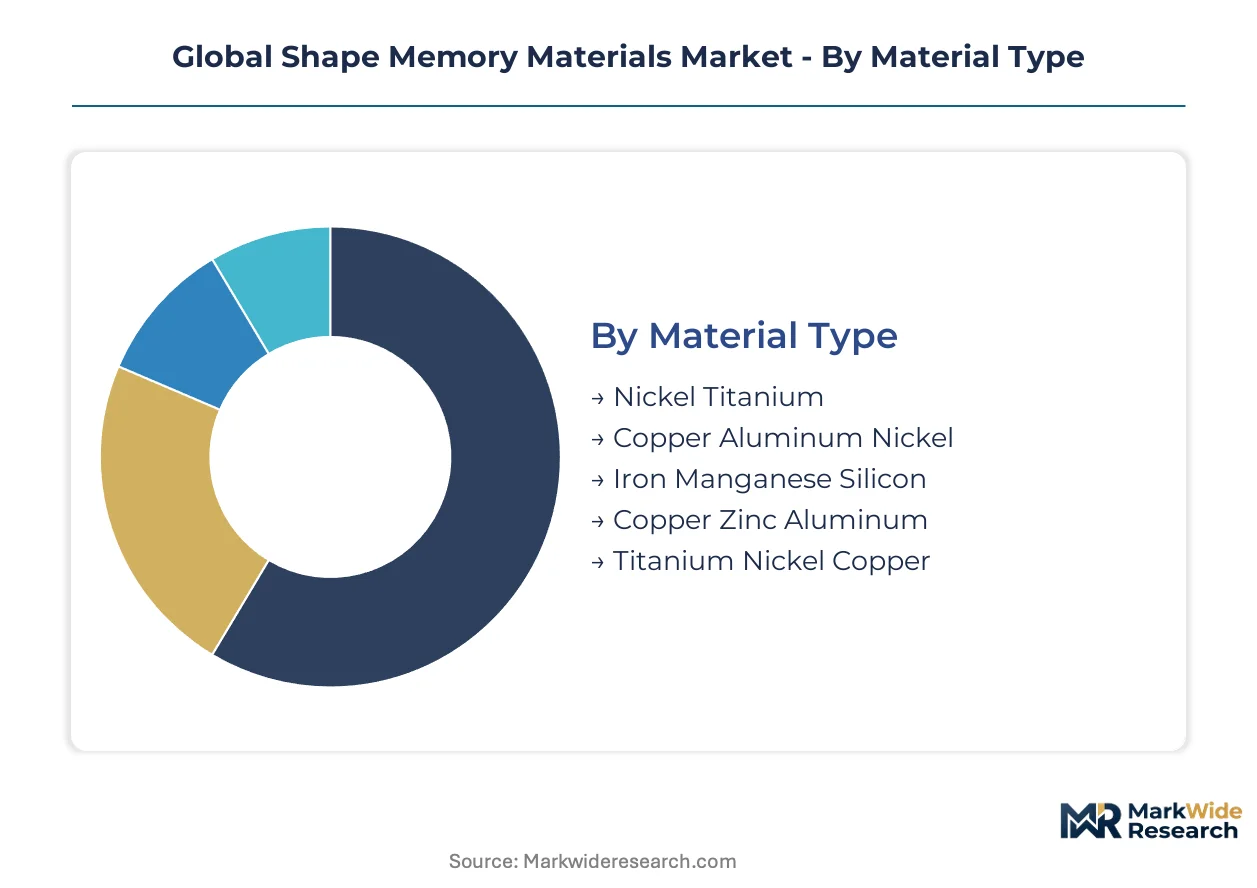
Material composition determines transformation temperature windows and superelastic performance limits across surgical, aerospace, and consumer applications. Form factor selection governs downstream processing economics, with precision-drawn wire commanding margin premiums over commodity sheet formats. Technology platforms diverge in actuation energy requirements, fragmenting supplier qualification pathways across medical and industrial end-uses.
Material Type:
Cost tier stratification separates premium vacuum-melted alloys from commodity induction-cast alternatives, with purity grades determining medical device market access.
- Nickel Titanium:Near-equiatomic nickel-titanium alloys exhibit superelasticity above 8% strain and Af temperatures tunable between −100°C and 100°C through thermomechanical processing. Demand concentrates in Massachusetts and Baden-Württemberg surgical device clusters, where FDA and EU MDR batch-level pedigree requirements filter out non-specialized suppliers.
- Copper Aluminum Nickel:Ternary copper-based alloys offer transformation temperatures above 100°C for thermal actuation applications at raw material cost advantages over nitinol. Procurement clusters in Osaka Prefecture favor this chemistry for consumer appliance thermal switches, though REACH registration burdens delay European commercialization.
- Iron Manganese Silicon:Iron-based shape memory alloys provide cost-competitive alternatives for civil engineering seismic damping applications where biocompatibility is irrelevant.
- Copper Zinc Aluminum:High zinc content enables low-cost thermal actuation in automotive underhood applications, though cyclic stability limitations constrain medical adoption.
- Titanium Nickel Copper:Copper additions to nitinol base chemistry depress transformation temperatures for cryogenic actuation in aerospace fuel system components.
Nickel Titanium holds installed capacity. Copper Aluminum Nickel is rotating up the share rankings.
Form:
Application requirements dictate form selection, with minimally invasive surgical instruments driving precision tube and wire specifications.
- Wire:Precision-drawn nitinol wire in diameters from 0.025mm to 3.0mm dominates catheter guidewire and orthodontic archwire applications. Surface oxide layers require electropolishing to meet ASTM F2063 biocompatibility standards. Nippon Steel Corporation controls aerospace-qualified wire streams across Asian surgical robotics supply chains.
- Tube:Seamless nitinol tubing with wall thickness below 50 micrometers enables stent delivery catheter shafts and laparoscopic instrument articulation. Baden-Württemberg precision drawing houses concentrate capability for ultra-thin-wall formats, creating supply bottlenecks for qualified medical-grade material.
- Sheet:Cold-rolled plate formats serve thermal actuator diaphragms and aerospace morphing structures where planar stress states dominate.
- Foil:Sub-100 micrometer thickness enables microelectromechanical thermal switches and battery management system actuators.
- Powder:Pre-alloyed nitinol powder feeds laser powder bed fusion systems for patient-specific orthopedic implants with topology-optimized compliance gradients.
- Film:Sputter-deposited thin films enable microactuator integration in consumer electronics haptic feedback systems.
Wire holds installed capacity. Tube is rotating up the share rankings.
Technology:
Actuation energy source fragments competitive positioning, with thermal platforms leveraging incumbent metallurgy against emerging magnetic and electroactive alternatives.
- Thermo-Mechanical:Conventional heat-activated shape recovery dominates installed base, with resistive heating or environmental temperature change triggering martensite-austenite transformation. Medical device manufacturers in Massachusetts rely on this mature platform for catheter steerability with predictable clinical workflows.
- Magnetic Shape Memory:Magnetic field actuation enables remote, non-contact shape control for applications where thermal cycling is impractical. Ni-Mn-Ga Heusler alloys exhibit strain outputs exceeding 6% under moderate magnetic fields, though single crystal production costs constrain volume adoption.
- Hydro-Actuated:Fluid pressure-driven shape change leverages existing hydraulic infrastructure in automotive and aerospace systems, bypassing electrical integration complexity.
- Electroactive:Direct electrical resistive heating of conductive shape memory polymers enables rapid response times for consumer electronics integration.
- Shape Memory Polymer:BASF SE and polymer compounders scale thermoplastic polyurethane formulations with programmable transformation temperatures, displacing metal in injection-moldable consumer electronics housings.
Thermo-Mechanical holds installed capacity. Shape Memory Polymer is rotating up the share rankings.
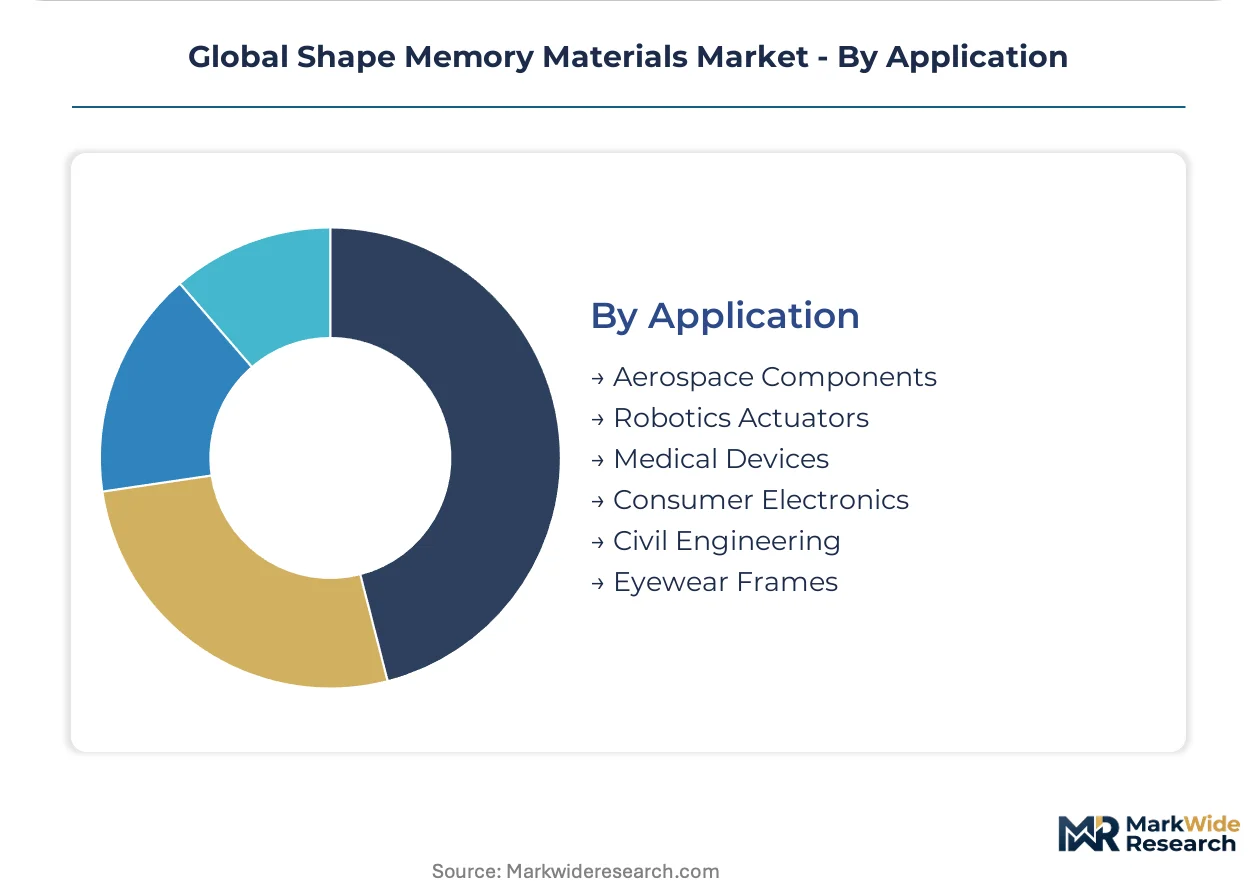
Application:
Customer type concentration varies by regulatory burden, with medical device procurement consolidating around certified suppliers while consumer electronics tolerates broader vendor bases.
- Medical Devices:Minimally invasive surgical instruments, stents, and orthopedic implants demand biocompatible nitinol with full metallurgical traceability. FDA quality system regulation and EU MDR conformity requirements elevate documentation burdens, compressing margins for non-specialized producers while rewarding backward-integrated alloy manufacturers.
- Aerospace Components:Morphing wings, variable geometry chevrons, and thermal actuation systems require fatigue-qualified material with aerospace material specifications. Japan's METI coordinates standards for robotic actuator materials that diverge from FAA requirements, fragmenting qualification pathways.
- Robotics Actuators:High-cycle fatigue nitinol wire enables precision drive systems in surgical automation. PMDA and METI coordinated standards in Japan create certified demand pathways distinct from FDA protocols.
- Consumer Electronics:Haptic feedback mechanisms and self-deploying antennas tolerate lower material consistency, enabling shape memory polymer penetration at cost points incompatible with medical grades.
- Civil Engineering:Seismic damping and structural health monitoring applications exploit high-force output of iron-based alloys without biocompatibility constraints.
- Eyewear Frames:Superelastic nitinol enables durable, lightweight optical frames with shape recovery after deformation, concentrated in mid-market fashion accessories.
Medical Devices holds installed capacity. Robotics Actuators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device procurement in the United States and Germany tolerates premium nitinol pricing due to stringent FDA and EU MDR traceability mandates. Consumer electronics manufacturers in China and Japan drive aggressive cost compression on shape memory polymer feedstock.
United States
Massachusetts surgical device clusters anchor domestic nitinol demand for catheter-based instruments. FDA quality system regulation elevates documentation burdens that filter out commodity suppliers. Boston-area precision drawing houses concentrate capability for ultra-thin-wall nitinol tubing used in minimally invasive tools.
Germany
Baden-Württemberg medical device manufacturers expand procurement of nickel-titanium alloys for laparoscopic instrumentation. EU MDR conformity requirements tighten material traceability standards and batch-level pedigree systems. Stuttgart-region metallurgists maintain captive vacuum metallurgy capabilities for aerospace-qualified material streams.
Japan
Osaka Prefecture robotics actuator demand concentrates procurement of high-cycle fatigue nitinol wire for surgical automation. METI and PMDA coordinate standards that create certified demand pathways distinct from FDA protocols. Kansai-region manufacturers adopt dual-track certification strategies to serve divergent regulatory requirements.
China
Domestic medical device manufacturing scales nitinol component fabrication for export to Middle Eastern and African markets. NMPA regulatory alignment with ISO standards accelerates local qualification timelines. Yangtze River Delta injection molders scale thermoplastic polyurethane formulations for consumer electronics housings.
India
CDSCO regulatory alignment attracts nitinol component fabrication for export markets. PLI scheme incentives support precision medical device manufacturing clusters. Maharashtra-based fabricators develop capability for catheter guidewire production serving Gulf Cooperation Council demand.
Global Shape Memory Materials Market Competitive Landscape
Backward-integrated alloy manufacturers and specialized precision fabricators split the market along certification-grade boundaries. The vendor base concentrates around vacuum metallurgy capabilities in Germany and Japan, with polymer compounders in Europe and Asia competing on injection-moldable formats. Three archetypes dominate: captive smelters with electron beam melting expertise, precision drawing houses with surface finishing knowledge, and polymer science specialists with programmable transformation temperature platforms. Capacity expansion in nitinol powder production and strategic partnerships between device OEMs and qualified material suppliers represent the dominant competitive moves.
Among European chemical conglomerates, BASF SE exemplifies the polymer science archetype with shape memory polyurethane formulations. Japanese steel majors including Nippon Steel Corporation occupy positions in bulk nitinol wire production. Specialized metallurgical firms such as SAES Getters sit within the high-purity vacuum-melted alloy tier, anchoring supply relationships with medical device manufacturers requiring full metallurgical traceability.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| ATI |
| Nippon Steel Corporation |
| SAES Getters |
| SMP Technologies Inc |
| Johnson Matthey |
| Furukawa Electric Co., Ltd. |
| Fort Wayne Metals |
| Others |
Supply & Pricing Matrix
Undercapacity in Baden-Württemberg precision drawing houses is compressing lead times for ultra-thin-wall nitinol tubing while elevating pricing power for qualified suppliers with captive vacuum metallurgy capabilities. This utilization squeeze forces medical device manufacturers in Massachusetts and Osaka Prefecture to accept longer contract terms and premium pricing to secure aerospace-qualified material streams.
Pricing Analysis
Aftermarket refurbishment contracts for surgical instrument nitinol components are displacing traditional replacement purchasing and driving lifetime value in German hospital procurement. Three-tier pricing structure across medical-grade certified, industrial-standard, and commodity-induction-cast levels separates batch-pedigree nitinol from lower-traceability alternatives. Cost compression in consumer electronics shape memory polymer feedstock is intensifying because Yangtze River Delta injection molders scale thermoplastic polyurethane formulations. Medical device clusters in Massachusetts and Baden-Württemberg exhibit least price sensitivity due to FDA and EU MDR traceability mandates, while consumer electronics manufacturers in China demonstrate highest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration among Baden-Württemberg precision drawing houses and Massachusetts-area electropolishing facilities controls access to medical-grade surface finishing. Raw material supply draws from nickel mining operations in Indonesia and Russia, titanium sponge production in Japan and Kazakhstan, and high-purity copper sources in Chile. Single-source vulnerability in vacuum arc remelting feedstock creates bottleneck risk when LME nickel pricing fluctuates. Distribution runs through qualified alloy manufacturers with backward-integrated electron beam melting capabilities, then to precision fabricators, then to device OEMs with direct hospital procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory divergence between FDA, EU MDR, and Japan's PMDA-METI frameworks creates specialized supplier niches that resist commoditization. The shift toward patient-specific orthopedic implants via additive manufacturing is fragmenting demand across topology-optimized compliance gradients rather than standard catalog components.
For Market Incumbents: Build certification moats by deepening backward integration into vacuum metallurgy and securing batch-level pedigree systems that satisfy EU MDR traceability mandates. Incumbents should anchor supply relationships with Massachusetts and Baden-Württemberg surgical device clusters through long-term offtake agreements that lock out commodity competitors. Capacity addition in nitinol powder production for laser powder bed fusion systems addresses the additive manufacturing threat from patient-specific implant startups. For New Entrants and Emerging Players: India's Maharashtra-based medical device manufacturing clusters offer underpenetrated access to Gulf Cooperation Council export markets where CDSCO regulatory alignment reduces qualification friction. New entrants should target robotics actuator materials in Japan's Kansai region where PMDA-METI coordinated standards create certified demand pathways distinct from entrenched FDA-qualified suppliers. A go-to-market angle through surface reconditioning and shape recovery restoration services captures recurring revenue without requiring full alloy production capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision drawing houses with electropolishing capabilities and aftermarket refurbishment contracts. Long-term viability across the analysis window favors targets with captive vacuum metallurgy and established relationships with hospital procurement systems rather than commodity induction-cast producers. The acquisition target archetype combines electron beam melting expertise with medical device batch-pedigree systems. The signal to watch is harmonization progress between FDA and PMDA pilot programs that would either consolidate supplier qualification costs or perpetuate regional specialization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Metallurgy | Captive electron beam melting secures aerospace-qualified material streams and filters out commodity competitors. |
| Long-term Supply Agreement with Device OEMs | Locked offtake with Massachusetts surgical device clusters defends margin position against nickel price volatility. |
| Capacity Expansion in Nitinol Powder Production | Pre-alloyed powder feeds laser powder bed fusion for patient-specific orthopedic implants with topology optimization. |
| Joint Venture for Regional Certification Dual-Track | PMDA-FDA coordinated testing protocols reduce fragmentation costs for Asian surgical robotics manufacturers. |
| Aftermarket Refurbishment Service Launch | Surface reconditioning contracts in Baden-Württemberg catheter labs convert replacement purchasing to recurring revenue. |
Research Methodology
A spread of perspectives from vacuum metallurgy technicians, medical device procurement managers, biomedical engineers, and polymer compounders converged on the working assumptions. Primary interviews with electron beam melting operators, GPO contracts managers at hospital systems, and regulatory affairs leads at device OEMs combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, METI standards publications, and customs trade data for nickel-titanium alloy imports. Bottom-up patient-specific implant demand modeling and top-down aerospace actuator procurement forecasts were triangulated.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition grade, form factor specification, actuation energy technology, and application regulatory burden. CAGRs were derived from installed capacity utilization rates and expansion announcements. Industry-specific forecast inputs incorporated vacuum arc remelting feedstock cost curves and PMDA-METI coordination timeline assumptions for robotic actuator materials.
Practitioners should monitor LME nickel pricing volatility, EU MDR harmonization implementation delays, and additive manufacturing qualification timeline acceleration for early signals that would revise trajectory assumptions. Quarterly review of hospital procurement database trends and aerospace material specification update frequencies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Global Shape Memory Alloys Market