
 Water Soluble Film Market | 2026-2036
Water Soluble Film Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Film Market Intelligence
Single-dose packaging buyers are reorganizing procurement priorities around sustainability credentials and automated dosing compatibility. Kuraray Co. Ltd. leverages captive polyvinyl alcohol resin production to secure feedstock consistency across Asian and European plants. Mitsubishi Chemical Group Corporation anchors its position through deep R&D spending on cold-water dissolution kinetics. Ecopol S.p.A. competes by specializing in blown-film extrusion lines purpose-built for thin-gauge water soluble applications.
Water soluble film denotes a polymer matrix engineered to disintegrate completely in aqueous environments without toxic residue, typically manufactured via cast or blown extrusion of polyvinyl alcohol at thicknesses between 20 and 80 microns for unit-dose encapsulation. Polyvinyl alcohol grades dominate current output owing to established solubility tunability and thermoplastic processability, while polyethylene glycol formulations represent the fastest-expanding chemistry subset in pharmaceutical blister alternatives. Among end use industries, pharmaceutical and personal care applications concentrate margin pools where regulatory validation requirements create pricing power for certified film suppliers.
EPA guidelines on safer chemical packaging and REACH substance restrictions are elevating compliance costs for non-biodegradable alternatives while accelerating substitution timelines. FDA unit-dose packaging standards and EU MDR material biocompatibility rules further narrow the supplier base to film producers with validated quality systems. Stakeholders must monitor polymer feedstock volatility and pre-qualify alternative resin sources before certification bottlenecks harden supply access.
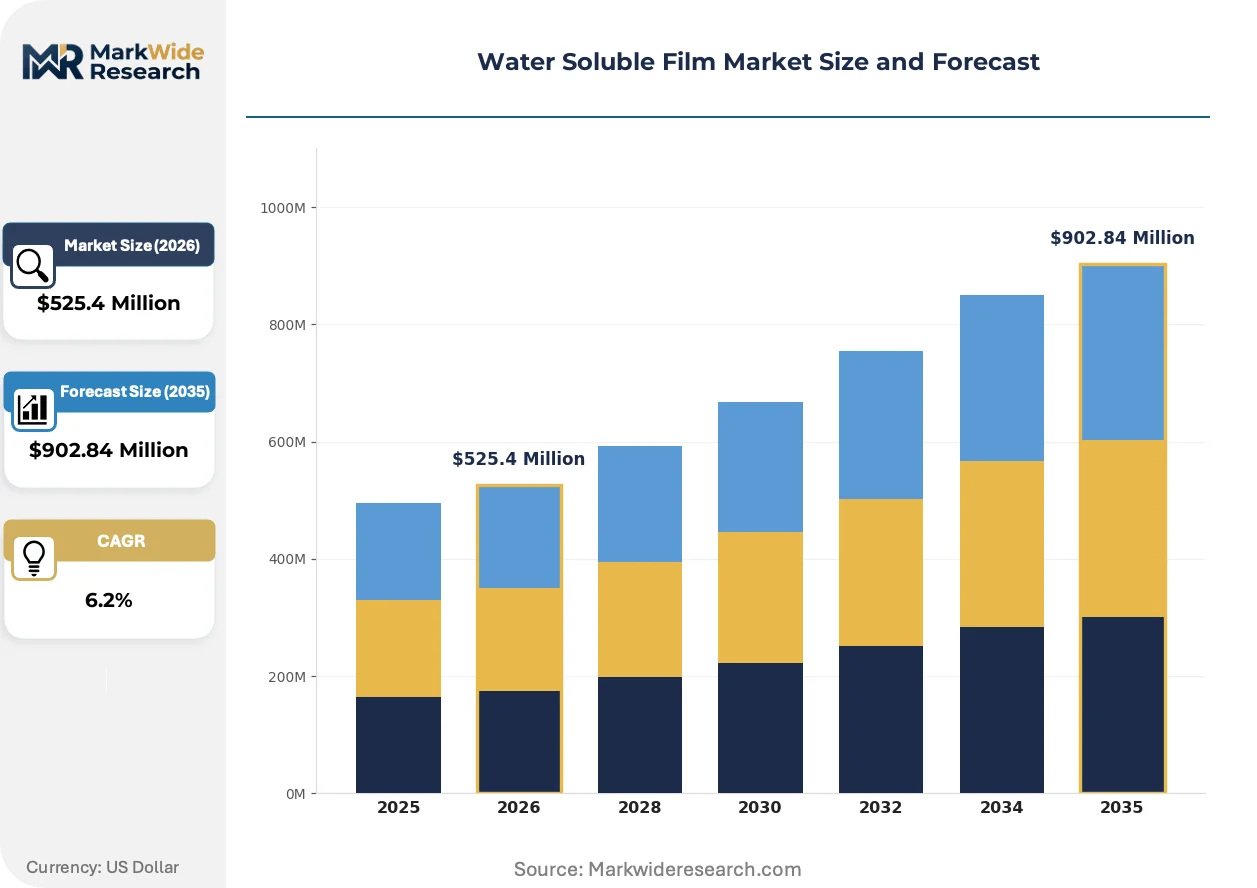
Market Dynamics
REACH substance restrictions and EPA safer chemical packaging guidelines are compressing the addressable market for conventional petroleum-derived films while elevating certified biodegradable alternatives. Polymer feedstock volatility and pre-qualification bottlenecks now determine supplier access more than unit economics.
Growth Catalysts
- Unit-dose detergent pods:Household cleaning brands in Germany and neighboring Central European markets are converting liquid detergent portfolios to pod formats, requiring thin-gauge water soluble film at scale.
- EU MDR biocompatibility rules:Pharmaceutical blister packaging validation requirements are narrowing supplier pools to film producers with certified quality systems, creating pricing power for compliant manufacturers.
- Cold-water dissolution kinetics:Advances in polyvinyl alcohol grade engineering are expanding addressable applications to lower-temperature washing environments and energy-conscious consumer segments.
Market Restraints
- Ethylene-vinyl acetate substitution threat:Conventional flexible packaging remains cost-competitive for non-unit-dose applications where dissolution performance is not mandatory.
- Polyvinyl alcohol supply concentration:Asian resin producers control upstream feedstock for blown and cast extrusion lines, exposing European converters to shipping cost volatility and currency fluctuation.
- REACH biodegradability testing timelines:Extended substance registration protocols delay new polymer chemistry commercialization by 18-36 months, freezing formulation innovation cycles.
Strategic Opportunities
- Pharmaceutical blister alternatives:Polyethylene glycol chemistry subsets are penetrating pediatric and geriatric unit-dose formats where taste-masking and rapid dissolution are prioritized.
- Automated dosing compatibility:Industrial laundries and food service operations are retrofitting equipment for pre-measured detergent and sanitizer delivery, opening B2B volume channels.
- EU Green Deal circular packaging mandates:National implementation frameworks in France, Italy, and the Netherlands are creating preferential procurement quotas for marine-biodegradable film in institutional cleaning contracts.
Industry Challenges
- Polymer rheology expertise gap:Blown-film extrusion at 20-40 micron gauges requires technicians trained in melt tension control and bubble stability, a skill set concentrated among legacy packaging engineers.
- Multi-jurisdiction certification burden:FDA unit-dose standards, EMA pharmaceutical guidelines, and national food contact approvals must be maintained in parallel, consuming quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Film Market |
| Market Size in 2026 | $525.4 Million |
| Market Size in 2035 | $902.84 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Alcohol, Polyethylene Glycol, Gelatin, Others End Use Industry: Agriculture, Pharmaceutical, Food Packaging, Personal Care Form: Sheets, Bags, Pods, Coatings Distribution Channel: Online Retail, Distributors, Direct Sales, B2B Sales |
| Companies Covered | Kuraray Co. Ltd., Mitsubishi Chemical Group Corporation, Sekisui Chemical Co. Ltd., Aicello Corporation, Ecopol S.p.A., Arrow GreenTech Ltd., Cortec Corporation, AMC (UK) Ltd., Jiangmen Proudly Water-soluble Plastic Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Film Market Strategic Shifts & Innovations
Active materials engineering and regulatory chemistry revisions are compressing product development cycles while fragmenting the supplier base along certification lines. The convergence of dissolution performance tuning and automated packaging line integration is reshaping technical specifications.
Multilayer coextrusion architectures are miniaturizing functional gradients within water soluble films, embedding controlled-release triggers and moisture barriers at sub-micron thicknesses. Pharmaceutical contract manufacturers in Switzerland and Germany are qualifying these structures for hygroscopic active pharmaceutical ingredient protection. The technology is miniaturizing the barrier-performance-to-thickness ratio that previously required 60-80 micron monolayer constructions.
REACH Annex XIV authorization requirements are expanding the list of substances requiring substitution plans, directly affecting plasticizer and processing aid portfolios used in film extrusion. European compounders are reformulating additive packages to maintain thermoplastic processability without listed substances. Personal care unit-dose segments in Germany and France are absorbing 15-20% formulation cost premiums to maintain market access under tightened compliance deadlines.
Brand-owner sustainability scorecards are elevating certified biodegradable film to a procurement gate condition rather than a price-negotiable attribute. Major household cleaning multinationals are consolidating supplier panels to three validated producers per region, displacing spot-market purchasing. This concentration is most visible in German retail channels where private-label detergent pods now carry explicit marine-biodegradability claims backed by third-party certification.
Water Soluble Film Market Segmentation
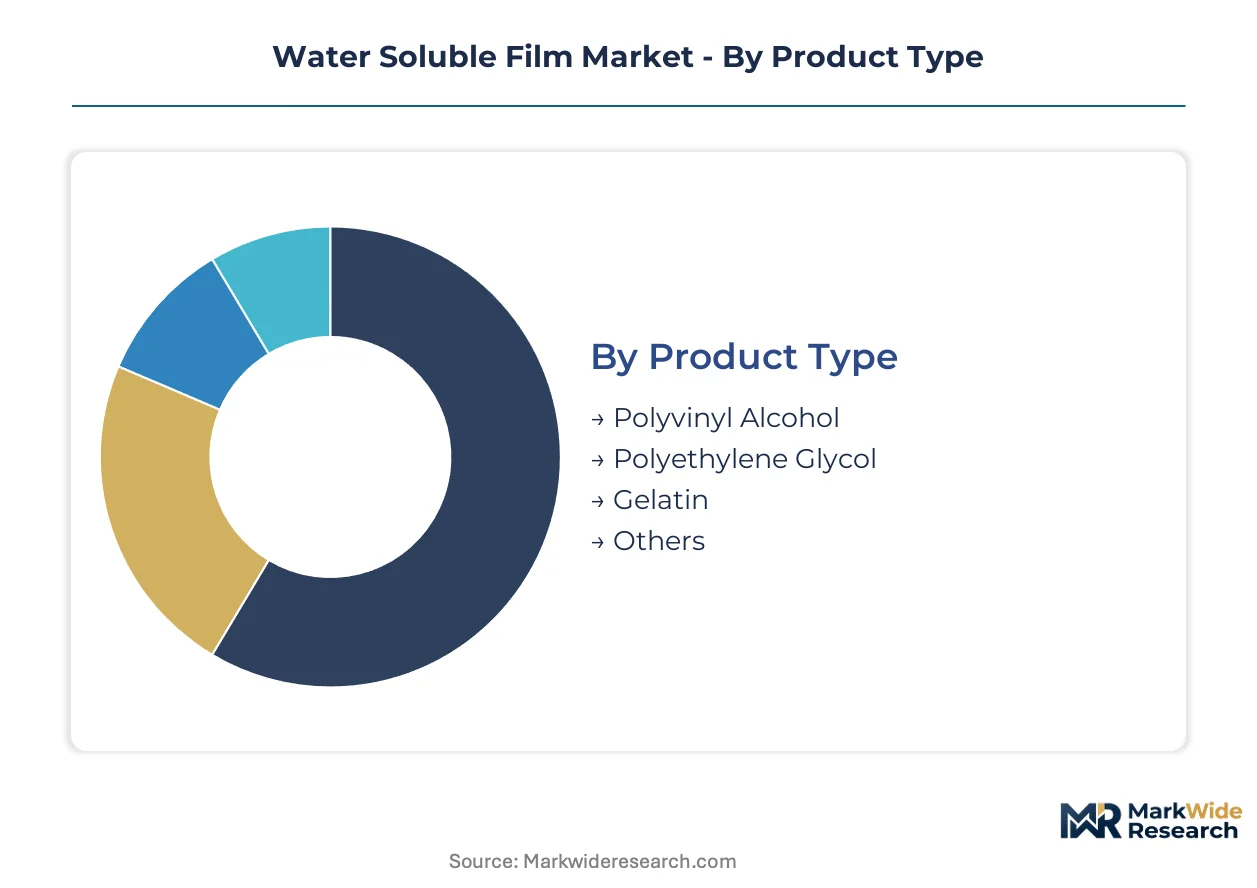
Water soluble film segmentation reveals how polymer chemistry and form factor choices interact with regulatory pathways. Each dimension carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
REACH substance restrictions and FDA pharmaceutical guidelines create divergent compliance costs across polymer chemistries, fragmenting the supplier base along certification lines.
- Polyvinyl Alcohol:Thermoplastic grades engineered for 20-80 micron gauges dominate current extrusion output. German household cleaning brands and Central European packaging converters anchor procurement volumes for unit-dose detergent applications.
- Polyethylene Glycol:Hydrophilic polymer matrices dissolve rapidly in aqueous environments without residue. Pediatric and geriatric pharmaceutical blister formats in Switzerland and Germany are absorbing this chemistry where taste-masking and cold-water dissolution are prioritized.
- Gelatin:Animal-derived protein films serve niche pharmaceutical encapsulation with established biocompatibility profiles.
- Others:Emerging polysaccharide and synthetic polymer alternatives target marine-biodegradability specifications under EU Green Deal procurement quotas.
Polyvinyl alcohol handles the majority of throughput; polyethylene glycol is gaining share fastest in certified pharmaceutical applications.
End Use Industry:
Margin concentration follows validation intensity, with pharmaceutical and personal care segments commanding pricing premiums over agricultural commodity applications.
- Pharmaceutical:Blister packaging and unit-dose sachets require EMA biocompatibility validation and FDA unit-dose standards. Swiss and German contract manufacturers are qualifying multilayer coextrusion structures for hygroscopic active ingredient protection.
- Personal Care:Single-dose masks, bath beads, and fragrance encapsulation carry 15-20% formulation cost premiums in France and Germany to maintain REACH compliance deadlines.
- Agriculture:Pesticide and fertilizer water soluble packaging serves field-delivery applications with lower certification barriers but higher volume throughput.
- Food Packaging:Portion-control sachets and edible films face national food contact approval requirements that vary across EU member states.
Pharmaceutical commands the steepest pricing tiers; personal care is climbing fastest on sustainability scorecard integration.
Form:
Equipment compatibility and automated line integration determine form factor adoption curves across industrial and consumer channels.
- Pods:Pre-formed unit-dose chambers dominate household cleaning procurement from German retail channels. Blown-film extrusion at 20-40 micron gauges requires specialized melt tension control for bubble stability.
- Bags:Industrial laundry and food service pre-measured delivery formats are retrofitting equipment for automated dosing compatibility.
- Sheets:Flat film constructions serve manual packaging operations and custom cutting applications.
- Coatings:Functional layer applications embed controlled-release triggers and moisture barriers at sub-micron thicknesses.
Pods generate the highest revenue concentration; bags are expanding most quickly in B2B retrofit channels.
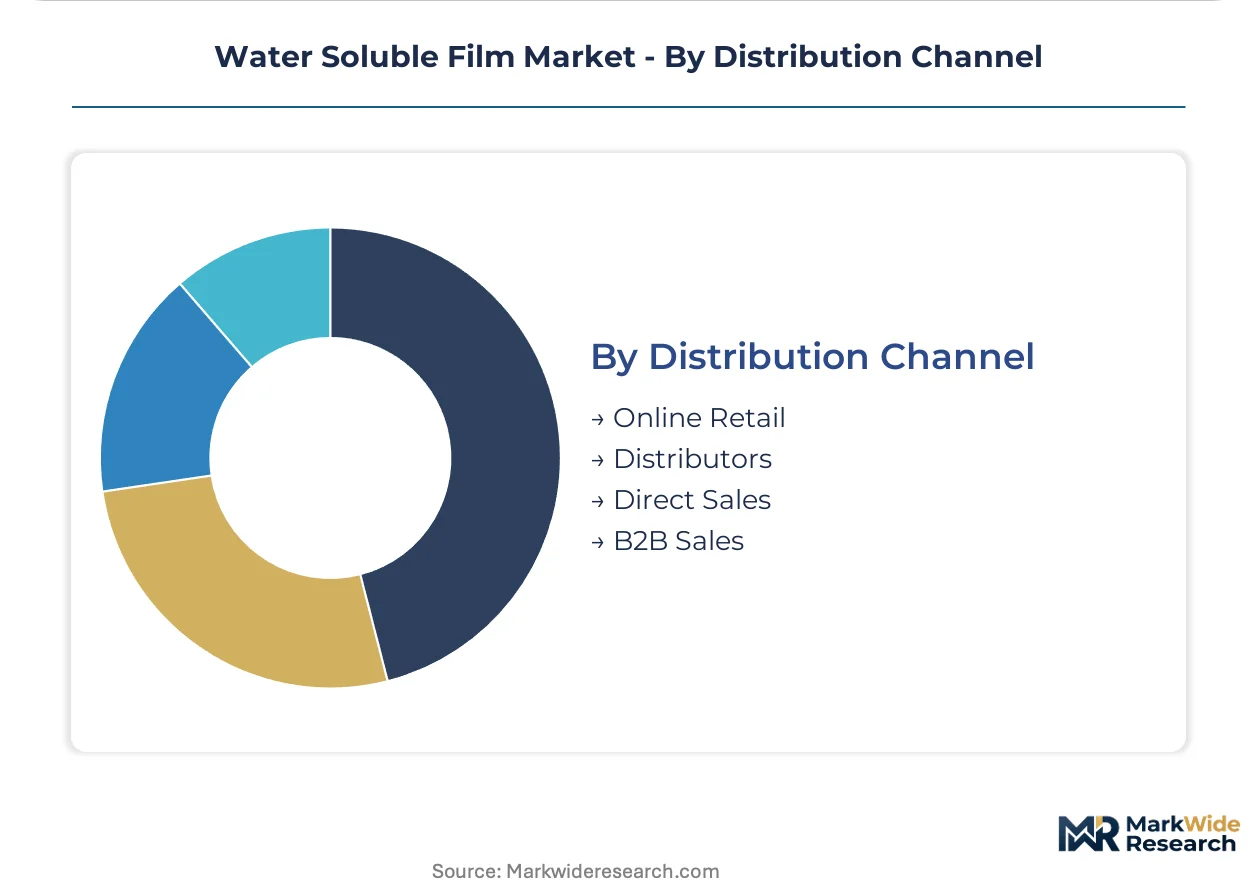
Distribution Channel:
Procurement consolidation by major household cleaning multinationals is compressing supplier panels and displacing spot-market purchasing.
- B2B Sales:Direct relationships with packaging converters and pharmaceutical contract manufacturers dominate volume procurement. German converters serving Central European brand owners concentrate demand through validated producer panels.
- Distributors:Regional chemical and packaging distributors maintain inventory for mid-tier converters without captive resin supply.
- Direct Sales:Large film producers engage multinational brand owners on sustainability scorecard compliance and long-term offtake agreements.
- Online Retail:Niche specialty grades and small-batch pharmaceutical applications access qualified buyers through digital procurement platforms.
B2B sales handle the majority of throughput; direct sales are climbing fastest on panel consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian resin producers control upstream polyvinyl alcohol feedstock for blown and cast extrusion lines. European packaging converters face shipping cost volatility and currency fluctuation when sourcing from these concentrated supply bases. German household cleaning brands anchor procurement volumes for unit-dose detergent applications.
Germany
Household cleaning brands in Germany are converting liquid detergent portfolios to pod formats at scale. REACH compliance deadlines and EU Green Deal circular packaging mandates tighten specifications for polymer biodegradability. Packaging converters in North Rhine-Westphalia serve Central European brand owners with validated quality systems.
United States
EPA guidelines on safer chemical packaging elevate compliance costs for conventional petroleum-derived films. FDA unit-dose packaging standards narrow supplier pools to certified film producers. Industrial laundries in the Midwest are retrofitting equipment for automated dosing compatibility with pre-measured sanitizer delivery.
China
Blown-film extrusion lines for thin-gauge water soluble applications concentrate production capacity. MIIT standards and GB standards govern industrial polymer processing specifications. Jiangmen-based converters supply Asian pharmaceutical contract manufacturers with certified film grades.
Switzerland
Swissmedic pharmaceutical guidelines and EMA biocompatibility rules validate multilayer coextrusion structures for hygroscopic active ingredient protection. Pediatric and geriatric unit-dose formats prioritize rapid dissolution kinetics. Basel-area contract manufacturers qualify polyethylene glycol chemistry subsets for taste-masking applications.
Japan
METI industrial standards support cold-water dissolution engineering for energy-conscious consumer segments. PMDA pharmaceutical packaging requirements maintain strict material biocompatibility protocols. Osaka-based chemical groups anchor R&D spending on polyvinyl alcohol grade engineering for lower-temperature washing environments.
Water Soluble Film Market Key Industry Players
Concentration sits with diversified chemical conglomerates possessing captive resin supply and specialized film extrusion specialists. The supplier base fragments along certification lines rather than scale tiers. Three archetypes dominate: integrated resin-to-film producers, blown-film extrusion specialists, and regional packaging converters with validated quality systems. Strategic moves center on backward integration into polyvinyl alcohol resin production and pre-qualification of alternative feedstock sources before certification bottlenecks harden.
Among Japanese chemical conglomerates, Kuraray Co. Ltd., Mitsubishi Chemical Group Corporation, and Sekisui Chemical Co. Ltd. represent the integrated resin-to-film archetype with upstream control over polyvinyl alcohol supply chains. Within the European specialist tier, Ecopol S.p.A. occupies a position exemplifying purpose-built blown-film extrusion capabilities for thin-gauge applications. These named entities anchor competitive positioning without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Kuraray Co. Ltd. |
| Mitsubishi Chemical Group Corporation |
| Sekisui Chemical Co. Ltd. |
| Aicello Corporation |
| Ecopol S.p.A. |
| Arrow GreenTech Ltd. |
| Cortec Corporation |
| AMC (UK) Ltd. |
| Jiangmen Proudly Water-soluble Plastic Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Ninety-day resin inventory buffers at European converters now determine contract pricing power more than volume commitments, as Asian polyvinyl alcohol feedstock concentration forces German and Swiss buyers to absorb currency and freight volatility into landed cost structures. REACH compliance deadlines and EU Green Deal procurement quotas reward certified biodegradable grades with 15-20% formulation premiums, while spot-market purchasers face exclusion from multinational household cleaning supplier panels.
Pricing Analysis
REACH Annex XIV authorization requirements dictate the pricing tier structure across pharmaceutical, personal care, and agricultural segments. Three-tier pricing stratifies across REACH-certified premium grades, FDA-validated pharmaceutical tiers, and economy agricultural formats where dissolution performance alone determines specification. Price differentiation centers on biodegradability certification level and cold-water dissolution kinetics, with pharmaceutical blister alternatives commanding the steepest premiums. Cost compression in economy agricultural tiers is intensifying because ethylene-vinyl acetate substitution threatens volume retention. Household cleaning multinationals show least price sensitivity due to sustainability scorecard mandates, while spot-market converters absorb full volatility exposure.
Supply Chain Analysis
Ninety-day resin inventory buffers reflect Asian polyvinyl alcohol supply concentration across China, Japan, and South Korea, where blown-film extrusion capacity feeds global converter demand. European packaging operations draw from vinyl acetate monomer feedstock anchored in petrochemical complexes near Rotterdam and Antwerp, with secondary reliance on imported resin grades. Single-source vulnerability concentrates in thin-gauge blown-film lines where 20-40 micron gauge expertise remains concentrated among legacy technicians. Distribution runs through validated B2B producer panels serving Central European brand owners, displacing spot-market purchasing for certified biodegradable grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supplier fragmentation along certification lines creates carve-out opportunities for specialized film producers, as EU MDR biocompatibility rules and REACH substance restrictions fragment demand into validated niche segments requiring distinct polymer chemistry expertise.
For Market Incumbents: Fortify backward integration into captive polyvinyl alcohol resin production to secure feedstock consistency ahead of REACH registration bottlenecks. Expand cold-water dissolution R&D spending to defend margin position against polyethylene glycol substitution in pediatric pharmaceutical formats. Pre-qualify alternative resin sources in Central European chemical clusters before certification timelines harden supply access. For New Entrants and Emerging Players: Differentiate on marine-biodegradability certification under EU Green Deal procurement quotas in French and Dutch institutional cleaning contracts. Target pharmaceutical blister alternatives in Swiss and German contract manufacturing clusters where EMA validation requirements narrow incumbent supplier pools. Pursue co-development partnerships with packaging converters lacking in-house blown-film extrusion expertise for thin-gauge pod applications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese chemical conglomerates seeking to monetize non-core film extrusion assets. Long-term viability rests on regulatory chemistry expertise rather than scale economies, favoring acquisition of certified quality systems over commodity capacity expansion. Watch for REACH Annex XIV substance listing announcements as inflection indicators for polymer reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyvinyl alcohol supply secures feedstock consistency across REACH compliance deadlines. |
| Cold-Water Dissolution R&D Investment | Mitsubishi Chemical Group spending anchors competitive positioning in energy-conscious consumer segments. |
| Marine-Biodegradability Certification | EU Green Deal procurement quotas in France and Netherlands reward third-party validated film grades. |
| Multilayer Coextrusion Qualification | Swiss and German pharmaceutical contract manufacturers adopt sub-micron barrier architectures for hygroscopic APIs. |
| Long-Term Offtake Agreements | Household cleaning multinationals consolidate supplier panels to three validated producers per region. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with packaging converter procurement leads, pharmaceutical contract manufacturing quality directors, blown-film extrusion line technicians, and household cleaning brand sustainability officers. Secondary validation drew from ECHA REACH registration databases, FDA unit-dose packaging guidance documents, EU MDR technical documentation requirements, and customs trade data for polyvinyl alcohol resin flows. Bottom-up volume triangulation across end-use segments was cross-checked against top-down chemical industry capacity assessments.
Across the analysis window, the forecasting framework modeled polymer chemistry grades, end-use industry validation intensity, form factor equipment compatibility, and regional regulatory cluster adoption patterns. CAGRs were derived from segment-level volume build-ups calibrated to resin consumption trends and certification timeline assumptions. Cold-water dissolution performance curves and automated packaging line integration rates served as industry-specific forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or abrupt polyvinyl alcohol feedstock disruption would require recalibration. Forecasts reflect documented assumptions about certification timeline adherence and multinational procurement consolidation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Non-Semiconductor Neon Market