
 Global Optical Encryption Market | 2026-2036
Global Optical Encryption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Encryption Market Foresight
Multi-source procurement for optical encryption engines is repositioning how telecom equipment vendors allocate foundry capacity and IP licensing budgets. Ciena Corporation leverages vertically integrated silicon photonics to control chipset-to-system margins across submarine and terrestrial deployments. Nokia Corporation anchors its portfolio with programmable encryption line cards that interoperate with legacy optical transport layers. Huawei Technologies Co. Ltd competes through deep domestic supply chain capture in China's fiber backbone buildouts.
Optical encryption secures data-in-transit by encoding photonic signals at the physical layer using techniques such as phase scrambling and polarization multiplexing, rendering intercepted fiber taps unreadable without corresponding key material. The technology serves industries where electronic-layer encryption introduces unacceptable latency or power overhead on high-capacity links. Optical transceivers carry the largest installed base across product categories, though encryption software and key generators capture expanding attach rates as network operators disaggregate hardware from control planes. Quantum Key Distribution commands premium positioning among technology segments despite deployment constraints, while Phase Encryption dominates volume shipments in commercial metro networks.
The U.S. FCC, EU GDPR framework, and China's MIIT each impose distinct data sovereignty and breach-notification requirements that elevate optical encryption from optional feature to procurement mandate. The U.S. NIST post-quantum cryptography timeline accelerates vendor investment in quantum-resistant physical-layer protocols. Stakeholders must evaluate whether QKD integration timelines align with existing DWDM refresh cycles or demand parallel infrastructure overlays.
Market Dynamics
Physics-based security layers are redirecting procurement cycles as network operators confront post-quantum cryptographic timelines and fiber interception risks across submarine and terrestrial backbones. This structural pivot elevates optical encryption from optional line-card feature to infrastructure mandate.
Growth Catalysts
- GDPR and data sovereignty frameworks:Cross-border data transport mandates in the European Union compel carriers to deploy physical-layer encryption at submarine cable landing stations. Breach-notification thresholds accelerate procurement decisions.
- Hyperscale data center interconnects:Cloud operators building private fiber networks between campuses require low-latency encryption that bypasses electronic-layer processing overhead. This demand concentrates in the United States and Germany.
- Quantum Key Distribution maturation:Laboratory-to-field transitions in China and Switzerland validate QKD for financial and government backbones. Pilot deployments now inform refresh-cycle planning for DWDM infrastructure.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for high-speed electro-optic modulators clusters with Asian semiconductor fabricators. Input scarcity elevates chipset costs and extends lead times for encryption engine production.
- NIST post-quantum standardization delays:Uncertainty around algorithm finalization freezes procurement budgets for hybrid classical-quantum systems. Enterprises defer commitments pending certification clarity.
- Silicon photonics substitution threat:Commoditized transceivers with embedded encryption erode pricing power for standalone encryption appliances. Volume manufacturing in China compresses margins at the mid-market tier.
Strategic Opportunities
- Underpenetrated submarine cable upgrades:Aging trans-Atlantic and trans-Pacific systems require inline encryption retrofitting. Landing stations in Portugal and Singapore present near-term deployment windows.
- Convergence of AI traffic patterns and encryption:Machine learning workloads generate east-west data center flows that bypass traditional perimeter security. Optical encryption addresses this blind spot without latency penalties.
- India's BharatNet fiber expansion:Government-funded rural backbone construction creates first-mover positioning for vendors offering cost-optimized encryption modules compliant with domestic sourcing requirements.
Industry Challenges
- Photonic integration engineering scarcity:Talent pools capable of co-designing silicon photonics with cryptographic key management remain shallow. Universities in Germany and the Netherlands struggle to graduate sufficient specialists.
- Multi-vendor interoperability certification:Proprietary encryption protocols from incumbent transport vendors fragment procurement. Open line system adoption requires costly validation cycles before deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Encryption Market |
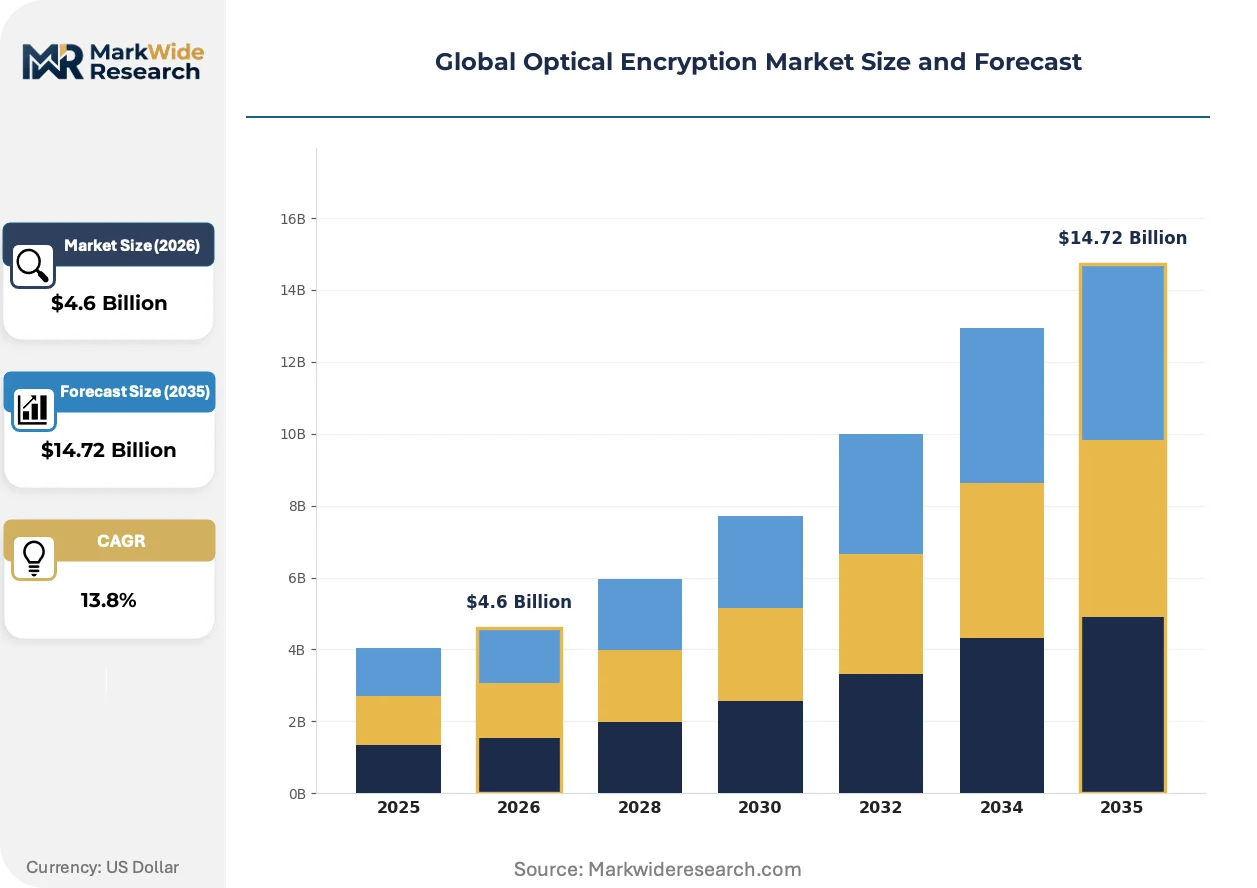
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $14.72 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encryptors, Decryptors, Optical Transceivers, Encryption Software, Key Generators Technology: Quantum Key Distribution, Phase Encryption, Amplitude Encryption, Polarization Encoding, Time-Domain Encoding Application: Data Security, Military Communications, Financial Transactions, Cloud Security, Critical Infrastructure Protection End User: Telecommunication Providers, Defense Agencies, Banking Institutions, Cloud Service Firms, Energy Operators |
| Companies Covered | Ciena Corporation, Huawei Technologies Co. Ltd, Nokia Corporation, Cisco Systems Inc., ADVA Optical Networking, Infinera Corporation, Broadcom Inc., ECI Telecom, Arista Networks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Encryption Market Shifts & Advancements
Physical-layer security architectures are fragmenting as network disaggregation separates encryption control planes from transport hardware. This decomposition enables software-defined key orchestration while complicating vendor accountability.
Coherent optical engines with embedded encryption are expanding into metro aggregation networks previously served by unencrypted direct-detect links. Regional carriers in France and Japan now specify line-rate encryption as default for 100G+ deployments. This capability compression eliminates standalone encryption appliances from access-layer budgets.
The EU Cybersecurity Act and NIS2 Directive impose mandatory security certification for critical telecommunications infrastructure. Operators must document encryption coverage across national backbones or face operational restrictions. German incumbent carriers are restructuring procurement to prioritize pre-certified optical transport platforms.
Hyperscale buyers now unbundle encryption software licenses from hardware purchases, forcing traditional equipment vendors to defend recurring revenue through key-management subscriptions. This preference shift concentrates in the United States where cloud operators command procurement leverage. Japanese system integrators are adapting sales models to accommodate disaggregated procurement frameworks.
Global Optical Encryption Market Segmentation
Optical encryption procurement diverges sharply across deployment contexts, with certification requirements, latency tolerances, and threat models dictating product selection. Each segment carries distinct regulatory burdens that reshape vendor qualification timelines and customer switching costs.
Product Type:
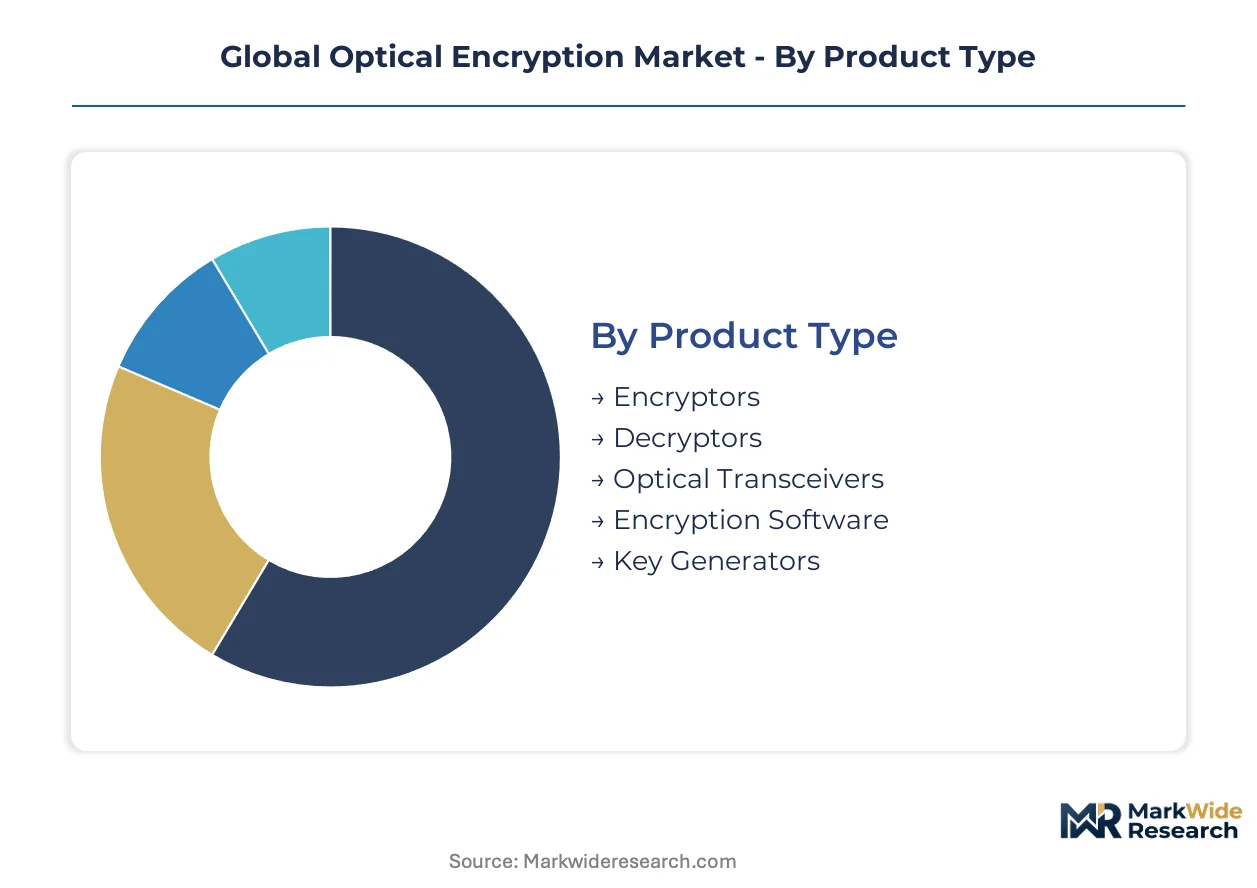
Certification burdens cluster around encryption software and key generators, where FIPS 140-2 validation and Common Criteria EAL4+ impose 18-24 month approval cycles. Hardware-centric segments face electromagnetic compatibility and safety testing rather than cryptographic certification.
- Optical Transceivers:These pluggable modules embed encryption engines directly within coherent DSP chipsets, eliminating standalone appliances from high-speed links. Demand concentrates in hyperscale data center interconnects across the United States and Germany, where cloud operators mandate line-rate security without electronic-layer latency penalties.
- Encryption Software:Disaggregated control planes enable software-defined key orchestration across multi-vendor transport infrastructure. Procurement in Switzerland and Japan prioritizes open APIs and YANG model compliance for integration with existing network management systems.
- Encryptors:Standalone appliances for legacy network retrofitting.
- Decryptors:Paired receiving units for symmetric key architectures.
- Key Generators:Hardware security modules for entropy sourcing and key lifecycle management.
Optical transceivers sit at the top of the volume ranking, with encryption software climbing the fastest.
Technology:
Cost tiers separate laboratory-validated quantum systems from commercially deployable phase and amplitude methods, with polarization and time-domain encoding occupying mid-market positioning for specialized government links.
- Phase Encryption:Commercial metro networks favor this technique for its compatibility with existing coherent receivers and DSP architectures. Deployment density runs highest in China's provincial backbone expansions, where MIIT procurement guidelines prioritize interoperable physical-layer security without forklift upgrades.
- Quantum Key Distribution:Physics-based security leveraging entangled photon pairs commands premium positioning for financial and government backbones. Pilot networks in Switzerland and China's Beijing-Shanghai trunk validate satellite-to-ground and fiber-based QKD against harvest-now-decrypt-later threats.
- Amplitude Encryption:Direct modulation approaches for cost-sensitive access networks.
- Polarization Encoding:Specialized military and diplomatic communications requiring high isolation.
- Time-Domain Encoding:Ultrafast pulse manipulation for covert channel applications.
Phase encryption dominates current shipment volumes, though QKD gains share fastest among government and financial procurement categories.
Application:
Application segments map directly to threat actor profiles and breach consequence severity, with military and critical infrastructure commanding the most stringent supply chain provenance requirements.
- Data Security:Enterprise and carrier networks protecting transit traffic against fiber tapping and passive interception. Investment intensity peaks in Germany, where GDPR breach-notification thresholds and BSI technical guidelines compel physical-layer encryption for cross-border data flows.
- Military Communications:National security networks requiring TEMPEST shielding and anti-tamper hardware. NATO member states and China's PLA-affiliated research institutes drive classified procurement with domestic sourcing mandates.
- Financial Transactions:Banking consortiums securing high-value payment infrastructure.
- Cloud Security:Hyperscale operators encrypting east-west data center traffic.
- Critical Infrastructure Protection:Energy and utility sectors safeguarding SCADA backbones.
Data security leads application volumes, while cloud security expands most quickly alongside AI workload proliferation.
End User:
Customer type determines procurement centralization, with telecommunication providers and defense agencies operating dedicated acquisition offices while banking and energy sectors delegate through systems integrators.
- Telecommunication Providers:Incumbent carriers and wholesale operators integrating encryption into DWDM refresh cycles. Verizon and Deutsche Telekom specify line-rate security as default for 100G+ submarine and terrestrial deployments, compressing standalone encryption vendor margins.
- Cloud Service Firms:Hyperscale builders of private fiber networks between campuses and availability zones. Amazon Web Services and Microsoft Azure unbundle software licenses from hardware, forcing equipment vendors toward subscription-based key management revenue models.
- Defense Agencies:Classified programs with classified budgets and classified requirements.
- Banking Institutions:Swift network participants and central bank digital currency infrastructure builders.
- Energy Operators:Grid operators securing substation-to-control-center communications.
Telecommunication providers anchor volume demand, with cloud service firms driving the steepest expansion trajectory through private fiber buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping optical encryption deployment as compliance cost differentials between jurisdictions redirect infrastructure investment toward markets with clearer certification pathways and stronger data sovereignty enforcement.
United States
Hyperscale cloud operators and submarine cable consortiums drive procurement intensity along coastal landing zones and inland data center corridors. The FCC mandates physical-layer security documentation for critical telecommunications infrastructure under evolving cybersecurity frameworks. Northern Virginia's data center cluster and the Los Angeles-San Francisco fiber corridor see concentrated deployment of line-rate encryption for inter-campus connectivity.
Germany
GDPR breach-notification thresholds and BSI technical guidelines compel carriers to encrypt cross-border transit traffic at submarine landing stations in Hamburg and Frankfurt. The EU Cybersecurity Act and NIS2 Directive impose mandatory certification requirements that extend procurement cycles. Bavaria's automotive and industrial automation clusters generate specialized demand for low-latency encrypted backhaul.
China
MIIT procurement guidelines prioritize domestic supply chain capture for provincial backbone expansions and Beijing-Shanghai trunk deployments. Government-funded fiber buildouts in western provinces accelerate volume demand for interoperable physical-layer security. Shenzhen and Shanghai host concentrated engineering activity for silicon photonics integration with encryption engines.
Switzerland
Financial services hubs in Zurich and Geneva validate quantum key distribution pilots for high-value payment infrastructure against harvest-now-decrypt-later threats. FINMA operational resilience requirements intersect with EU data transfer adequacy negotiations. The Geneva-Bern corridor serves as a testbed for satellite-to-ground QKD integration with terrestrial fiber networks.
India
BharatNet rural fiber expansion creates first-mover positioning for vendors offering cost-optimized encryption modules compliant with domestic sourcing mandates under the PLI scheme. TRAI security guidelines for critical infrastructure elevate encryption from optional feature to procurement requirement. Maharashtra and Karnataka's emerging data center clusters generate demand for metro aggregation encryption.
Global Optical Encryption Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue quantum-ready architectures and disaggregated software licensing models. The vendor base organizes around three strategic archetypes: vertically integrated transport equipment vendors, silicon photonics specialists, and pure-play encryption software providers. Competitive positioning hardens through M&A activity targeting photonic integration capabilities and strategic partnerships for submarine cable retrofitting.
Among North American equipment vendors, Ciena Corporation and Cisco Systems Inc. occupy positions within the integrated transport tier, while Nokia Corporation anchors European-based competition through programmable encryption line cards. These named entities exemplify divergent approaches to hardware-software bundling as hyperscale buyers unbundle licenses from chassis purchases.
| Leading Market Players |
|---|
| Ciena Corporation |
| Huawei Technologies Co. Ltd |
| Nokia Corporation |
| Cisco Systems Inc. |
| ADVA Optical Networking |
| Infinera Corporation |
| Broadcom Inc. |
| ECI Telecom |
| Arista Networks Inc. |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators and submarine cable consortiums command procurement leverage that compresses channel margins while elevating subscription-based key management revenue. Their concentrated buying power forces equipment vendors toward direct licensing models that bypass traditional distributor markups on encryption hardware.
Pricing Analysis
Distributor margins on standalone encryption appliances have compressed as coherent optical engines with embedded security eliminate mid-market tier demand. Three-tier pricing structure across FIPS 140-2 certified, Common Criteria validated, and uncertified commercial grades separates government procurement from enterprise metro deployments. Cost compression in silicon photonics transceivers is intensifying because Chinese foundries commoditize 100G+ coherent DSP integration. Cloud service firms exhibit lowest price sensitivity due to latency-driven specification requirements, while regional carriers in India and Southeast Asia face acute budget constraints.
Supply Chain Analysis
Certification timelines for cryptographic modules gate supplier qualification, extending vendor onboarding to 18-24 months for defense and financial verticals. Foundry capacity for indium phosphide electro-optic modulators concentrates in Taiwan, South Korea, and Japan, while silicon photonics packaging clusters in China and Malaysia. Input scarcity for high-speed modulators creates single-source vulnerability when Asian semiconductor fabricators allocate capacity to AI accelerator demand. Distribution runs through direct OEM relationships for hyperscale buyers and systems integrators for government and utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Optical Encryption Market functions as a stable compounder anchored by infrastructure refresh cycles that embed physical-layer security as non-discretionary spend. Regulatory mandates across data sovereignty frameworks ensure replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anchor defensive positioning through captive silicon photonics foundry relationships that insulate margin structure against commoditized transceiver imports from Chinese competitors. Prioritize FIPS 140-2 and Common Criteria pre-certification investments that extend switching costs for government and financial verticals. Consolidate submarine cable retrofit expertise through targeted engineering hires in Portugal and Singapore landing station markets.
For New Entrants and Emerging Players: Cloud-native key management platforms offer the lowest customer acquisition cost pathway for software-only entrants seeking bypass of hardware certification barriers. Target India's BharatNet rural fiber expansion as the most penetrable geography, where domestic sourcing requirements under PLI schemes disadvantage established foreign equipment vendors. Pursue open line system interoperability certification as the primary go-to-market angle for disaggregated procurement frameworks.
For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking vertical integration into physical-layer security for private fiber networks. Long-term viability centers on quantum-ready architecture transitions that preserve incumbent positioning through post-quantum cryptography standardization. Monitor NIST algorithm finalization announcements as the critical inflection signal for hybrid classical-quantum system procurement release.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Ciena Corporation controls chipset-to-system margins through in-house coherent DSP production. |
| Quantum Key Distribution Pilot Expansion | Switzerland's financial hubs validate satellite-to-ground QKD against harvest-now-decrypt-later threats. |
| Open API Certification | YANG model compliance enables software-defined key orchestration across multi-vendor transport layers. |
| Submarine Cable Retrofit Partnership | Aging trans-Atlantic systems create deployment windows at Portugal and Singapore landing stations. |
| Domestic Supply Chain Capture | Huawei Technologies leverages MIIT procurement guidelines for China's provincial backbone expansions. |
Research Methodology
Direct dialogue with network architects at hyperscale operators, procurement directors at submarine cable consortiums, photonic integration engineers, and regulatory compliance officers at telecom equipment vendors grounded qualitative assessment. Secondary validation drew from FCC infrastructure security filings, EU Cybersecurity Act implementation guidance, MIIT procurement bulletins, and SEC 10-K disclosures from listed optical transport vendors. Bottom-up and top-down triangulation reconciled shipment data with infrastructure investment announcements across submarine and terrestrial backbone projects.
Bottom-up modeling traced encryption engine attach rates through DWDM port shipments and coherent transceiver production volumes, while top-down analysis calibrated against aggregate carrier capex disclosure. Segmentation dimensions spanned product type, encryption technology, application vertical, end-user category, and geographic regulatory cluster. CAGRs emerged from logistic curve fitting to infrastructure replacement cycles and quantum cryptography standardization timelines. Forecast inputs incorporated hyperscaler private fiber buildout announcements and NIST post-quantum cryptography migration schedules.
Indium phosphide supply disruptions, NIST algorithm finalization delays, and silicon photonics substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding regulatory enforcement continuity and infrastructure refresh timing. A model refresh is warranted upon material change in post-quantum cryptography certification timelines or hyperscale cloud operator private fiber deployment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
User Provisioning Software Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Digital Credential Management Software Market
Security Software
Video Intercom Devices Market
Security Software
Cloud Identity and Access Management Software Market
Security Software
Global Background Screening Market
Security Software
Endpoint Detection and Response Market
Security Software
Cloud Security Software Market
Security Software
Global Cloud IAM Market
Security Software
Biometric POS Terminals Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Passwordless Authentication Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Internet Filter Software Market