
 Europe Private 5G Network Market | 2026-2036
Europe Private 5G Network Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Private 5G Network Market Insights
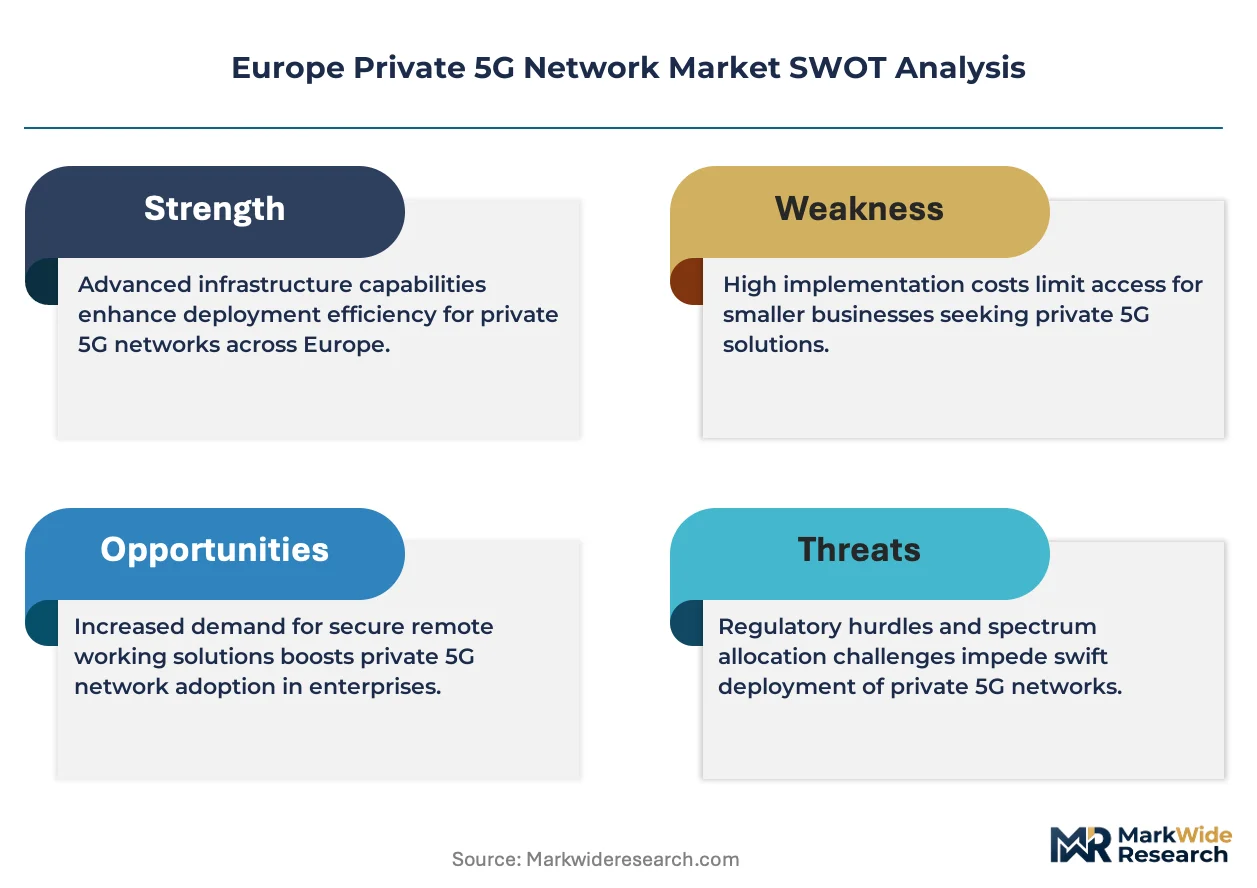
Ultra-reliable low-latency communication (URLLC) specifications is redrawing competitive boundaries in the Europe Private 5G Network landscape. Nokia Corporation leverages its radio access network heritage to anchor deployments across Nordic manufacturing zones. Siemens sustains deep vertical integration into industrial automation protocols that private 5G networks must support. Ericsson differentiates through end-to-end network slicing capabilities tailored to European regulatory environments.
Europe Private 5G Networks are dedicated cellular systems operating in licensed, shared, or unlicensed spectrum bands, typically delivering sub-10 millisecond latency and 99.999% reliability for mission-critical industrial communications. These networks replace or augment Wi-Fi and wired Ethernet in environments where mobility, density, or electromagnetic interference demands cellular-grade performance. Deployment models show on-premises installations capturing early margin pools as enterprises prioritize data sovereignty, while cloud-based orchestration layers gain traction among mid-sized manufacturers seeking operational flexibility without capital intensity. End user segmentation reveals manufacturing as the established revenue base, with transportation and healthcare applications accelerating as safety-certification pathways mature.
CE marking under the EU Radio Equipment Directive, GDPR data-localization requirements, and NIS2 cybersecurity obligations collectively shape vendor qualification timelines and enterprise procurement criteria across member states. ETSI standards for network interoperability further constrain product architectures, favoring suppliers with proven European certification track records. Stakeholders must monitor spectrum auction schedules in Germany, France, and the UK alongside evolving ENISA guidance on critical infrastructure segmentation to anticipate deployment windows and compliance costs.
Market Dynamics
Ultra-reliable low-latency communication specifications are compressing deployment timelines as German automotive manufacturers demand sub-10 millisecond performance guarantees for robotic welding and autonomous guided vehicle coordination.
Growth Catalysts
- CE marking under the EU Radio Equipment Directive:Harmonized certification pathways accelerate cross-border equipment deployment, reducing vendor qualification cycles from 18 months to under 12 months for qualified suppliers.
- Factory-floor automation in automotive:BMW, Mercedes-Benz, and Volkswagen Group facilities are mandating cellular-grade mobility for welding robots, creating immediate demand for dedicated spectrum installations.
- Network slicing:Virtualized radio resource partitioning enables single infrastructure to simultaneously support safety-critical control loops and non-critical monitoring traffic.
Market Restraints
- Licensed spectrum auction costs:Germany's Bundesnetzagentur reserves 3.7-3.8 GHz local licenses at reserve prices exceeding mid-sized manufacturer IT capital budgets.
- Radio unit supply concentration:Nordic semiconductor foundries dominate massive MIMO antenna component fabrication, exposing deployment schedules to single-source vulnerabilities.
- Wi-Fi 6E substitution:Unlicensed 6 GHz band equipment offers comparable throughput for non-mission-critical applications at one-third the infrastructure cost.
Strategic Opportunities
- Healthcare surgical robotics in France:ANSM certification pathways for latency-sensitive telesurgery are opening hospital procurement budgets previously reserved for wired fiber.
- GDPR data-localization requirements:On-premises core network deployments satisfy sovereignty mandates that public cellular cannot address, creating defensive moats for private infrastructure vendors.
- Edge AI convergence:Integration of 5G radio units with GPU-equipped edge servers enables real-time machine vision without backhaul dependency.
Industry Challenges
- OT-IT skill convergence:Industrial automation engineers lack cellular RF planning expertise, forcing system integrators to absorb training costs or hire from scarce telecom talent pools.
- NIS2 compliance timelines:ENISA guidance on critical infrastructure segmentation requires network architecture redesigns for existing pilot deployments, delaying production cutovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Private 5G Network Market |
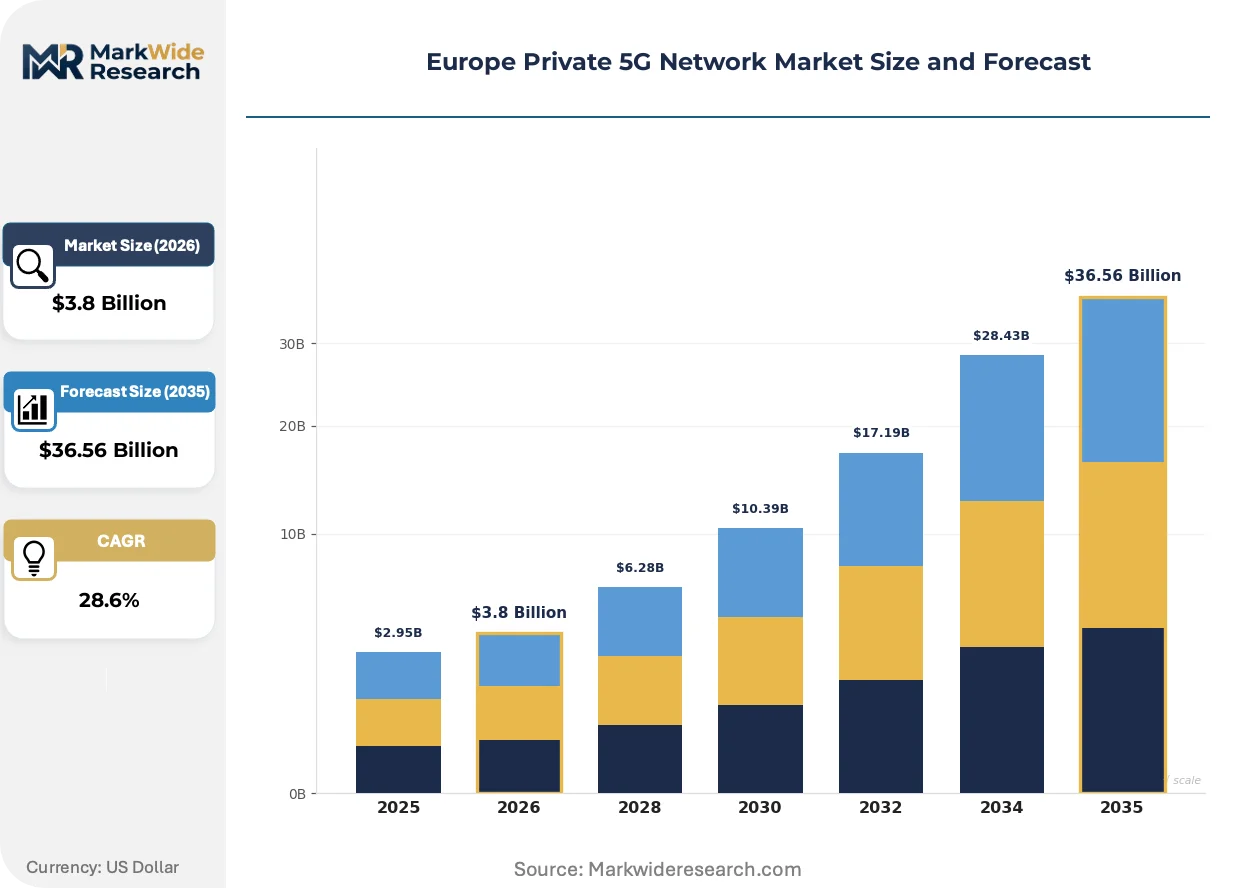
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Managed, Hybrid, Cloud-Based End User: Manufacturing, Transportation, Healthcare, Education Technology: Small Cell, Macro Cell, Radio Access Network, Core Network Application: Industrial Automation, IoT Connectivity, Smart Campus, Emergency Services |
| Companies Covered | Siemens, Huawei Technologies, Nokia Corporation, Bosch, NEC Corporation, Ericsson, Deutsche Telekom, Vodafone Group, Cisco Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Private 5G Network Market Trends and Innovations
Open radio access network architectures are fragmenting vendor lock-in patterns as European manufacturers demand interoperability guarantees in procurement specifications.
Virtualized distributed units are decomposing traditional baseband processing hierarchies. Containerized DU software permits German automotive plants to deploy compute resources on standard servers rather than proprietary hardware. This compression of the radio access stack is enabling mid-sized manufacturers to self-integrate network components without turnkey vendor dependency.
The EU's NIS2 Directive tightens incident reporting obligations for critical infrastructure operators. Network operators must now disclose significant cybersecurity events within 24 hours to national Computer Security Incident Response Teams. Private 5G deployments in French energy and German transportation sectors are accelerating security architecture investments to preempt regulatory penalties.
Enterprise buyers are consolidating vendor relationships around systems integrators capable of delivering end-to-end operational technology convergence. Manufacturing procurement teams increasingly reject radio-only suppliers, favoring partners who integrate 5G cores with programmable logic controllers and manufacturing execution systems. This preference shift is most pronounced in Nordic industrial corridors where Ericsson and Nokia maintain combined equipment and automation service capabilities.
Europe Private 5G Network Market Segmentation
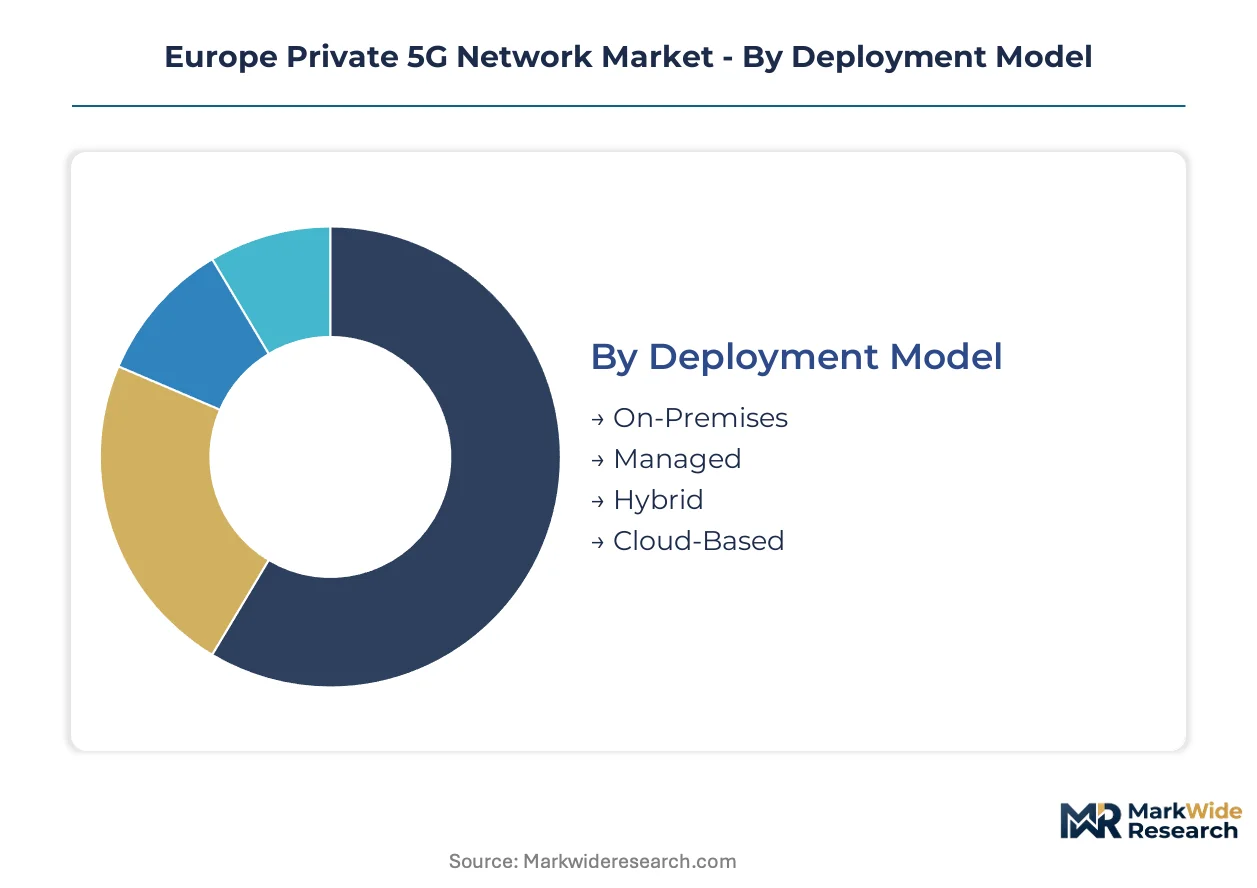
Segmentation in European private 5G networks reveals how regulatory fragmentation and vertical requirements reshape procurement patterns. Buyers across Germany, France, and Nordic industrial clusters prioritize different deployment architectures based on CE marking timelines and GDPR data-localization obligations.
Deployment Model:
GDPR data-localization requirements and NIS2 cybersecurity obligations create divergent compliance burdens across deployment architectures.
- On-Premises:Enterprises retain full control over core network hardware and subscriber data within facility boundaries. German automotive manufacturers favor this model to satisfy Bundesnetzagentur spectrum license conditions and prevent cross-border data transfers.
- Managed:Third-party operators assume operational responsibility while the enterprise retains spectrum rights. French hospital systems are adopting managed deployments to access cellular expertise without recruiting scarce RF engineers.
- Hybrid:Combines on-premises radio units with cloud-orchestrated core functions. Mid-sized manufacturers in Nordic industrial corridors deploy hybrid models to balance sovereignty requirements against capital constraints.
- Cloud-Based:Fully virtualized network functions hosted in regional data centers. Educational institutions across the Netherlands and Belgium select cloud-based options for rapid campus-wide coverage without infrastructure ownership.
On-Premises handles the majority of throughput; Cloud-Based is the fastest mover on share.
End User:
Vertical-specific latency tolerances and safety-certification pathways determine technology selection and vendor qualification intensity.
- Manufacturing:Welding robots and autonomous guided vehicles demand sub-10 millisecond latency with 99.999% reliability. BMW Group facilities in Bavaria and Volkswagen plants in Lower Saxony anchor demand for dedicated spectrum installations.
- Transportation:Port automation and rail signaling require seamless handover across large geographic footprints. Rotterdam port authorities and Hamburg Hafen are deploying private 5G to replace aging TETRA networks.
- Healthcare:Telesurgery and real-time patient monitoring impose stringent availability requirements. ANSM certification pathways in France are opening hospital procurement budgets previously reserved for wired fiber infrastructure.
- Education:Smart campus initiatives prioritize density and coverage over ultra-reliability. Technical universities in Denmark and Sweden leverage private 5G for augmented reality laboratory applications.
Manufacturing commands the largest installed base; Healthcare is climbing the fastest on procurement volume.
Technology:
ETSI interoperability standards and vendor certification track records constrain architecture choices for European deployments.
- Small Cell:Low-power radio units provide localized coverage for indoor industrial environments. German automotive paint shops and assembly lines deploy small cells to overcome electromagnetic interference from metal structures.
- Macro Cell:High-power outdoor base stations cover expansive logistics yards and port terminals. Macro installations at Rotterdam Maasvlakte and Hamburg Container Terminal enable crane automation across multi-kilometer zones.
- Radio Access Network:Open RAN architectures are fragmenting vendor lock-in patterns as European manufacturers demand interoperability guarantees. Containerized DU software permits deployment on standard servers rather than proprietary hardware.
- Core Network:Virtualized packet core functions handle authentication, billing, and policy enforcement. On-premises core deployments satisfy GDPR sovereignty mandates that public cellular cannot address.
Radio Access Network absorbs the greatest vendor attention; Core Network is gaining share fastest through virtualization.
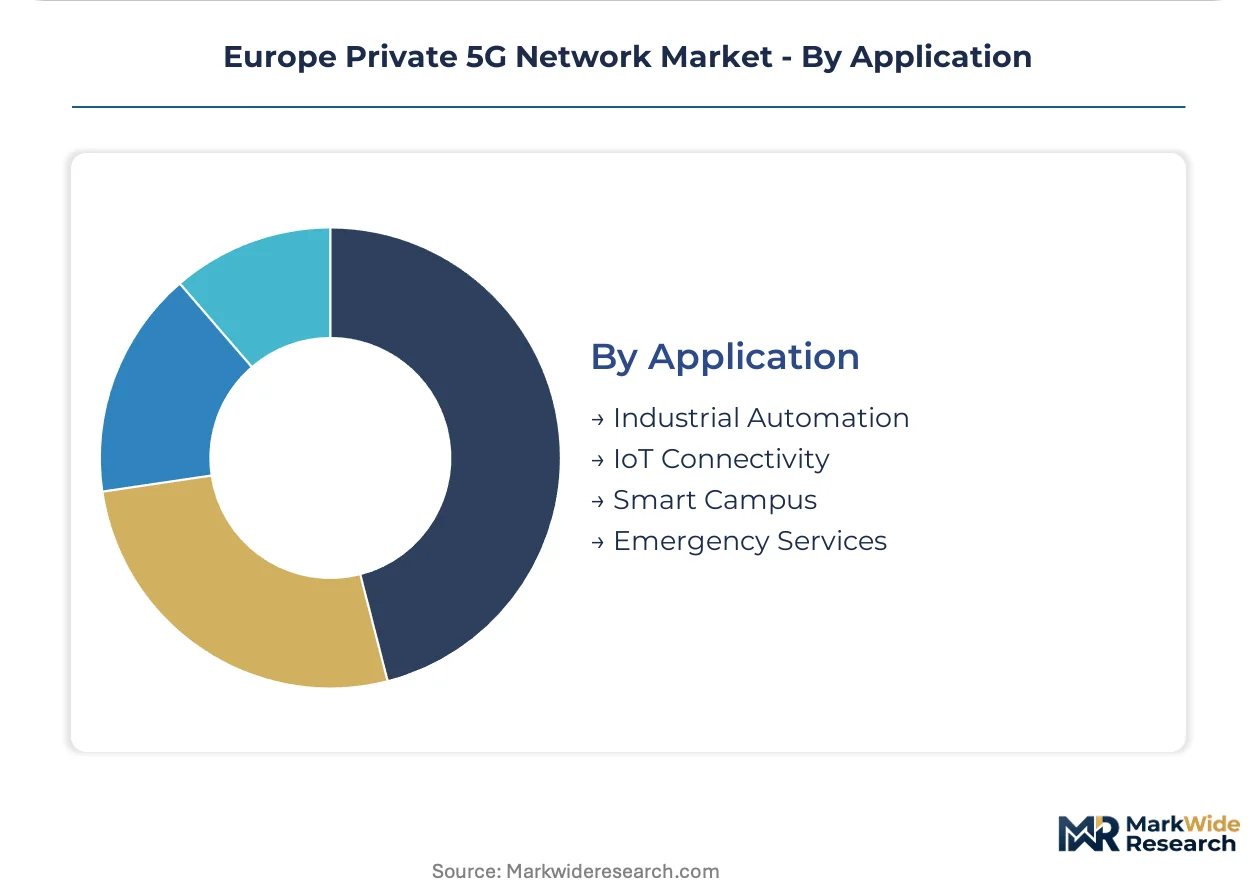
Application:
Safety-certification maturity and return-on-visibility determine deployment sequencing across use case categories.
- Industrial Automation:Robotic control loops and machine-to-machine coordination require deterministic latency. Mercedes-Benz Sindelfingen and BMW Dingolfing factories mandate cellular-grade mobility for welding robot fleets.
- IoT Connectivity:Massive sensor deployments for predictive maintenance and environmental monitoring. Nordic pulp and paper mills connect thousands of vibration sensors without Wi-Fi congestion.
- Smart Campus:Unified connectivity for buildings, vehicles, and personnel across educational and corporate facilities. Technical University of Munich deploys private 5G for autonomous shuttle services and AR-enabled maintenance training.
- Emergency Services:Mission-critical voice and data for first responders replacing legacy TETRA infrastructure. French SGP-PP and German BDBOS authorities are evaluating 5G for future public safety networks.
Industrial Automation carries the heaviest throughput load; Emergency Services is expanding most quickly on policy momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's private 5G network market exhibits strong intra-regional technology flows, with German industrial automation exports driving equipment demand into French and Nordic manufacturing facilities. Cross-border spectrum coordination remains limited, preserving national deployment fragmentation.
Germany
Bundesnetzagentur local licenses at 3.7-3.8 GHz anchor factory-floor automation demand from BMW, Mercedes-Benz, and Volkswagen. The NIS2 Directive imposes 24-hour incident reporting to national CSIRTs for critical infrastructure operators. Bavarian automotive plants in Dingolfing and Munich suburbs deploy dedicated spectrum for welding robot coordination.
France
ANSM certification pathways for telesurgery are opening hospital procurement budgets previously reserved for wired fiber infrastructure. The EU Cybersecurity Act mandates CE marking under the Radio Equipment Directive for cross-border equipment deployment. Île-de-France healthcare clusters around Paris and Lyon are piloting latency-sensitive surgical robotics networks.
United Kingdom
Ofcom's shared access framework at 3.8-4.2 GHz enables industrial deployments without exclusive spectrum auctions. Post-Brexit regulatory divergence from EU CE marking creates parallel certification burdens for equipment vendors. Port automation initiatives at Felixstowe and Liverpool are replacing aging TETRA infrastructure with private cellular.
Sweden
ETSI headquarters proximity accelerates standards-compliant product development for Nokia and Ericsson supply chains. The Swedish Post and Telecom Authority streamlined local licensing for industrial testbeds. Kista Science City and Gothenburg manufacturing corridors anchor Nordic Open RAN interoperability pilots.
Netherlands
Rotterdam port authorities deploy macro-cell coverage across Maasvlakte terminals for crane automation spanning multi-kilometer zones. GDPR data-localization requirements favor on-premises core networks over cloud-hosted alternatives. Technical universities in Eindhoven and Delft leverage private 5G for augmented reality laboratory applications.
Europe Private 5G Network Market Competitive Landscape
Listed leaders compete with private specialists across spectrum access and industrial integration capabilities. The vendor base clusters around three strategic archetypes: telecom equipment incumbents with radio access heritage, industrial automation conglomerates with OT protocol expertise, and mobile network operators seeking enterprise service expansion. Dominant competitive moves include vertical integration into manufacturing execution systems and geographic expansion through national spectrum partnerships.
Within the industrial automation tier, Siemens AG and Robert Bosch GmbH exemplify European conglomerates leveraging captive manufacturing relationships. Nokia Corporation and Ericsson AB occupy positions as Nordic telecom equipment anchors with end-to-end network slicing capabilities. Deutsche Telekom AG represents mobile operator archetypes pursuing managed service models for mid-sized manufacturers.
| Leading Market Players |
|---|
| Siemens |
| Huawei Technologies |
| Nokia Corporation |
| Bosch |
| NEC Corporation |
| Ericsson |
| Deutsche Telekom |
| Vodafone Group |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Twelve-month lead times for massive MIMO radio units compress vendor pricing power while amplifying procurement premiums for qualified suppliers holding buffer inventory across Nordic semiconductor foundries.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle end-to-end integration with manufacturing execution systems and carry CE marking pre-certification; standard tiers separate radio hardware from core software licensing. Price differentiation rests on spectrum access modality—licensed local spectrum commands 40-60% premiums over shared access deployments—and vertical integration depth of system integrators. Cost compression in economy tiers is intensifying because mid-sized manufacturers are consolidating vendor relationships around managed service providers. Hospital systems and educational institutions exhibit highest price sensitivity due to constrained capital budgets, while German automotive OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit exposure for gallium nitride substrates and advanced packaging substrates concentrates upstream vulnerability for European radio unit assemblers. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; antenna component machining centers on Germany and China. Raw material dependencies span rare earth elements for RF filtering, high-purity silicon for baseband processing, and copper alloys for thermal management. Single-source vulnerability pervades massive MIMO beamforming chipsets where Nordic foundries dominate. Distribution runs through systems integrators with OT-IT convergence capabilities rather than direct equipment sales, privileging vendors with captive industrial automation service arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability specifications are transforming this market into a platform-economics inflection where ecosystem orchestration supersedes proprietary radio heritage as the primary value capture mechanism.
For Market Incumbents: Fortify certification track records under EU Cybersecurity Act and NIS2 Directive timelines to preempt regulatory disqualification. Deepen backward integration into manufacturing execution system protocols to defend against industrial automation conglomerates expanding into private network deployment. Prioritize spectrum partnership density in France and Nordic corridors where local licensing frameworks favor established vendors with national regulatory relationships. For New Entrants and Emerging Players: ANSM fast-track certification for latency-sensitive healthcare applications opens procurement channels previously locked to wired fiber incumbents. Target French hospital clusters and Netherlands technical universities as most penetrable segments given limited existing cellular infrastructure and pressing coverage requirements. Pursue Open RAN software specialization as go-to-market angle, offering containerized distributed unit solutions that bypass proprietary hardware dependencies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-orchestrated deployment models as virtualization reduces dedicated hardware requirements. Long-term viability favors vendors with dual capability in radio access network software and industrial OT protocol integration. Acquisition target archetype: mid-sized systems integrators with proven NIS2 compliance architectures and existing manufacturing sector relationships. Signal to watch: Bundesnetzagentur spectrum auction participation rates among non-telecom industrial applicants as indicator of enterprise self-deployment appetite versus managed service preference.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | CE marking under EU Radio Equipment Directive accelerates cross-border equipment deployment timelines for qualified suppliers. |
| Spectrum Partnership Expansion | Local licensing agreements with Bundesnetzagentur and ANSM secure deployment windows in German automotive and French healthcare clusters. |
| Edge AI Convergence Development | GPU-equipped edge server integration with 5G radio units enables real-time machine vision without backhaul dependency. |
| Managed Service Model Launch | Third-party operational responsibility addresses OT-IT skill gaps among mid-sized manufacturers seeking cellular expertise. |
| Healthcare Vertical Penetration | ANSM certification pathways for telesurgery unlock hospital procurement budgets previously reserved for wired fiber infrastructure. |
Research Methodology
Desk research of ETSI standards documentation, ENISA cybersecurity guidance, and national spectrum auction records preceded structured interviews with private network deployment leads at German automotive OEMs, French hospital system CIOs, Nordic industrial corridor plant engineers, and systems integrators specializing in OT-IT convergence. Primary fieldwork combined with secondary validation against Bundesnetzagentur licensing databases, ANSM certification registries, and equipment vendor SEC disclosures. Bottom-up deployment volume estimates triangulated against top-down spectrum allocation forecasts.
Variance decomposition across deployment model, end-user vertical, technology layer, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include on-premises versus cloud-orchestrated architecture, manufacturing versus healthcare versus transportation end-use, small cell versus macro cell versus virtualized RAN technology, and national spectrum framework type. CAGRs derived from logistic diffusion curves fitted to early-adopter deployment trajectories, with inputs including industrial automation capital expenditure cycles and EU directive implementation timelines.
Decision-makers should treat outputs as directional under assumptions of stable CE marking timelines and continued NIS2 enforcement intensity; material deviation in regulatory guidance or spectrum auction schedules would warrant model refresh. Practitioners should keep alternative scenarios live as Open RAN interoperability maturation and Wi-Fi 6E substitution thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Enterprise WLAN Market
Network Technology
Low-Power WAN Market
Network Technology
Global Intelligent Network Market
Network Technology
Self-Healing Networks Market
Network Technology
Global Network Monitoring Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Gigabit Ethernet Market
Network Technology
Global Internet Transit Market
Network Technology
GCC Set-Top Box Market
Network Technology
Cloud Gateway Module Market
Network Technology
Private Network Services Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Dark Fiber Market
Network Technology
Global Network Management Market
Network Technology
Global Cloud Managed Wi-Fi Market