
 Intelligent Network Management Market | 2026-2036
Intelligent Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Network Management Market Foresight
Enterprise buyer concentration around hyperscale cloud operators is recalibrating procurement priorities across the vendor landscape. Cisco Systems leverages its installed base of routing hardware to extend software subscription attach rates. Huawei Technologies anchors significant R&D expenditure on AI-native network chips despite geopolitical headwinds. Juniper Networks differentiates through cloud-native automation platforms that compete directly with incumbent orchestration stacks.
Intelligent network management denotes the application of machine learning algorithms, software-defined control planes, and real-time telemetry ingestion to automate fault detection, capacity planning, and policy enforcement across heterogeneous infrastructure estates. These systems process streaming telemetry at sub-second intervals to trigger autonomous remediation workflows, reducing mean time to resolution in carrier-grade environments. Performance monitoring solutions occupy the largest revenue pool as legacy SNMP-based toolsets face displacement, while cloud-based deployment models represent the fastest-expanding configuration as enterprises abandon capital-intensive on-premises network operations centers. Security management functionality commands premium pricing due to converged cyber-physical threat surfaces in critical infrastructure.
The FCC enforces network reliability and outage reporting standards that compel US carriers to invest in predictive analytics infrastructure. ETSI NFV specifications and the EU AI Act create dual compliance burdens for European operators deploying autonomous decision-making systems. Stakeholders must evaluate whether their current vendor roadmaps align with emerging requirements for explainable AI in network automation and cross-border data governance frameworks.
Market Dynamics
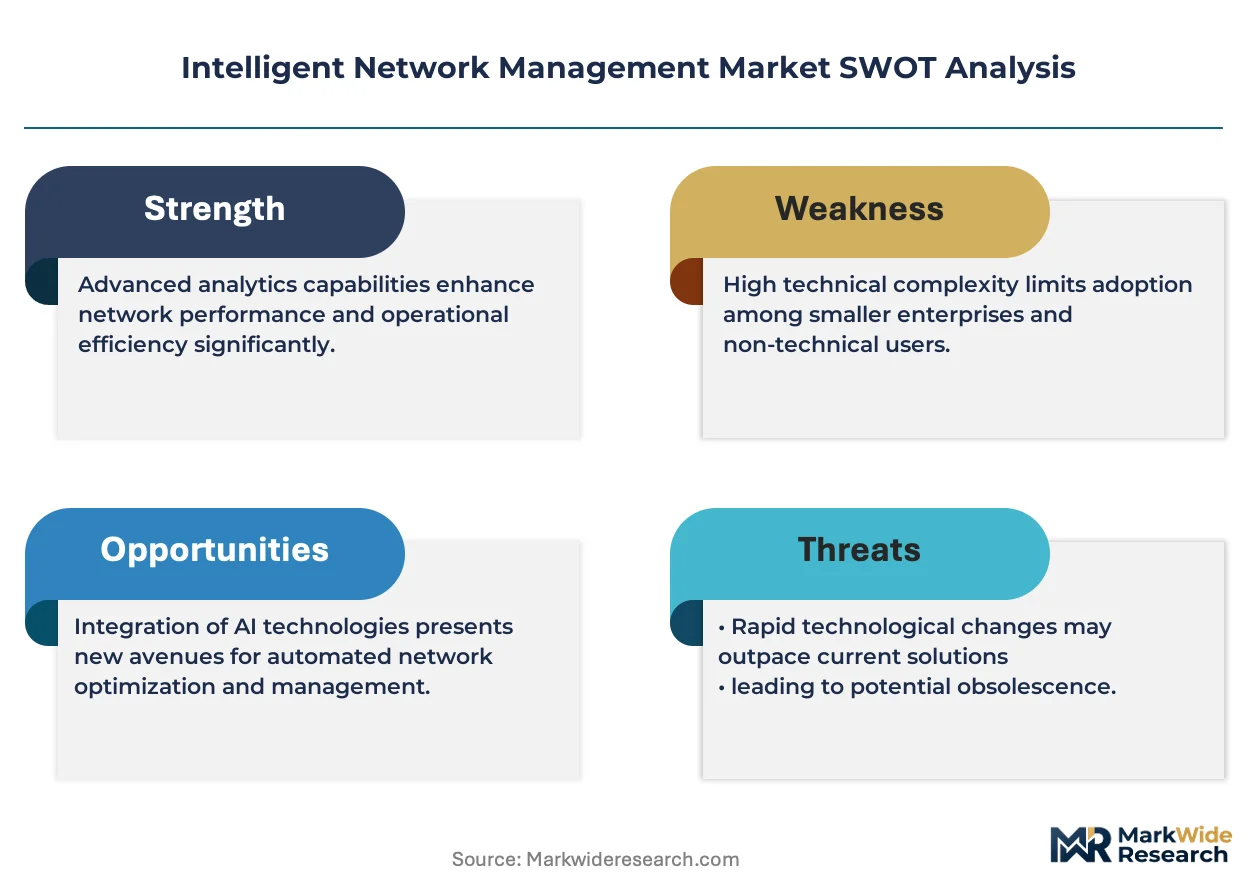
Telecom carriers face simultaneous pressure from the EU AI Act's explainability mandates and the FCC's network reliability enforcement, forcing infrastructure teams to rebuild automation stacks around auditable decision pathways rather than black-box optimization.
Growth Catalysts
- 5G Standalone Core Deployments:Mobile operators in Germany and Japan are migrating control plane functions to containerized architectures that require AI-driven orchestration for dynamic network slicing.
- EU AI Act Compliance Deadlines:European operators must retrofit autonomous remediation systems with human-in-the-loop overrides, creating replacement demand for explainable automation platforms.
- Critical Infrastructure Cyber-Physical Convergence:Energy utilities and transportation authorities in the United States are converging OT and IT monitoring under unified AI-native management consoles.
Market Restraints
- Silicon Supply Concentration:AI-native network processing chips depend on advanced foundry capacity concentrated in Taiwan, exposing equipment vendors to geopolitical disruption risk.
- Specialized Talent Scarcity:The intersection of carrier-grade networking and machine learning engineering remains severely under-supplied, inflating implementation timelines.
- Legacy Protocol Entrenchment:Decades of SNMP and CLI-based operational procedures create institutional resistance to telemetry-driven automation in incumbent carriers.
Strategic Opportunities
- Edge Computing Infrastructure:Distributed AI inference at cell tower sites and factory floors in India creates demand for lightweight, autonomous network management agents.
- Japan's Beyond 5G Initiative:METI funding for 6G research prioritizes self-evolving network architectures, opening procurement channels for predictive analytics vendors.
- API-First Integration:Cloud-native orchestration platforms that expose modular REST interfaces are capturing share from monolithic legacy systems in enterprise data centers.
Industry Challenges
- Cross-Domain Certification Complexity:Vendors must simultaneously satisfy ETSI NFV specifications, 3GPP release timelines, and national cybersecurity frameworks for each deployment.
- Observability Data Overload:Sub-second telemetry streams from millions of network elements exceed storage and query capacity of conventional data lakes, requiring architectural reinvention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Network Management Market |
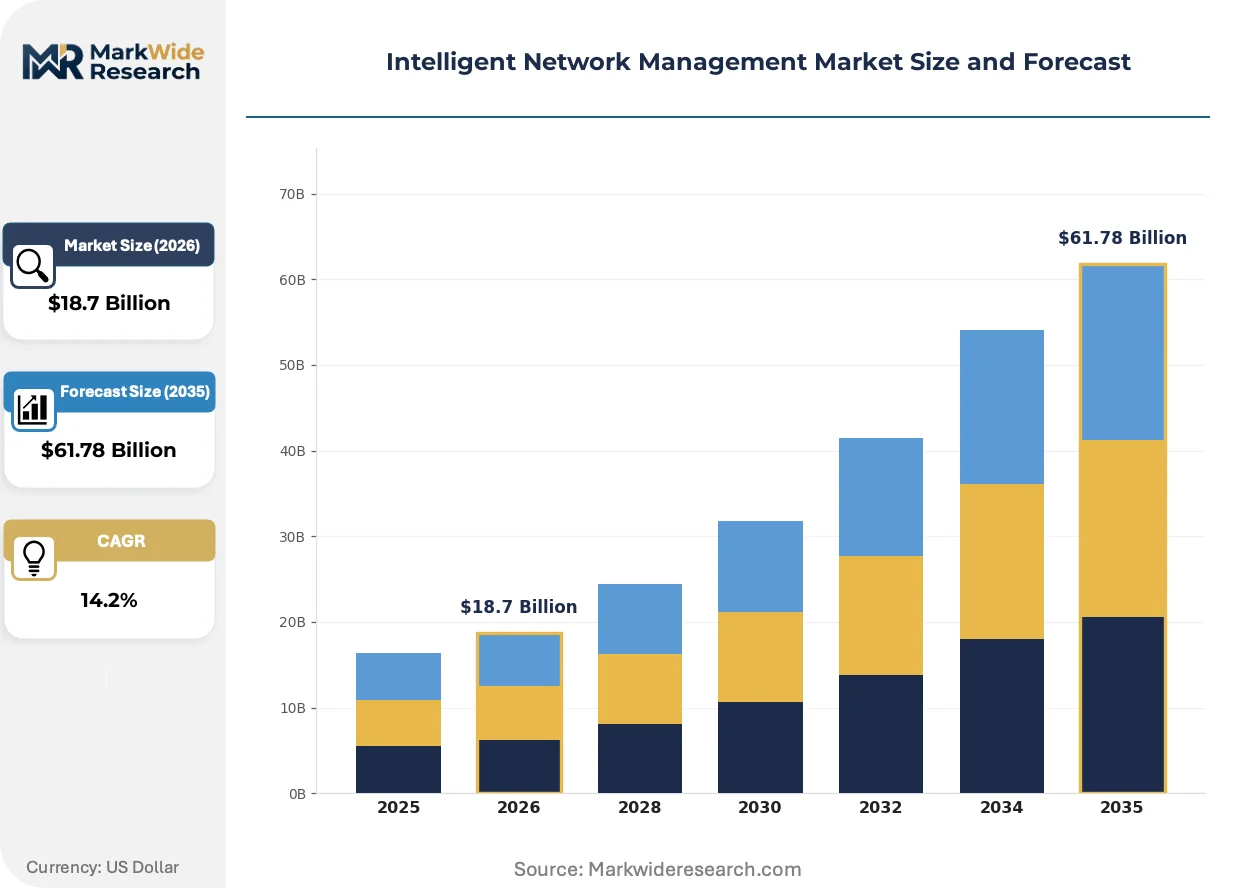
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Performance Monitoring, Configuration Management, Fault Management, Security Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecom Providers, IT Enterprises, Government Agencies, Healthcare Organizations Technology: AI-Driven Analytics, SDN, NFV, IoT Integration |
| Companies Covered | Cisco Systems, Inc., Huawei Technologies Co., Ltd., Juniper Networks, Inc., Nokia Corporation, Telefonaktiebolaget LM Ericsson, Hewlett Packard Enterprise, Ciena Corporation, Sandvine, Netcracker Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Network Management Market Shifts & Advancements
Intent-based networking is dissolving the boundary between configuration management and automated assurance, compressing the traditional three-tier operational stack into unified control planes that interpret business objectives directly.
Distributed AI inference engines deployed at network edge nodes are unifying traffic engineering, security policy enforcement, and fault prediction into single silicon substrates. Tier-1 carriers in South Korea and the United States are piloting these converged platforms for metro access networks. This compression eliminates the latency and synchronization overhead of centralized cloud controllers.
The EU AI Act's risk classification framework for autonomous infrastructure systems is mandating algorithmic audit trails and human oversight interfaces. European operators must now document training data provenance and decision logic for network automation exceeding defined criticality thresholds. German carriers are responding by procuring only platforms with built-in explainability modules.
Enterprise buyers are consolidating vendor relationships around full-stack automation providers rather than assembling point solutions. Network operations teams at financial services and healthcare institutions in the United States now require unified consoles spanning campus, WAN, and cloud connectivity. This preference shift disadvantages specialized performance monitoring vendors lacking orchestration depth.
Intelligent Network Management Market Segmentation
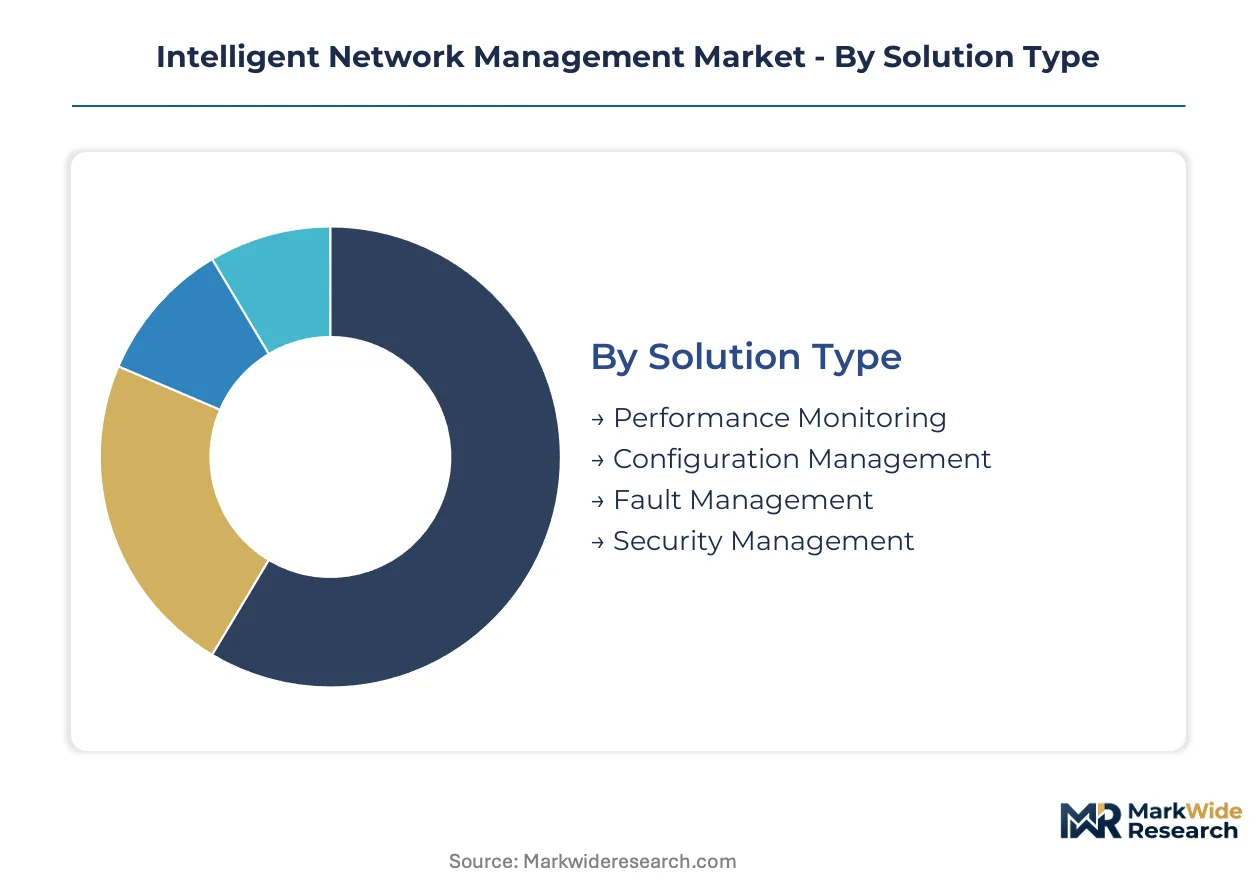
Intelligent network management vendors must align solution architectures with divergent operational maturity levels across buyer segments. Deployment constraints and regulatory mandates fragment procurement patterns, creating distinct competitive arenas within each category.
Solution Type:
Supply concentration in telemetry processing silicon shapes which functional modules carriers can deploy at scale.
- Performance Monitoring:Streaming analytics engines ingest sub-second telemetry from millions of network elements to detect latency anomalies and throughput degradation. German mobile operators migrating to 5G Standalone Core architectures drive replacement demand as legacy SNMP toolsets face displacement.
- Security Management:Converged cyber-physical threat detection unifies firewall policy orchestration with OT intrusion prevention for critical infrastructure operators. United States energy utilities facing FERC reliability mandates absorb premium pricing for these integrated platforms.
- Configuration Management:Intent-based translation layers convert business policies into device-level configurations across multi-vendor estates.
- Fault Management:Autonomous remediation workflows trigger root cause analysis and ticket generation without human intervention.
Performance Monitoring absorbs the bulk of installed capacity; Security Management is expanding most quickly.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational expenditure models favored by cloud-native enterprises.
- Cloud-Based:SaaS-delivered orchestration platforms eliminate data center footprint while enabling elastic scaling for seasonal traffic patterns. Japanese financial institutions modernizing WAN infrastructure favor these configurations to avoid network operations center capital expenditure.
- Hybrid:Split-plane architectures retain sensitive control functions on-premises while pushing analytics workloads to public cloud. United States healthcare organizations navigating HIPAA data residency requirements concentrate demand here.
- On-Premises:Fully captive infrastructure satisfies national security constraints for classified government networks.
- Managed Services:Outsourced network operations center functions transfer operational risk to specialized service providers.
Hybrid deployments dominate current procurement volumes; Cloud-Based configurations are gaining share fastest.
End User:
Customer type determines compliance burden complexity and acceptable vendor consolidation depth.
- Telecom Providers:Carrier-grade reliability requirements demand sub-50 millisecond fault detection with 99.999% availability guarantees. Tier-1 mobile operators in South Korea and the United States drive standardization around ETSI NFV-compliant orchestration stacks.
- IT Enterprises:Campus and branch convergence requirements prioritize API-first platforms integrating with existing IT service management workflows. United States technology sector buyers consolidate procurement around full-stack automation providers.
- Government Agencies:Sovereign cloud mandates and classified network isolation constrain vendor selection to domestic suppliers.
- Healthcare Organizations:Patient data protection requirements overlay network reliability with stringent access audit capabilities.
Telecom Providers command the largest addressable spend; IT Enterprises are climbing the fastest.
Technology:
Maturity gaps between proven control plane virtualization and emerging AI inference architectures fragment implementation timelines.
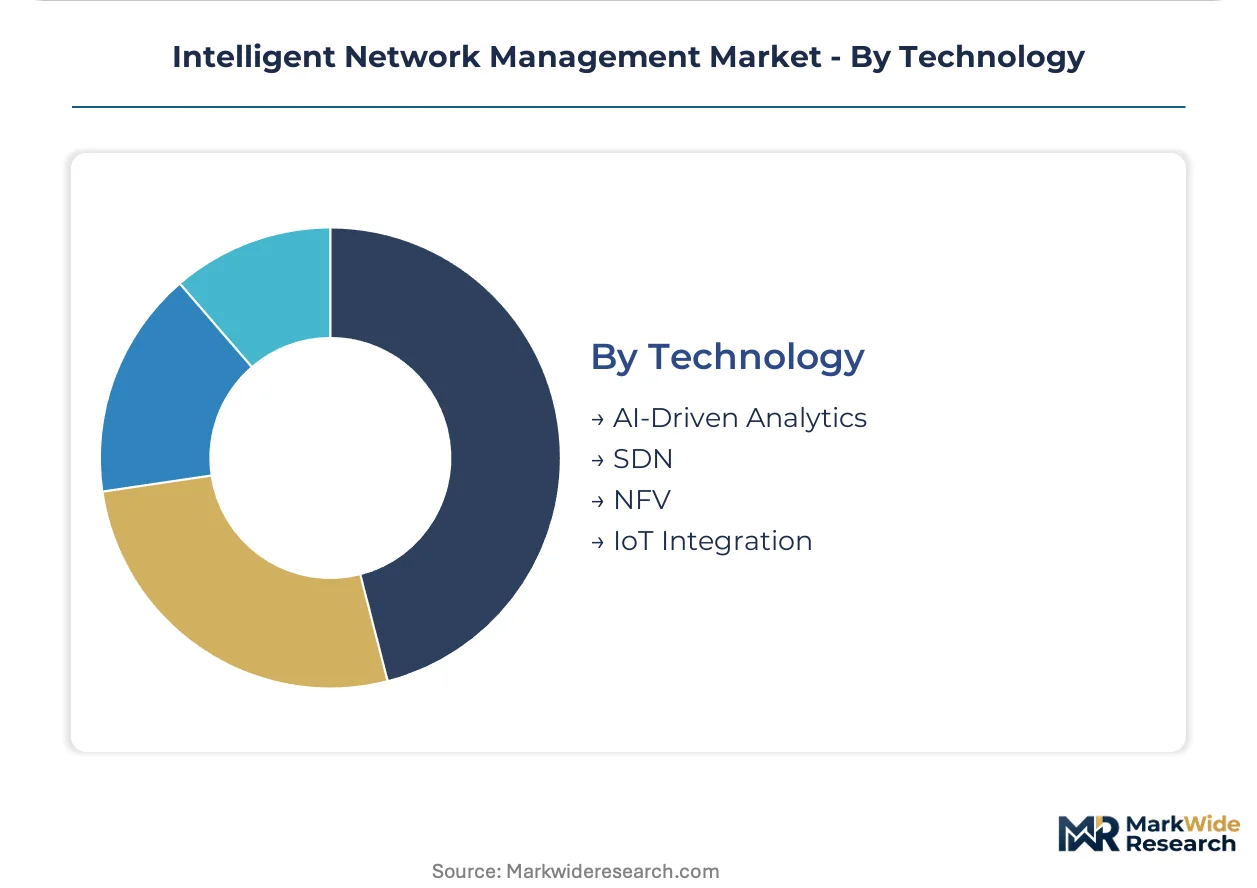
- AI-Driven Analytics:Machine learning models trained on historical fault patterns predict capacity exhaustion and security incidents before service impact. European operators retrofitting systems for EU AI Act explainability mandates create replacement demand for auditable decision pathways.
- SDN:Centralized controller architectures decouple forwarding hardware from policy logic, enabling programmatic traffic engineering across heterogeneous equipment generations.
- NFV:Virtualized network function chaining replaces purpose-built appliances with software instances running on commodity compute.
- IoT Integration:Lightweight agents extend management visibility to edge sensors and industrial controllers beyond traditional IP infrastructure.
SDN anchors the majority of deployed control planes; AI-Driven Analytics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced foundry capacity in Taiwan supplies the silicon substrates powering AI-native network processing chips deployed across carrier infrastructure worldwide.
United States
Hyperscale cloud operators and Tier-1 mobile carriers drive procurement of predictive analytics platforms for 5G Standalone Core modernization. The FCC enforces network reliability and outage reporting standards that compel carriers to invest in autonomous remediation infrastructure. Seattle and Northern Virginia host concentrated data center clusters where financial services institutions consolidate campus and WAN automation under unified consoles.
Germany
Industrial manufacturing conglomerates and automotive OEMs demand intent-based networking solutions for converged OT-IT monitoring across factory floors. The EU AI Act mandates explainable decision pathways and human-in-the-loop overrides for autonomous infrastructure systems exceeding criticality thresholds. Munich and Stuttgart anchor procurement activity as Deutsche Telekom and industrial automation leaders retrofit legacy SNMP toolsets with auditable AI platforms.
Japan
Financial institutions modernizing WAN infrastructure favor cloud-based orchestration to eliminate network operations center capital expenditure. METI funding for 6G research under the Beyond 5G Initiative prioritizes self-evolving network architectures requiring predictive analytics vendors. Tokyo and Osaka metropolitan areas concentrate deployment of distributed AI inference engines at cell tower sites for sub-millisecond traffic engineering.
South Korea
Consumer electronics conglomerates and telecommunications operators pilot converged silicon substrates unifying traffic engineering, security policy enforcement, and fault prediction for metro access networks. The national telecommunications regulator enforces carrier-grade reliability requirements demanding sub-50 millisecond fault detection with 99.999% availability guarantees. Seoul and Busan host pilot programs for edge computing infrastructure where lightweight autonomous network management agents process telemetry at factory floors.
India
Mobile network operators expanding 4G and early 5G coverage create demand for cloud-native orchestration platforms with modular REST interfaces displacing monolithic legacy systems. TRAI spectrum allocation policies and infrastructure sharing mandates accelerate procurement of software-defined control planes. Bangalore and Hyderabad technology corridors concentrate R&D activity for distributed AI inference at cell tower sites serving enterprise branch networks.
Intelligent Network Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native automation and AI-driven orchestration niches. The vendor landscape stratifies across three tiers: incumbent routing hardware suppliers extending software subscription attach rates, telecommunications equipment specialists investing in AI-native network chips, and cloud-first challengers competing directly with legacy orchestration stacks. Dominant competitive moves include strategic partnerships between silicon vendors and automation platform developers, plus geographic expansion into sovereign cloud markets constrained by data residency requirements.
Within the incumbent hardware tier, Cisco Systems, Inc. and Juniper Networks, Inc. exemplify established vendors leveraging installed base relationships to extend software-centric revenue models. Huawei Technologies Co., Ltd. occupies a position reflecting significant R&D concentration on AI-native silicon despite geopolitical headwinds affecting procurement access. Nokia Corporation and Telefonaktiebolaget LM Ericsson represent European telecommunications specialists anchoring carrier-grade reliability positioning. Hewlett Packard Enterprise and Ciena Corporation sit within the converged infrastructure segment bridging enterprise IT and carrier networking domains. Among specialized automation vendors, Sandvine and Netcracker Technology Corporation exemplify niche players targeting traffic intelligence and billing orchestration functions respectively.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Huawei Technologies Co., Ltd. |
| Juniper Networks, Inc. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Hewlett Packard Enterprise |
| Ciena Corporation |
| Sandvine |
| Netcracker Technology Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ETSI NFV-compliant orchestration stacks and uncertified automation platforms manifests in both subscription pricing and silicon sourcing strategies. Premium-tier vendors bundle human-in-the-loop audit capabilities required by the EU AI Act while routing procurement through Taiwan-based foundry relationships for AI-native network processing chips.
Pricing Analysis
Service-bundling separates subscription tiers: premium contracts embed 24/7 network operations center support and algorithmic audit trails, while economy tiers unbundle remediation workflows. Pricing stratifies across premium, standard, and economy tiers based on telemetry ingestion volume and explainability module depth. Pricing pressure stems from hyperscale cloud operators consolidating procurement around full-stack providers, compressing margins for point-solution vendors. Telecom carriers exhibit lowest price sensitivity due to carrier-grade reliability mandates; mid-market IT enterprises demonstrate highest sensitivity, favoring SaaS configurations to eliminate capital expenditure.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and the United States anchor hub-and-spoke fulfillment patterns for telemetry processing silicon and routing hardware. Advanced foundry capacity for AI-native network chips draws from Taiwan Semiconductor Manufacturing facilities, while commodity compute components source from Chinese and Vietnamese assembly operations. Single-source vulnerability concentrates in Taiwan's 3nm foundry node for high-performance network processing units. Distribution runs through carrier-direct channels for Tier-1 telecom providers and value-added resellers serving enterprise IT segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent network management sits at a technology-transition inflection as AI-driven orchestration platforms displace legacy SNMP-based toolsets and CLI-dependent operational procedures. This substitution wave recalibrates competitive positioning across vendor tiers and buyer segments.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by accelerating software subscription attach rates on installed routing hardware bases. Cisco Systems and Juniper Networks should deepen backward integration into telemetry processing silicon to reduce Taiwan foundry dependency. Certification investment in ETSI NFV compliance and EU AI Act explainability modules anchors defensive positioning against emerging automation specialists. For New Entrants and Emerging Players: Enter via API-first orchestration platforms targeting mid-market IT enterprises in the United States consolidating campus and WAN management under unified consoles. Edge computing infrastructure in India presents the most penetrable white space, where lightweight autonomous agents at cell tower sites serve factory floor networks. Channel partnerships with systems integrators specializing in HIPAA-compliant hybrid deployments accelerate enterprise traction. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by incumbent hardware vendors seeking AI-native software capabilities. Long-term viability favors vendors with demonstrated cross-domain certification spanning 3GPP release timelines, ETSI NFV specifications, and national cybersecurity frameworks. The signal to watch is procurement consolidation patterns among United States financial services institutions demanding full-stack automation spanning cloud, campus, and WAN connectivity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telemetry ingestion, orchestration, and explainability audit trails for EU AI Act compliance. |
| Strategic Partnership | Silicon vendors pairing with automation developers secure Taiwan foundry allocation for AI-native network chips. |
| Acquisition of Specialist Firm | Incumbents absorb cloud-native challengers to compress software subscription timelines and eliminate CLI dependencies. |
| Geographic Expansion | Entry into sovereign cloud markets in Germany and Japan captures data residency-constrained procurement. |
| Product Launch | Distributed AI inference engines at South Korean cell towers demonstrate sub-millisecond traffic engineering capabilities. |
Research Methodology
Independent corroboration across network operations center directors, carrier infrastructure architects, enterprise IT procurement officers, and regulatory compliance leads underwrites the qualitative findings. Primary fieldwork combined structured interviews with Tier-1 mobile operators in South Korea and the United States, secondary validation through FCC enforcement actions and ETSI specification releases, and bottom-up triangulation against hyperscaler capex disclosures and equipment vendor SEC filings.
Comparable-period anchoring to legacy SNMP deployment cycles and 5G Standalone Core migration timelines structured the forecast window across the analysis window. The analytical framework modeled segmentation dimensions including deployment model, end-user vertical, solution type, and regulatory compliance tier. CAGRs derived from equipment vendor revenue disclosures and carrier procurement patterns were stress-tested against METI funding trajectories for Japan's Beyond 5G Initiative and TRAI spectrum allocation policies in India.
Revisions become necessary when Taiwan foundry capacity constraints intensify, EU AI Act enforcement timelines accelerate, or hyperscale cloud operators pivot procurement toward captive in-house development. Forecasts reflect documented assumptions regarding 5G Standalone Core migration rates and explainability module adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Fiber to the Premises Market
Network Technology
Small Cell Networks Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
ISP Management Systems Market
Network Technology
Managed MPLS Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Mobile Backhaul Market
Network Technology
Industrial Ethernet Market
Network Technology
Network Packet Broker Market
Network Technology
North America Structured Cabling Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Network Telemetry Market
Network Technology
Wi-Fi Router Market
Network Technology
Home Wi-Fi Router and Extender Market