
 Ethernet Transceivers Market | 2026-2036
Ethernet Transceivers Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Transceivers Market Foresight
The EU F-Gas Regulation is pivoting the cost-of-entry calculus for optical transceiver vendors serving European data centers. Broadcom Inc. leverages its merchant silicon roadmap to sustain leadership in high-speed PAM4 DSP architectures. Marvell Technologies anchors its position through in-house production of coherent DSPs and custom AI interconnect silicon.
Ethernet transceivers are electro-optical modules that convert electrical signals to optical wavelengths for high-speed data transmission, typically operating at lane rates from 10 Gbps to 112 Gbps PAM4 in pluggable form factors such as QSFP-DD and OSFP. Their primary purpose is to extend reach and bandwidth density between switches, routers, and servers in congested network fabrics. Optical technology dominates the technology dimension, with coherent and direct-detect variants splitting the margin pool between long-haul and intra-data center links. Data centers represent the fastest-growing end user category, driven by AI training clusters demanding 800G and 1.6T port densities.
FCC equipment authorization rules govern electromagnetic emissions for copper and optical transceivers sold into US enterprise networks, while ECHA REACH compliance constrains substance use in European module assemblies. China's MIIT enforces domestic GB standards and dual carbon goals that shape procurement specifications for transceivers deployed in state-backed cloud infrastructure. Stakeholders must monitor whether emerging national content requirements fragment supply chain configurations for next-generation speeds.
Market Dynamics
AI training clusters are compressing upgrade cycles for optical interconnects, forcing data center operators to absorb 800G and 1.6T modules ahead of traditional depreciation schedules while suppliers scramble to scale PAM4 DSP production.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon coolants is accelerating adoption of lower-power pluggable optics in European hyperscale facilities, creating replacement demand for legacy high-thermal modules.
- China MIIT dual carbon goals:Domestic cloud providers must meet procurement specifications for energy-efficient transceivers in state-backed infrastructure, concentrating orders for 400G and 800G coherent modules with local vendors.
- Coherent DSP architectures:Advances in 7nm and 5nm digital signal processors are collapsing power-per-bit metrics, enabling 800G ZR+ deployments in metro networks previously served by direct-detect alternatives.
Market Restraints
- Indium phosphide substrate concentration:Three suppliers control the majority of high-purity InP wafer production, exposing 100G/ lane and above module makers to input cost volatility and allocation risk.
- ECHA REACH substance restrictions:Cadmium and lead limitations in European module assemblies are forcing redesigns of laser diode packaging, extending qualification timelines for new form factors.
- Copper DAC substitution:Passive direct-attach copper cables are capturing rack-scale interconnects under 3 meters, compressing addressable market for short-reach optical transceivers in AI clusters.
Strategic Opportunities
- Linear drive pluggable optics:Eliminating DSPs from module designs converges with switch ASIC roadmaps, opening white space for lower-cost 800G implementations in power-constrained data halls.
- India TRAI broadband targets:The national fiber-to-the-home push is creating demand for 10G and 25G PON optics in access networks, an underpenetrated geography for merchant transceiver vendors.
- Co-packaged optics transition:Integration of optical engines directly onto switch substrates represents a channel innovation, bypassing traditional pluggable module distribution for highest-density AI fabrics.
Industry Challenges
- 112G PAM4 signal integrity expertise:Scarce analog design talent is bottlenecking module development cycles, with lead times for qualified SerDes engineers extending beyond 18 months.
- FCC equipment authorization timelines:Electromagnetic compatibility certification for new form factors is stretching to 24 weeks, delaying revenue recognition for 800G product launches.
- Legacy QSFP28 inventory absorption:Data center operators are extending depreciation of 100G modules, creating friction in upgrade cycles and compressing pricing for intermediate 200G/400G SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Transceivers Market |
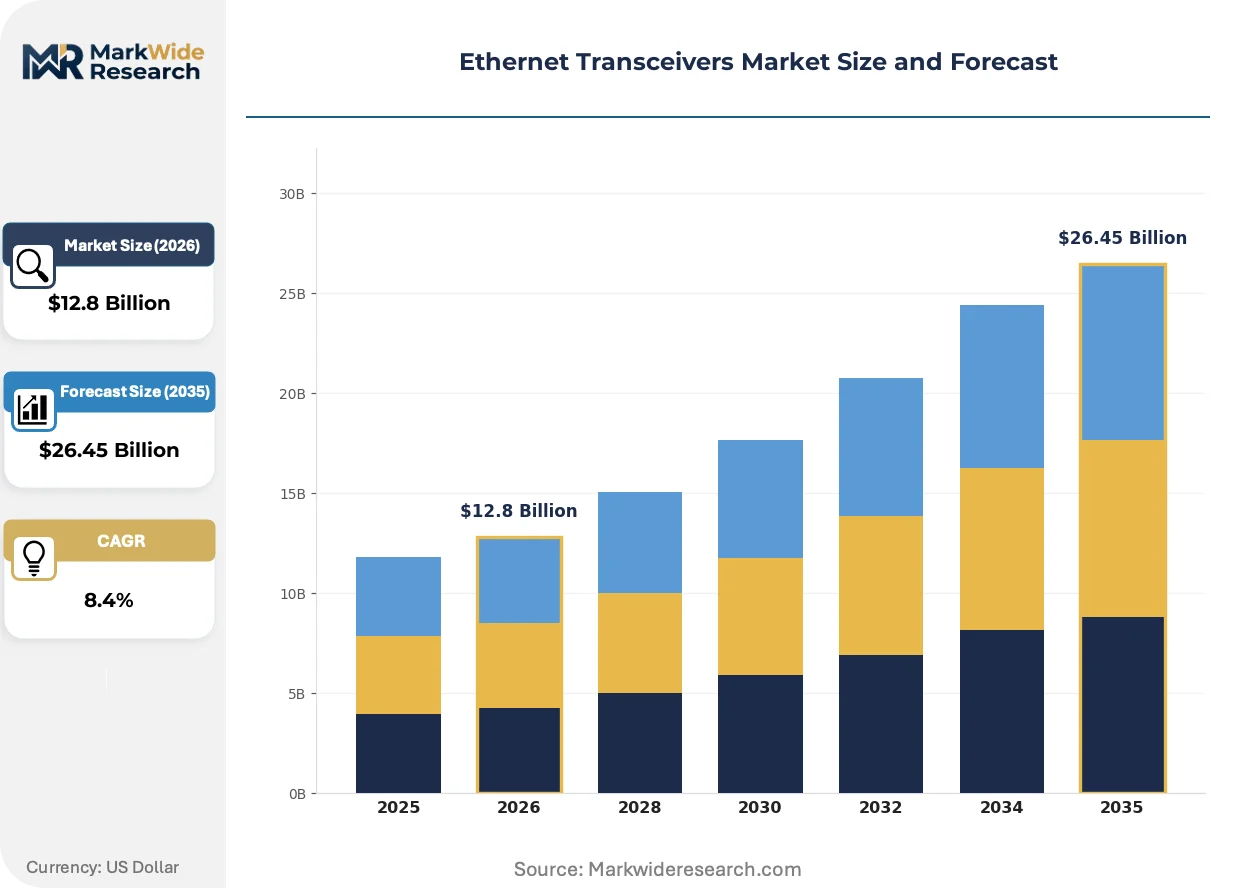
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 10G SFP+, 40G QSFP+, 100G CFP2, 25G SFP28 Technology: Optical, Copper, Active Optical Cable, BiDi End User: Data Centers, Telecommunication, Enterprise Networks, Industrial Connector Type: LC, SC, MTP/MPO, RJ45 |
| Companies Covered | Broadcom Inc., Cisco Systems, Inc., Intel Corporation, Lumentum Holdings Inc., Coherent Corp., Sumitomo Electric Industries, Ltd., Accelink Technologies Co., Ltd., Marvell Technologies, MaxLinear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Transceivers Market Shifts & Advancements
Silicon photonics is displacing discrete optical subassemblies across multiple speed classes, while regulatory pressure on embodied carbon and power consumption is rewriting procurement specifications. These forces are compressing traditional technology transitions.
Silicon photonics is automating the integration of lasers, modulators, and photodetectors onto single CMOS substrates. Hyperscale operators are adopting co-packaged and pluggable variants at 800G and 1.6T speeds to collapse cost-per-bit and thermal budgets. The technology is automating what previously required manual alignment of discrete components, enabling module makers to scale output without proportional expansion of precision assembly labor.
EU F-Gas Regulation mandates an 80% reduction in hydrofluorocarbon emissions by 2030, directly constraining cooling architectures in European data centers. Module vendors must certify power consumption thresholds to qualify for procurement shortlists, shifting R&D priority toward thermal efficiency metrics alongside bandwidth density. France, Germany, and Netherlands hyperscale projects are most affected, with operators specifying 15W maximum module power for 800G deployments.
Hyperscale self-qualification programs are displacing traditional OEM channel relationships for high-volume transceiver procurement. Meta, Google, and Microsoft are establishing direct supplier audits and custom test protocols, compressing distribution margins and favoring module makers with captive manufacturing over merchant assembly houses. This pattern is most visible in North American AI cluster buildouts, where annual volume commitments exceed 500,000 units per SKU.
Ethernet Transceivers Market Segmentation
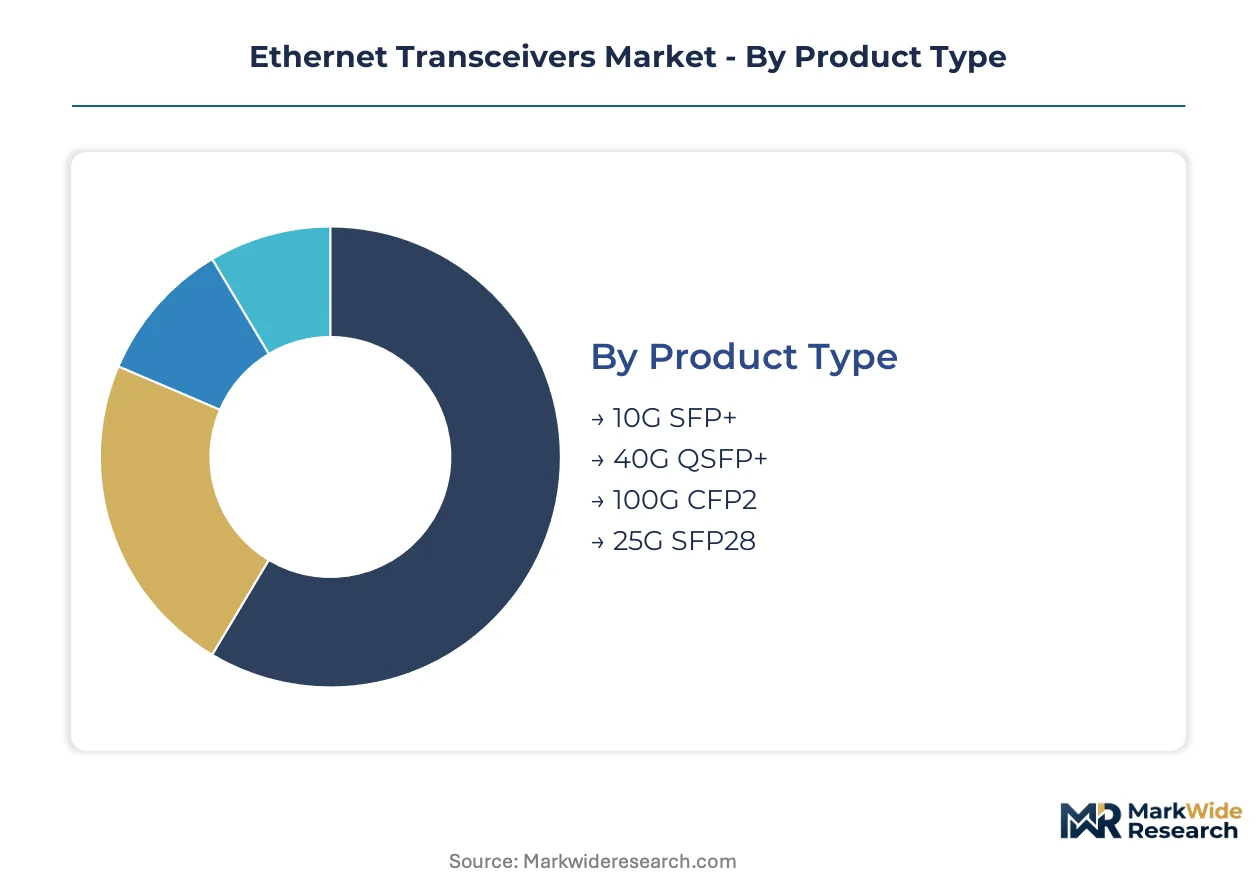
Segmentation in Ethernet transceivers reveals how procurement specifications diverge across cooling architectures, signal integrity requirements, and port density needs. Buyers select modules based on thermal budgets, reach distances, and switch ASIC compatibility rather than headline speed alone.
Product Type:
Cost tier separates legacy refresh cycles from AI-driven infrastructure builds, with hyperscale operators optimizing price-per-port differently than enterprise IT managers.
- 100G CFP2:CFP2 modules support coherent DSP architectures for metro and long-haul applications requiring 100G wavelengths over 500km. Data center interconnects between Ashburn and Chicago absorb volumes as cloud operators expand regional redundancy. FCC equipment authorization timelines stretch procurement cycles for this form factor.
- 25G SFP28:SFP28 dominates top-of-rack server connections with 25G lane rates and sub-3W power envelopes. Enterprise data centers in Germany and Netherlands specify these for 10G upgrade paths constrained by EU F-Gas cooling limits. ECHA REACH substance restrictions complicate laser diode packaging redesigns.
- 10G SFP+:Legacy form factor sustaining enterprise campus networks and industrial control systems with mature supply chains and depreciated pricing.
- 40G QSFP+:Intermediate density option bridging 10G server ports to 100G spine switches in cost-constrained facilities.
100G CFP2 leads volumes today; 25G SFP28 is gaining share fastest.
Technology:
Application environment dictates material selection—copper for rack-scale density, optical for thermal compliance, with power-per-bit as the decisive metric.
- Optical:Pluggable optics using lasers and photodetectors convert electrical signals to 850nm, 1310nm, or 1550nm wavelengths for distances beyond 10 meters. China MIIT dual carbon goals concentrate procurement for 400G and 800G coherent variants in state-backed cloud infrastructure. Indium phosphide substrate concentration exposes supply chains to allocation risk.
- Copper:Passive direct-attach cables transmit electrical signals over twinaxial copper with near-zero latency for intra-rack GPU clusters. AI training facilities in Texas and Arizona deploy DACs under 3 meters to minimize power and cost. Copper DAC substitution compresses addressable market for short-reach optical alternatives.
- Active Optical Cable:Integrated cable-assembly format eliminating separate transceiver modules for high-density storage networks.
- BiDi:Bidirectional optics using wavelength division multiplexing to double fiber capacity in fiber-constrained metro builds.
Optical technology commands the revenue pool; copper implementations are climbing the fastest in AI cluster deployments.
End User:
Volume concentration and margin structure diverge sharply between hyperscale self-qualification programs and carrier procurement cycles.
- Data Centers:Hyperscale facilities deploy 800G and 1.6T modules in AI training clusters demanding 51.2T switch capacities and liquid cooling compatibility. Meta, Google, and Microsoft establish direct supplier audits, compressing distribution margins for merchant assembly houses. Linear drive pluggable optics open white space for lower-cost 800G implementations.
- Telecommunication:Carriers specify coherent DSP modules for 5G fronthaul and metro aggregation with 15-year depreciation horizons. India TRAI broadband targets create demand for 10G and 25G PON optics in access networks. Co-packaged optics transition threatens traditional pluggable module channels.
- Enterprise Networks:Corporate IT extends QSFP28 depreciation, creating friction in upgrade cycles and compressing 200G/400G pricing.
- Industrial:Manufacturing and energy facilities require extended temperature ranges and vibration tolerance for process control networks.
Data centers dominate absolute volumes; telecommunication carriers show the steepest expansion trajectory for coherent metro deployments.
Connector Type:
Physical interface selection locks buyers into fiber infrastructure investments with decade-long depreciation schedules.
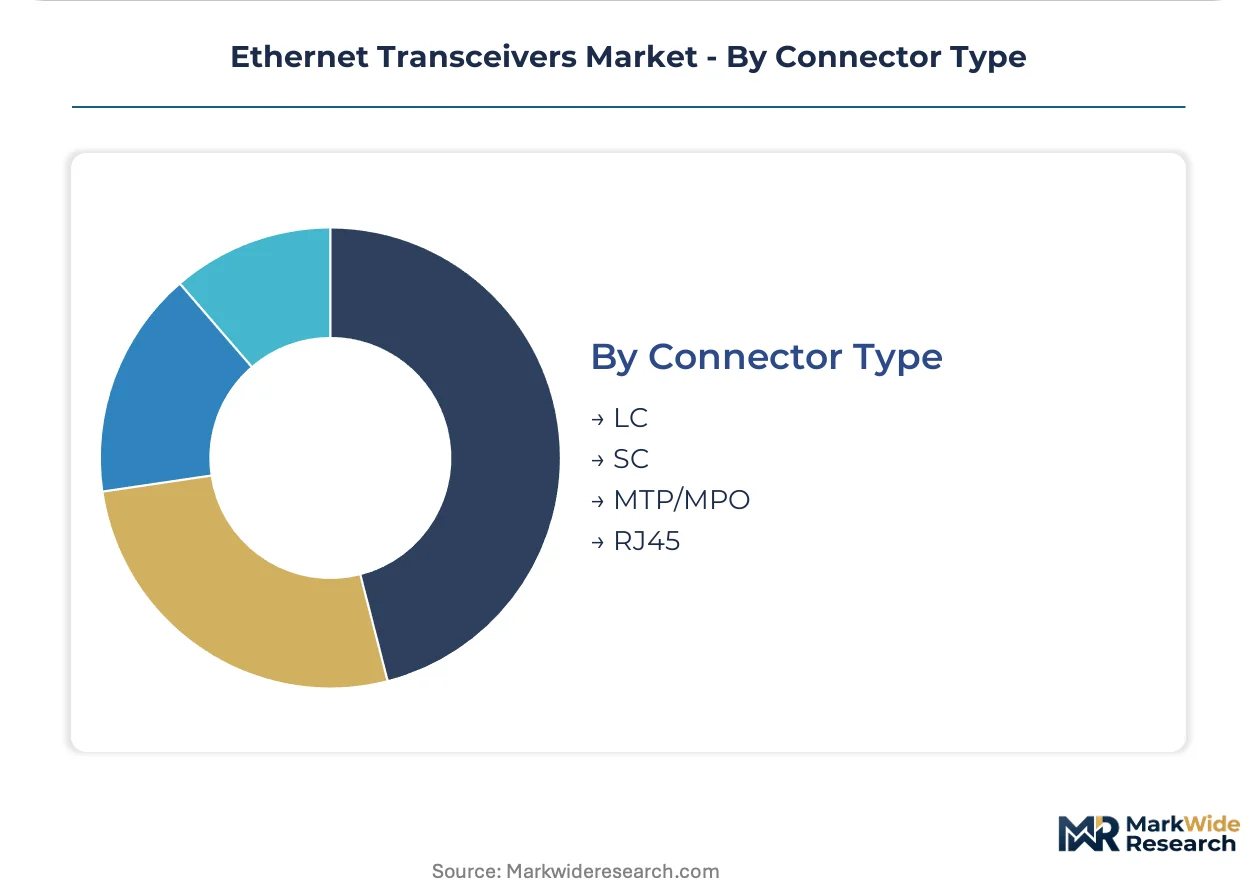
- LC:Small form-factor connector using 1.25mm ferrules for single-fiber duplex links in enterprise and telecom access networks. Japan METI efficiency standards shape procurement for low-insertion-loss variants in power-constrained facilities. Legacy single-mode infrastructure sustains demand despite density limitations.
- MTP/MPO:Multi-fiber push-on connector supporting 8, 12, or 24 fibers in a single housing for parallel optics and breakout configurations. Hyperscale data centers in Singapore and Sydney specify MTP/MPO for 400G SR8 and 800G SR8 deployments. 112G PAM4 signal integrity expertise bottlenecks qualified assembly capacity.
- SC:Subscriber connector with 2.5mm ferrule sustaining PON and legacy SONET/SDH installations.
- RJ45:Copper electrical interface for 10GBASE-T and slower speeds in campus and industrial environments.
LC connectors retain installed base dominance; MTP/MPO is expanding most quickly in parallel optics deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical design engineers and SerDes specialists concentrate in Silicon Valley, Shenzhen, and Tokyo-Yokohama corridors, anchoring regional innovation capacity for next-generation transceiver architectures.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth absorb 800G and 1.6T modules for AI training clusters exceeding 100,000 GPUs. FCC equipment authorization rules govern electromagnetic emissions certification, stretching new product timelines to 24 weeks. Meta and Google self-qualification programs in Prineville, Oregon and Papillion, Nebraska bypass traditional distribution channels for direct supplier relationships.
China
Domestic cloud providers and state-backed infrastructure buildouts concentrate orders for 400G and 800G coherent modules with local vendors. MIIT enforces GB standards and dual carbon goals that shape procurement specifications for energy-efficient transceivers in state-backed cloud infrastructure. Yangtze River Delta facilities in Suzhou and Hangzhou scale silicon photonics output for hyperscale demand.
Germany
Enterprise data centers in Frankfurt and Munich specify 25G SFP28 modules for 10G upgrade paths constrained by cooling limits. EU F-Gas Regulation mandates 80% hydrofluorocarbon reduction by 2030, forcing module power thresholds below 15W for 800G deployments. ECHA REACH substance restrictions complicate laser diode packaging redesigns for European module assemblies.
Japan
Telecom carriers specify coherent DSP modules for 5G fronthaul with extended depreciation horizons. METI efficiency standards shape procurement for low-insertion-loss LC connector variants in power-constrained facilities. Tokyo-Yokohama corridor vendors anchor precision assembly capacity for 112G PAM4 signal integrity applications.
India
National fiber-to-the-home expansion creates demand for 10G and 25G PON optics in underpenetrated access networks. TRAI broadband targets drive procurement volumes for merchant transceiver vendors entering the geography. Bangalore and Hyderabad clusters absorb module supply for domestic telecom infrastructure modernization programs.
Ethernet Transceivers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Ethernet transceivers market. Merchant silicon vendors with captive DSP architectures occupy premium positions in 800G and 1.6T speed classes, while discrete optical component suppliers defend share in coherent metro applications. Three strategic archetypes dominate: integrated semiconductor vendors controlling PAM4 DSP roadmaps, precision optical assembly houses scaling silicon photonics output, and systems OEMs with captive transceiver operations. Competitive dynamics center on backward integration into indium phosphide substrate supply and strategic partnerships with hyperscale self-qualification programs.
Among diversified semiconductor vendors, Broadcom Inc. and Marvell Technologies exemplify the integrated DSP architecture archetype, anchoring positions through merchant silicon roadmaps and in-house production capabilities. Cisco Systems, Inc. represents the systems-integrated model, leveraging captive demand from switching and routing equipment deployments. These three companies occupy distinct competitive positions: Broadcom and Marvell as merchant silicon suppliers to multiple OEMs and hyperscale operators, Cisco as a vertically integrated systems vendor capturing module value within broader networking equipment sales.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Cisco Systems, Inc. |
| Intel Corporation |
| Lumentum Holdings Inc. |
| Coherent Corp. |
| Sumitomo Electric Industries, Ltd. |
| Accelink Technologies Co., Ltd. |
| Marvell Technologies |
| MaxLinear Inc. |
| Others |
Supply & Pricing Matrix
Silicon photonics automation is collapsing assembly labor intensity while concentrating production scale in Yangtze River Delta facilities, simultaneously lowering unit economics and tightening supply control among CMOS-integrated module vendors serving hyperscale procurement programs.
Pricing Analysis
Bundled DSP-and-optics packages command premium positioning against unbundled discrete component sourcing. Three-tier pricing structure across premium coherent DSP architectures, standard PAM4 direct-detect modules, and economy-grade legacy form factors separates hyperscale direct-qualification volumes from distributor-mediated enterprise sales. Cost compression in 800G coherent tiers is intensifying because switch ASIC vendors are internalizing SerDes functions. Enterprise IT managers show highest price sensitivity, while AI cluster operators absorb premium pricing for thermal-qualified modules.
Supply Chain Analysis
Single-source vulnerability sits with indium phosphide substrate suppliers concentrated in Japan, Germany, and the United States. High-purity InP wafers, GaAs laser diodes, and advanced DSP silicon draw from geographically dispersed specialty foundries. Tariff exposure on Chinese-assembled modules threatens cost structures for North American hyperscale deployments. Distribution runs through direct supplier audits established by Meta, Google, and Microsoft, bypassing traditional OEM channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: module vendors manufacturing in China face MIIT dual carbon compliance costs while European facilities absorb EU F-Gas Regulation-driven thermal qualification expenses, creating divergent cost bases for identical speed classes.
For Market Incumbents: Deepen captive DSP architecture control to defend against merchant silicon roadmaps from Broadcom and Marvell. Secure allocation agreements with InP substrate suppliers in Japan and Germany to mitigate raw material concentration risk. Expand silicon photonics capacity in Suzhou and Hangzhou to capture China domestic cloud procurement volumes.
For New Entrants and Emerging Players: Launch via direct qualification programs with North American hyperscale operators rather than OEM distribution channels. Target India's TRAI-driven fiber-to-the-home expansion for 10G and 25G PON optics, the most penetrable geography for merchant vendors. Emphasize linear drive pluggable designs to differentiate on power consumption metrics.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision optical assembly houses without captive DSP silicon. Long-term viability across the projection horizon hinges on backward integration into coherent DSP architectures or silicon photonics foundry capacity. Watch FCC equipment authorization timeline compression as an inflection signal for 800G product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Automates laser-modulator integration for 800G and 1.6T module scaling in Yangtze River Delta facilities. |
| Direct Hyperscale Qualification Program | Bypasses OEM distribution margins by establishing custom test protocols with Meta, Google, and Microsoft procurement teams. |
| Coherent DSP Architecture Licensing | Captures value from 5G fronthaul and metro aggregation deployments requiring 15-year depreciation horizons. |
| InP Substrate Supply Agreement | Secures wafer allocation from Japanese and German suppliers to mitigate concentration risk in 100G/lane modules. |
| Linear Drive Pluggable Optics Development | Eliminates DSP power draw to qualify for EU F-Gas Regulation 15W thermal thresholds in Frankfurt and Munich data centers. |
Research Methodology
Direct dialogue with optical transceiver procurement managers at hyperscale operators, DSP architecture leads at merchant silicon vendors, and precision assembly engineers at silicon photonics foundries anchored qualitative findings. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard filings, ECHA REACH substance restriction updates, and hyperscaler capex disclosure reports. Bottom-up and top-down triangulation cross-checked module shipment estimates against switch port deployment data.
Bottom-up modeling aggregated speed-class volumes across 100G, 400G, 800G, and 1.6T form factors, while top-down analysis calibrated total addressable market against data center capital expenditure trajectories. Segmentation dimensions included connector type, cooling architecture compatibility, and switch ASIC generation alignment. CAGRs were derived from elasticity modeling of bandwidth demand against lane rate transitions, with coherent DSP penetration and copper DAC substitution rates as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT domestic content requirement expansion or FCC authorization timeline extension. Forecasts reflect assumptions on PAM4 SerDes yield curves and InP substrate supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Global Managed SD-WAN Service Market