
 Indoor Distributed Antenna Systems Market | 2026-2036
Indoor Distributed Antenna Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Distributed Antenna Systems Market Analytics
China is fragmenting as local manufacturers expand production of 5G NR-compatible active DAS equipment for domestic smart city programs. CommScope leverages its fiber optic backbone portfolio to dominate North American stadium and arena deployments. Corning Incorporated sustains technology leadership through its proprietary optical cabling systems that reduce signal loss in high-density venues. JMA Wireless specializes in software-defined DAS platforms that allow remote configuration of multi-carrier environments.
Indoor Distributed Antenna Systems comprise networks of spatially separated antenna nodes connected to a common source through coaxial cable, fiber optic, or Ethernet transport to provide uniform wireless coverage inside structures where outdoor signals cannot penetrate effectively. Active DAS solutions deploy remote radio units with powered amplification to maintain signal integrity across large footprints exceeding 500,000 square feet, while passive DAS relies on splitter and coupler architectures for smaller venues with lower capacity requirements. The solution landscape shows active DAS capturing the dominant share of new project value as 5G NR mid-band deployments require powered amplification, though hybrid configurations are gaining traction in airport terminals where legacy 4G LTE infrastructure must coexist with newer networks. Small cells represent the fastest-growing installation category for enterprises seeking dedicated capacity in isolated high-density zones without full-building infrastructure overhauls.
The FCC mandates in-building public safety radio coverage for new commercial construction above specified square footage thresholds, directly shaping procurement specifications for first responder frequency support. ETSI standards in Europe and the EU AI Act's infrastructure reliability provisions are influencing how DAS vendors certify network resilience for critical facility applications. Stakeholders must monitor spectrum auction outcomes and building code harmonization across jurisdictions to anticipate where carrier-neutral architectures will become mandatory rather than optional.
Market Dynamics
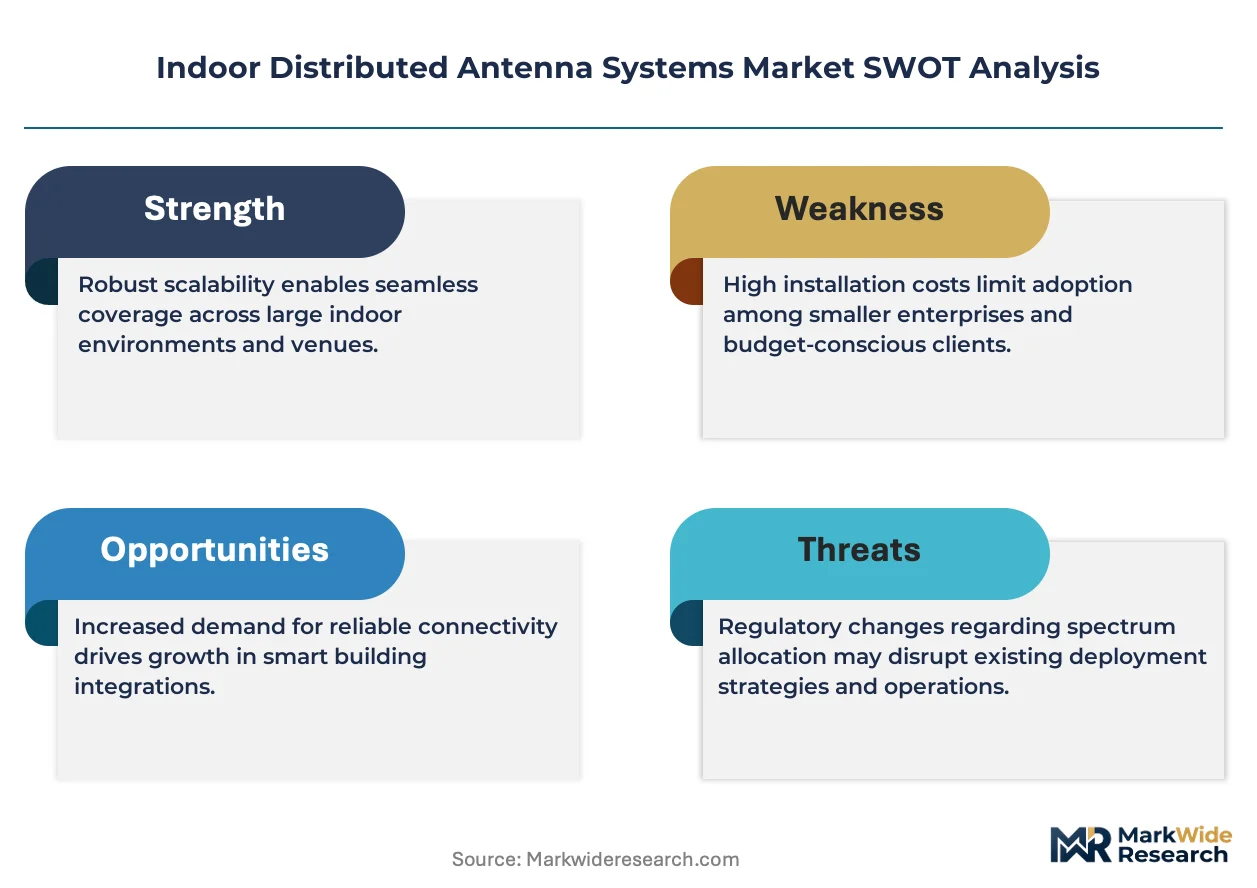
The transition from passive to active DAS architectures is compressing deployment timelines while expanding addressable venue sizes, as powered amplification eliminates signal degradation across sprawling healthcare campuses and mixed-use developments.
Growth Catalysts
- FCC public safety mandates:The FCC's in-building wireless coverage requirements for new commercial construction above specified square footage thresholds compel facility owners to install carrier-neutral DAS infrastructure supporting first responder frequencies.
- 5G NR mid-band rollouts:Healthcare facilities are accelerating infrastructure upgrades to support real-time patient monitoring and connected medical devices requiring guaranteed bandwidth.
- Smart campus densification:University and corporate campus expansions in Texas and California are driving large-scale DAS deployments to unify cellular, public safety, and private network services.
Market Restraints
- Fiber optic supply concentration:Reliance on specialized optical cabling manufacturers creates vulnerability to input cost volatility and extended lead times for high-density venue projects.
- Copper coaxial legacy entrenchment:Existing passive DAS installations in older stadiums and airports impose technical limitations on 5G NR capacity upgrades without full infrastructure replacement.
- Multi-carrier coordination friction:Negotiating access agreements with multiple mobile network operators introduces regulatory friction and extends project approval cycles.
Strategic Opportunities
- Small cell integration:Enterprises seeking dedicated capacity in isolated high-density zones without full-building overhauls represent an emerging application category with faster deployment cycles.
- Software-defined architectures:Remote configuration capabilities for multi-carrier environments enable technology convergence between DAS and private 5G networks.
- EU AI Act infrastructure reliability provisions:Certification requirements for critical facility applications create regulatory tailwind for vendors demonstrating network resilience in European healthcare and transportation hubs.
Industry Challenges
- RF engineering talent scarcity:The specialized skill set required for active DAS design and commissioning outpaces supply, extending project timelines and inflating implementation costs.
- Legacy system integration complexity:Hybrid deployments in airport terminals must reconcile aging 4G LTE infrastructure with 5G NR requirements, complicating spectrum management and power distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Distributed Antenna Systems Market |
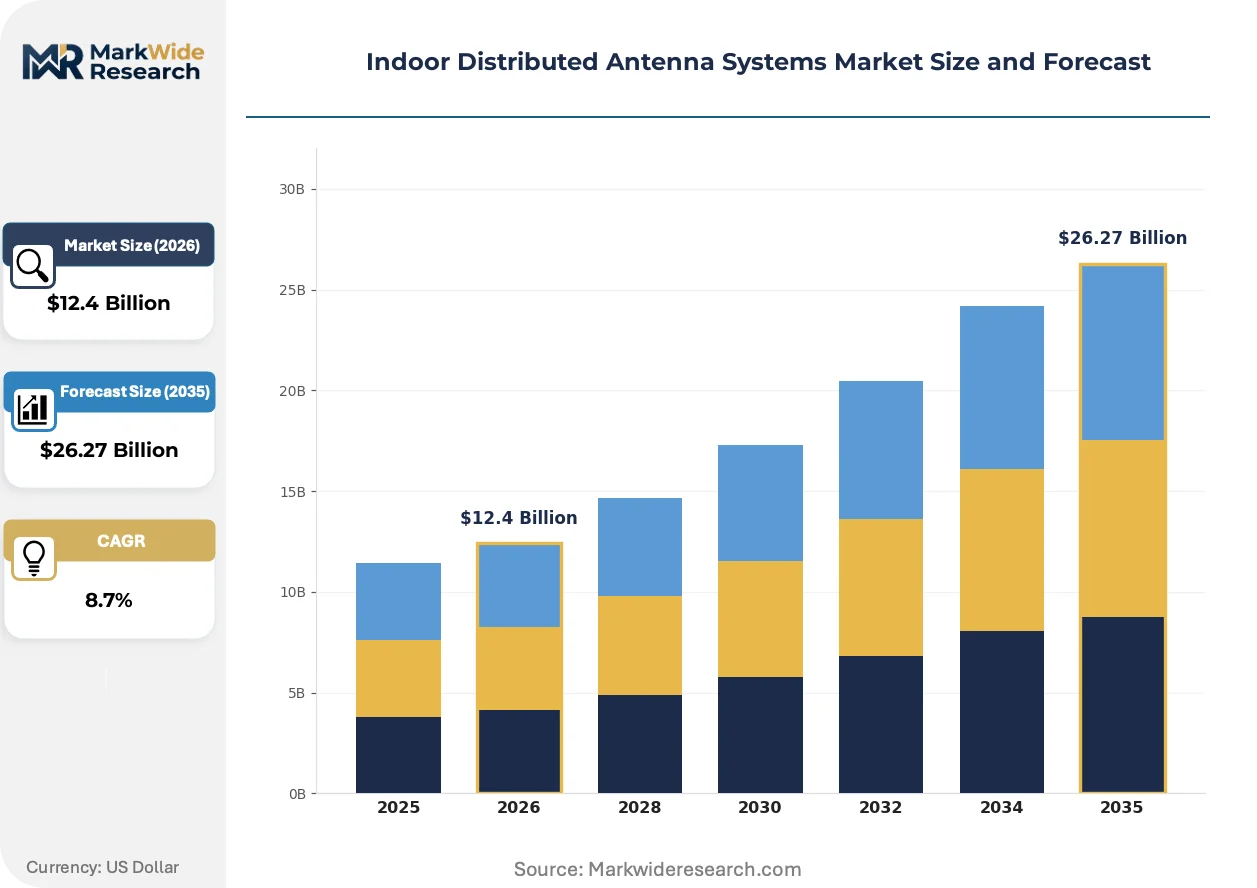
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Active DAS, Passive DAS, Hybrid DAS, Small Cells End User: Healthcare Facilities, Educational Institutions, Shopping Malls, Airports Installation: On-Premise, Off-Premise, Ceiling-Mounted, Wall-Mounted Technology: 4G LTE, 5G NR, Wi-Fi, Bluetooth |
| Companies Covered | CommScope, Corning Incorporated, American Tower Corporation, SOLiD Inc., Comba Telecom Systems Holdings Ltd., JMA Wireless, TE Connectivity, Huawei Technologies Co., Ltd., Boingo Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Distributed Antenna Systems Market Evolving Landscape
Active DAS platforms are absorbing software-defined networking principles, collapsing the distinction between fixed infrastructure and reconfigurable connectivity fabrics. This convergence is redrawing competitive boundaries between traditional hardware vendors and cloud-native network specialists.
Active DAS solutions deploy remote radio units with powered amplification to maintain signal integrity across footprints exceeding 500,000 square feet. Healthcare systems and convention centers are adopting these architectures at accelerating pace to eliminate dead zones in radiology suites and exhibition halls. The technology is hybridizing with private 5G cores, enabling venues to offer guaranteed service-level agreements for mission-critical applications.
The EU AI Act's infrastructure reliability provisions are influencing how DAS vendors certify network resilience for critical facility applications. European healthcare regulators now require documented failover capabilities for patient monitoring systems, forcing manufacturers to redesign power distribution and backup architectures. Hospital procurement teams in Germany and France are prioritizing vendors with pre-certified compliance packages, compressing vendor qualification timelines.
Enterprise buyers are unbundling DAS deployment from long-term managed service contracts, preferring capital purchase models with separate maintenance agreements. This pattern disrupts traditional carrier-led project structures and shifts negotiation leverage toward facility owners. The behavior is most visible in United States stadium renovations, where owners demand direct vendor relationships and multi-source maintenance options.
Indoor Distributed Antenna Systems Market Segmentation
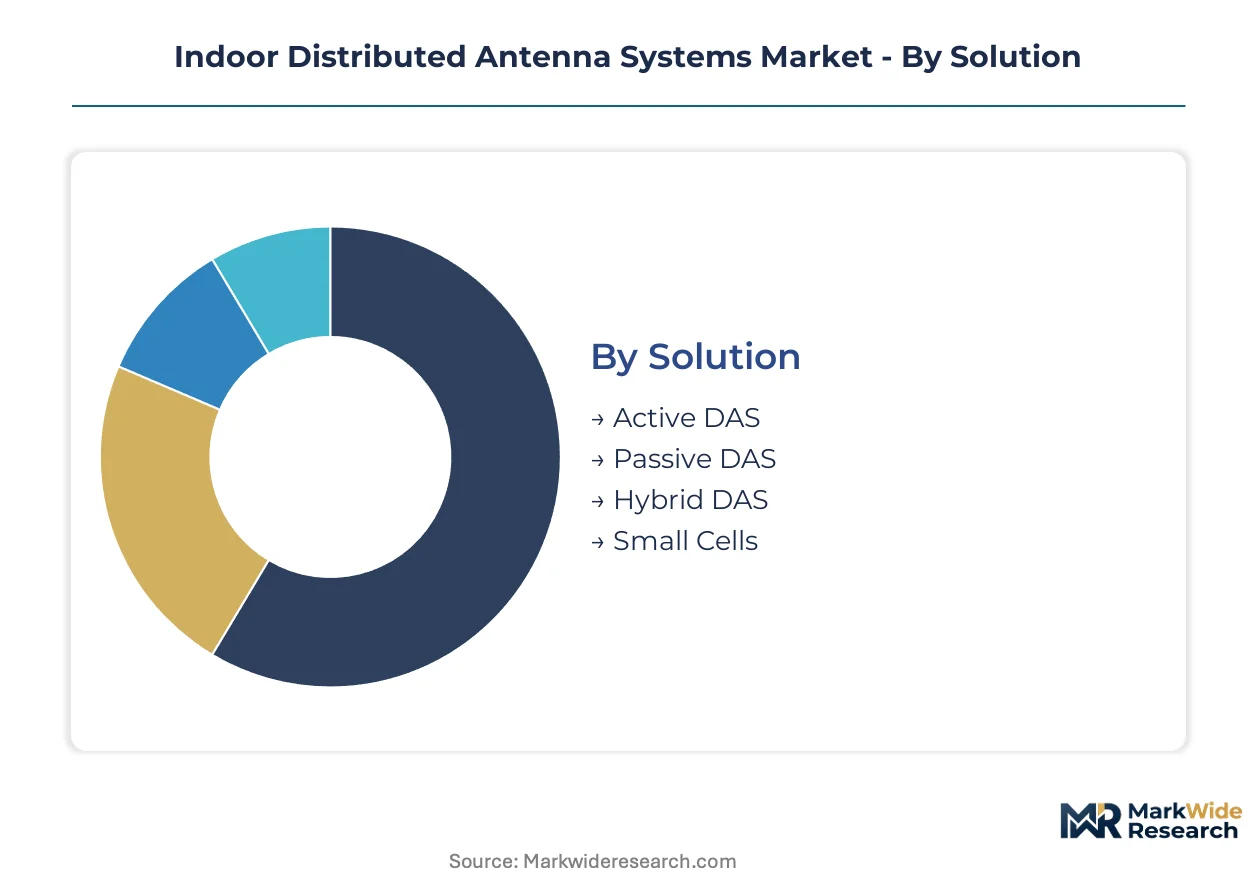
Segmentation in the Indoor Distributed Antenna Systems Market reveals how deployment complexity, venue constraints, and spectrum requirements fragment procurement behavior. Buyers select architectures based on footprint size, carrier density, and legacy infrastructure obligations rather than technology preference alone.
Solution:
Cost tier determines which architectures facility owners can deploy across varying square footage and capacity requirements.
- Active DAS:Remote radio units with powered amplification maintain signal integrity across footprints exceeding 500,000 square feet. Healthcare systems in Texas and California are accelerating adoption to eliminate dead zones in radiology suites and exhibition halls where guaranteed bandwidth supports real-time patient monitoring.
- Passive DAS:Splitter and coupler architectures without powered amplification serve smaller venues with lower capacity requirements. Existing installations in older stadiums and airports impose technical limitations on 5G NR upgrades without full infrastructure replacement.
- Hybrid DAS:Configurations blending active and passive elements reconcile legacy 4G LTE infrastructure with 5G NR requirements in airport terminals.
- Small Cells:Enterprises seeking dedicated capacity in isolated high-density zones without full-building overhauls represent an emerging application category with faster deployment cycles.
Active DAS commands the established base. The steepest expansion runs through Small Cells.
End User:
Application environment dictates RF engineering requirements, from patient safety protocols to public safety mandates.
- Healthcare Facilities:Hospitals deploy 5G-ready infrastructure for connected medical devices requiring guaranteed bandwidth and failover capabilities. FCC in-building wireless coverage mandates for public safety communications compel facility owners to upgrade legacy passive systems.
- Airports:Terminal expansions require carrier-neutral architectures supporting first responder frequencies alongside commercial cellular. Multi-carrier coordination friction introduces regulatory complexity and extends project approval cycles.
- Educational Institutions:Smart campus projects in Texas and California drive large-scale deployments unifying cellular, public safety, and private network services.
- Shopping Malls:Retail venues prioritize cost-efficient coverage for consumer connectivity and operational IoT networks.
Healthcare Facilities anchor the current installed base. Airports demonstrate the steepest climb in project value per square foot.
Installation:
Physical mounting configuration constrains cable routing, power distribution, and aesthetic integration with venue architecture.
- Ceiling-Mounted:Concealed deployments in healthcare and retail environments minimize visual disruption while maximizing coverage uniformity. Hospital procurement teams prioritize vendors with pre-certified compliance packages for overhead infrastructure.
- On-Premise:Equipment rooms and headend facilities located within building footprints reduce transport latency for mission-critical applications.
- Wall-Mounted:Surface installations serve retrofit scenarios where ceiling access is restricted by HVAC or fire suppression systems.
- Off-Premise:Centralized baseband processing in remote facilities supports campus-wide deployments across geographically distributed buildings.
Ceiling-Mounted deployments retain the dominant share. On-Premise configurations are gaining share fastest as private 5G cores require localized processing.
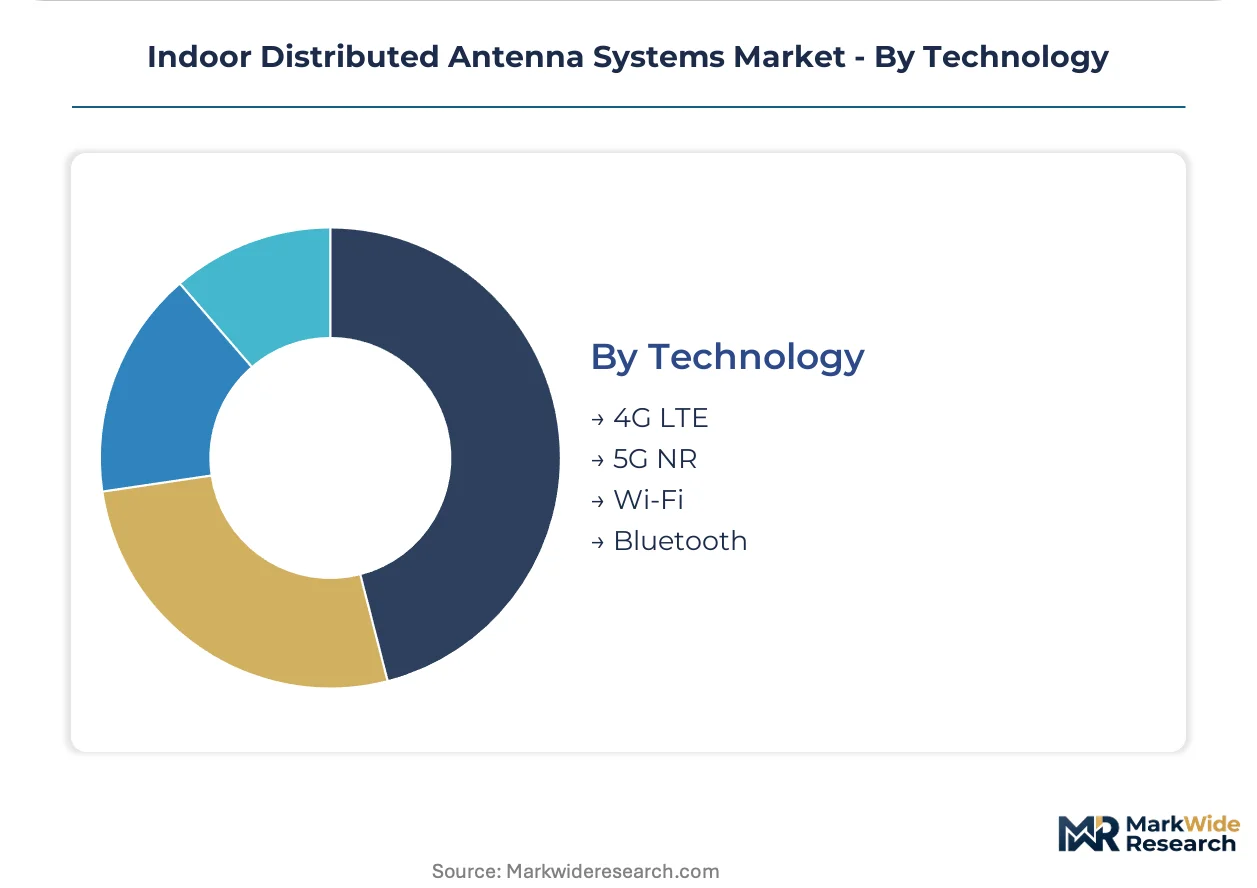
Technology:
Spectrum band selection determines hardware compatibility, carrier aggregation capabilities, and forward-upgrade paths.
- 5G NR:Mid-band deployments require powered amplification and new radio hardware. Stadium renovations and smart campus projects are driving large-scale infrastructure commitments.
- 4G LTE:Legacy installations persist in venues where carrier upgrade timelines lag facility owner procurement cycles.
- Wi-Fi:Unlicensed spectrum integration enables offload strategies and private network overlays in enterprise environments.
- Bluetooth:Low-energy protocols support indoor positioning and asset tracking applications in healthcare logistics.
4G LTE retains the installed base majority. 5G NR demonstrates the steepest expansion trajectory as mid-band rollouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized optical cabling manufacturers concentrate supply for high-density venue projects, creating vulnerability to input cost volatility. This geographic concentration pattern shapes where active DAS deployments advance fastest and where procurement teams face extended lead times.
United States
Stadium renovations and smart campus projects in Texas and California drive large-scale DAS deployments. FCC in-building wireless coverage mandates for public safety communications compel facility owners to upgrade legacy passive systems. Hospital procurement teams in Houston and Los Angeles prioritize vendors with pre-certified compliance packages for overhead infrastructure.
China
Local manufacturers expand production of 5G NR-compatible active DAS equipment for domestic smart city programs. MIIT spectrum allocation policies accelerate mid-band rollout timelines in dense urban corridors. Yangtze River Delta municipalities are deploying carrier-neutral architectures across transportation hubs and healthcare campuses.
Germany
Hospital procurement teams prioritize vendors with pre-certified compliance packages under EU AI Act infrastructure reliability provisions. ETSI standards influence how DAS vendors certify network resilience for critical facility applications. Bavarian healthcare regulators now require documented failover capabilities for patient monitoring systems in Munich and Nuremberg medical centers.
Japan
METI guidelines on private 5G spectrum allocation enable enterprise buyers to unbundle DAS deployment from carrier-managed contracts. JIS standards govern optical cabling specifications for high-density venue projects. Kanto region convention centers are adopting active DAS architectures to eliminate dead zones in exhibition halls exceeding 500,000 square feet.
United Kingdom
Enterprise buyers in London are demanding direct vendor relationships and multi-source maintenance options for stadium renovations. Ofcom spectrum auction outcomes determine where carrier-neutral architectures become mandatory rather than optional. Southeast England healthcare facilities are accelerating 5G-ready infrastructure upgrades for connected medical devices.
Indoor Distributed Antenna Systems Market Competitive Landscape
Optical backbone specialists and software-defined platform developers split the market between hardware-centric and architecture-flexible procurement preferences. The vendor base concentrates around three strategic archetypes: fiber infrastructure incumbents with stadium deployment scale, proprietary cabling innovators reducing signal loss, and software-defined specialists enabling remote multi-carrier configuration. Dominant competitive moves include strategic partnerships with mobile network operators and portfolio diversification into private 5G core integration.
Among North American infrastructure providers, CommScope and Corning Incorporated exemplify the fiber-centric archetype, while JMA Wireless occupies the software-defined tier. CommScope leverages established relationships with venue owners undergoing large-scale renovations. Corning Incorporated sustains technology positioning through specialized optical cabling systems. JMA Wireless represents the emerging convergence between fixed DAS infrastructure and reconfigurable connectivity fabrics.
| Leading Market Players |
|---|
| CommScope |
| Corning Incorporated |
| American Tower Corporation |
| SOLiD Inc. |
| Comba Telecom Systems Holdings Ltd. |
| JMA Wireless |
| TE Connectivity |
| Huawei Technologies Co., Ltd. |
| Boingo Wireless |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta manufacturing clusters anchor global capacity for 5G NR-compatible active DAS equipment, concentrating optical component supply and amplifying pricing leverage for domestic smart city programs. This geographic concentration compresses margins for Western vendors while creating tiered procurement dynamics based on certification grade and volume scale.
Pricing Analysis
FCC in-building public safety mandates dictate the pricing tier structure across the United States market, separating premium-certified active DAS from standard passive configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UL certification status, fiber optic transport quality, and after-sales service bundling. Cost compression in economy-tier passive systems is intensifying because Chinese manufacturers are expanding production of 5G NR-compatible equipment. Healthcare facilities demonstrate the least price sensitivity due to patient safety compliance requirements, while retail shopping malls anchor the most cost-conscious buyer segment.
Supply Chain Analysis
Extended payment terms from optical cabling manufacturers to DAS integrators are restructuring working capital requirements across the value chain. Production concentrates in China, South Korea, and Japan for specialized fiber optic components, remote radio units, and powered amplification hardware. Raw material dependencies include rare-earth-doped optical fiber, gallium nitride semiconductors, and high-purity copper coaxial cable. Single-source vulnerability around erbium-doped fiber amplifiers creates chokepoint exposure for large-footprint healthcare deployments. Distribution runs through carrier-neutral system integrators who bundle hardware procurement with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service contracts for remote monitoring and multi-carrier configuration represent the fastest-expanding recurring-revenue layer, outpacing hardware sales as enterprise buyers unbundle capital purchases from long-term maintenance agreements.
For Market Incumbents: Insulate market position by deepening captive supply of proprietary optical cabling systems and accelerating software-defined platform development to counter emerging cloud-native network specialists. Fiber infrastructure incumbents should defend stadium and arena relationships through direct owner contracts that bypass traditional carrier-led structures. Certification investment in EU AI Act compliance packages compresses vendor qualification timelines for European healthcare procurement teams. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where legacy passive DAS saturation remains low and 5G NR upgrade cycles are accelerating. Software-defined DAS platforms for multi-carrier remote configuration offer a differentiated go-to-market angle against hardware-centric incumbents. Small cell integration for isolated high-density zones enables faster deployment cycles with lower capital barriers than full-building active DAS overhauls. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications equipment conglomerates seeking to divest non-core in-building wireless assets. Long-term viability over the coming decade hinges on convergence between fixed DAS infrastructure and private 5G network cores. The signal to monitor is spectrum auction outcomes and building code harmonization across jurisdictions, which determine where carrier-neutral architectures become mandatory procurement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Integration | JMA Wireless and emerging vendors collapse distinctions between fixed infrastructure and reconfigurable connectivity fabrics. |
| Private 5G Core Convergence | Active DAS hybridization with private networks enables guaranteed service-level agreements for mission-critical healthcare applications. |
| EU AI Act Certification Investment | Pre-certified compliance packages compress vendor qualification timelines for German and French hospital procurement teams. |
| Direct Owner Relationship Development | Stadium renovations in Texas and California shift negotiation leverage from carriers toward facility owners demanding multi-source maintenance. |
| Small Cell Portfolio Expansion | Enterprises seeking dedicated capacity in isolated high-density zones represent faster deployment cycles than full-building infrastructure overhauls. |
Research Methodology
Initial hypotheses were tested against primary input from RF engineering directors, hospital procurement managers, stadium facility executives, and carrier network planning leads and refined through secondary validation. Primary fieldwork combined structured interviews with DAS integrators and mobile network operator infrastructure teams. Secondary sources included FCC public safety mandate filings, ETSI standard documentation, EU AI Act regulatory texts, and SEC disclosures from listed telecommunications equipment manufacturers. Bottom-up project pipeline analysis triangulated against top-down market sizing from spectrum auction data and building permit records.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling active versus passive architecture adoption, carrier-neutral versus single-carrier deployments, and ceiling-mounted versus on-premise installation preferences. Segmentation dimensions included solution type, end-user vertical, installation configuration, and technology spectrum band. CAGRs were derived from weighted average growth trajectories across these segments. Industry-specific forecast inputs incorporated MIIT spectrum allocation timelines in China and METI private 5G guidelines in Japan.
Practitioners should monitor fiber optic supply concentration, multi-carrier coordination friction, and RF engineering talent scarcity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Mobile Hotspot Router Market
Network Technology
Wi-Fi Extender Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Managed MPLS Market
Network Technology
Passive Optical Network Market
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Global Private 5G Network Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Microduct Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Wimax Solutions Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Netops Market
Network Technology
Network Management Systems (NMS) Market