
 Wi-Fi Extender Market | 2026-2036
Wi-Fi Extender Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Extender Market Analytics
Subscription-based hardware leasing is reconfiguring competitive entry barriers for Wi-Fi extender vendors. TP-Link leverages its manufacturing scale to anchor pricing power across mass-market retail channels. Netgear differentiates through premium firmware ecosystems that sustain recurring service revenue. Xiaomi competes on vertical integration into chipset sourcing, controlling cost structures that undercut traditional OEM margins.
A Wi-Fi extender is a network device that receives an existing wireless signal, amplifies it, and retransmits it on the same or different frequency band—typically operating on 2.4 GHz, 5 GHz, or 6 GHz spectra with throughput ratings from 300 Mbps to over 5 Gbps depending on the Wi-Fi generation supported—to eliminate dead zones in buildings where router coverage proves insufficient. Plug-in extenders dominate unit volume due to minimal installation friction, while Wi-Fi 6 and tri-band configurations capture expanding margin pools as latency-sensitive applications proliferate across residential and commercial deployments.
The FCC governs unlicensed spectrum allocation and transmit power limits for extenders sold in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for devices entering European markets. Japan's MIC enforces stringent electromagnetic compatibility standards that filter out lower-tier manufacturers. Stakeholders must monitor pending 6 GHz band expansion rulings and energy-efficiency labeling requirements that will reshape product development priorities and channel compliance costs.
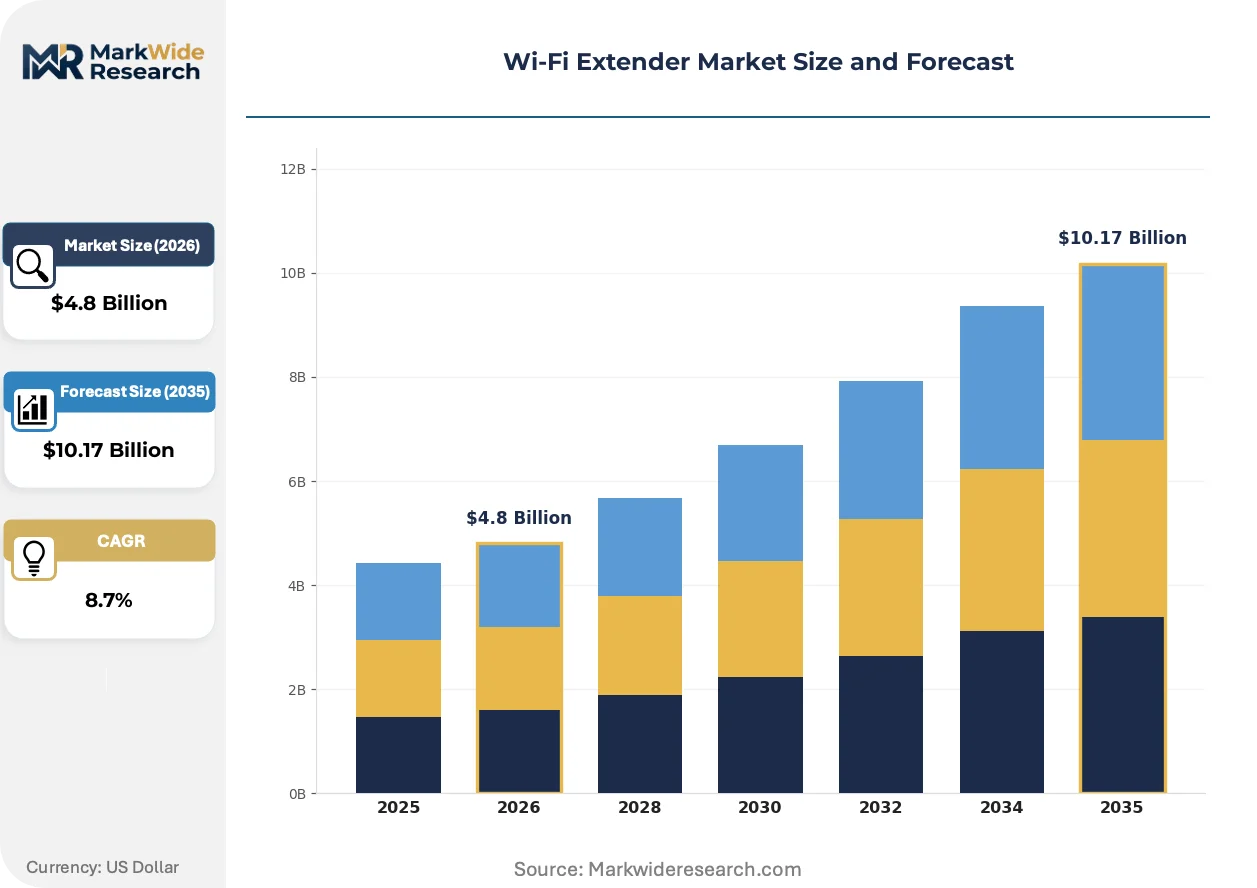
Market Dynamics
The Wi-Fi extender market is being restructured by spectrum allocation decisions that expand usable 6 GHz channels, creating immediate obsolescence risk for single-band inventory while opening margin capture for tri-band hardware architectures.
Growth Catalysts
- FCC 6 GHz Authorization:The FCC's 2020 unlicensed spectrum ruling for 6 GHz operation unlocks 1,200 MHz of contiguous bandwidth for Wi-Fi 6E extenders, enabling gigabit-plus throughput in residential deployments previously constrained by 5 GHz congestion.
- Mesh Network Protocols:IEEE 802.11k/v/r standards for seamless roaming are accelerating replacement cycles in multi-story dwellings where consumers demand single-SSID coverage without manual band steering.
- Remote Work Infrastructure:Enterprise IT procurement of residential-grade extenders for distributed workforces is creating B2B demand channels that bypass traditional retail distribution.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundry capacity constraints for Wi-Fi 6/6E system-on-chip production are extending lead times for extender OEMs and compressing margin structures at the mid-tier price point.
- Power Amplifier Cost Volatility:Gallium nitride component pricing fluctuations directly impact bill-of-materials for high-output extenders targeting outdoor or commercial range extension.
- Router-Integrated Substitution:Carrier-provided gateway hardware with built-in mesh node capability is displacing standalone extender purchases in subscriber households receiving ISP equipment bundles.
Strategic Opportunities
- India Smart City Deployment:Municipal Wi-Fi infrastructure projects in Tier-2 Indian cities present volume contracting opportunities for outdoor-rated extender hardware with IP67 environmental sealing.
- Matter Protocol Convergence:Thread border router integration within Wi-Fi extenders creates a dual-protocol hub for smart home device onboarding, capturing value from IoT ecosystem proliferation.
- EU Energy Labeling Mandate:The EU's pending standby power regulations for networked equipment will advantage vendors with optimized power architectures, creating compliance-based differentiation.
Industry Challenges
- RF Engineering Talent Scarcity:Qualified antenna design engineers capable of optimizing 6 GHz radiation patterns for compact form factors command premium compensation that strains R&D budgets at emerging vendors.
- Certification Timeline Compression:FCC Part 15 and CE RED testing cycles for multi-band transmitters extend time-to-market by 4-6 months, delaying revenue recognition against competitor launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Extender Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Plug-in Extender, Desktop Extender, Outdoor Extender, Wireless Range Booster Technology: Wi-Fi 5, Wi-Fi 6, Dual Band, Tri Band End User: Residential, Commercial, Educational Institutes, Hospitality Connection Type: Wireless, Wired, Ethernet, Powerline |
| Companies Covered | Asus, D-Link, TP-Link, Wavlink, Rockspace, Netgear, JoyLantern, Xiaomi, Linksys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Extender Market Evolving Landscape
Hardware architecture convergence is compressing the traditional separation between extenders, mesh nodes, and IoT hubs, with semiconductor integration enabling single-device substitution for previously discrete network layers.
Wi-Fi 7 chipset integration is collapsing the performance gap between extenders and wired access points. Early adopters in gaming-focused households are prioritizing 320 MHz channel bonding and 4K-QAM modulation for latency-sensitive traffic. This silicon transition is enabling margin expansion in premium hardware tiers while pressuring Wi-Fi 6 inventory liquidation.
Ofcom's 2023 consultation on 6 GHz power level increases is prompting hardware redesigns for UK market entry. Manufacturers are pre-certifying extenders for elevated EIRP limits anticipated in 2025, front-loading compliance costs. Rural broadband subsidy programs in England and Scotland are channeling procurement toward outdoor-rated extenders with directional antenna configurations.
Subscription bundling is restructuring consumer acquisition economics. Retail channels now face disintermediation as Amazon, Best Buy, and direct-to-consumer brands push hardware-plus-service packages with cloud management portals. This shift is most pronounced in North American suburban markets where consumers prioritize setup simplicity over capital expenditure minimization.
Wi-Fi Extender Market Segmentation
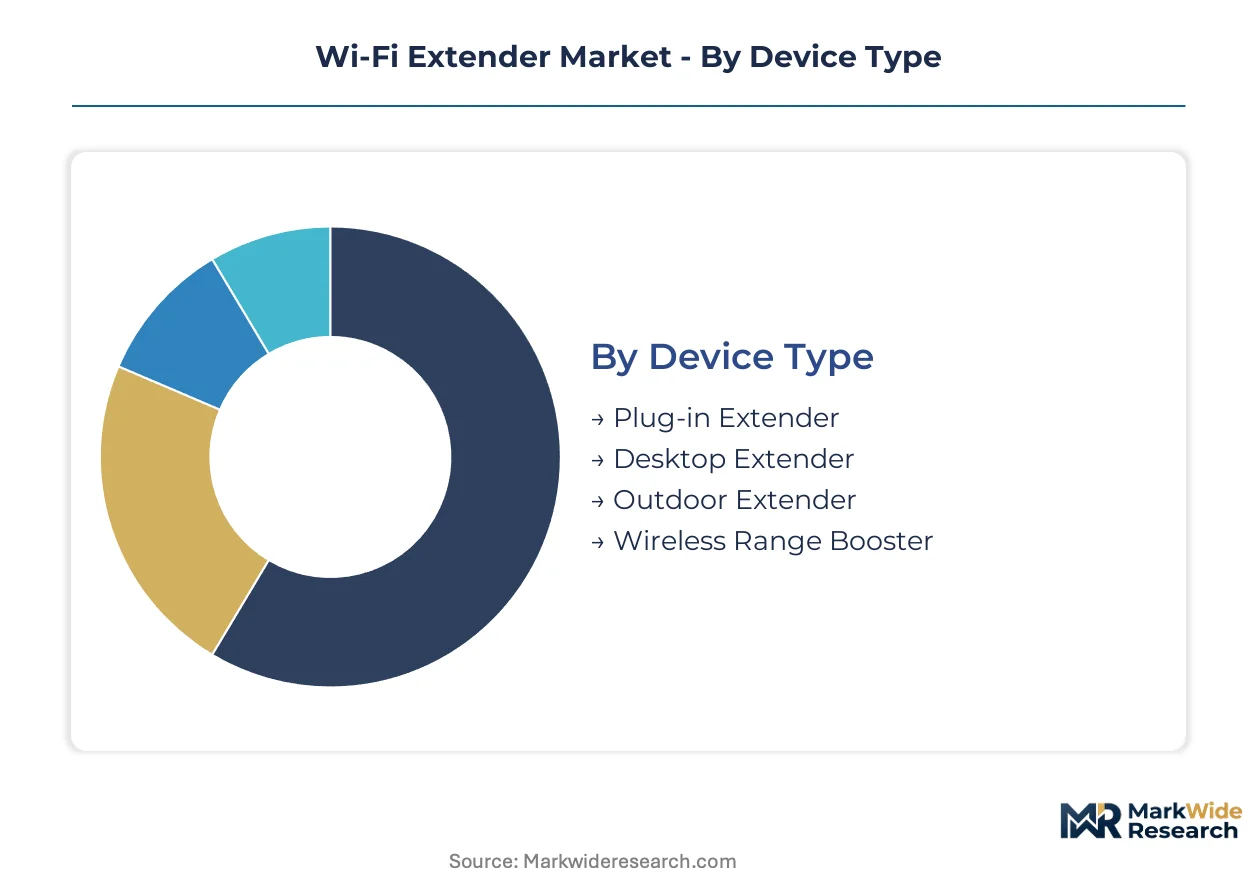
Wi-Fi extender segmentation reveals how hardware form factors, spectrum capabilities, and deployment contexts create distinct margin profiles. Vendors optimize R&D allocation across these dimensions to match procurement patterns in residential, commercial, and institutional channels.
Device Type:
Mature plug-in formats dominate unit economics while emerging outdoor architectures capture infrastructure-grade pricing premiums.
- Plug-in Extender:Compact wall-mounted units integrate directly into electrical outlets with minimal footprint. North American suburban households with aging single-band routers drive replacement cycles toward Wi-Fi 6E-capable plug-in models. FCC 6 GHz authorization unlocks bandwidth for these units previously constrained by 5 GHz congestion.
- Desktop Extender:Freestanding units with external antenna arrays deliver higher EIRP and ethernet backhaul ports. Commercial deployments in co-working spaces and small offices prioritize these for wired uplink flexibility and configurable RF patterns. Desktop units command margin premiums over plug-in equivalents through superior thermal management and amplifier output.
- Outdoor Extender:IP67-rated enclosures with directional antennas extend coverage to exterior spaces. Municipal smart city projects in Tier-2 Indian cities and rural broadband subsidy zones in England channel procurement toward these hardened configurations.
- Wireless Range Booster:Entry-level single-band repeaters target price-sensitive consumers in emerging markets with legacy 2.4 GHz infrastructure. These face accelerating obsolescence pressure from Wi-Fi 6 mesh substitution.
Plug-in extenders handle the majority of throughput; outdoor extenders are expanding most quickly on share.
Technology:
Cost tier stratification separates premium silicon from legacy inventory liquidating through discount channels.
- Wi-Fi 5:802.11ac chipsets with 80 MHz channel bonding and 256-QAM modulation remain entrenched in budget retail. Price-conscious residential buyers in markets with delayed 6 GHz regulatory approval sustain demand for these units despite Wi-Fi 6 substitution pressure.
- Wi-Fi 6:OFDMA and 1024-QAM architectures deliver 4x capacity improvement over Wi-Fi 5. Gaming-focused households and remote work infrastructure procurement prioritize these for latency-sensitive traffic. Taiwan-based foundry capacity constraints extend lead times for Wi-Fi 6 system-on-chip production.
- Dual Band:Simultaneous 2.4 GHz and 5 GHz operation with automatic band steering. Mass-market retail channels in suburban North America concentrate volume here as the default configuration for multi-device homes.
- Tri Band:Dedicated backhaul channels on 5 GHz or 6 GHz eliminate half-duplex throughput penalties. Mesh network protocols and seamless roaming requirements in multi-story dwellings accelerate adoption of these premium architectures.
Wi-Fi 6 configurations handle the majority of throughput; tri-band architectures are climbing the fastest on adoption curves.
End User:
Application context determines performance specifications, with hospitality and education imposing distinct certification and management requirements.
- Residential:Single-family homes and multi-dwelling units with consumer-managed networks. Smart home adoption and multi-device connectivity requirements in North American suburbs sustain the largest addressable volume for plug-in and mesh-style hardware.
- Commercial:Enterprise IT procurement for distributed workforces and small office deployments. These buyers prioritize cloud management portals and subscription bundling over capital expenditure minimization.
- Educational Institutes:Campus-wide coverage with centralized authentication and traffic shaping. High-density classroom and dormitory environments demand seamless roaming capabilities compliant with IEEE 802.11k/v/r standards.
- Hospitality:Hotel and resort deployments requiring guest network isolation and property management system integration. These installations favor ceiling-mounted or in-wall form factors with centralized controller compatibility.
Residential deployments handle the majority of throughput; hospitality applications are gaining share fastest as post-pandemic travel recovery accelerates property technology investment.
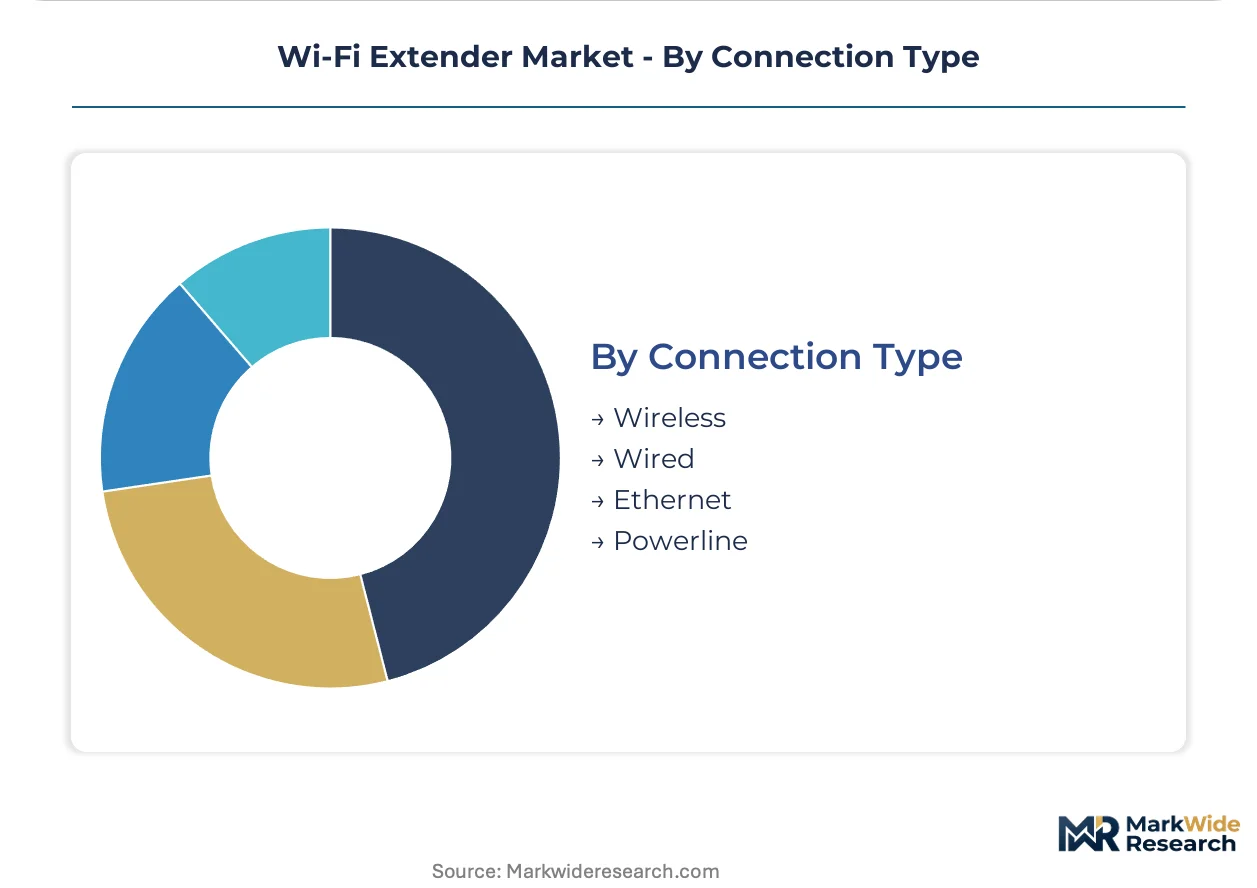
Connection Type:
Supply concentration in powerline chipset sourcing shapes cost structures for hybrid backhaul configurations.
- Wireless:Standard repeater mode receiving and retransmitting over RF links. Consumer preference for zero-cable installation sustains this as the default mode for residential plug-in units despite throughput degradation.
- Wired:Ethernet backhaul delivering full-duplex gigabit connectivity between extender and router. Commercial buyers and gaming enthusiasts prioritize these deployments for latency elimination.
- Ethernet:Physical RJ45 ports enabling local device connectivity and backhaul flexibility. Desktop extenders and outdoor units integrate multiple ports to serve as edge switches.
- Powerline:HomePlug AV2 or G.hn signaling over electrical wiring to extend network reach where Wi-Fi propagation fails. European markets with older construction and thick masonry walls maintain stronger demand for these hybrid solutions.
Wireless backhaul handles the majority of throughput; powerline connections are expanding most quickly in European retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in Wi-Fi extender hardware concentrate in East Asian manufacturing clusters, while import dependency shapes procurement patterns in North American and European retail channels. Regulatory divergence on 6 GHz spectrum authorization is fragmenting product certification requirements across jurisdictions. Suburban household density and aging router infrastructure create distinct demand profiles by country.
United States
Multi-device connectivity requirements in suburban households drive replacement cycles toward Wi-Fi 6E-capable hardware. The FCC's 2020 unlicensed spectrum ruling for 6 GHz operation unlocks contiguous bandwidth previously constrained by 5 GHz congestion. Austin and Raleigh-Durham clusters anchor enterprise IT procurement for distributed workforces.
Germany
Thick masonry construction in older housing stock sustains demand for powerline-hybrid extenders with HomePlug AV2 backhaul. The EU Radio Equipment Directive mandates CE marking and interoperability testing for devices entering European markets. Bavaria's industrial corridor concentrates procurement for commercial co-working space deployments.
China
Vertical integration into chipset sourcing controls cost structures for mass-market retail channels. The MIIT governs radio transmission equipment type approval and electromagnetic compatibility certification. Shenzhen and Dongguan manufacturing clusters dominate original equipment production for global brand licensing.
India
Municipal Wi-Fi infrastructure projects in Tier-2 cities present volume contracting opportunities for outdoor-rated hardware. The WPC (Wireless Planning and Coordination Wing) enforces equipment type approval for 2.4 GHz and 5 GHz devices. Bangalore and Hyderabad tech corridors drive residential mesh adoption among IT professional households.
United Kingdom
Rural broadband subsidy programs in England and Scotland channel procurement toward outdoor extenders with directional antenna configurations. Ofcom's 2023 consultation on 6 GHz power level increases prompts hardware redesigns for elevated EIRP limits anticipated in 2025. London commuter belt concentrations anchor premium mesh network adoption.
Wi-Fi Extender Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on semiconductor and RF engineering. The vendor base stratifies across three tiers: vertically integrated hardware OEMs with captive manufacturing, fabless design houses licensing reference architectures, and white-label assemblers serving retail private label. Two competitive moves dominate: backward integration into GaN power amplifier sourcing to control bill-of-materials volatility, and subscription bundling of cloud management portals to capture recurring service revenue.
Within the integrated OEM tier, TP-Link and Netgear exemplify divergent positioning strategies. TP-Link anchors mass-market retail channels through manufacturing scale advantages. Netgear occupies a premium position sustained by firmware ecosystem differentiation. Xiaomi represents the vertically integrated challenger archetype, leveraging in-house production of chipsets to undercut traditional OEM margin structures.
| Leading Market Players |
|---|
| Asus |
| D-Link |
| TP-Link |
| Wavlink |
| Rockspace |
| Netgear |
| JoyLantern |
| Xiaomi |
| Linksys |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shenzhen and Dongguan to Long Beach anchor landed cost dynamics for Wi-Fi extender OEMs, compressing margin structures at the mid-tier while enabling price differentiation between mass-market plug-in units and premium tri-band architectures with dedicated backhaul channels.
Pricing Analysis
Industrial OEM buyers anchor transactional pricing structures across contract manufacturing channels. Three-tier pricing stratifies across Wi-Fi 7 premium tiers, Wi-Fi 6E standard configurations, and legacy Wi-Fi 5 economy units. Price differentiation hinges on chipset certification grade and volume scale commitments. Cost compression in entry-level segments intensifies because of Taiwan foundry capacity constraints. Residential consumers in suburban North America exhibit highest price sensitivity, while enterprise IT procurement for distributed workforces prioritizes subscription bundling over capital expenditure minimization.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion for Wi-Fi 7 system-on-chip production. Supply concentrates in Taiwan, China, and South Korea for RF front-end components. Raw material dependencies include gallium nitride substrates, high-frequency laminates, and multi-layer ceramic capacitors. Single-source vulnerability around TSMC's leading-edge nodes creates procurement risk. Distribution runs through mass-market retail channels, direct-to-consumer platforms, and B2B IT procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi extender demand is accelerating through a high-growth disruption as FCC and Ofcom 6 GHz spectrum allocations unlock contiguous bandwidth for next-generation hardware, creating immediate obsolescence pressure on single-band inventory while opening margin capture for tri-band architectures.
For Market Incumbents: Harden firmware ecosystem differentiation through subscription-based cloud management portals that sustain recurring service revenue. Deepen captive supply of GaN power amplifiers to control bill-of-materials volatility against pricing fluctuations. Defend against router-integrated substitution from carrier-provided gateway hardware by embedding Thread border router capabilities for Matter protocol convergence. For New Entrants and Emerging Players: Pursue municipal Wi-Fi infrastructure contracts in Tier-2 Indian cities where outdoor-rated extenders with IP67 environmental sealing face limited established competition. Target rural broadband subsidy zones in England and Scotland where directional antenna configurations command infrastructure-grade pricing premiums. Lead with powerline-hybrid backhaul solutions in European markets with older masonry construction. For Investors and Strategic Acquirers: Carve-out targets emerge from networking divisions of diversified electronics conglomerates seeking portfolio rationalization away from commoditized consumer hardware. Five-to-ten year viability favors vendors with backward integration into chipset sourcing and established certification pipelines across FCC, CE RED, and MIC regimes. Monitor pending 6 GHz power level increases from Ofcom as inflection indicator for UK market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Amplifier Backward Integration | Captive sourcing of gallium nitride components insulates margin structures from raw material volatility. |
| Thread Border Router Integration | Matter protocol convergence positions extenders as dual-protocol hubs for smart home device onboarding. |
| Subscription Cloud Management Launch | Recurring service revenue streams disintermediate retail channels and improve customer lifetime value. |
| Outdoor-Rated Hardware Certification | IP67 sealing and directional antenna configurations unlock municipal and rural infrastructure procurement. |
| Wi-Fi 7 Chipset Platform Migration | 320 MHz channel bonding and 4K-QAM modulation capture gaming-focused household premium tiers. |
Research Methodology
Operator-level perspectives from RF engineering directors, OEM procurement managers, carrier equipment strategists, and smart home platform architects anchored the qualitative base. Primary interviews combined with secondary validation against FCC equipment authorization databases, Ofcom spectrum consultation filings, MIIT radio transmission type approvals, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Scenario-bracketing framed analytical approaches across the projection horizon. Segmentation dimensions modeled include device type, Wi-Fi generation, spectrum configuration, end-user application, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, technology transition curves, and infrastructure deployment timelines. Forecast inputs incorporated foundry capacity utilization rates and pending 6 GHz authorization rulings.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, semiconductor capital expenditure cycles, or cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions on technology adoption curves and regulatory approval timelines. Material shifts in spectrum allocation rulings, foundry capacity expansion, or carrier equipment bundling strategies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Internet Transit Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
ISP Management Systems Market
Network Technology
Global GPS Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Global Network Monitoring Market
Network Technology
Mobile Network Optimization Market
Network Technology
Global Network Management Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
North America Network Management Solutions Market
Network Technology
CPE Router Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Low-Power WAN Market
Network Technology
Network Performance Monitoring Market
Network Technology
Global Active Network Management Market
Network Technology
North America Structured Cabling Market