
 United Kingdom HR Payroll Software Market | 2026-2036
United Kingdom HR Payroll Software Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom HR Payroll Software Market Insights
The United Kingdom HR Payroll Software Market is consolidating around two distinct value layers. Enterprise-grade suites with embedded compliance engines command sustained pricing power, while stripped-back cloud tools compete aggressively on per-employee monthly fees. ADP leverages its cross-border payment infrastructure to anchor multi-country payroll contracts for British multinationals. Zellis differentiates through deep integration with UK pension schemes and statutory sick pay calculations. Sage Payroll dominates the mid-market with channel density across accounting practices nationwide.
HR payroll software automates wage calculation, tax withholding, pension contributions, and statutory reporting through rule-based engines that apply UK-specific deduction schedules and real-time information submission protocols. The primary commercial purpose is to eliminate manual errors in PAYE processing while ensuring timely filings to HM Revenue and Customs. Cloud-based deployment leads solution uptake as vendors shift from perpetual licensing to recurring SaaS revenue models with automatic legislative updates. Small and medium enterprises represent the fastest-expanding client size band as auto-enrolment duties and national living wage adjustments outstrip spreadsheet capacity. Payroll management functions capture the deepest margin pools due to compliance-critical positioning and high switching costs.
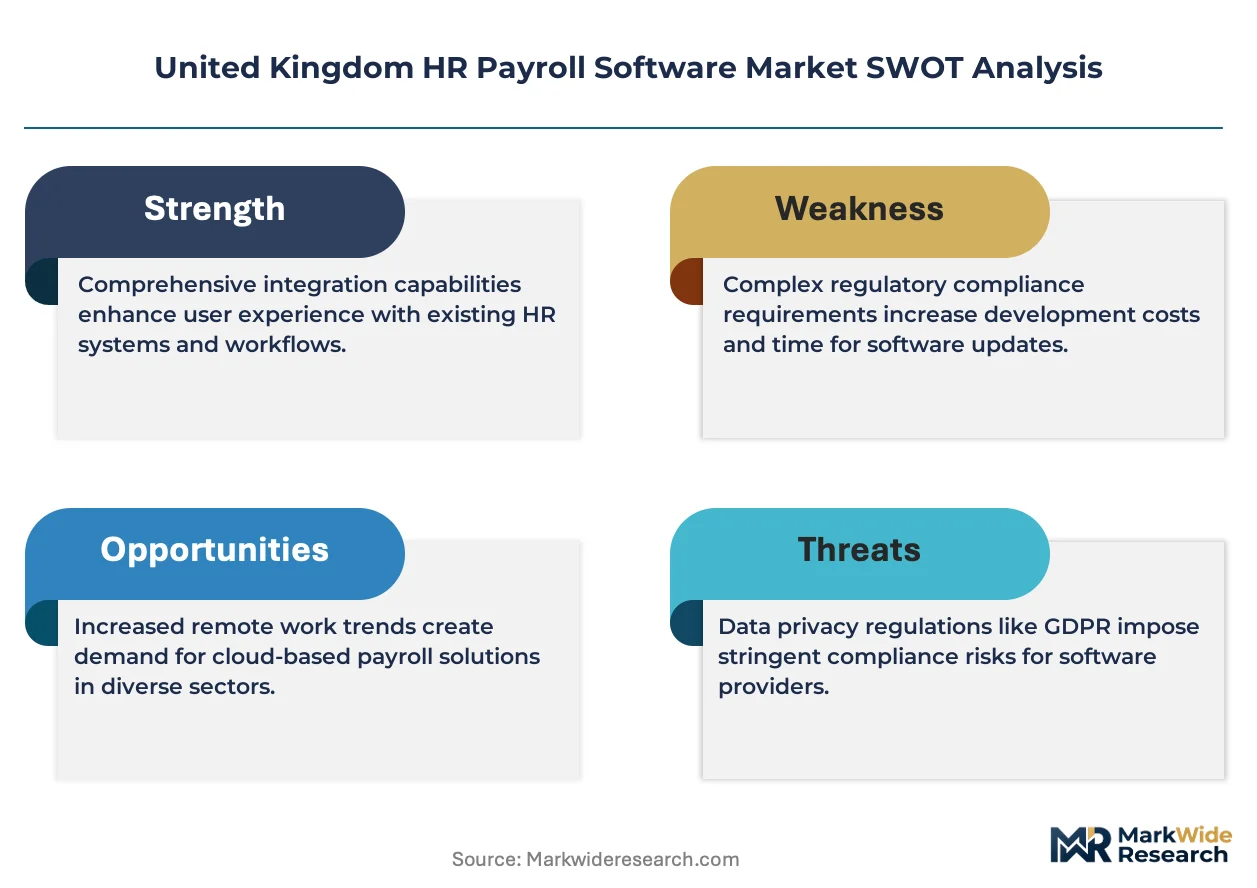
HM Revenue and Customs mandates real-time information reporting and auto-enrolment pension compliance, forcing software vendors to maintain continuous regulatory update pipelines. The Information Commissioner's Office enforces GDPR standards on employee data processing, shaping security architecture and cross-border hosting decisions. Buyers must evaluate whether vendor roadmaps accommodate pending changes to employment status classification and off-payroll working rules.
Market Dynamics
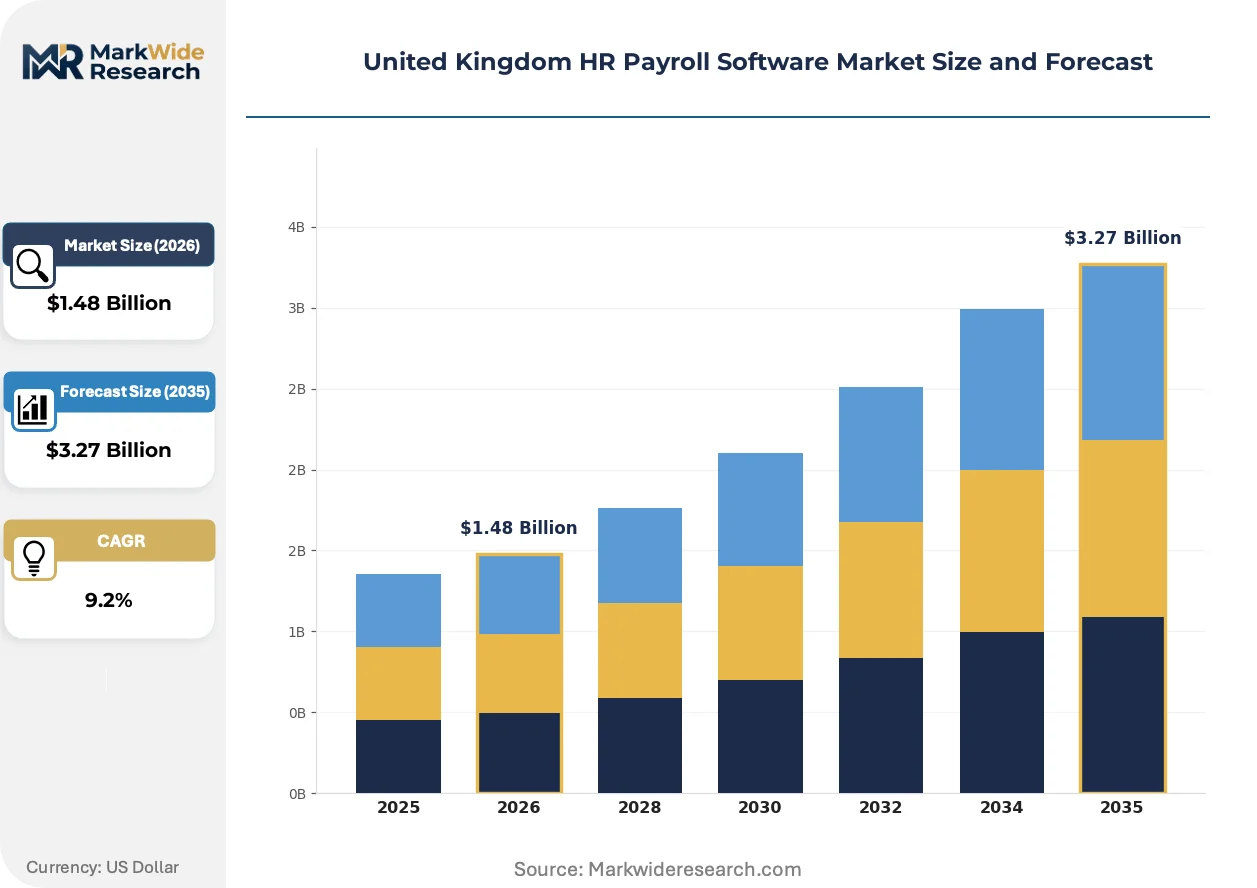
HM Revenue and Customs real-time information reporting mandates and auto-enrolment pension duties are compressing compliance timelines for British employers. Cloud-native payroll engines with embedded legislative update pipelines now determine competitive positioning as legacy on-premise systems face obsolescence.
Growth Catalysts
- Auto-enrolment pension duties:Mandatory workplace pension contributions for all eligible workers force small and medium enterprises to abandon spreadsheets for automated deduction engines.
- API-first architectures:Open banking connectivity and accounting software integrations reduce manual data re-entry for professional services firms clustered in Greater Manchester.
- London fintech corridor concentration:Cross-border payment infrastructure demands from British multinationals accelerate demand for multi-country payroll orchestration.
Market Restraints
- GDPR compliance costs:Information Commissioner's Office enforcement on employee data processing elevates security architecture expenditure and limits cross-border hosting flexibility.
- Legacy system entrenchment:Deep integration of historical on-premise installations with pension scheme administrators creates high switching friction for established enterprises.
- Skills scarcity:Shortage of payroll technicians versed in both HMRC real-time information protocols and cloud platform administration constrains vendor implementation capacity.
Strategic Opportunities
- Mid-sized professional services penetration:Accounting practices in Birmingham and Leeds remain underserved by current channel density, presenting white space for SaaS vendors.
- Employment status classification changes:Pending off-payroll working rule modifications will force contractor-heavy industries to adopt compliant determination tools.
- Embedded finance convergence:Integration of payroll data with lending eligibility engines and earned wage access products creates new revenue streams for platform providers.
Industry Challenges
- Legislative velocity management:Continuous update pipelines for national living wage adjustments and statutory sick pay calculations strain vendor development resources.
- Interoperability complexity:Fragmented pension scheme administrator APIs and inconsistent data formats impede seamless contribution filing across Northern Ireland, Scotland, and England.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom HR Payroll Software Market |
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: Payroll Management, Time Tracking, Employee Self-Service, Benefits Administration, Tax Management Client Size: Small & Medium Enterprises, Large Enterprises, Startups, Non-Profit Organizations End User Industry: Manufacturing, Financial Services, Education, Hospitality, Government Agencies |
| Companies Covered | ADP, Zellis, IRIS, Moorepay, Sage Payroll, PayFit, BrightPay, MHR, Employment Hero, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom HR Payroll Software Market Trends and Innovations
Machine learning classification engines and open banking connectivity are reshaping how British employers process payments and maintain compliance. Vendors race to embed predictive capabilities that anticipate regulatory changes before formal enactment.
Natural language processing is automating payslip query resolution and anomaly detection in PAYE calculations. Mid-sized retailers and hospitality chains in Edinburgh and Cardiff are deploying these tools to reduce helpline burden during monthly payroll cycles. The technology is automating tier-one support functions previously staffed by bureau administrators.
HM Revenue and Customs mandates for real-time information submission continue tightening reporting windows for all employer sizes. Software vendors must maintain continuous legislative monitoring and overnight rule deployment to prevent client penalties. Professional services firms with complex contractor populations face the steepest adaptation requirements.
Subscription pricing models are displacing perpetual licenses across the buyer base. Small enterprises in Bristol and Glasgow prefer monthly per-employee fees with automatic updates over capital expenditure on depreciating on-premise assets. This shift compresses vendor cash conversion cycles while embedding clients in recurring revenue relationships.
United Kingdom HR Payroll Software Market Segmentation
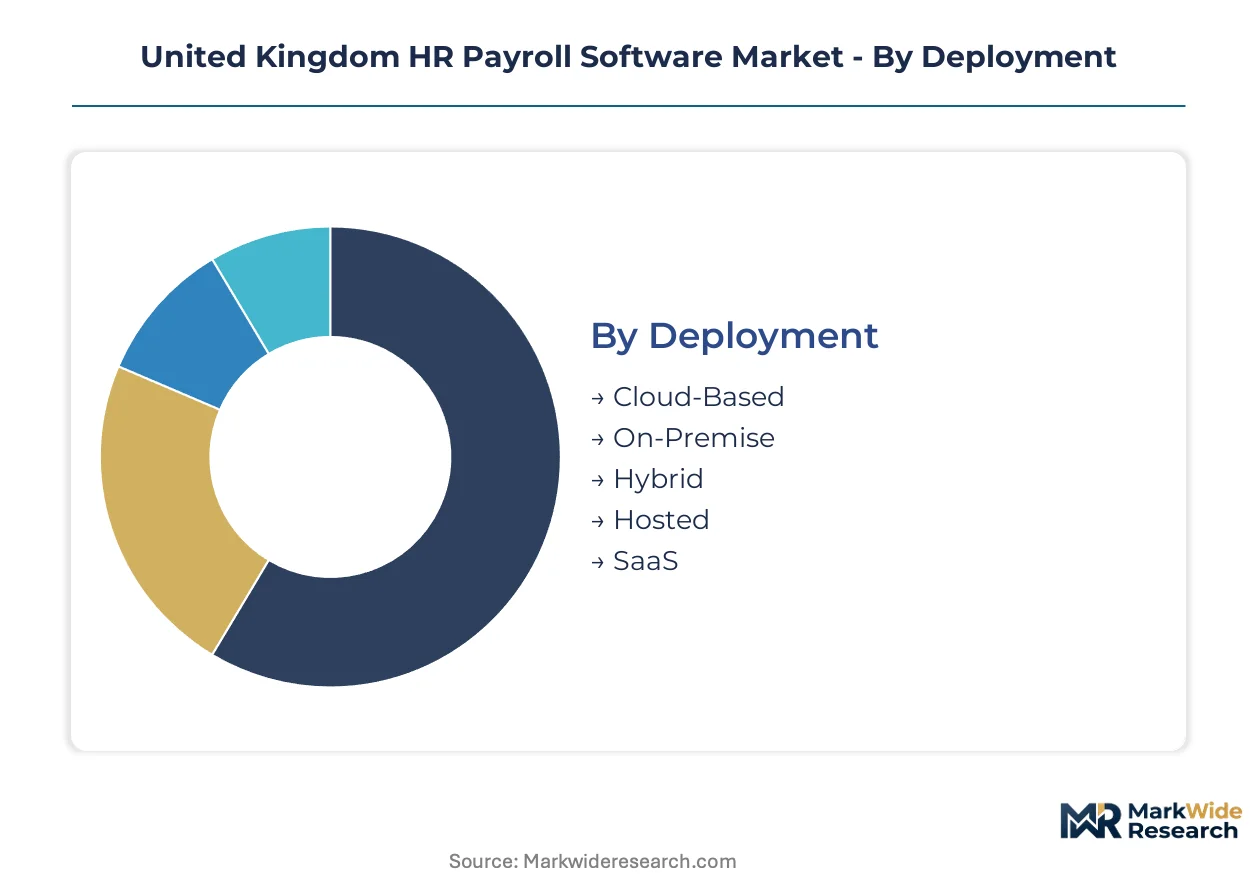
Segmentation in the United Kingdom HR Payroll Software Market reveals how vendor capabilities align with divergent compliance burdens and technical maturity across buyer types. Deployment architecture and client scale determine pricing models and implementation complexity more than any other dimension.
Deployment:
Supply concentration in cloud-native platforms has displaced legacy infrastructure investments across England, Scotland, Wales and Northern Ireland.
- Cloud-Based:Multi-tenant architectures with automatic legislative updates dominate new contract signings. Demand concentrates among mid-sized professional services firms in Greater Manchester's cluster where HMRC real-time information compliance timelines are tightest.
- On-Premise:Perpetually licensed installations requiring manual patch management persist in pension scheme administrator integrations with deep historical data. Manufacturing employers in the West Midlands retain these systems due to high switching friction with legacy benefit providers.
- Hybrid:Split configurations keep sensitive pension data on-premise while routing PAYE calculations through cloud engines. Government agencies in Whitehall procurement frameworks favor this model for audit trail separation.
- Hosted:Single-tenant cloud deployments managed by third-party data centers serve financial services firms with specific disaster recovery requirements. London's fintech corridor shows concentration here due to FCA operational resilience mandates.
- SaaS:Pure subscription models with per-employee monthly pricing capture startups in Bristol and Edinburgh seeking zero capital expenditure. Automatic national living wage adjustment pipelines differentiate competitive offerings.
Cloud-Based deployments absorb the bulk of installed capacity; SaaS is expanding most quickly among new market entrants.
Solution Type:
Cost tier differentiation separates compliance-critical modules from administrative add-ons in vendor bundling strategies.
- Payroll Management:Core wage calculation engines applying PAYE deduction schedules and statutory sick pay rules. Financial services firms in the City of London demand multi-country orchestration capabilities for cross-border contractor populations.
- Time Tracking:Clock-in systems integrated with shift pattern analysis and overtime accrual. Hospitality chains in Edinburgh and Cardiff deploy these to manage variable-hour compliance with national minimum wage regulations.
- Employee Self-Service:Portal interfaces for payslip access and tax code queries. Manufacturing sites in Northern England favor mobile-first designs for distributed production workforces.
- Benefits Administration:Auto-enrolment pension contribution management and scheme switching workflows. Professional services partnerships in Birmingham use these to handle complex salary sacrifice arrangements.
- Tax Management:Specialized engines for off-payroll working determinations and employment status classification. Contractor-heavy industries anticipate pending HMRC rule changes with these tools.
Payroll Management commands the deepest margin pools; Tax Management is climbing the fastest as regulatory complexity intensifies.
Client Size:
Volume concentration among mid-market buyers has reshaped vendor channel strategies and feature roadmaps.
- Small & Medium Enterprises:Organizations with 50-250 employees where spreadsheet capacity collapses under auto-enrolment duties. Accounting practices nationwide serve as distribution channels for standardized SaaS bundles.
- Large Enterprises:Multi-site employers requiring pension scheme aggregation across legacy acquisitions. These buyers negotiate custom service level agreements for HMRC filing deadline guarantees.
- Startups:High-growth technology firms prioritizing API-first integrations with equity management platforms. London's fintech corridor represents dense demand for rapid scaling without payroll administrator headcount expansion.
- Non-Profit Organizations:Charities and social enterprises with complex volunteer-to-employee transition workflows. Funding constraints drive preference for discounted per-employee pricing tiers.
Small & Medium Enterprises represent the largest addressable population; Startups are gaining share fastest in new contract velocity.
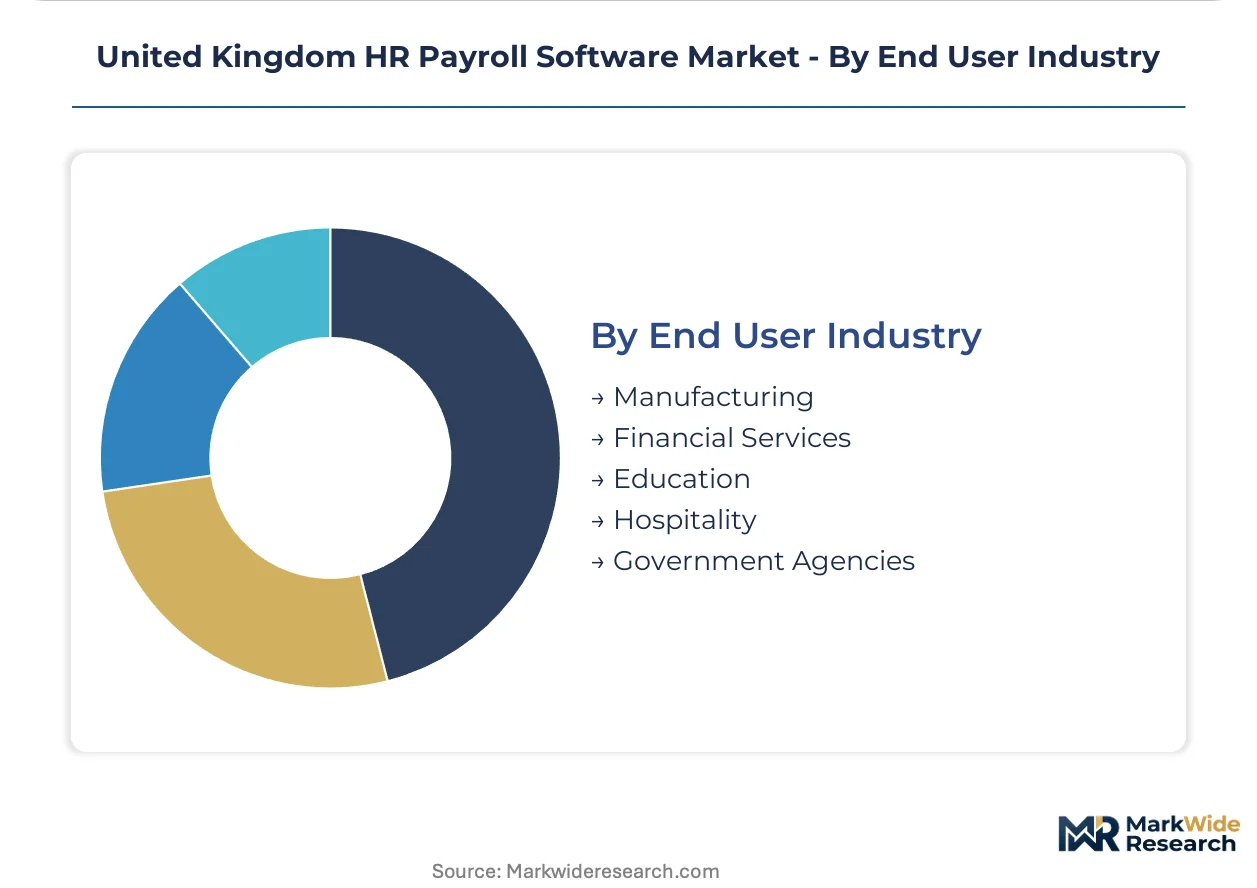
End User Industry:
Application-specific compliance requirements create vertical specialization opportunities for differentiated modules.
- Manufacturing:Shift-based payroll with overtime rule engines and piece-rate calculation capabilities. The West Midlands automotive cluster demands integration with shop-floor data collection systems.
- Financial Services:Multi-jurisdiction payroll for internationally mobile workforces and bonus deferral tracking. The City of London and Canary Wharf drive requirements for cross-border payment infrastructure.
- Education:Term-time only contracts and pension scheme transitions for academic staff. Universities in Scotland and England face complex historical final salary scheme wind-downs.
- Hospitality:High-frequency payroll cycles and tronc distribution management for tipped workers. Edinburgh's tourism sector and Cardiff's hotel chains prioritize rapid onboarding for seasonal staff.
- Government Agencies:Civil service pay scales and public sector pension scheme administration. Central government procurement frameworks mandate specific security accreditation levels.
Financial Services captures the highest per-employee contract values; Hospitality shows the steepest expansion trajectory as compliance automation penetrates fragmented employer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's fintech corridor concentrates the densest demand for multi-country payroll orchestration as British multinationals require cross-border payment infrastructure. Greater Manchester's professional services cluster drives cloud-native adoption among mid-sized accounting practices. Edinburgh and Cardiff hospitality chains accelerate compliance automation for seasonal workforce management.
London and Southeast England
Financial services firms in the City and Canary Wharf demand real-time information compliance engines with multi-jurisdiction capabilities. HM Revenue and Customs mandates tighten reporting windows for internationally mobile workforces. The fintech corridor anchors demand for API-first architectures connecting payroll to equity management platforms.
Greater Manchester and Northern England
Professional services partnerships in Manchester and Leeds abandon spreadsheets for automated deduction engines as auto-enrolment duties intensify. The Pensions Regulator enforcement drives mid-sized employers toward cloud-native solutions. Birmingham's accounting practices remain underserved, presenting white space for SaaS vendors expanding channel density.
Scotland
Edinburgh's tourism sector and Glasgow's manufacturing base deploy high-frequency payroll cycles for variable-hour compliance. Universities across Scotland face complex final salary pension scheme wind-downs requiring specialized administration modules. The Scottish Government's public sector procurement frameworks mandate specific security accreditation levels for payroll vendors.
Wales
Cardiff's hotel chains prioritize rapid onboarding tools for seasonal hospitality staff. Manufacturing employers in the Welsh valleys retain legacy on-premise installations due to deep pension scheme administrator integrations. The Welsh Government's economic development programs subsidize cloud migration for small enterprises in underserved regional markets.
Northern Ireland
Belfast's professional services firms navigate fragmented pension scheme administrator APIs with inconsistent data formats. Cross-border employers managing Republic of Ireland and UK payroll simultaneously require dual-compliance engines. Stormont procurement frameworks favor hybrid deployments separating sensitive pension data from cloud PAYE calculations.
United Kingdom HR Payroll Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance-engine sophistication and cross-border payment infrastructure. Enterprise-grade suites with embedded legislative update pipelines command sustained pricing power while stripped-back cloud tools compete aggressively on per-employee monthly fees. Three archetypes dominate: global payroll orchestrators with multi-country infrastructure, UK specialists with deep pension scheme integration, and mid-market SaaS vendors with accounting practice channel density. Consolidation through strategic acquisitions and API-first partnership ecosystems represents the dominant competitive trajectory.
Within the global orchestrator tier, ADP leverages cross-border payment infrastructure to anchor multi-country contracts for British multinationals. Zellis occupies a position among UK specialists through deep integration with domestic pension schemes and statutory sick pay calculations. Sage Payroll exemplifies the mid-market SaaS archetype with nationwide channel density across accounting practices. These three anchors illustrate how vendor capabilities align with divergent compliance burdens and technical maturity across buyer segments.
| Leading Market Players |
|---|
| ADP |
| Zellis |
| IRIS |
| Moorepay |
| Sage Payroll |
| PayFit |
| BrightPay |
| MHR |
| Employment Hero |
| Others |
Pricing and Supply Chain Analysis
Cloud-native payroll engineers concentrated in London's fintech corridor and Greater Manchester's professional services cluster command salary premiums that compress margins for mid-tier SaaS vendors while sustaining enterprise-grade pricing power. This labor-cost differential widens the spread between compliance-critical suite pricing and stripped-back per-employee monthly fees.
Pricing Analysis
Value-based pricing anchored to HMRC filing guarantee uptime and penalty avoidance commands premium positioning for enterprise-grade suites with embedded legislative update pipelines. Three-tier pricing structure across premium, standard, and economy levels separates multi-country orchestration capabilities from domestic-only cloud tools and basic bureau services. Cost compression in the standard tier intensifies because channel partners compete aggressively on per-employee monthly fees. Small enterprises in Bristol and Glasgow show highest price sensitivity, while financial services firms in the City of London demonstrate lowest sensitivity due to compliance-critical positioning.
Supply Chain Analysis
Freight costs for data center hardware and networking equipment into UK co-location facilities add marginal overhead to cloud-native deployment economics. Software development labor draws from India, Poland, and Portugal for back-end engineering, while UK-based product managers and compliance specialists anchor rule-engine development. Single-source vulnerability concentrates in pension scheme administrator APIs with inconsistent data formats across Northern Ireland, Scotland, and England. Distribution runs through accounting practice channels for mid-market penetration and direct enterprise sales for multinational contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom HR Payroll Software Market sits in a technology-transition phase as API-first architectures displace legacy on-premise installations. Cloud-native platforms with automatic legislative updates are replacing perpetual-license systems requiring manual patch management.
For Market Incumbents: Extend compliance-engine sophistication through deeper integration with HM Revenue and Customs real-time information protocols. Acquire specialist firms with proven pension scheme administrator APIs to neutralize switching friction threats from legacy system entrenchment. Channel control through accounting practice density remains the priority lever for mid-market defense.
For New Entrants and Emerging Players: Accounting software marketplace partnerships offer the most penetrable route into underserved Birmingham and Leeds professional services clusters. White space exists in contractor-heavy industries anticipating pending off-payroll working rule modifications. API-first positioning with open banking connectivity provides differentiated go-to-market angle against incumbent bureau services.
For Investors and Strategic Acquirers: Re-rating potential sits with UK-specialist vendors possessing deep pension scheme integration given auto-enrolment duty expansion. Long-term viability favors platforms with recurring SaaS revenue models and automatic legislative update pipelines. Watch HMRC enforcement intensity on real-time information filing deadlines as inflection indicator for compliance-engine valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity with open banking and accounting software reduces manual data re-entry for Greater Manchester professional services firms. |
| Acquisition of Specialist Firm | Pension scheme administrator API specialists neutralize interoperability complexity across Northern Ireland, Scotland, and England. |
| Product Launch | Embedded earned wage access products leverage payroll data for lending eligibility engines in London's fintech corridor. |
| Strategic Partnership | Channel partnerships with accounting practices nationwide accelerate mid-market penetration in underserved Birmingham and Leeds clusters. |
| Geographic Expansion | Edinburgh and Cardiff hospitality chains require rapid onboarding tools for seasonal workforce compliance automation. |
Research Methodology
Document review covered HM Revenue and Customs regulatory filings, The Pensions Regulator enforcement data, and Information Commissioner's Office GDPR guidance, complemented by interviews with payroll software product managers, accounting practice channel partners, enterprise HR technology procurement officers, and pension scheme administrators. Secondary validation drew from vendor SEC filings, UK cloud infrastructure capex disclosures, and professional services firm technology adoption surveys. Bottom-up contract value analysis and top-down market sizing triangulated segment-level estimates.
Installed base projections and revenue forecasts across the analysis window reflect segmentation by deployment architecture, solution type, client size, and end-user industry. Modeled dimensions include cloud-native versus on-premise migration velocity, compliance module bundling patterns, and vertical specialization depth. CAGRs were derived from historical adoption curves adjusted for regulatory mandate timing and channel capacity expansion.
The model holds under stable HM Revenue and Customs enforcement intensity and consistent auto-enrolment duty scope; deviation in off-payroll working rule implementation timelines or pension scheme administrator API standardization would shift vendor competitive positioning. Forecasts reflect assumptions about legislative update pipeline maintenance costs and cloud infrastructure scaling economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time Series Analysis Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Sports Production Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Casino Management Systems Market
Software & Services
Global UIUX Software Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Middleware Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Automotive Software Market