
 United States and European Fiber Optic Cable Market | 2026-2036
United States and European Fiber Optic Cable Market Size, Share, and Industry Trends Forecast 2026-2036
United States and European Fiber Optic Cable Market Analytics
Hyperscale data center operators are bifurcating from traditional telecom carriers as the dominant procurement force in fiber optic cable demand. Corning Incorporated leverages its vertically integrated manufacturing base in North Carolina to control optical fiber preform supply. Prysmian Group anchors European supply through its Milan-centered R&D and submarine cable specialization. Nexans SA competes on industrial-grade armored cable lines for energy and automation crossover applications.
United States and European fiber optic cable denotes silica-glass filament bundles with cladding indices engineered for total internal reflection, typically operating at 1310 nm or 1550 nm wavelengths to transmit photonic signals across distances exceeding 100 kilometers without regeneration. The primary commercial purpose centers on replacing copper conductor systems in high-bandwidth, low-latency data transmission infrastructure. Single-mode fiber dominates transatlantic and long-haul terrestrial routes due to attenuation rates below 0.2 dB per kilometer, while multi-mode fiber occupies shorter-reach enterprise and data center interconnects where cost-per-link drives procurement. Outdoor installation types command premium pricing in both markets because of gel-filled loose tube designs and UV-resistant jacketing required for aerial and direct-buried deployments.
The Federal Communications Commission in the United States and the EU's Radio Equipment Directive framework shape product certification timelines and cross-border market access conditions for cable assemblies. REACH compliance and RoHS substance restrictions in Europe filter supplier eligibility based on halogen-free jacketing and restricted heavy metal content in cable coatings. Stakeholders must monitor how BEAD program disbursement velocity in the United States and EU Gigabit Infrastructure Act enforcement timelines alter project backlogs and inventory planning horizons.
Market Dynamics
Hyperscale data center operators are decoupling from traditional telecom procurement patterns, creating bifurcated demand streams that reward cable suppliers with captive preform capacity and penalize merchant-market dependent fabricators.
Growth Catalysts
- EU Gigabit Infrastructure Act:Binding national coverage targets for 2030 are accelerating public subsidy flows into fiber-to-the-home trenching across France and Germany.
- Data center interconnect density:AI training clusters are demanding multi-fiber push-on (MPO) cable assemblies with 400G and 800G lane aggregation.
- BEAD program velocity:The Broadband Equity Access and Deployment framework is unlocking federal matching funds for last-mile fiber builds in underserved US states.
Market Restraints
- Optical fiber preform supply concentration:Vycor and synthetic silica deposition capacity clusters in North Carolina and Japan, creating chokepoint vulnerability for European cable fabricators.
- REACH substance restriction compliance:Halogen-free jacketing mandates are filtering out low-cost Asian suppliers from EU public procurement tenders.
- Copper cable residual cost advantage:Legacy coaxial infrastructure in US multi-dwelling units delays fiber overbuild economics where DOCSIS 4.0 upgrades suffice.
Strategic Opportunities
- Eastern European broadband gap:Poland and Romania remain below 50% fiber penetration, creating greenfield deployment zones for EU cohesion fund-backed projects.
- Submarine cable landing station expansion:Transatlantic capacity additions are driving demand for armored beach manhole and terrestrial backhaul cable systems.
- Smart grid fiber overlay:Distribution automation and synchrophasor networks are converging power utility and telecom cable specifications in Germany's industrial corridor.
Industry Challenges
- Fusion splicing technician scarcity:Precision fiber termination skills lag deployment timelines in both US rural markets and EU peripheral regions.
- Cross-border type-approval fragmentation:Divergent FCC Part 68 and EU Radio Equipment Directive testing protocols extend product launch cycles for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and European Fiber Optic Cable Market |
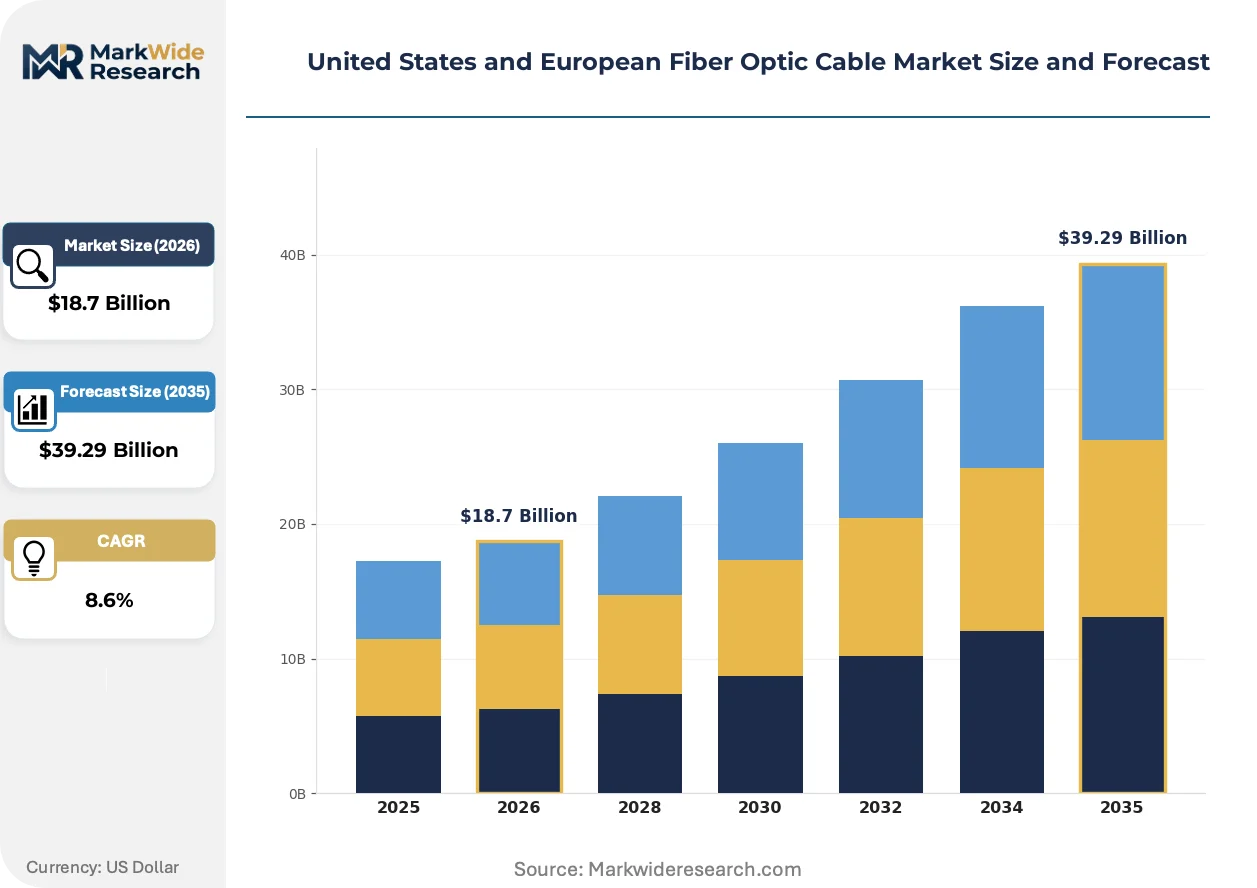
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Armored, Non-Armored Installation Type: Indoor, Outdoor, Aerial, Direct Buried End User: Telecommunications, Data Centers, Enterprise, Industrial Application: Telecom Networks, Ethernet Networks, Broadband, Military |
| Companies Covered | Corning Incorporated, Prysmian Group, Nexans SA, OFS Fitel, Sumitomo Electric Industries, CommScope Holding Company, Weinert Industries AG, Coherent Corporation, LEONI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and European Fiber Optic Cable Market Evolving Landscape
Silicon photonics integration and hollow-core fiber architectures are compressing the performance gap between optical transmission and electronic switching, forcing cable suppliers to align with chip-level co-packaging roadmaps.
Hollow-core photonic bandgap fiber is displacing conventional single-mode designs in latency-sensitive financial trading networks and inter-data center links. Chicago and Frankfurt exchange operators are piloting deployments. The technology is displacing legacy dispersion-compensated spans by eliminating silica-induced nonlinear distortion, enabling direct detect transceivers at extended reaches.
REACH Annex XVII substance restrictions are tightening permissible concentrations of lead stabilizers and phthalate plasticizers in polyethylene cable jackets. German cable fabricators are reformulating compound recipes to maintain CE marking eligibility. Outdoor-rated loose tube products face the steepest reformulation costs due to UV stabilizer substitution requirements.
Consolidated procurement by hyperscale cloud operators is compressing supplier margins through multi-year framework agreements with price-down escalators. Traditional telecom distributors are losing shelf space to direct manufacturer relationships. The shift is most visible in Northern Virginia and Dublin data center clusters where Meta, Microsoft, and Amazon negotiate cable supply at rack-scale rather than project-scale.
United States and European Fiber Optic Cable Market Segmentation
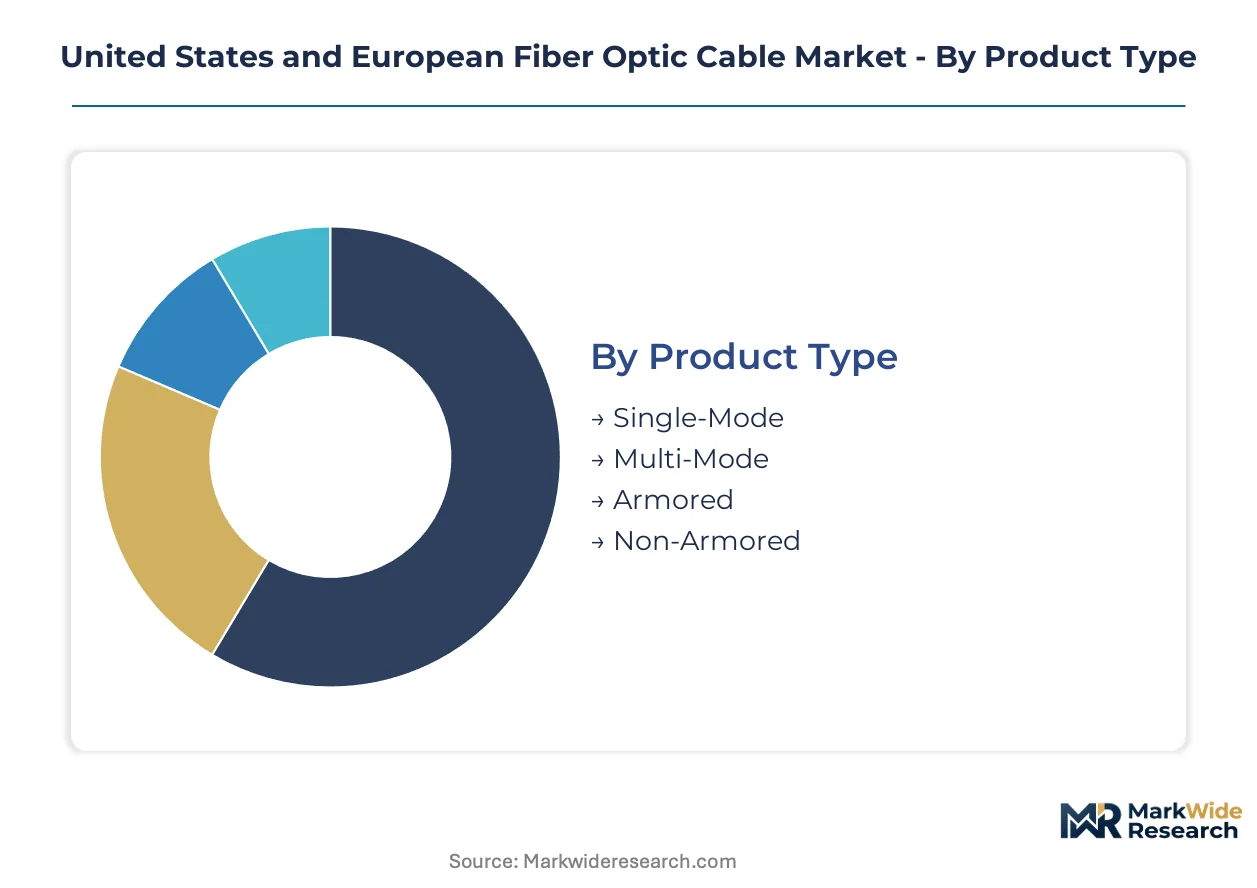
Fiber optic cable procurement patterns diverge sharply across product specifications and deployment environments. Regulatory frameworks in Germany and the United States create compliance-driven purchasing tiers that reshape competitive positioning within each segment.
Product Type:
REACH Annex XVII substance restrictions and FCC Part 68 certification timelines create divergent compliance burdens across silica-glass formulations.
- Single-Mode:Silica-core filaments with 8-10 micron core diameters engineered for 1310 nm and 1550 nm wavelength transmission. Germany's industrial corridor and transatlantic landing stations in Virginia concentrate procurement where attenuation below 0.2 dB/km eliminates regeneration requirements. REACH-compliant jacketing adds 12-18% material cost premium for EU deployments.
- Multi-Mode:50 or 62.5 micron core designs optimized for shorter-reach enterprise and data center interconnects. Northern Virginia and Dublin hyperscale clusters drive MPO assembly demand for 400G and 800G lane aggregation. Cost-per-link sensitivity favors this grade in intra-facility backbone runs.
- Armored:Steel tape or wire-reinforced constructions for direct-buried and rodent-prone routes.
- Non-Armored:Standard polyethylene-jacketed designs for duct and aerial installations with lower mechanical threat profiles.
Single-Mode handles the majority of throughput; Multi-Mode is expanding most quickly on share in AI training clusters.
Installation Type:
Deployment environment dictates gel-filling requirements, UV stabilizer specifications, and trenching economics that separate premium from standard procurement tiers.
- Outdoor:Gel-filled loose tube constructions with carbon-black loaded jackets rated for -40°C to +70°C thermal cycling. BEAD program disbursements in rural US states and EU cohesion fund projects in Poland accelerate demand where aerial and direct-buried methods dominate last-mile economics.
- Indoor:Tight-buffered designs with plenum-rated halogen-free jackets for riser and horizontal distribution. German commercial building codes and NFPA 262 compliance in US metropolitan markets filter supplier eligibility through flame-spread certification.
- Aerial:Self-supporting figure-8 or all-dielectric designs for pole attachment without messenger wire.
- Direct Buried:Armored or thick-walled constructions for trench deployment without conduit protection.
Outdoor commands the steepest pricing premium; Indoor is climbing the fastest as data center interconnect density intensifies.
End User:
Procurement authority is fragmenting across carrier, cloud operator, and industrial buyer archetypes with divergent technical specifications.
- Data Centers:Hyperscale operators in Northern Virginia, Frankfurt, and Dublin negotiate rack-scale cable supply through multi-year framework agreements. MPO and MTP connector assemblies with polarization-maintaining fiber dominate procurement specifications.
- Telecommunications:Incumbent carriers in Germany and US ILECs manage project-scale procurement with legacy fusion splicing infrastructure and longer qualification cycles.
- Enterprise:Financial services and healthcare verticals in US Northeast corridor and London.
- Industrial:Power utilities and manufacturing automation networks in Germany's Ruhr region.
Data Centers is the fastest mover on share; Telecommunications retains the largest installed base volume.
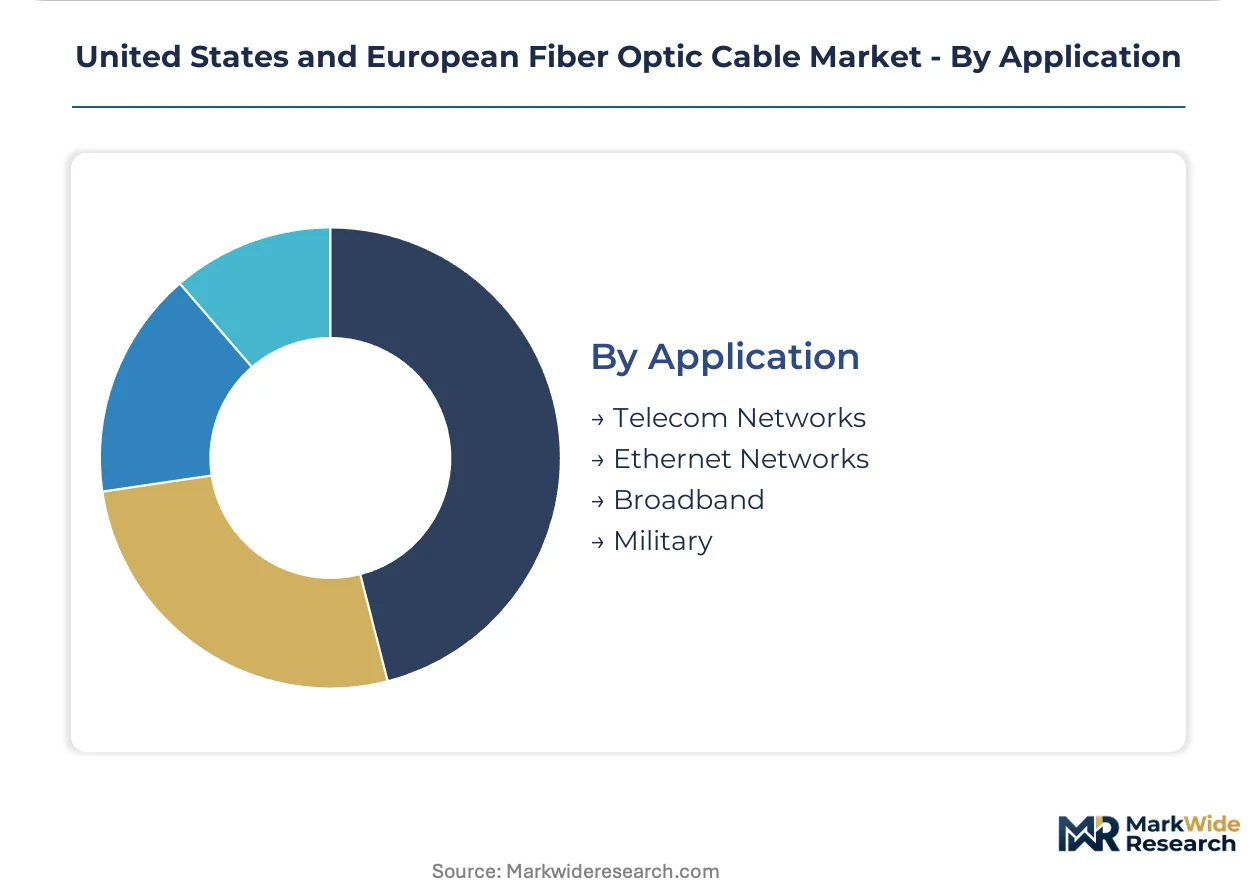
Application:
Latency sensitivity and security classification separate commercial from specialized procurement channels.
- Telecom Networks:Long-haul terrestrial and submarine cable landing station backhaul spanning transatlantic routes. Hollow-core fiber pilots between Chicago and Frankfurt exchanges are displacing dispersion-compensated legacy spans.
- Broadband:FTTH and FTTB deployments driven by EU Gigabit Infrastructure Act mandates and BEAD program velocity in underserved US states. France and Germany national coverage targets concentrate trenching demand.
- Ethernet Networks:Enterprise LAN and data center interconnect standards from 10GBASE-SR to 400GBASE-SR16.
- Military:TEMPEST-rated and tactical fiber assemblies for command, control, and battlefield communications.
Telecom Networks handles the majority of throughput; Broadband is gaining share fastest on public subsidy acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic submarine cable landing stations in Virginia Beach and Bude anchor North American-European fiber demand, while terrestrial backhaul corridors in Germany's industrial belt and the US Northeast concentrate procurement velocity for high-capacity single-mode deployments.
United States
BEAD program disbursements accelerate last-mile trenching across rural states, with Virginia, Texas, and California capturing the majority of federal matching funds. FCC Part 68 certification timelines filter supplier eligibility for cross-border cable assemblies. Northern Virginia's hyperscale cluster drives MPO assembly demand for AI training infrastructure at rack-scale procurement volumes.
Germany
The EU Gigabit Infrastructure Act mandates 100% gigabit coverage by 2030, tightening deployment timelines for FTTH contractors in Bavaria and North Rhine-Westphalia. REACH Annex XVII substance restrictions on halogen-free jacketing add 12-18% material cost premiums for public tenders. The Ruhr industrial corridor converges power utility and telecom cable specifications for smart grid fiber overlays.
France
National broadband targets under the France THD program concentrate trenching demand in Île-de-France and Auvergne-Rhône-Alpes, with public subsidy flows exceeding private investment in peripheral regions. ANSM compliance protocols align with EU Radio Equipment Directive frameworks for CE marking eligibility. Paris exchange operators pilot hollow-core fiber deployments for latency-sensitive financial trading networks.
United Kingdom
Project Gigabit procurement frameworks prioritize altnet fiber builds in Midlands and North England, displacing incumbent carrier dominance in underserved postcodes. Ofcom's wholesale access remedies shape interconnection pricing for cable landing station backhaul. London's financial district anchors demand for polarization-maintaining fiber in high-frequency trading infrastructure.
Poland
EU cohesion fund allocations target the Eastern European broadband gap, with fiber penetration below 50% creating greenfield deployment zones in Masovian and Silesian Voivodeships. National regulatory authority UKE enforces wholesale open fiber access mandates for state-aided builds. Warsaw's emerging data center cluster attracts submarine cable landing investments for Baltic Sea route diversification.
United States and European Fiber Optic Cable Market Competitive Landscape
Listed leaders compete with private specialists across capital access and procurement flexibility, with publicly traded entities commanding framework agreement scale while private fabricators retain agility in niche certification tiers. The vendor base stratifies between captive preform producers and merchant-market dependent assemblers, creating divergent margin structures. Three archetypes dominate: vertically integrated optical fiber manufacturers, cable assembly specialists with regional certification depth, and industrial crossover players leveraging energy sector relationships. Capacity expansion and backward integration into preform supply represent the dominant competitive moves.
Among US and European-based fabricators, Corning Incorporated, Prysmian Group, and Nexans SA exemplify the tiered competitive structure. Corning represents the vertically integrated archetype with in-house preform production. Prysmian occupies a position bridging submarine specialization and terrestrial supply. Nexans exemplifies the industrial crossover model, anchoring its fiber positioning through energy sector channel relationships. These three entities collectively illustrate how geographic manufacturing concentration, regulatory certification breadth, and end-market diversification separate premium-tier suppliers from merchant-market competitors.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Nexans SA |
| OFS Fitel |
| Sumitomo Electric Industries |
| CommScope Holding Company |
| Weinert Industries AG |
| Coherent Corporation |
| LEONI |
| Others |
Value Network & Pricing Analysis
Multi-year framework agreements with price-down escalators lock in supply access for hyperscale operators while compressing margins for merchant-market dependent fabricators across the United States and European markets. These contracts tether volume commitments to preform allocation security, creating divergent pricing visibility between captive producers and assembly-only suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified outdoor loose tube designs from halogen-free indoor tight-buffered grades and unqualified merchant-market cables. Price differentiation rests on certification tier and volume scale, with hyperscale rack-scale procurement commanding steepest discounts. Cost compression in standard-grade multi-mode assemblies is intensifying because consolidated cloud operator buying pools extract annual price-down commitments. Enterprise buyers in financial services verticals show least price sensitivity, prioritizing latency performance and polarization-maintaining fiber specifications over per-meter economics.
Supply Chain Analysis
Strategic stockpiling of optical fiber preforms dominates inventory strategy among European cable fabricators confronting Vycor and synthetic silica deposition capacity concentration in North Carolina and Japan. Raw material supply draws from high-purity silica sand deposits, germanium tetrachloride dopants, and specialized UV stabilizer compounds for outdoor jacketing. Single-source vulnerability in preform supply creates structural risk for EU-based assemblers lacking backward integration. Distribution runs through direct manufacturer relationships with hyperscale operators, bypassing traditional telecom distributor channels in Northern Virginia and Dublin clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by BEAD program disbursement acceleration and EU Gigabit Infrastructure Act enforcement timelines converging on fiber trenching demand.
For Market Incumbents: Shield margin position by deepening captive preform capacity in North Carolina and accelerating REACH Annex XVII compliance certification for halogen-free jacketing lines. Consolidate supplier relationships with hyperscale operators through multi-year framework agreements that lock in volume against emerging merchant-market competitors.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships opens procurement eligibility for EU cohesion fund-backed projects in Poland and Romania. Target the Eastern European broadband gap where fiber penetration remains below fifty percent and incumbent carrier relationships are weakest. Lead with armored cable specialization for smart grid fiber overlay applications in Germany's Ruhr industrial corridor.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors vertically integrated preform producers over assembly-only fabricators. Long-term viability centers on backward integration into synthetic silica deposition capacity and submarine cable landing station relationships. Watch hollow-core fiber pilot deployments between Chicago and Frankfurt exchanges as signal for latency-sensitive infrastructure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Supply | Captive Vycor capacity insulates Corning and Prysmian from merchant-market chokepoints. |
| REACH Annex XVII Compliance Certification | Halogen-free jacketing eligibility filters German and French public procurement tender participation. |
| Hyperscale Direct Relationship Development | Rack-scale negotiation access displaces traditional telecom distributor channels in Northern Virginia. |
| Submarine Cable Landing Station Expansion | Armored beach manhole demand anchors transatlantic backhaul procurement for Virginia Beach and Bude routes. |
| Hollow-Core Fiber Pilot Deployment | Chicago and Frankfurt exchange trials signal latency-sensitive financial trading network specification shifts. |
Research Methodology
The analysis maps single-mode, multi-mode, armored, and non-armored cable segments, each validated through procurement directors at hyperscale operators, FTTH contractors in Germany and France, and submarine cable system engineers. Primary interviews with fiber deployment managers, REACH compliance officers, and data center interconnect specialists combined with secondary validation from FCC Part 68 certification databases, EU cohesion fund disbursement records, and BEAD program funding trackers. Bottom-up cable volume estimates triangulated against top-down infrastructure investment flows across the analysis window.
Consistency checks against hyperscaler capex disclosures and public subsidy commitment databases validated volume and value outputs over the projection horizon. Segmentation modeling spanned product type, installation environment, end-user archetype, and application with regional regulatory cluster overlays. CAGRs derived from deployment timeline phasing tied to EU Gigabit Infrastructure Act milestones and BEAD matching fund release schedules, with AI training cluster density and MPO assembly adoption curves as fiber-specific forecast inputs.
Underlying assumptions cover subsidy disbursement velocity, preform capacity expansion timelines, and fusion splicing technician availability, with deviation risk concentrated in REACH substance restriction amendments and transatlantic tariff exposure. Revision becomes warranted when BEAD program implementation crosses state-level matching threshold delays or hollow-core fiber commercialization accelerates beyond pilot phase.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
US Private LTE and 5G Network Market
Network Technology
Germany Residential Gateway Market
Network Technology
Unified Network Management Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Sand Lane Systems Market
Network Technology
Global Home Networking Device Market
Network Technology
Lit Fiber Market
Network Technology
Network Equipment Market
Network Technology
Wimax Solutions Market
Network Technology
Microduct Market
Network Technology
Global Network Management Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Self-Healing Networks Market
Network Technology
Carrier Routing Equipment Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Virtual Customer Premises Equipment Market