
 Global Wi-Fi Range Extender Market | 2026-2036
Global Wi-Fi Range Extender Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wi-Fi Range Extender Market Foresight
Online retail channels is tilting toward direct-to-consumer sales and away from traditional electronics distributors. NETGEAR Inc. leverages its established e-commerce infrastructure to sustain premium positioning in North America. TP-Link Technologies Co. Ltd anchors volume sales through broad marketplace presence across multiple continents. Shenzhen Tenda Technology Co. Ltd competes aggressively on price in emerging markets through localized platform partnerships.
A Wi-Fi range extender receives an existing wireless signal, amplifies it, and rebroadcasts it on the same or different frequency band, typically operating at 2.4 GHz, 5 GHz, or 6 GHz with throughput ratings from 300 Mbps to over 5 Gbps depending on the Wi-Fi generation supported. Its primary commercial purpose is eliminating dead zones in buildings where a single router cannot deliver adequate signal strength for streaming, conferencing, or IoT connectivity. Dual Band and Tri Band technology segments carry the widest margin pools as consumers prioritize simultaneous backhaul and client service without throughput collapse. Wi-Fi 6 equipment is displacing Wi-Fi 5 inventory fastest in residential and small office settings where latency-sensitive applications have proliferated. Plug-in Extender form factors dominate unit volumes due to minimal installation friction, though Outdoor Extender applications are deepening as property owners extend coverage to detached structures and perimeter security devices.
The FCC in the United States governs unlicensed spectrum use and device certification under Part 15 rules, while the EU's Radio Equipment Directive and CE marking framework shape product compliance for European market access. China's MIIT enforces GB standards for wireless transmission power and frequency stability, creating divergent testing requirements for manufacturers serving multiple geographies. Stakeholders must monitor spectrum reallocation proceedings and Wi-Fi 7 certification timelines to align R&D roadmaps with regulatory ratification schedules.
Market Dynamics
The Wi-Fi Range Extender Market is undergoing structural compression as mesh networking architectures and Wi-Fi 7 certification timelines force hardware refresh cycles while spectrum reallocation proceedings in major economies accelerate obsolescence of prior-generation inventory.
Growth Catalysts
- FCC Wi-Fi 6E Spectrum Allocation:The United States regulator opened 6 GHz bands for unlicensed use, compelling residential and small office buyers to upgrade legacy 2.4 GHz and 5 GHz equipment to capture wider channels and reduced congestion.
- Fiber-to-the-Home Deployment:Germany, China, and the United States are pushing fiber infrastructure deep into residential neighborhoods, creating in-building coverage gaps that drive demand for plug-in and mesh-compatible extenders.
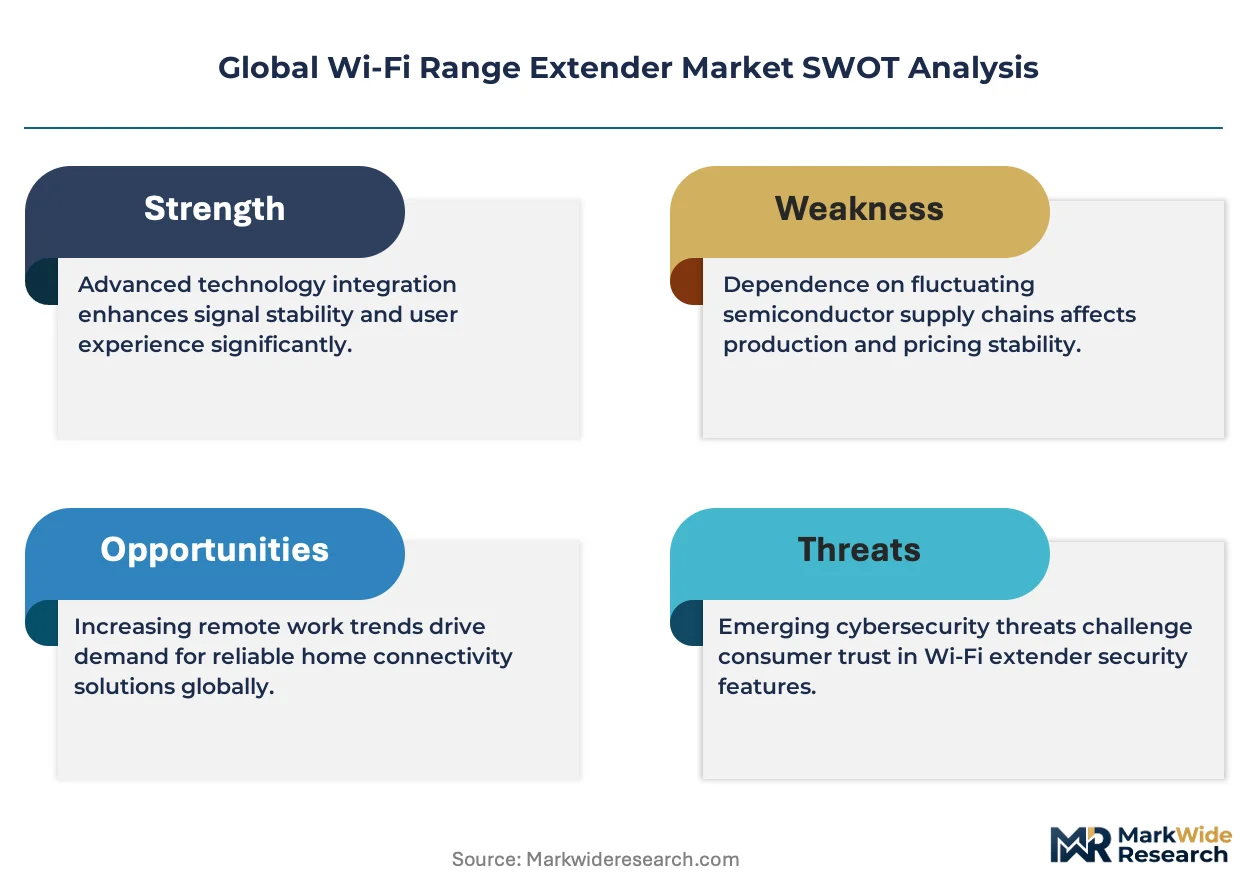
- IoT Device Density:Smart home ecosystems now integrate 50+ connected devices per household, requiring seamless handoff capabilities that dual-band and tri-band extenders provide to eliminate dead zones.
Market Restraints
- Silicon Supply Concentration:Advanced Wi-Fi 6E and Wi-Fi 7 chipsets depend on fabrication capacity concentrated in Taiwan and South Korea, exposing manufacturers to geopolitical disruption and allocation constraints.
- Radio Equipment Directive Compliance Costs:CE marking requirements under EU regulations impose divergent testing protocols for 6 GHz power levels and frequency stability, fragmenting R&D budgets across certification regimes.
- Mesh System Substitution:Whole-home mesh networking systems from router manufacturers are capturing buyers who would otherwise purchase standalone extenders, compressing the addressable market for discrete repeater hardware.
Strategic Opportunities
- India Broadband Expansion:The country's PLI scheme for telecom equipment and rising fiber penetration in tier-2 cities create underpenetrated demand for cost-optimized extenders compatible with localized spectrum rules.
- Outdoor Extender Applications:Property owners in suburban United States and German markets are extending coverage to detached structures and perimeter security devices, opening a hardware segment with premium pricing tolerance.
- Direct-to-Consumer Channel Migration:Marketplace platforms and manufacturer e-commerce infrastructure are displacing traditional electronics distributors, enabling margin capture and customer data ownership.
Industry Challenges
- RF Engineering Talent Scarcity:Wi-Fi 7 antenna design and 6 GHz interference mitigation require specialized expertise concentrated among semiconductor vendors and contract manufacturers, constraining in-house product development timelines.
- Multi-Geography Certification Parallelism:Simultaneous FCC Part 15, CE marking, and MIIT GB standard testing creates bottlenecks as regulatory ratification schedules for Wi-Fi 7 remain misaligned across the United States, European Union, and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wi-Fi Range Extender Market |
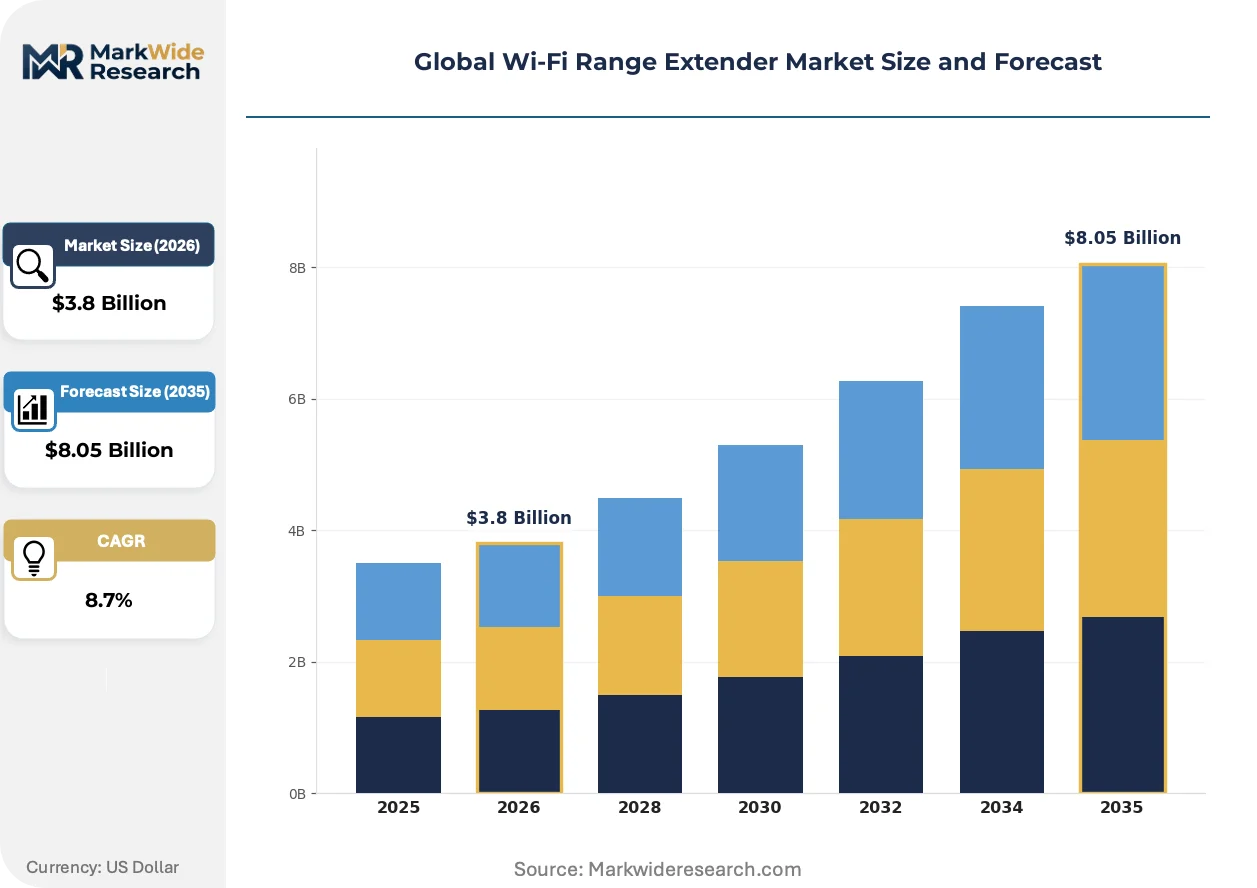
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Extender, Plug-in Extender, Outdoor Extender, Powerline Extender Technology: Wi-Fi 5, Wi-Fi 6, Dual Band, Tri Band End User: Residential, Small Office, Large Office, Public Spaces Installation Type: Wired, Wireless, Hybrid, Plug-and-Play |
| Companies Covered | NETGEAR Inc., TP-Link Technologies Co. Ltd, D-Link Corporation, Linksys Group Inc., Cisco Systems Inc., Huawei Technologies Co. Ltd, Shenzhen Tenda Technology Co. Ltd, ASUSTeK Computer Inc., TRENDnet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wi-Fi Range Extender Market Shifts & Advancements
Product roadmaps are converging on unified mesh architectures and software-defined radio configurations that blur historical boundaries between extenders, access points, and router functionality.
Wi-Fi 7 chipsets with 320 MHz channel bonding and multi-link operation are collapsing the performance gap between standalone extenders and wired backhaul access points. Residential buyers in the United States and Germany are adopting these units within 18-month replacement cycles to support 4K streaming and low-latency gaming. The technology is collapsing traditional tiering between premium mesh nodes and economy extenders as throughput ratings converge above 5 Gbps.
The European Union's Radio Equipment Directive is tightening electromagnetic compatibility testing for 6 GHz devices, forcing manufacturers to redesign thermal management and shielding before market entry. Industrial consequence includes delayed product launches for mid-tier vendors lacking pre-certified reference designs. Small office and hospitality segments across Germany and France are responding by consolidating purchases around vendors with established CE marking pipelines.
Subscription-based network management is displacing one-time hardware transactions as buyers prioritize continuous security updates and parental control features. Direct sales channels and marketplace platforms are capturing this shift by bundling cloud services with hardware. The United States residential segment shows the strongest pivot, with buyers accepting annual fees for unified network dashboards across extender and router ecosystems.
Global Wi-Fi Range Extender Market Segmentation
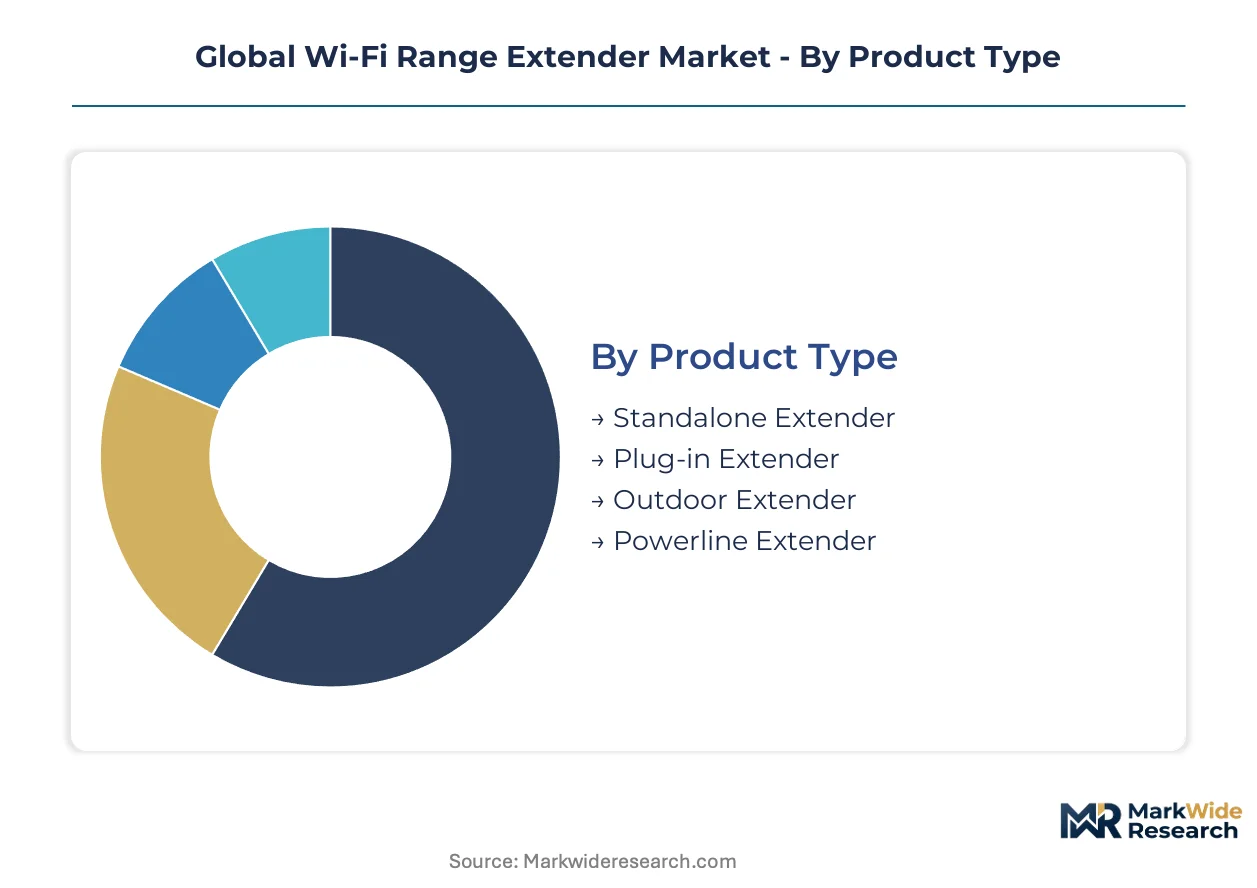
Wi-Fi range extender segmentation reveals how hardware form factors and spectrum capabilities map to distinct coverage gaps across residential, commercial, and outdoor environments. Buyers select configurations based on installation constraints, throughput requirements, and existing router compatibility.
Product Type:
Residential coverage gaps span detached structures, multi-floor layouts, and perimeter zones that demand specialized mounting and environmental sealing.
- Standalone Extender:Desktop units with dedicated power supplies and Ethernet backhaul ports deliver maximum throughput flexibility. Demand concentrates in United States suburban homes with basement offices and attic studios where wired router connections remain impractical.
- Plug-in Extender:Compact units occupying wall outlets dominate unit volumes through minimal installation friction. Germany and United States apartment dwellers favor these for kitchen and bedroom dead zones where furniture space is constrained.
- Outdoor Extender:Weather-sealed enclosures with IP ratings withstand temperature extremes and moisture exposure. Property owners in United States and German markets deploy these for detached garages, pool houses, and perimeter security camera networks.
- Powerline Extender:Units leveraging electrical wiring as backhaul transport suit buildings with thick masonry walls that attenuate wireless signals. Adoption clusters in older European housing stock and rural United States properties with sprawling footprints.
Established volume favors Plug-in Extender; emerging adoption favors Outdoor Extender.
Technology:
Cost tiers separate legacy spectrum equipment from premium units capturing regulatory allocations and latency-sensitive applications.
- Wi-Fi 5:802.11ac chipsets operating exclusively on 2.4 GHz and 5 GHz bands serve budget-conscious replacement cycles. Inventory clearance dominates emerging market channels as manufacturers redirect fabrication capacity toward newer standards.
- Wi-Fi 6:802.11ax implementations with OFDMA and target wake time capabilities support dense IoT deployments. United States and China residential buyers prioritize these for 50+ device households with simultaneous streaming and conferencing demands.
- Dual Band:Simultaneous 2.4 GHz and 5 GHz operation with dedicated backhaul and client service lanes preserves throughput integrity. Small office deployments across Germany and France favor this architecture for video conferencing stability.
- Tri Band:Additional 5 GHz or 6 GHz backhaul channels eliminate bandwidth contention in mesh configurations. Premium residential installations in United States and Chinese markets absorb these units for gaming and 4K streaming workflows.
Volume leadership sits with Dual Band; steepest expansion trajectory belongs to Tri Band.
End User:
Application intensity varies from intermittent residential streaming to always-on enterprise connectivity with service level requirements.
- Residential:Single-family and multi-unit dwellings with 10-75 connected endpoints represent the foundational demand base. Smart home ecosystem expansion in United States and Chinese markets drives replacement cycles as device counts outgrow legacy router coverage.
- Small Office:Professional services firms and remote work hubs with 5-25 employees require seamless handoff across conference rooms and open floor plans. Germany and United States markets show strongest uptake for mesh-compatible configurations.
- Large Office:Enterprise deployments with centralized IT management favor extenders as gap-fillers rather than primary architecture. Adoption is constrained by preference for wired access point infrastructure in new construction.
- Public Spaces:Hospitality venues, retail locations, and transportation hubs deploy extenders for guest network saturation. China's high-speed rail stations and airport terminals represent concentrated procurement for this segment.
Residential commands absolute volume; Small Office offers the most favorable margin structure.
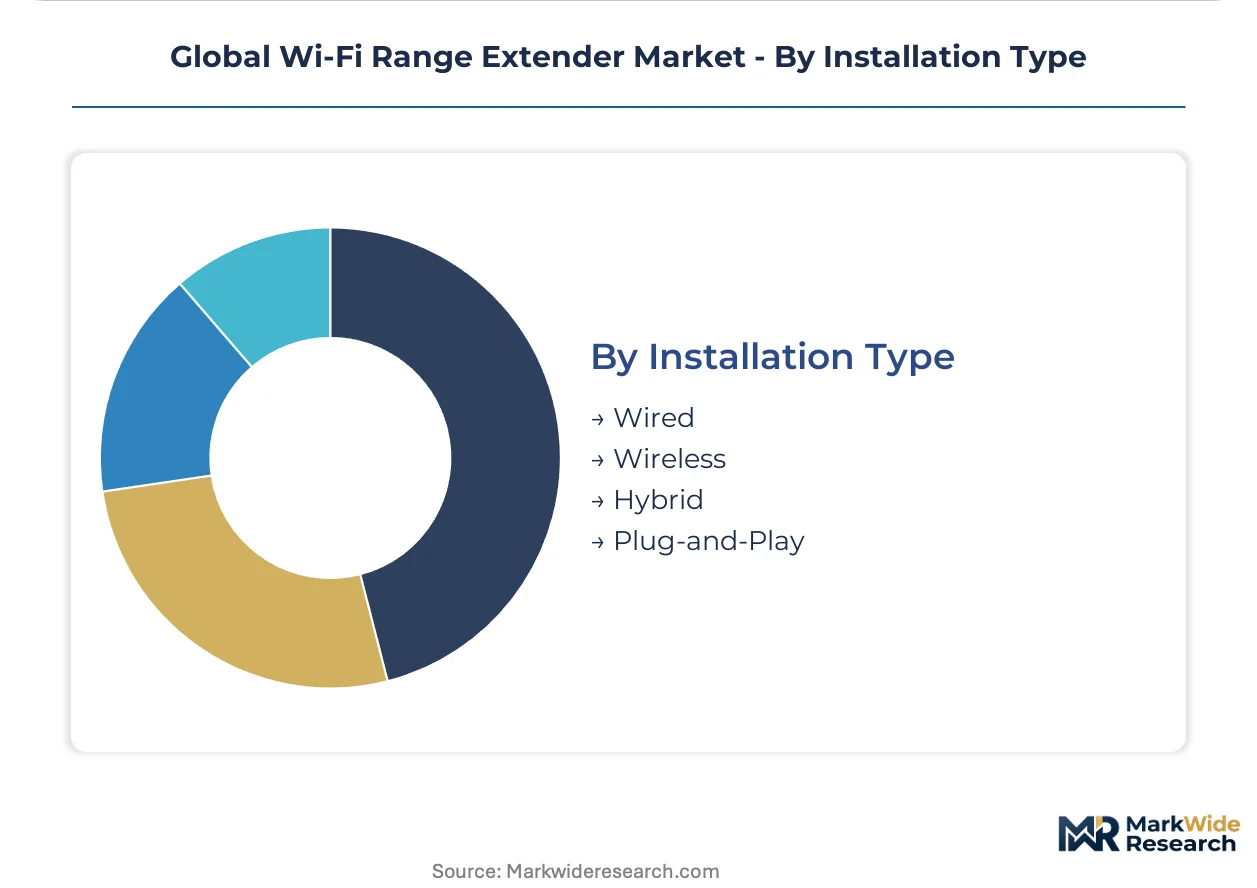
Installation Type:
Customer technical sophistication and infrastructure readiness determine configuration complexity tolerance.
- Wired:Ethernet backhaul connections deliver maximum throughput stability for stationary high-bandwidth endpoints. United States home office setups and German small business server closets favor this reliability.
- Wireless:Pure over-the-air repeater functionality suits renters and temporary deployments where cable routing is prohibited. Mass-market residential channels across all geographies move these units in highest volumes.
- Hybrid:Configurations supporting both Ethernet and wireless backhaul adapt to evolving infrastructure conditions. Professional installers in United States and European markets specify these for future-proofing client investments.
- Plug-and-Play:Automated setup via mobile applications with WPS pairing eliminates manual configuration. China's e-commerce platforms and United States big-box retail channels promote these for self-install consumer segments.
Wireless installation dominates transaction volume; Hybrid configurations are gaining share fastest among technically capable buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fiber-to-the-home deployment corridors in Germany, the United States, and China anchor demand concentration for Wi-Fi range extenders, as high-speed backhaul infrastructure creates in-building coverage gaps that discrete repeaters and mesh nodes must fill.
United States
Suburban smart home penetration and detached structure networking drive hardware refresh cycles toward Wi-Fi 6E and Wi-Fi 7 chipsets. FCC Part 15 rules govern 6 GHz unlicensed spectrum access, with recent allocations compelling equipment upgrades. The Dallas-Fort Worth metroplex and Austin technology corridor concentrate procurement for mesh-compatible extenders serving 50+ device households.
Germany
Multi-floor residential layouts in older housing stock and small office retrofits sustain demand for plug-in and powerline extenders. CE marking under the EU Radio Equipment Directive imposes stringent electromagnetic compatibility testing for 6 GHz devices. The Rhine-Ruhr industrial belt and Bavarian cities including Munich anchor distribution through specialized electronics retailers and direct-to-consumer platforms.
China
Massive fiber infrastructure rollout and dense urban apartment configurations create volume demand for cost-optimized extenders. MIIT enforces GB standards for wireless transmission power and frequency stability, diverging from FCC and CE protocols. Shenzhen's hardware manufacturing cluster and Shanghai's e-commerce logistics hubs concentrate both production and platform-based distribution.
India
Tier-2 city broadband expansion and government PLI scheme incentives for telecom equipment attract low-cost extender deployment. TRAI spectrum allocations shape device certification requirements distinct from European and North American regimes. Bangalore's technology corridor and Hyderabad's electronics manufacturing zones anchor assembly and testing operations for export-oriented vendors.
Japan
Compact residential footprints and high device density per household sustain premium demand for tri-band mesh extenders. METI industrial standards and JIS certification frameworks govern radio equipment compliance. Tokyo's metropolitan sprawl and Osaka-Kobe manufacturing districts concentrate procurement through integrated electronics retailers and carrier distribution channels.
Global Wi-Fi Range Extender Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying chipsets and reference designs to branded hardware vendors. The vendor base organizes into three recognizable tiers: multinational networking equipment houses with established e-commerce infrastructure, regional volume manufacturers competing through marketplace presence, and emerging market specialists leveraging localized platform partnerships. Consolidation pressure intensifies as Wi-Fi 7 certification timelines and multi-geography compliance costs favor players with pre-certified reference designs and established regulatory pipelines. Strategic moves concentrate on backward integration into semiconductor sourcing and geographic expansion through direct-to-consumer channel migration.
Within the multinational tier, NETGEAR Inc. and TP-Link Technologies Co. Ltd exemplify divergent positioning archetypes—one sustaining premium North American positioning through proprietary e-commerce infrastructure, the other anchoring volume sales through broad marketplace presence across multiple continents. Shenzhen Tenda Technology Co. Ltd occupies a distinct position among emerging market specialists, representing aggressive price competition through localized platform partnerships. These three entities collectively illustrate how vendor strategy fragments across premium positioning, scale-driven volume capture, and cost-optimized regional penetration.
| Leading Market Players |
|---|
| NETGEAR Inc. |
| TP-Link Technologies Co. Ltd |
| D-Link Corporation |
| Linksys Group Inc. |
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd |
| Shenzhen Tenda Technology Co. Ltd |
| ASUSTeK Computer Inc. |
| TRENDnet Inc. |
| Others |
Supply & Pricing Matrix
Shenzhen's semiconductor packaging and PCB fabrication clusters concentrate Wi-Fi chipset assembly capacity, granting contract manufacturers substantial leverage over branded hardware vendors negotiating bill-of-materials terms for extender production.
Pricing Analysis
Volume-discount tiering separates enterprise procurement contracts from direct-to-consumer transactions. Pricing stratifies across premium tri-band mesh units, standard dual-band plug-in models, and economy single-band legacy inventory. Cost compression in the economy tier intensifies because Chinese marketplace vendors absorb margin erosion to maintain platform visibility. Residential buyers in Germany and the United States show lowest price sensitivity for outdoor-rated extenders with IP certification.
Supply Chain Analysis
Upstream feedstock for advanced Wi-Fi 6E and Wi-Fi 7 chipsets draws from Taiwan and South Korea fabrication facilities, with China and Vietnam handling final assembly and testing. Key inputs include GaAs power amplifiers, high-frequency PCBs, and RF shielding materials. Single-source vulnerability concentrates in 6 GHz frontend module supply. Distribution runs through e-commerce platforms and specialized electronics retailers rather than traditional broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi range extender market is entering a cyclical recovery phase as FCC and EU spectrum reallocation forces hardware refresh cycles across residential and small office segments.
For Market Incumbents: Entrench mesh ecosystem compatibility through backward integration into cloud management software and pre-certified reference designs. Mesh system substitution from router manufacturers poses the primary demand threat. Certification investment in CE marking and FCC Part 15 pipelines preserves European and North American market access against emerging competitors lacking regulatory infrastructure. For New Entrants and Emerging Players: Build out cost-optimized Wi-Fi 6 extender portfolios targeting India's tier-2 city broadband expansion under TRAI spectrum rules. Outdoor extender applications in German and United States suburban markets represent the most penetrable white-space segment. Direct-to-consumer marketplace presence with automated mobile setup applications bypasses traditional channel barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with captive semiconductor sourcing relationships and established multi-geography certification pipelines. Long-term viability hinges on Wi-Fi 7 transition timing and software-defined radio development capabilities. Watch FCC and MIIT Wi-Fi 7 ratification schedules as the critical inflection signal for inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Certification Investment | FCC Part 15 and CE marking pre-approval accelerates product launch timelines ahead of regulatory ratification. |
| Mesh Software Platform Development | Cloud-based network management creates recurring revenue streams and locks in hardware ecosystem loyalty. |
| Outdoor Extender Product Line Expansion | IP-rated enclosures for United States and German suburban markets command premium pricing tolerance. |
| Direct-to-Consumer Channel Migration | Manufacturer e-commerce infrastructure displaces distributor margins and captures customer data ownership. |
| Semiconductor Supply Agreement | Long-term contracts with Taiwan and South Korea fabricators mitigate allocation constraints during demand surges. |
Research Methodology
Desk research of FCC spectrum allocation filings, EU Radio Equipment Directive guidance documents, and MIIT GB standard updates preceded structured interviews with RF engineering directors, e-commerce platform category managers, and semiconductor procurement leads at contract manufacturers. Secondary validation drew from customs trade data, SEC 10-K disclosures by networking equipment vendors, and broadband infrastructure deployment statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Assumptions held fixed include regulatory ratification schedules for Wi-Fi 7 certification, fiber-to-the-home deployment trajectories in Germany and China, and mesh system pricing parity with standalone extenders. The analytical framework modeled product type, technology generation, end-user segment, installation configuration, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates with cross-validation against historical replacement cycle patterns and IoT device density projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated router manufacturers into extender-displacement mesh systems would shift outcomes. Cross-checking against FCC equipment authorization databases and carrier procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Zero-Touch Provisioning Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Global Home Networking Device Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Optical Network Equipment Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Network Packet Broker Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Network Emulator Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Global Network Management Market
Network Technology
Network Performance Monitoring Market
Network Technology
Microduct Market