
 Gigabit Passive Optical Network (GPON) Market | 2026-2036
Gigabit Passive Optical Network (GPON) Market Size, Share, and Industry Trends Forecast 2026-2036
Gigabit Passive Optical Network (GPON) Market Foresight
Capital-intensity divergence between integrated system vendors and component specialists is reorganizing competitive tiers in GPON supply. Huawei sustains manufacturing scale across optical line terminals and splitters through captive silicon and optical component foundries. Nokia differentiates through wavelength division multiplexing overlays that extend existing fiber plant capacity for telecommunication providers. Calix competes by anchoring cloud-native software platforms that virtualize network management for internet service providers.
Gigabit Passive Optical Network denotes a point-to-multipoint fiber access architecture employing passive splitters to serve multiple subscribers from a single optical line terminal, typically operating at downstream rates of 2.488 Gbps and upstream rates of 1.244 Gbps under ITU-T G.984 specifications. Its primary purpose is to deliver high-bandwidth broadband to residential and business premises without active intermediate electronics, reducing operational expenditure for operators. Optical network terminals command the largest product volume as fiber-to-the-home deployments mature across developed markets, while wavelength division multiplexing technology captures expanding margin pools as operators seek to multiply per-fiber capacity without new cable pulls. Fiber-to-the-building applications are accelerating fastest in dense urban environments where horizontal wiring costs constrain full home fiberization.
The Federal Communications Commission's broadband labeling rules and the EU's Gigabit Infrastructure Act are reshaping equipment certification requirements and deployment timelines for network operators. China's Ministry of Industry and Information Technology enforces domestic GB standards that influence optical component specifications across Asia-Pacific supply chains. Stakeholders must monitor how national fiber subsidy programs and open-access network mandates alter procurement patterns for optical line terminals and splitters.
Market Dynamics
Telecommunication providers are consolidating fiber access infrastructure around wavelength division multiplexing overlays, compressing procurement timelines for optical line terminals as national broadband mandates harden deployment schedules.
Growth Catalysts
- ITU-T G.984 Standards Harmonization:Technical specifications for 2.488 Gbps downstream transmission are accelerating equipment interoperability testing across multi-vendor deployments.
- China's State-Backed Fiberization Programs:Domestic procurement quotas for optical line terminals are sustaining volume commitments through state-owned telecommunication operators.
- Cloud-Native Network Management:Software-defined access architectures are reducing operational expenditure for internet service providers managing distributed optical network terminals.
Market Restraints
- Passive Splitter Supply Concentration:Optical component foundry capacity concentrates in East Asian manufacturing clusters, exposing procurement timelines to regional logistics constraints.
- Copper Infrastructure Substitution Resistance:Legacy DSL and coaxial cable networks in aging urban buildings delay fiber-to-the-home penetration where horizontal rewiring costs exceed replacement thresholds.
- EU Gigabit Infrastructure Act Compliance Burden:Certification timelines for optical network terminals are extending as open-access network interoperability requirements multiply testing protocols.
Strategic Opportunities
- Rural Broadband Subsidy Programs:USDA Rural Utilities Service grants in the United States are funding fiber-to-the-premises builds in underpenetrated counties.
- XGS-PON Technology Convergence:10 Gbps symmetric transmission standards are creating upgrade pathways for operators seeking to multiplex residential and enterprise traffic on shared fiber plant.
- Pre-Connectorized Drop Cable Distribution:Factory-terminated fiber assemblies are reducing field labor requirements for internet service provider installation crews.
Industry Challenges
- Fiber Splicing Technician Scarcity:Precision fusion splicing skills required for single-mode fiber termination are outpacing vocational training program output in multiple markets.
- Legacy Network Integration Complexity:Interworking between GPON optical line terminals and existing Ethernet backhaul switches is requiring protocol gateway development.
- Optical Power Budget Certification Delays:Splitter loss calculations and optical time-domain reflectometer testing are extending pre-activation verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gigabit Passive Optical Network (GPON) Market |
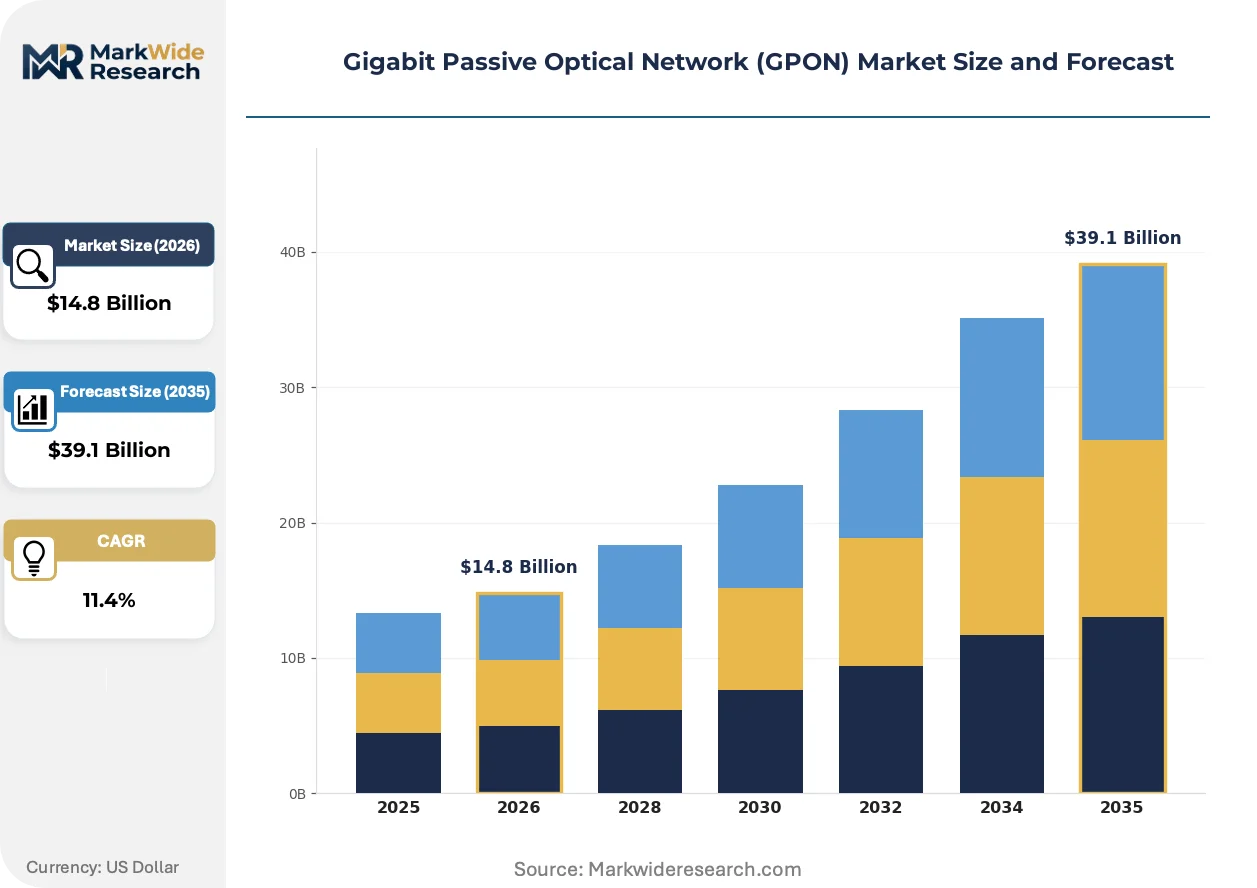
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Network Terminal, Optical Line Terminal, Splitter, Optical Distribution Frame Technology: Gigabit Ethernet, Wavelength Division Multiplexing, Time Division Multiplexing, Passive Optical Amplification Application: Fiber to the Home, Fiber to the Building, Broadband Access, Business Connectivity End User: Telecommunication Providers, Internet Service Providers, Data Centers, Government Agencies |
| Companies Covered | Fiberhome, ADTRAN, Huawei, Cisco Systems, DASAN Zhone Solutions, ZTE, Calix, NEC, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gigabit Passive Optical Network (GPON) Market Shifts & Advancements
Wavelength division multiplexing overlays are fragmenting equipment procurement patterns as operators seek capacity multiplication without cable plant replacement. Software-defined access architectures are compressing vendor lock-in cycles.
NG-PON2 technology is bifurcating the optical access market into residential and enterprise service tiers. The ITU-T G.989 standard enables 40 Gbps aggregate downstream capacity through tunable wavelength allocation. Major telecommunication providers in Japan and South Korea are deploying TWDM-PON overlays for business park connectivity. This technology is bifurcating supplier relationships as operators maintain separate procurement streams for residential GPON and enterprise NG-PON2 equipment.
The FCC's broadband nutrition label mandate is forcing optical network terminal manufacturers to disclose consistent performance metrics. Equipment vendors must now certify actual versus advertised throughput under standardized test conditions. Internet service providers in the United States are revising subscriber equipment bundles to meet October 2024 enforcement deadlines. This regulatory pressure is compressing margin structures for low-tier optical network terminal suppliers unable to meet disclosure precision requirements.
Subscription models for managed optical network terminals are displacing capital purchase arrangements among regional internet service providers. Monthly per-subscriber fees covering hardware, firmware updates, and remote diagnostics are replacing upfront CPE procurement. This shift is most visible in Germany and France where open-access fiber wholesalers are standardizing terminal specifications across retail service providers. The model reduces subscriber churn risk for operators while transferring obsolescence exposure to managed service vendors.
Gigabit Passive Optical Network (GPON) Market Segmentation
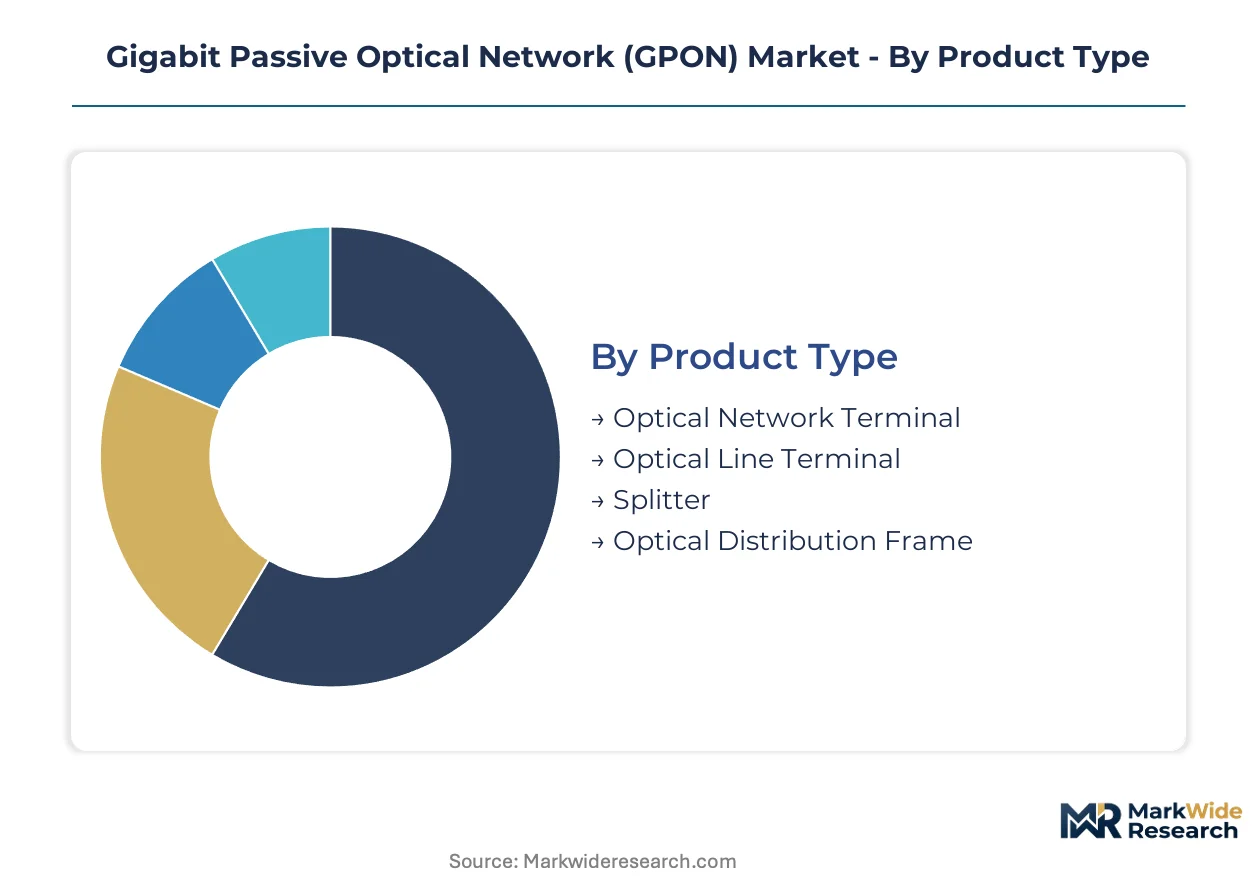
GPON equipment procurement patterns diverge sharply across product tiers, with optical line terminals capturing capital expenditure concentration while subscriber-side terminals drive volume scale. Technology overlays and application contexts further fragment supplier relationships as operators balance legacy fiber plant extension against greenfield deployment economics.
Product Type:
Margin pools concentrate in centralized infrastructure equipment where semiconductor integration and thermal management create differentiation barriers.
- Optical Line Terminal:Central office equipment aggregating subscriber traffic through passive splitter networks, typically housing 16-128 PON ports per chassis. China's state-owned telecommunication operators sustain procurement volume through MIIT-mandated fiberization quotas, compressing vendor qualification timelines for domestic suppliers.
- Optical Network Terminal:Subscriber premises equipment terminating fiber drops with integrated routing and voice gateway functions. Internet service providers in Germany and France are standardizing terminal specifications through open-access fiber wholesale models, displacing capital purchase arrangements with managed service subscriptions.
- Splitter:Passive optical components dividing downstream signals to multiple subscribers without electrical power. Foundry capacity concentrates in East Asian manufacturing clusters, exposing procurement to regional logistics constraints.
- Optical Distribution Frame:Physical fiber management infrastructure for central office and outside plant environments. Pre-connectorized variants are reducing field labor requirements for internet service provider installation crews.
Optical line terminal holds installed capacity. Optical network terminal is rotating up the share rankings.
Technology:
Equipment interoperability requirements under ITU-T standards are compressing proprietary differentiation windows across transmission architectures.
- Wavelength Division Multiplexing:Technology overlays enabling capacity multiplication on existing fiber plant through multiple optical wavelengths. Japanese and South Korean telecommunication providers are deploying TWDM-PON configurations for business park connectivity, creating separate procurement streams from residential GPON infrastructure.
- Gigabit Ethernet:Packet-based transmission standard bridging GPON optical line terminals with Ethernet backhaul switches. Protocol gateway development is extending interworking certification cycles as operators consolidate heterogeneous network layers.
- Time Division Multiplexing:Traditional upstream bandwidth allocation mechanism under ITU-T G.984 specifications. Legacy deployments in mature FTTH markets constrain upgrade pathway economics.
- Passive Optical Amplification:Signal boosting without electrical conversion for extended reach applications. Rural broadband subsidy programs in the United States are funding deployments in underpenetrated counties where optical power budgets challenge standard configurations.
Wavelength division multiplexing commands technology margin. Gigabit Ethernet is climbing the fastest in deployment velocity.
Application:
Deployment context determines labor cost structures and regulatory compliance burdens more than equipment specifications alone.
- Fiber to the Home:End-to-end fiber connectivity to individual residential premises. FCC broadband labeling rules are forcing optical network terminal manufacturers to disclose consistent performance metrics, compressing margin structures for suppliers unable to meet disclosure precision requirements.
- Fiber to the Building:Shared fiber infrastructure serving multiple dwelling units through in-building distribution. Dense urban environments in aging European cities are accelerating this model where horizontal rewiring costs constrain full home fiberization.
- Broadband Access:Generalized high-bandwidth connectivity encompassing residential and small business segments. USDA Rural Utilities Service grants are funding fiber-to-the-premises builds in underpenetrated United States counties.
- Business Connectivity:Dedicated fiber services for enterprise and wholesale applications. XGS-PON technology convergence is creating upgrade pathways for operators seeking to multiplex residential and enterprise traffic on shared fiber plant.
Fiber to the home holds installed capacity. Fiber to the building is gaining share fastest among application contexts.
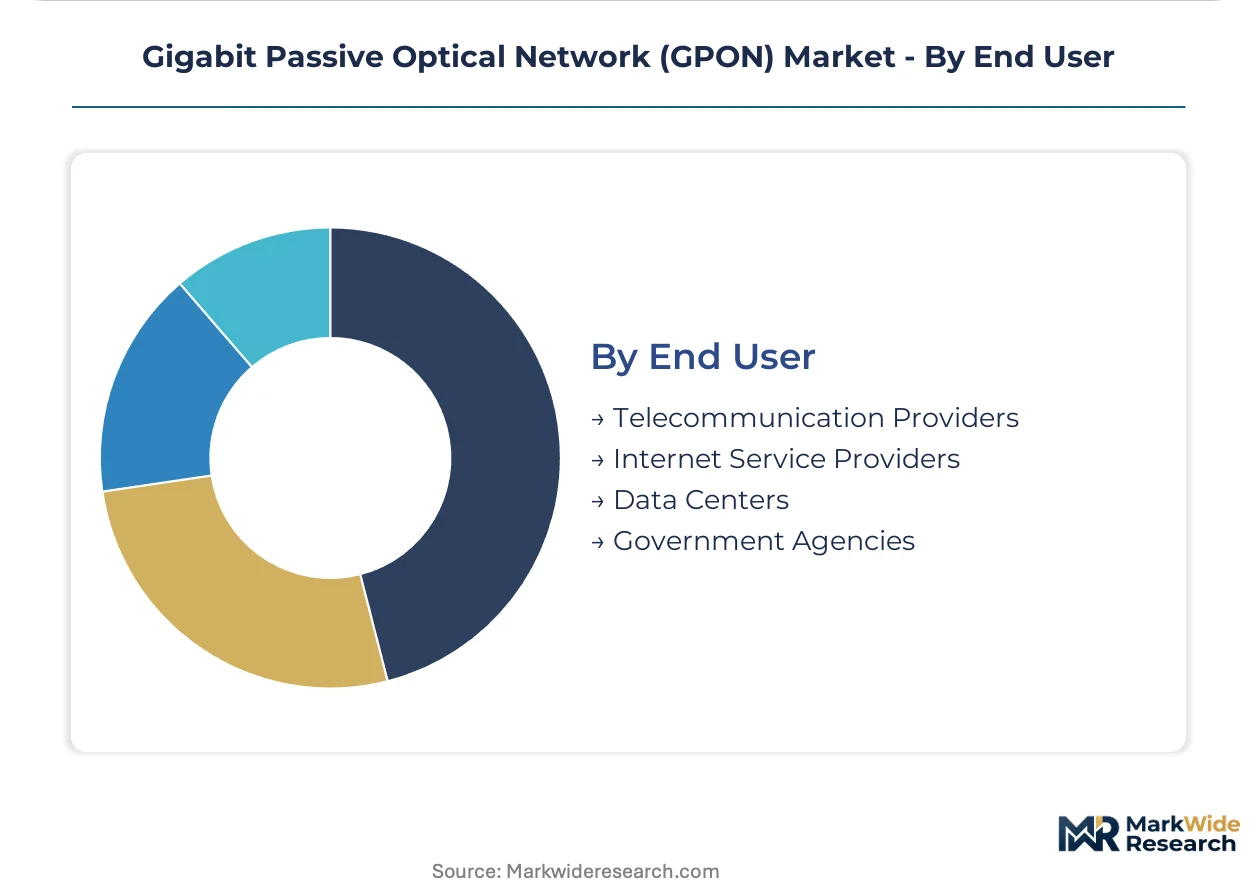
End User:
Procurement authority and network management complexity fragment customer relationships across infrastructure scale tiers.
- Telecommunication Providers:National-scale operators owning physical fiber infrastructure and central office assets. ITU-T G.984 standards harmonization is accelerating equipment interoperability testing across their multi-vendor deployments.
- Internet Service Providers:Retail service providers leasing wholesale fiber access or operating overbuild networks. Cloud-native network management architectures are reducing their operational expenditure through software-defined access platforms.
- Data Centers:Hyperscale and colocation facilities requiring high-capacity fiber interconnects. NG-PON2 technology is bifurcating supplier relationships as these operators maintain separate procurement streams from residential GPON equipment.
- Government Agencies:Public sector entities deploying fiber for administrative and educational connectivity. EU Gigabit Infrastructure Act compliance is extending their certification timelines as open-access network interoperability requirements multiply testing protocols.
Telecommunication providers hold installed capacity. Internet service providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese manufacturing clusters while procurement premiums persist in Western European markets. Equipment vendors command margin spreads of 40-60 basis points between Shenzhen-based foundries and Frankfurt deployment sites. This asymmetry is reshaping supplier qualification timelines across the GPON supply chain.
China
State-owned telecommunication operators drive procurement volume through MIIT-mandated fiberization quotas. The Ministry of Industry and Information Technology enforces domestic GB standards that cascade across Asia-Pacific component specifications. Shenzhen and Wuhan house optical component foundries supplying splitters and transceivers to regional network builds.
United States
USDA Rural Utilities Service grants fund fiber-to-the-premises builds in underpenetrated counties where optical power budgets challenge standard configurations. The FCC's broadband labeling rules force optical network terminal manufacturers to disclose consistent performance metrics. Texas and California lead state-level fiber subsidy programs diverging from federal procurement timelines.
Germany
Open-access fiber wholesale models standardize terminal specifications across retail service providers, displacing capital purchase arrangements with managed service subscriptions. The EU Gigabit Infrastructure Act extends certification timelines as interoperability requirements multiply testing protocols. Bavaria and North Rhine-Westphalia concentrate operator headquarters and central office infrastructure.
Japan
Telecommunication providers deploy TWDM-PON configurations for business park connectivity, creating separate procurement streams from residential GPON infrastructure. METI guidelines shape wavelength allocation standards under ITU-T G.989. Tokyo and Osaka anchor hyperscale data center interconnect demand driving NG-PON2 overlay investments.
South Korea
National broadband mandates harden deployment schedules for wavelength division multiplexing overlays compressing optical line terminal procurement timelines. The Korea Communications Commission enforces performance disclosure requirements paralleling FCC nutrition label mandates. Seoul Capital Area and Busan-Ulsan corridor concentrate fiber density metrics exceeding OECD averages.
Gigabit Passive Optical Network (GPON) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GPON supply chain. Integrated system vendors with captive silicon foundries dominate optical line terminal manufacturing scale while component specialists capture margin pools in wavelength-specific subsystems. Three archetypes define competitive positioning: state-affiliated equipment conglomerates with vertical manufacturing control, Western network infrastructure vendors differentiating through software overlays, and regional optical component specialists serving wholesale splitter markets. Consolidation pressure manifests through strategic partnerships for cloud-native management platforms and capacity expansion in pre-connectorized drop cable distribution.
Within the integrated infrastructure tier, Huawei and Nokia occupy positions reflecting divergent geographic market access and technology stack priorities. ZTE anchors the specialist-manufacturer segment alongside Fiberhome, both representing Chinese state-affiliated equipment production archetypes. Calix exemplifies the software-centric challenger model competing through cloud-native access platforms rather than captive hardware scale.
| Leading Market Players |
|---|
| Fiberhome |
| ADTRAN |
| Huawei |
| Cisco Systems |
| DASAN Zhone Solutions |
| ZTE |
| Calix |
| NEC |
| Nokia |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent at Shenzhen and Wuhan optical component clusters compress margin floors for passive splitters while amplifying pricing leverage for integrated terminal manufacturers with captive silicon capacity. This scale asymmetry between component specialists and system vendors concentrates procurement power among state-backed telecommunication operators in China, while European open-access mandates fragment pricing authority across wholesale-retail interfaces in Germany and France.
Pricing Analysis
Configured-to-order optical line terminals command 15-25 percent premiums over standard chassis configurations due to port density customization and thermal management specifications. The dominant pricing structure stratifies across premium, standard, and economy tiers tied to ITU-T G.984 certification grades and MIIT domestic standard compliance. Cost compression in economy-tier splitters intensifies as East Asian foundry expansion outpaces procurement volume growth from rural broadband programs. Internet service providers in Germany and France exhibit highest price sensitivity through subscription-based terminal procurement, while telecommunication providers in China absorb premiums for centralized infrastructure equipment.
Supply Chain Analysis
Strategic stockpiling of optical transceivers and pre-connectorized drop cables dominates procurement behavior among US internet service providers managing USDA Rural Utilities Service grant timelines, while Chinese state-owned operators favor just-in-time delivery synchronized to MIIT-mandated fiberization quotas. Manufacturing concentrates in China, South Korea, and Japan for optical components, with raw material dependencies spanning germanium for photodetectors, silica for fiber preforms, and rare-earth dopants for optical amplifiers. Single-source vulnerability in East Asian splitter foundries exposes procurement timelines to regional logistics constraints. Distribution runs through direct OEM relationships for optical line terminals and wholesale component markets for passive infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPON infrastructure sits in early-cycle expansion as national broadband mandates in the United States, European Union, and China harden deployment schedules and compress replacement timelines for legacy copper networks.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into optical component foundries, particularly for wavelength division multiplexing subsystems where Japanese and South Korean competitors are deploying TWDM-PON overlays. Defend position by accelerating cloud-native software platform development to counter Calix's virtualized network management threat. Prioritize certification investment for FCC broadband labeling compliance and EU Gigabit Infrastructure Act interoperability testing to extend vendor lock-in cycles. For New Entrants and Emerging Players: Anchor in rural broadband subsidy white space, specifically USDA Rural Utilities Service grant-funded counties where optical power budget challenges create demand for extended-reach passive optical amplification solutions. Target fiber-to-the-building applications in aging European urban cores where horizontal rewiring costs constrain full home fiberization. Pursue managed service subscription models displacing capital purchase arrangements among regional internet service providers in Germany and France. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with wavelength-specific subsystem expertise over commodity terminal manufacturers facing margin compression from Chinese state-affiliated production. Long-term viability across the next decade hinges on NG-PON2 upgrade pathway exposure and software-defined access architecture integration. Acquisition targets should demonstrate captive silicon capacity or cloud-native platform differentiation. Watch for inflection when XGS-PON procurement volumes cross symmetric 10 Gbps deployment thresholds in enterprise-residential converged traffic scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Access Platform Integration | Calix's software-defined architecture reduces operational expenditure for internet service providers managing distributed optical network terminals. |
| Wavelength Division Multiplexing Overlay Deployment | Japanese telecommunication providers deploy TWDM-PON configurations for business park connectivity, creating separate procurement streams from residential GPON. |
| Pre-Connectorized Drop Cable Manufacturing Scale-Up | Factory-terminated fiber assemblies reduce field labor requirements for USDA Rural Utilities Service grant-funded installation crews. |
| Backward Integration into Optical Component Foundries | Huawei sustains manufacturing scale through captive silicon and splitter production, compressing vendor qualification timelines for domestic Chinese procurement. |
| Regulatory Certification Pathway Investment | FCC broadband labeling compliance and EU Gigabit Infrastructure Act interoperability testing extend equipment vendor qualification barriers against low-tier suppliers. |
Research Methodology
Operator-level perspectives from central office engineers, fiber deployment project managers, optical component procurement leads, and wholesale network architects anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with telecommunication provider infrastructure planners and internet service provider technical directors, validated against secondary sources including FCC equipment authorization databases, MIIT GB standard filings, ITU-T G.984 specification documents, and EU Gigabit Infrastructure Act regulatory impact assessments. Bottom-up equipment shipment modeling triangulated against top-down national broadband mandate expenditure tracking.
Sensitivity analysis tested forecast robustness across deployment velocity scenarios for rural subsidy programs and technology migration pathways from GPON to XGS-PON and NG-PON2. The analytical framework segmented volume and value outputs across product type, technology overlay, application context, and end-user procurement authority throughout the projection horizon. CAGRs derived from polynomial trend fitting of historical optical line terminal procurement data, adjusted for replacement cycle compression under national fiberization mandates. Industry-specific inputs included MIIT-mandated fiberization quota trajectories and FCC broadband labeling enforcement timelines.
Material uncertainties — subsidy program funding continuity, trade restriction escalation on optical component tariffs, and fiber splicing technician training pipeline capacity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ITU-T standards harmonization velocity and open-access network mandate adoption rates across European markets. Revision becomes warranted when XGS-PON equipment procurement crosses threshold penetration in residential-service tier deployments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Netops Market
Network Technology
CPE Router Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Private Network Services Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Radio Modem Market
Network Technology
Virtual Router Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Managed Switches Market
Network Technology
Structured Cabling Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Global Network Probe Market
Network Technology
Protocol Analyzer Market
Network Technology
Europe Private 5G Network Market
Network Technology
Network Emulator Market
Network Technology
Wi-Fi Extender Market