
 Netops Market | 2026-2036
Netops Market Size, Share, and Industry Trends Forecast 2026-2036
Netops Market Foresight
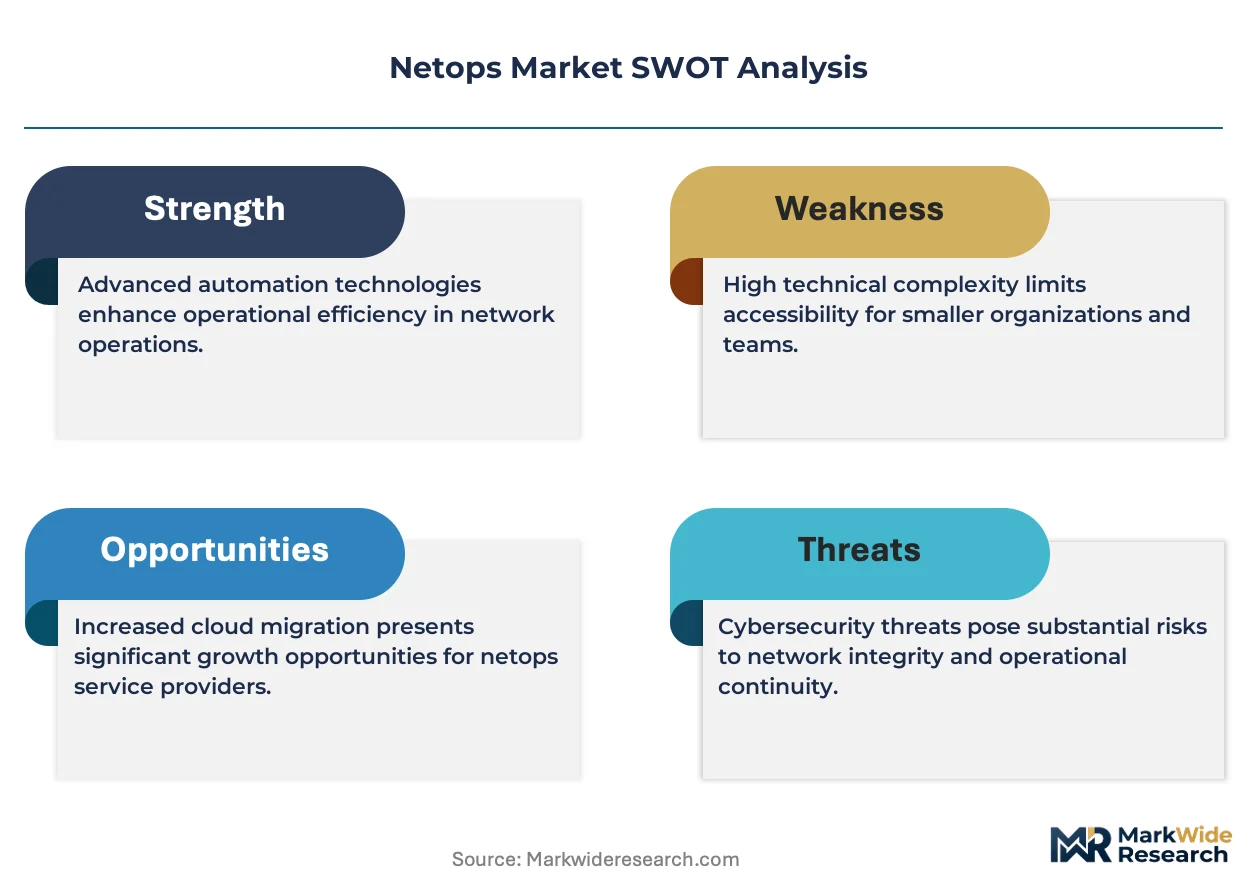
Cloud-native observability is fragmenting traditional monolithic network operations architectures into distributed, API-driven service meshes. Cisco Systems leverages its entrenched hardware footprint to extend software-layer control across hybrid environments. Broadcom anchors high-performance telemetry through its semiconductor-to-software stack. Datadog competes on developer-centric workflows that embed network metrics into CI/CD pipelines.
Netops encompasses the practices, tools, and platforms used to monitor, manage, and automate enterprise network infrastructure, typically processing telemetry streams exceeding one million events per second for real-time fault detection and remediation. The discipline serves industrial and commercial purposes by ensuring service-level agreement compliance, minimizing mean time to resolution, and enabling predictive capacity planning. Cloud deployment now leads segment growth as enterprises abandon capital-intensive on-premise network management centers, while managed services capture expanding margin pools by assuming operational accountability for multi-vendor environments. Security solutions within the solution dimension show accelerated adoption as zero-trust architectures mandate continuous network verification.
The FCC shapes US market access through cybersecurity labeling requirements for network management software, while the EU AI Act imposes conformity assessments on automated decision-making within network operations. ISO 27001 and IEC 62443 standards govern product security baselines, forcing vendors to embed compliance into development lifecycles rather than retrofit controls post-deployment. Stakeholders must decide whether to build sovereign network operations stacks or accept dependency on transnational cloud platforms.
Market Dynamics
Cloud-native observability is fragmenting traditional monolithic network operations architectures into distributed, API-driven service meshes, forcing vendors to rebuild telemetry pipelines for containerized environments.
Growth Catalysts
- NIS2 Directive:European enterprises must deploy continuous network monitoring to meet mandatory incident reporting timelines, expanding managed Netops contracts across financial and energy sectors.
- Zero-trust mandates:US federal agencies and defense contractors require microsegmentation visibility, driving demand for real-time flow analysis and identity-aware networking tools.
- Legacy infrastructure modernization:German manufacturing and automotive clusters are replacing SNMP-based monitoring with streaming telemetry to support industrial IoT scale.
Market Restraints
- Semiconductor supply concentration:Specialized NPUs and SmartNICs for high-velocity packet processing depend on Taiwan and South Korea foundry capacity, creating procurement bottlenecks.
- EU AI Act conformity costs:Automated remediation systems face mandatory algorithmic impact assessments, extending sales cycles by 6-12 months for European deployments.
- Skills scarcity:Site reliability engineering expertise combining network engineering with Kubernetes administration commands 40% salary premiums, constraining enterprise self-build options.
Strategic Opportunities
- Edge computing expansion:5G network slicing and multi-access edge computing sites in India lack mature observability, creating greenfield deployment potential for cloud-native platforms.
- Convergence of AIOps and Netops:Unified correlation of network telemetry with application performance data opens cross-sell opportunities in DevOps-centric enterprises.
- US cybersecurity labeling:FCC requirements for software bill of materials disclosure favor vendors with pre-certified supply chains, creating compliance-based differentiation.
Industry Challenges
- Multi-vendor integration complexity:Enterprises operate Cisco, Arista, Juniper, and white-box switches simultaneously, requiring expensive normalization layers for unified visibility.
- Certification timeline compression:ISO 27001 and IEC 62443 audits for network management software now demand continuous compliance evidence rather than point-in-time assessments.
- Observability data gravity:Petabyte-scale telemetry retention costs conflict with GDPR data minimization principles, forcing architectural trade-offs in European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netops Market |
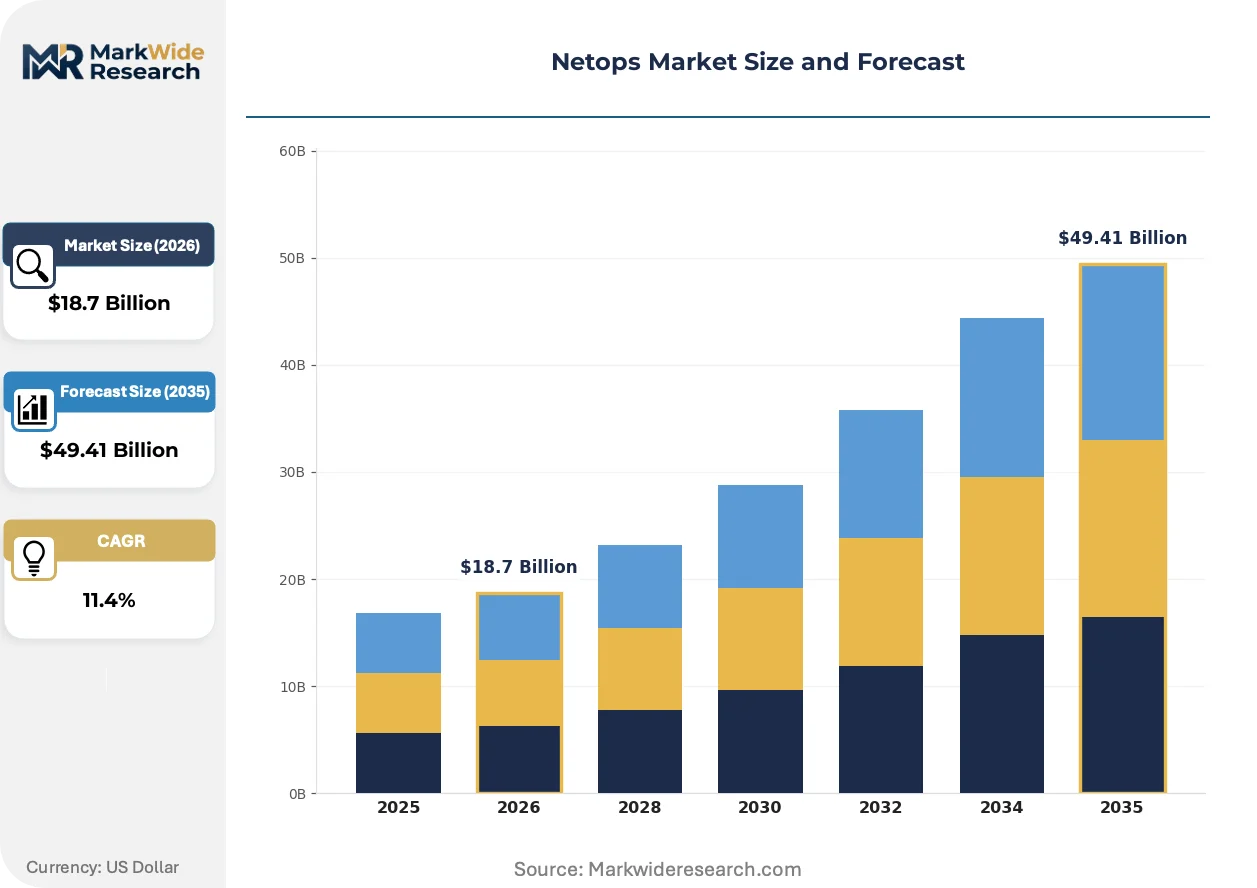
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Multi-Cloud Service Type: Managed Services, Consulting, Technical Support, Training End User: SMEs, Large Enterprises, Government Agencies, Educational Institutes Solution: Network Automation, Performance Monitoring, Security Solutions, Data Analytics |
| Companies Covered | Cisco Systems, Broadcom, Juniper Networks, Hewlett Packard Enterprise, SolarWinds, Dynatrace, Datadog, LogicMonitor, Arista Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netops Market Shifts & Advancements
Telemetry architectures are undergoing fundamental restructuring as streaming protocols replace polling-based monitoring, while regulatory pressure forces security capabilities into every layer of network operations tooling.
eBPF-based kernel instrumentation is migrating from niche cloud-native environments to mainstream enterprise data centers. Large financial services institutions in London and Singapore now deploy eBPF for zero-overhead network visibility without agent installation. This migration from traditional SNMP and flow-based monitoring collapses the boundary between infrastructure and application observability, compressing vendor differentiation around data plane programmability.
The EU AI Act imposes conformity assessments on automated decision-making within network operations, classifying self-healing systems as high-risk when they affect critical infrastructure. Vendors must now document algorithmic logic and maintain human-in-the-loop capabilities for remediation actions. German utilities and French telecommunications operators are most affected, restructuring procurement specifications to mandate explainable AI clauses.
Site reliability engineering teams now specify network observability requirements directly, bypassing traditional network operations centers. Platform engineering budgets in technology and fintech verticals absorb Netops tooling as infrastructure-as-code primitives. This shift concentrates purchasing authority with developers rather than infrastructure specialists, reshaping vendor sales motions toward API-first documentation and self-service onboarding in North American and Nordic markets.
Netops Market Segmentation
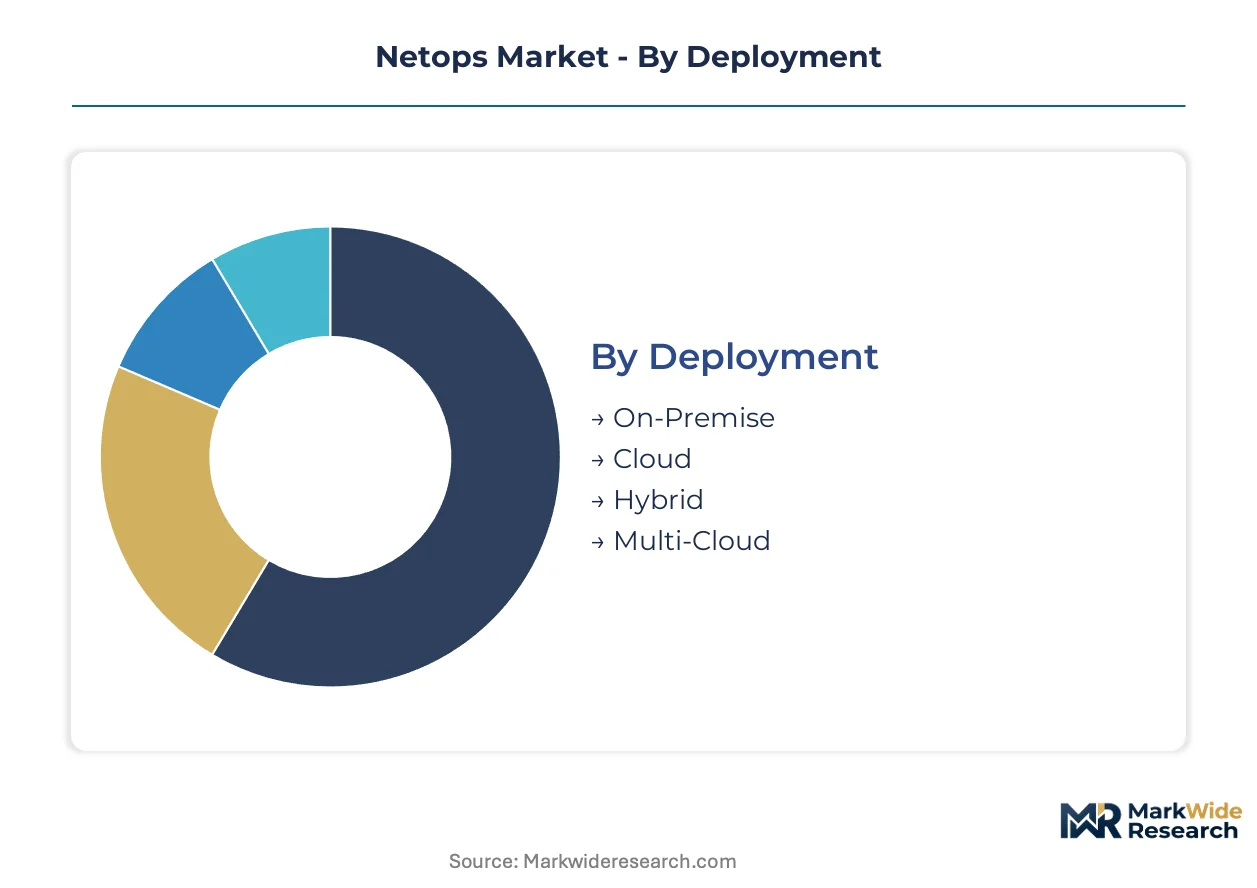
Netops procurement patterns diverge sharply across deployment architectures and operational maturity levels. Understanding these fault lines reveals where vendor investments concentrate and which customer profiles justify premium pricing.
Deployment:
Cost tier determines architectural commitment, with capital intensity separating self-managed infrastructure from consumption-based alternatives.
- On-Premise:Organizations retain full hardware ownership for packet processing and telemetry aggregation within dedicated data centers. German automotive manufacturers and Japanese industrial conglomerates favor this model for sub-millisecond latency requirements in automated production lines.
- Cloud:Consumption-based delivery eliminates data center capital expenditure while embedding network operations within hyperscaler ecosystems. US fintech startups and Singaporean digital banks deploy cloud-native observability to align operational expenditure with transaction volume fluctuations.
- Hybrid:Workload placement follows data sovereignty and performance requirements across owned and leased infrastructure. French energy utilities and Canadian healthcare networks use hybrid deployments to keep patient and operational data on-premise while bursting analytics to cloud.
- Multi-Cloud:Orchestration layers abstract vendor-specific APIs to prevent single-provider dependency. Australian mining operators and Brazilian agribusiness conglomerates distribute network management across AWS, Azure, and regional cloud providers for geographic resilience.
On-Premise commands the established base. The steepest expansion runs through Cloud.
Service Type:
Margin structure varies by accountability depth, with operational transfer pricing highest where vendors assume direct infrastructure responsibility.
- Managed Services:Vendors assume 24/7 operational accountability for multi-vendor network estates, including SLA-backed remediation. EU NIS2 Directive compliance deadlines are accelerating managed services adoption among European financial institutions requiring mandatory incident reporting capabilities.
- Consulting:Advisory engagements cover architecture design, tool selection, and operational transformation roadmapping. UK telecommunications operators and Indian IT services exporters commission consulting to rationalize legacy SNMP environments toward streaming telemetry.
- Technical Support:Break-fix and escalation services maintain vendor software and hardware deployments. South Korean semiconductor fabricators and Taiwanese electronics manufacturers prioritize technical support for specialized SmartNIC and NPU troubleshooting.
- Training:Certification programs address the 40% salary premium for site reliability engineering expertise combining network engineering with Kubernetes administration. US federal contractors and Israeli cybersecurity firms invest heavily in training to build internal observability capabilities.
Managed Services captures the margin concentration. Training expands most quickly as skills scarcity intensifies.
End User:
Customer type shapes procurement authority, with developer-centric buying patterns disrupting traditional infrastructure-centric sales motions.
- SMEs:Mid-market enterprises consume Netops through bundled SaaS offerings with minimal customization. Nordic professional services firms and Benelux logistics operators favor pre-configured observability templates over bespoke implementations.
- Large Enterprises:Complex multi-site networks demand unified visibility across Cisco, Arista, Juniper, and white-box switching estates. Swiss pharmaceutical multinationals and Saudi Aramco's downstream operations command the largest contract values for normalized telemetry platforms.
- Government Agencies:Zero-trust mandates and classified network segmentation drive specialized procurement. US federal agencies and UK Ministry of Defence facilities require microsegmentation visibility with FedRAMP and NCSC accreditation.
- Educational Institutes:Research universities operate unique high-bandwidth scientific computing networks alongside standard campus infrastructure. CERN in Switzerland and the US National Laboratories deploy custom Netops for particle physics data transfer optimization.
Large Enterprises command the established base. Government Agencies are gaining share fastest as zero-trust mandates harden.
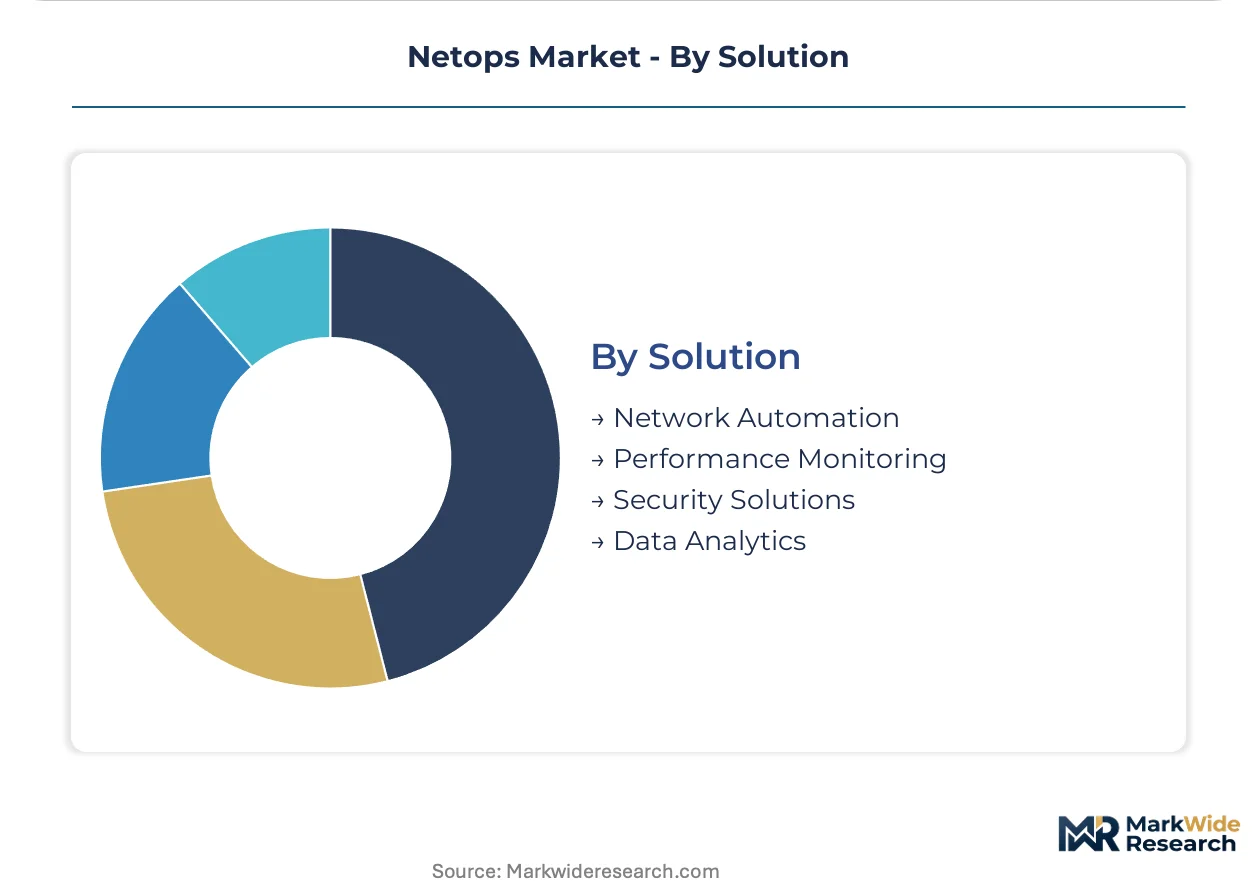
Solution:
Application criticality determines pricing power, with security-adjacent capabilities capturing premium positioning.
- Network Automation:Infrastructure-as-code primitives enable version-controlled configuration management and self-healing remediation. Platform engineering teams at US technology companies and Nordic fintechs now specify automation requirements directly, bypassing traditional network operations centers.
- Performance Monitoring:Real-time fault detection processes telemetry streams exceeding one million events per second. German utilities and French telecommunications operators restructure procurement specifications to mandate explainable AI clauses for automated remediation under EU AI Act conformity assessments.
- Security Solutions:Zero-trust architectures mandate continuous network verification through identity-aware networking and microsegmentation. US defense contractors and Israeli critical infrastructure operators drive accelerated adoption as cyber-physical convergence intensifies.
- Data Analytics:Predictive capacity planning correlates historical telemetry patterns with workload growth projections. Indian IT services exporters and Brazilian digital banks leverage analytics for multi-tenant infrastructure optimization.
Performance Monitoring commands the established base. Security Solutions shows the steepest expansion trajectory as zero-trust architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered network automation platforms to automotive and industrial buyers across the European Union, while the United States supplies cloud-native observability stacks to financial services institutions in London and Singapore.
United States
Federal zero-trust mandates and defense contractor microsegmentation requirements drive procurement of identity-aware networking tools. The FCC cybersecurity labeling program imposes software bill of materials disclosure obligations on network management vendors. Silicon Valley platform engineering teams and Washington DC federal integrators concentrate demand for API-first observability primitives.
Germany
Automotive manufacturing clusters and industrial IoT scale requirements accelerate replacement of SNMP-based monitoring with streaming telemetry. The EU AI Act conformity assessments extend sales cycles for automated remediation systems serving critical infrastructure. Munich and Stuttgart automotive headquarters command normalized telemetry platforms across multi-vendor Cisco, Arista, and white-box switching estates.
United Kingdom
Telecommunications operators commission consulting engagements to rationalize legacy monitoring architectures toward cloud-native pipelines. NCSC accreditation requirements shape procurement for classified network segmentation in defense facilities. London financial services institutions deploy eBPF-based kernel instrumentation for zero-overhead visibility without agent installation.
India
IT services exporters leverage predictive analytics for multi-tenant infrastructure optimization across global client bases. TRAI regulations govern data localization requirements for network telemetry retention. Bangalore and Hyderabad technology campuses absorb Netops tooling as infrastructure-as-code primitives within platform engineering budgets.
Singapore
Digital banks deploy cloud-native observability to align operational expenditure with transaction volume fluctuations across ASEAN markets. The Monetary Authority of Singapore imposes resilience requirements on critical technology service providers supporting financial infrastructure. Marina Bay financial district and Changi digital corridor concentrate demand for real-time fault detection exceeding one million events per second.
Netops Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates around entrenched hardware incumbents extending software-layer control, semiconductor-to-software stack integrators, and developer-centric SaaS platforms. Strategic archetypes include infrastructure incumbents leveraging installed base, telemetry specialists anchoring high-performance data planes, and API-first platforms embedding network metrics into CI/CD workflows. Dominant competitive moves encompass strategic partnerships for multi-cloud orchestration and portfolio diversification into security-adjacent capabilities.
Within the infrastructure incumbent tier, Cisco Systems and Juniper Networks occupy positions anchored by hardware footprint extension into hybrid environments. Broadcom exemplifies the semiconductor-to-software integration archetype through its telemetry stack spanning specialized NPUs and SmartNICs. Datadog represents the developer-centric platform model, sitting within the API-first observability segment that bypasses traditional network operations centers.
| Leading Market Players |
|---|
| Cisco Systems |
| Broadcom |
| Juniper Networks |
| Hewlett Packard Enterprise |
| SolarWinds |
| Dynatrace |
| Datadog |
| LogicMonitor |
| Arista Networks |
| Others |
Supply & Pricing Matrix
Taipei and Hsinchu semiconductor clusters anchor global SmartNIC and NPU fabrication capacity, concentrating upstream bargaining power among Taiwanese foundries serving telemetry-intensive Netops deployments. This geographic chokepoint transmits cost volatility downstream to observability platform vendors competing on packet-processing performance.
Pricing Analysis
Next-generation eBPF-based instrumentation commands 35-50% premiums over legacy SNMP polling suites, while prior-generation flow-based tools face commoditization in mid-market accounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by telemetry throughput ceiling and AI-driven remediation capability. Pricing pressure stems from hyperscaler self-build alternatives compressing commercial software margins. SMEs exhibit acute price sensitivity favoring consumption-based SaaS, whereas German automotive manufacturers absorb premium positioning for sub-millisecond latency guarantees.
Supply Chain Analysis
US export controls on advanced semiconductors constrain SmartNIC shipments to Chinese network equipment vendors, fragmenting procurement strategies. Taiwan, South Korea, and the United States concentrate specialized NPU fabrication, while memory components draw from Korean and Japanese suppliers. Single-source vulnerability concentrates in 7nm and below process nodes for high-velocity packet processing silicon. Distribution runs through direct OEM relationships for large enterprises and cloud marketplaces for developer-centric deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netops represents a service-attach opportunity where managed services and training revenues expand faster than hardware telemetry appliance sales, recasting vendor economics toward recurring operational accountability.
For Market Incumbents: Entrench hybrid cloud orchestration capabilities to defend against API-first observability platforms bypassing traditional network operations centers. Extend software-layer control through strategic certification investments in ISO 27001 and IEC 62443 to capture EU NIS2 Directive compliance budgets. Anchor high-performance telemetry through captive SmartNIC supply relationships mitigating Taiwan foundry concentration risk. For New Entrants and Emerging Players: Indian 5G network slicing and multi-access edge computing sites offer greenfield deployment potential lacking mature observability infrastructure. Target developer-centric platform engineering budgets in Nordic fintechs and US technology companies where procurement authority has shifted from infrastructure specialists to site reliability engineering teams. Lead with infrastructure-as-code primitives and self-service onboarding to bypass entrenched channel relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because multi-vendor integration complexity creates acquisition value for normalized telemetry platforms spanning Cisco, Arista, Juniper, and white-box estates. Target semiconductor-to-software stack specialists with telemetry differentiation at the data plane layer. Watch for EU AI Act conformity assessment bottlenecks extending European sales cycles as an inflection signal for managed services preference over self-build alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified correlation of network telemetry with application performance data opens DevOps-centric cross-sell opportunities. |
| Acquisition of Specialist Firm | Semiconductor-to-software stack targets address SmartNIC supply concentration and telemetry differentiation gaps. |
| Strategic Partnership | Multi-cloud orchestration alliances prevent single-provider dependency for Australian mining and Brazilian agribusiness operators. |
| Geographic Expansion | Edge computing sites in India lack mature observability, creating greenfield deployment potential for cloud-native platforms. |
| Product Launch | eBPF-based kernel instrumentation addresses London financial services demand for zero-overhead visibility without agent installation. |
Research Methodology
Initial hypotheses were tested against primary input from network operations directors, site reliability engineering leads, platform engineering managers, and hyperscaler infrastructure procurement officers and refined through secondary validation. Primary fieldwork combined structured interviews with telemetry architects at financial services institutions and automotive manufacturers with secondary analysis of hyperscaler capex disclosures, FCC cybersecurity labeling documentation, and EU NIS2 Directive implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across deployment models, service types, and end-user categories.
Demand-supply balance framing anchored the forecast framework, modeling adoption curves for cloud-native observability against semiconductor foundry capacity constraints for specialized packet-processing silicon. Segmentation dimensions spanned deployment architecture, operational maturity level, and regulatory compliance intensity. CAGRs derived from weighted scenario analysis incorporating EU AI Act conformity timeline uncertainty and zero-trust mandate rollout pace across US federal agencies. Industry-specific inputs included TRAI data localization requirements and Monetary Authority of Singapore resilience standards.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscalers into proprietary telemetry stacks would shift outcomes from baseline projections. Material shifts in Taiwan semiconductor export restrictions or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Global Active Network Management Market
Network Technology
Intelligent Network Management Market
Network Technology
Data Center Switches Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
CPE Router Market
Network Technology
Sand Lane Systems Market
Network Technology
Enterprise Routers Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Digital Repeater Market
Network Technology
Mobile Accelerator Market
Network Technology
Europe SD-WAN Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Microduct Market