
 Global Wireless Printers Market | 2026-2036
Global Wireless Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Printers Market Foresight
EU Ecodesign regulations for imaging equipment is consolidating demand around energy-efficient wireless printer portfolios. HP Inc. leverages its Instant Ink subscription platform to lock in recurring revenue across home office deployments. Canon anchors its competitiveness through proprietary imageRUNNER ADVANCE cloud connectivity stacks. Epson differentiates via PrecisionCore Heat-Free technology that reduces power draw during high-volume wireless jobs.
Wireless printers are peripheral devices that receive print commands via radio-frequency protocols including Wi-Fi 802.11ax, Bluetooth 5.0, and NFC touch-to-pair, eliminating physical tethering to host computers. These systems employ embedded system-on-chip architectures with dedicated print processors, typically supporting resolutions from 600 x 600 dpi in enterprise laser units to 5760 x 1440 dpi in photographic inkjet configurations, serving distributed document workflows across un-tethered office environments. Inkjet wireless printers occupy the largest installed base among product types due to lower hardware acquisition costs, though laser wireless units capture disproportionate margin pools in large enterprise fleets where cost-per-page economics dominate procurement. All-in-One wireless configurations represent the fastest-expanding product category as SMB buyers consolidate scanning, copying, and faxing into single networked devices. Wi-Fi connectivity leads the connectivity dimension but NFC-enabled tap-to-print is gaining traction in hospitality and healthcare settings where guest or patient data isolation matters.
The EPA ENERGY STAR program and EU RoHS directives constrain material selection and standby power budgets for wireless printers sold in North America and Europe. Japan's METI enforces Top Runner standards that push manufacturers toward lower-consumption RF modules and sleep-state engineering. China's GB standards for electromagnetic compatibility add certification layers for brands sourcing from Shenzhen and Dongguan manufacturing clusters. Stakeholders must weigh regulatory compliance investments against the margin compression from commoditized entry-level hardware.
Market Dynamics
Enterprise procurement of cloud-managed print fleets is consolidating vendor relationships while the EU Green Deal's ecodesign requirements force hardware redesigns across imaging equipment portfolios. This dual pressure from procurement centralization and regulatory compliance is restructuring competitive positioning in wireless printer supply.
Growth Catalysts
- EU Ecodesign Mandates:Energy-efficiency requirements for imaging equipment under the EU Green Deal are consolidating demand around low-power wireless printer portfolios. Procurement officers in Germany and France now specify standby power thresholds below 1 watt.
- Healthcare NFC Adoption:Tap-to-print protocols are displacing credential-based authentication in US hospital systems where HIPAA-compliant patient data isolation requires physical proximity verification before document release.
- Wi-Fi 6E Proliferation:The 6 GHz spectrum expansion in Japan and South Korea is enabling high-throughput wireless print streams for 4K medical imaging and architectural renderings without LAN congestion.
Market Restraints
- Semiconductor Supply Concentration:RF system-on-chip modules for wireless printers concentrate in TSMC and Samsung foundries, creating vulnerability to Taiwan Strait logistics disruptions.
- Raw Material Cost Volatility:Rare earth elements in precision stepper motors for laser units face price swings tied to Chinese export quota adjustments under MIIT oversight.
- Smartphone Scanning Substitution:Document capture apps on iOS and Android devices are compressing demand for standalone all-in-one wireless units in home office segments.
Strategic Opportunities
- India SMB Digitization:The country's PLI scheme for electronics manufacturing is attracting wireless printer assembly investments to serve underpenetrated small-business clusters in Bangalore and Hyderabad.
- Print-as-a-Service Convergence:Subscription models combining hardware, cloud management, and consumables are opening recurring revenue streams in US distributed enterprise fleets.
- Zero-Trust Security Integration:Convergence of wireless print protocols with IEEE 802.1X network access control is creating premium positioning for vendors serving US federal contractor environments.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers proficient in real-time operating systems for print processors is delaying product cycles at mid-tier manufacturers.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with EPA ENERGY STAR, EU RoHS, and China's GB electromagnetic standards extends time-to-market by 8-14 months for new SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Printers Market |
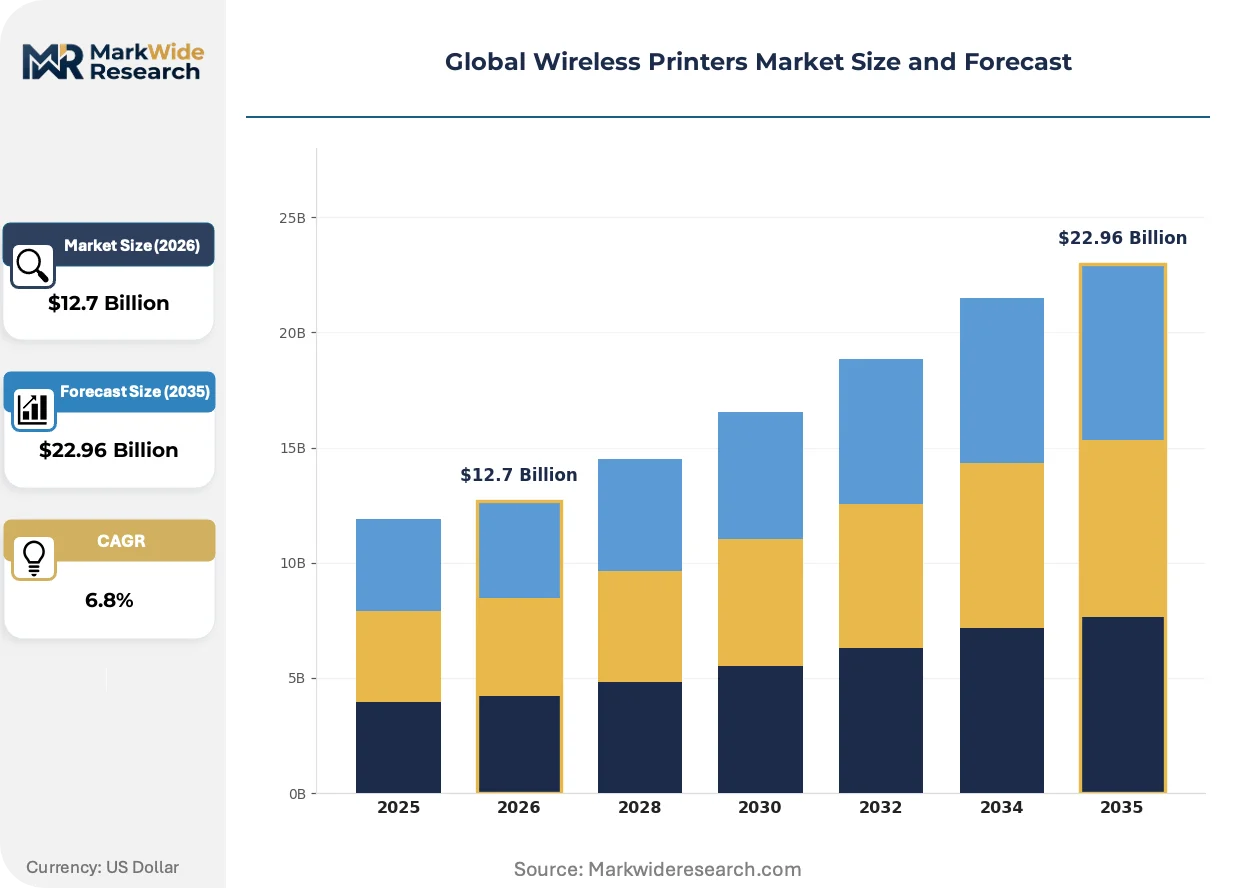
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, All-in-One, Thermal Connectivity: Wi-Fi, Bluetooth, NFC, USB End User: Residential, Small Office, Large Enterprise, Educational Institutions Usage Environment: Home Office, Commercial, Industrial, Mobile |
| Companies Covered | HP Inc., Canon, Epson, Brother International, Xerox, Ricoh, Lexmark, Konica Minolta, Kyocera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Printers Market Shifts & Advancements
Heat-free inkjet architectures and AI-driven predictive maintenance are redefining hardware specifications while regulatory pressure on standby power consumption accelerates design turnover across manufacturer portfolios.
PrecisionCore Heat-Free technology is expanding into high-volume enterprise wireless deployments by eliminating thermal cycling in piezoelectric printheads. Financial services and legal firms in London and New York are adopting these systems for 10,000-plus monthly page volumes where reduced power draw supports ESG reporting requirements. The technology is compressing total cost of ownership calculations against laser alternatives in cost-per-page procurement evaluations.
The EU F-Gas Regulation phase-down is restricting refrigerant options in cooling systems for high-speed laser fuser units, forcing manufacturers to redesign thermal management architectures. This constraint most heavily impacts production lines serving German industrial print fleets where continuous-duty cycles demand sustained fuser temperatures. Vendors are responding with ceramic heating element substitutions and redesigned airflow geometries.
Managed print service contracts are unbundling hardware ownership from consumables fulfillment and remote monitoring, disrupting traditional distributor relationships in US healthcare and education verticals. Value-added resellers in Texas and California are pivoting toward consultative fleet optimization rather than box-moving margins. This behavioral shift concentrates purchasing authority at regional system integrators with cloud platform certifications.
Global Wireless Printers Market Segmentation
Wireless printer procurement varies sharply across deployment contexts. Certification requirements, connectivity protocols, and duty-cycle specifications fragment vendor portfolios into distinct addressable pockets with incompatible technical standards.
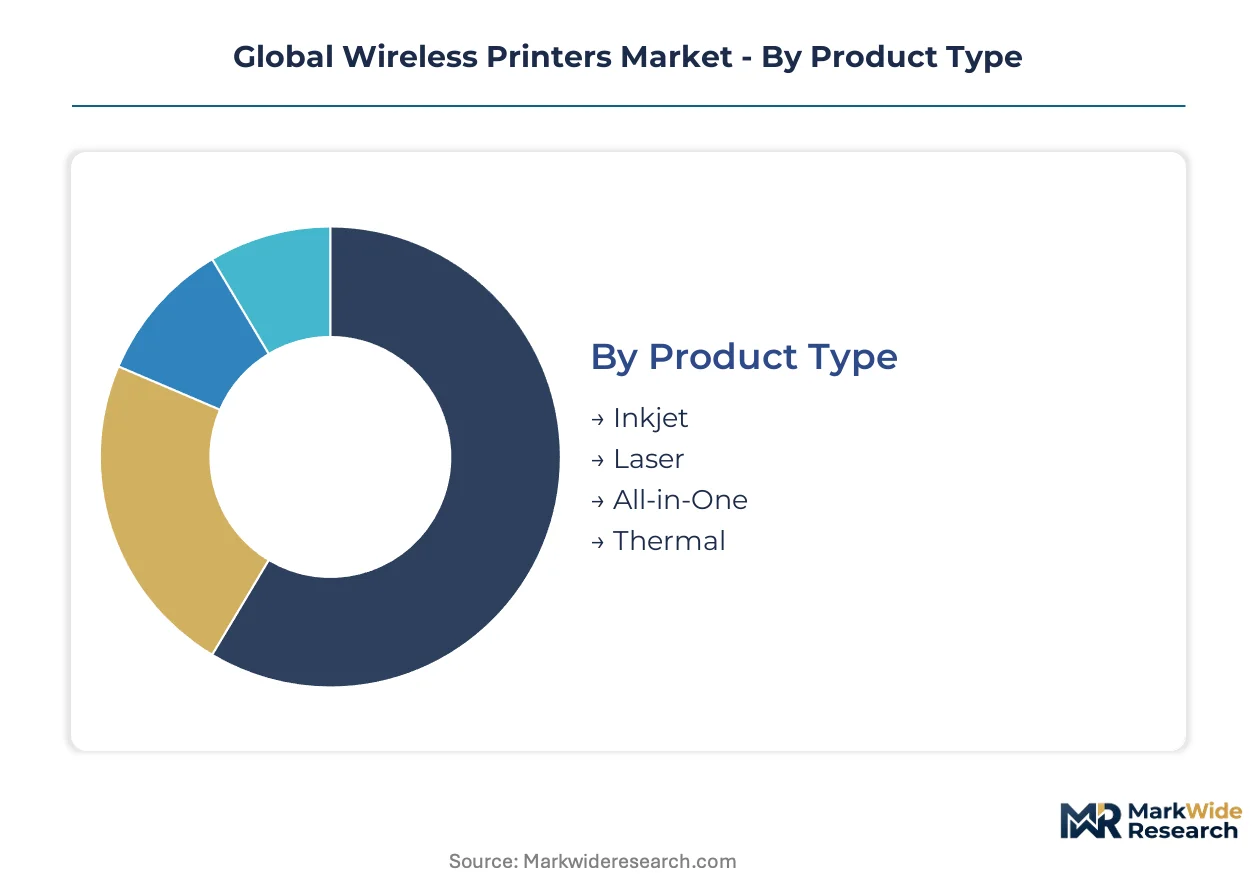
Product Type:
EPA ENERGY STAR and EU RoHS compliance burdens concentrate on laser and inkjet segments with active heating elements, while thermal units face fewer material restrictions but limited addressable demand.
- Inkjet:Piezoelectric or thermal printhead architectures deposit aqueous or solvent-based inks onto porous substrates. German and French procurement officers now specify standby power below 1 watt under EU Green Deal ecodesign mandates, compressing margins on entry-level hardware.
- Laser:Electrophotographic imaging employs organic photoconductor drums and toner fusion at 180-200°C. US healthcare systems in Texas and California favor these units for HIPAA-compliant fleet standardization despite higher acquisition costs.
- All-in-One:Integrated scanning, copying, and fax modules share RF connectivity backbones. SMB clusters in Bangalore and Hyderabad drive assembly investments under India's PLI scheme for electronics manufacturing.
- Thermal:Direct thermal or thermal transfer mechanisms eliminate consumable complexity for receipt and label applications. Logistics hubs in Shenzhen and Dongguan integrate these into mobile printing workflows.
Leading the category by volume: Inkjet. Growing fastest: All-in-One.
Connectivity:
Cost tiering separates premium protocol stacks from commodity implementations, with enterprise-grade security modules commanding 3-4x hardware premiums over consumer equivalents.
- Wi-Fi:802.11ax (Wi-Fi 6) and emerging 6E implementations in Japan and South Korea enable 4K medical imaging streams without LAN congestion. Financial services firms in London and New York specify WPA3-Enterprise for zero-trust network integration.
- Bluetooth:5.0 and 5.3 Low Energy variants support proximity-locked print release in hospitality settings. Pairing latency constraints limit adoption beyond 10-meter range requirements.
- NFC:Tap-to-pair protocols displace credential-based authentication in US hospital systems where physical proximity verification satisfies HIPAA patient data isolation requirements.
- USB:Wired fallback connectivity persists in air-gapped federal contractor environments where IEEE 802.1X network access control blocks all RF transmission.
Deploying most widely: Wi-Fi. Expanding most quickly: NFC.
End User:
Application-specific duty cycles and page-volume thresholds determine whether subscription or CapEx procurement models dominate segment economics.
- Residential:Home office deployments prioritize hardware acquisition cost over total cost of ownership. Document capture apps on iOS and Android devices are compressing demand for standalone units in this segment.
- Small Office:SMB buyers consolidate scanning, copying, and faxing into single networked devices with cloud-managed print fleet capabilities.
- Large Enterprise:Cost-per-page economics dominate procurement with managed print service contracts unbundling hardware ownership from consumables fulfillment.
- Educational Institutions:K-12 and university systems in Texas and California require FERPA-compliant print release stations with authenticated pull-printing.
Generating highest revenue per unit: Large Enterprise. Climbing the fastest: Small Office.
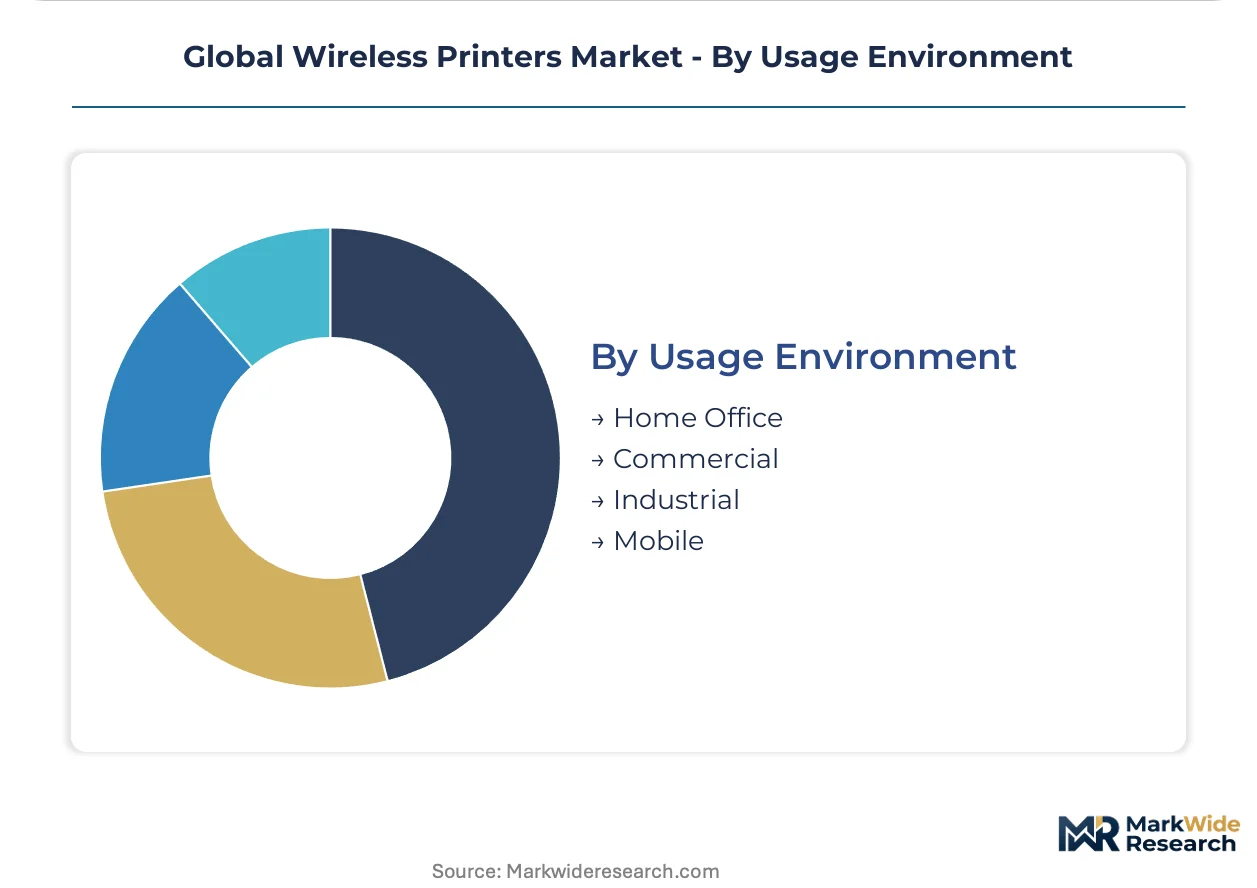
Usage Environment:
Geographic concentration of demand clusters in the United States, Germany, and Japan where distributed workforces require secure mobile printing infrastructure.
- Home Office:Residential-grade hardware with consumer Wi-Fi security protocols serves remote workers in suburban US markets. Subscription ink models lock in recurring revenue across these deployments.
- Commercial:General office environments in London and New York specify 10,000-plus monthly page volumes with ESG-reportable power draw metrics.
- Industrial:Continuous-duty cycles in German manufacturing fleets demand sustained fuser temperatures with ceramic heating element substitutions under EU F-Gas Regulation phase-down constraints.
- Mobile:Field service technicians and logistics operators in Shenzhen and Dongguan manufacturing clusters deploy battery-powered thermal units with Bluetooth tethering.
Addressing largest installed base: Commercial. Gaining share fastest: Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China's coastal electronics clusters while consumption spreads across distributed workforce hubs in the United States, Germany, and Japan. This production-consumption divide shapes trade flows and regulatory compliance investments across the value chain.
United States
Healthcare systems in Texas and California drive HIPAA-compliant fleet standardization for secure mobile printing infrastructure. The EPA ENERGY STAR program constrains standby power budgets for hardware sold across federal procurement channels. Value-added resellers in Dallas and Los Angeles are pivoting toward consultative fleet optimization rather than traditional distributor margins.
Germany
Industrial print fleets demand continuous-duty cycles with sustained fuser temperatures under EU F-Gas Regulation phase-down constraints. The EU Green Deal's ecodesign requirements force standby power thresholds below 1 watt for imaging equipment procurement. Manufacturing facilities in Bavaria and North Rhine-Westphalia are adopting ceramic heating element substitutions to maintain compliance.
Japan
METI enforces Top Runner standards that push manufacturers toward lower-consumption RF modules and sleep-state engineering for enterprise deployments. The 6 GHz spectrum expansion enables high-throughput wireless print streams for 4K medical imaging without LAN congestion. Electronics clusters in Tokyo and Osaka anchor R&D investments for next-generation Wi-Fi 6E implementations.
China
GB standards for electromagnetic compatibility add certification layers for brands sourcing from Shenzhen and Dongguan manufacturing clusters. MIIT oversight of rare earth export quotas creates price volatility in precision stepper motors for laser units. Assembly investments are expanding to serve underpenetrated small-business demand in Bangalore and Hyderabad through India's PLI scheme.
India
The PLI scheme for electronics manufacturing is attracting wireless printer assembly investments to serve small-business clusters in Bangalore and Hyderabad. Central bank liquidity provisions support working capital for SMB fleet procurement. Regional system integrators in Delhi-NCR and Mumbai are building cloud platform certifications to capture managed print service contracts.
Global Wireless Printers Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with established imaging portfolios. Tier-one players leverage subscription platforms and cloud connectivity stacks to lock in recurring revenue across enterprise fleets. Mid-tier specialists compete on heat-free architectures and niche connectivity protocols. Dominant competitive moves include strategic partnerships with cloud management providers and portfolio diversification into print-as-a-service offerings.
Within the diversified conglomerate tier, HP Inc. and Canon exemplify scale-driven positioning through integrated hardware-subscription ecosystems. Epson occupies a specialist position emphasizing proprietary piezoelectric architectures. These three anchors represent divergent strategic bets: recurring revenue lock-in through consumables platforms, enterprise cloud stack integration, and thermal efficiency differentiation respectively.
| Leading Market Players |
|---|
| HP Inc. |
| Canon |
| Epson |
| Brother International |
| Xerox |
| Ricoh |
| Lexmark |
| Konica Minolta |
| Kyocera |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in managed print services are consolidating regional dealer networks across Texas and California, tightening pricing discipline while compressing hardware margins through volume-based procurement leverage against Shenzhen assembly lines.
Pricing Analysis
Margin tightening in enterprise laser segments reflects procurement officers specifying sub-1-watt standby thresholds under EU Green Deal mandates. Three-tier pricing structure across premium, standard, and economy levels separates cloud-managed fleet subscriptions from transactional hardware sales. Cost-down pressure on entry-level inkjet units accelerates because smartphone scanning apps are compressing residential replacement cycles. SMB buyers in Bangalore and Hyderabad exhibit highest price sensitivity, while US healthcare systems prioritize HIPAA-compliant authentication modules over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from German industrial print fleets are mandating qualification of ceramic heating element suppliers beyond single-source Japanese vendors. RF system-on-chip modules draw from TSMC foundries in Taiwan and Samsung facilities in South Korea, while precision stepper motors rest on rare earth supply from Chinese export quotas under MIIT oversight. Single-source vulnerability in Taiwan Strait logistics creates contingency planning overhead. Distribution runs through value-added resellers pivoting toward consultative fleet optimization in Dallas and Los Angeles markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless printer market is becoming a vertical-integration race as players pursue captive supply of PrecisionCore printhead architectures and proprietary cloud connectivity stacks to escape commoditized hardware margins.
For Market Incumbents: Cement subscription lock-in through Instant Ink-style consumables platforms that reduce customer churn across home office deployments. Defend against smartphone scanning substitution by embedding AI-driven document enhancement in all-in-one hardware. Prioritize backward integration into piezoelectric printhead manufacturing to protect margin pools from Korean component suppliers. For New Entrants and Emerging Players: Direct-to-SMB digital channels offer lowest customer acquisition cost entry into India's underpenetrated Bangalore and Hyderabad clusters. White-space exists in NFC-enabled tap-to-print for US hospital systems requiring HIPAA-compliant physical proximity verification. Lead with zero-trust security integration and IEEE 802.1X certification to bypass entrenched reseller relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier specialists with heat-free inkjet IP in Japan and Germany where ESG reporting requirements are accelerating fleet refresh decisions. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Watch for inflection when EU F-Gas Regulation phase-down forces ceramic heating element redesigns across laser portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | HP's Instant Ink locks recurring revenue across distributed US home office deployments. |
| Heat-Free Technology Licensing | Epson's PrecisionCore expansion challenges laser dominance in London financial services print fleets. |
| Zero-Trust Security Certification | IEEE 802.1X convergence opens federal contractor procurement channels previously blocked to foreign vendors. |
| India PLI Assembly Investment | Bangalore and Hyderabad manufacturing clusters capture SMB digitization demand with localized fulfillment. |
| Ceramic Heating Element Substitution | Bavarian industrial print fleets maintain EU F-Gas compliance without continuous-duty cycle degradation. |
Research Methodology
Document review covered SEC 10-K filings from imaging equipment manufacturers, EU Ecodesign regulatory impact assessments, and India PLI scheme disclosure documents, complemented by interviews with enterprise fleet procurement managers, managed print service operators, and RF module design engineers. Primary fieldwork engaged hospital biomedical engineering directors in Texas and California, German industrial facility managers in Bavaria and North Rhine-Westphalia, and electronics manufacturing specialists in Shenzhen and Dongguan. Secondary validation drew from EPA ENERGY STAR certification databases, Japan METI Top Runner standard filings, and China GB electromagnetic compatibility test reports. Bottom-up unit shipment estimates triangulated against top-down consumables revenue analysis.
Segmented outputs across the projection horizon modeled product type splits between inkjet, laser, all-in-one, and thermal configurations; connectivity protocol adoption curves for Wi-Fi 6E, NFC, and Bluetooth 5.3; and end-user segmentation spanning residential, small office, large enterprise, and educational institutions. CAGRs were derived from regression analysis against historical replacement cycles, regulatory compliance deadlines, and smartphone substitution elasticity coefficients. Industry-specific inputs included rare earth export quota volatility under MIIT oversight and EU F-Gas refrigerant phase-down schedules.
Inputs from Japanese electronics R&D consortia and German industrial print fleet operators were available through the study window; gaps in real-time Taiwan Strait logistics disruption data introduce uncertainty bands around RF module cost assumptions. Deviation in China rare earth export policy or TSMC foundry allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Digital Paper System Market
Printing Technology
Digital Presses Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Professional Printers Market
Printing Technology
Printing Machinery Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Digital Franking Machine Market
Printing Technology
ID Card Printers Market
Printing Technology
Photo Printing Market
Printing Technology
RFID Printer Market
Printing Technology
Cloud Print Market
Printing Technology
Card Printers Market
Printing Technology
Digital Printing Market
Printing Technology
Book Printing Service Market