
 Serverless Architecture Market | 2026-2036
Serverless Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Serverless Architecture Market Analysis
The capability gap between hyperscaler infrastructure investments and mid-tier platform engineering is rotating competitive dynamics across the serverless landscape. Amazon Web Services leverages its Lambda ecosystem and edge computing integration to sustain developer loyalty across enterprise accounts. Microsoft Azure anchors hybrid cloud serverless deployments through Azure Functions and Kubernetes event-driven autoscaling. Google Cloud Platform differentiates with Cloud Run's container-native approach and tight BigQuery integration for data-intensive workloads.
Serverless architecture eliminates server management by executing code in ephemeral, event-triggered containers that scale automatically from zero to thousands of concurrent instances measured in millisecond cold-start latency. Its primary commercial purpose is converting fixed infrastructure costs into variable consumption economics while accelerating application deployment cycles. Public cloud deployment models dominate current revenue as enterprises prioritize managed service reliability over operational control, though multi-cloud configurations represent the fastest-expanding segment as organizations distribute vendor risk across Function as a Service and Event-Driven Computing implementations. Backend as a Service retains mature margin pools in mobile application development where pre-built authentication and database APIs reduce time-to-market.
FedRAMP authorization requirements in the United States, GDPR data residency mandates from European regulators, and ISO 27001 certification standards collectively shape vendor qualification timelines and enterprise procurement decisions. The EU AI Act introduces additional algorithmic transparency obligations for serverless-hosted machine learning inference workloads that process personal data. Stakeholders must monitor evolving sovereign cloud regulations and cross-border data flow restrictions that could fragment previously unified global serverless footprints into jurisdiction-specific deployments.
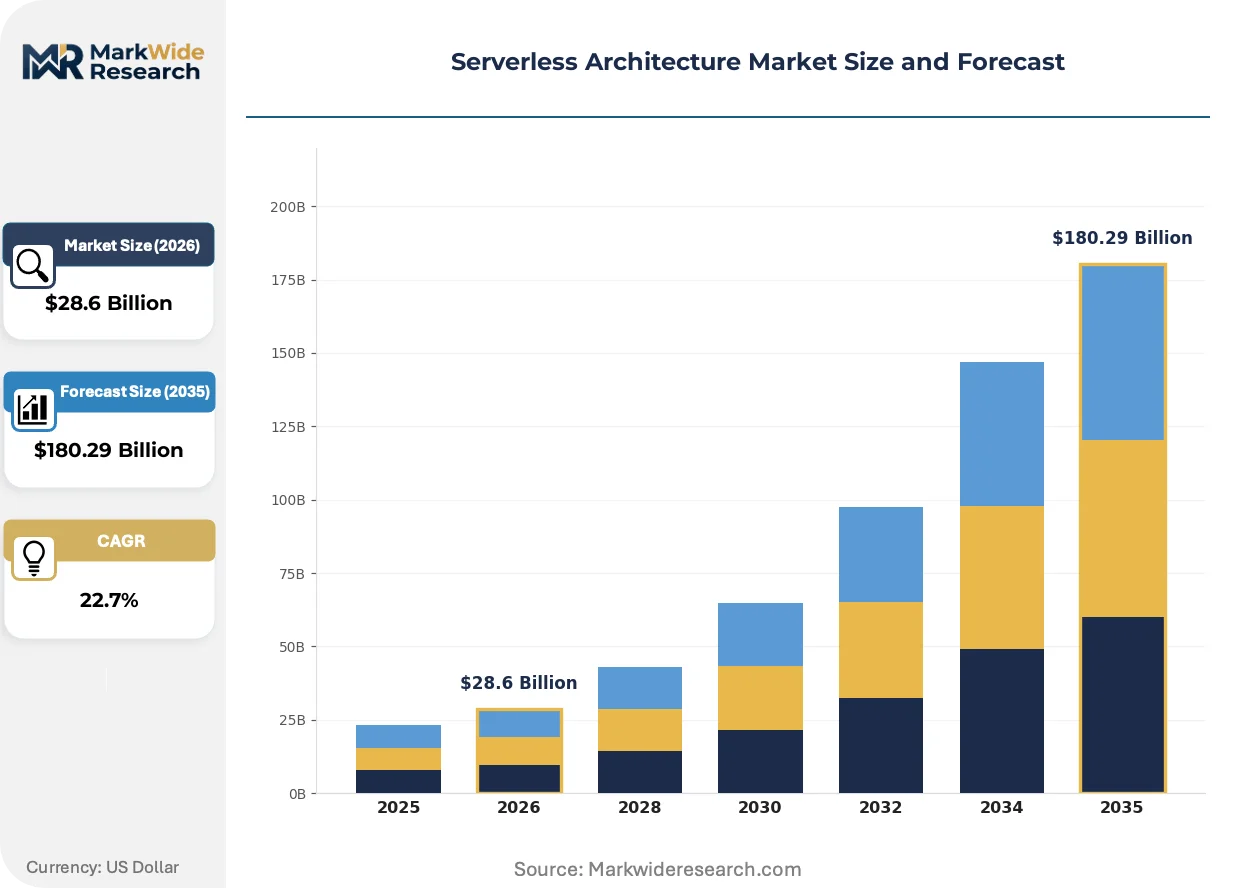
Market Dynamics
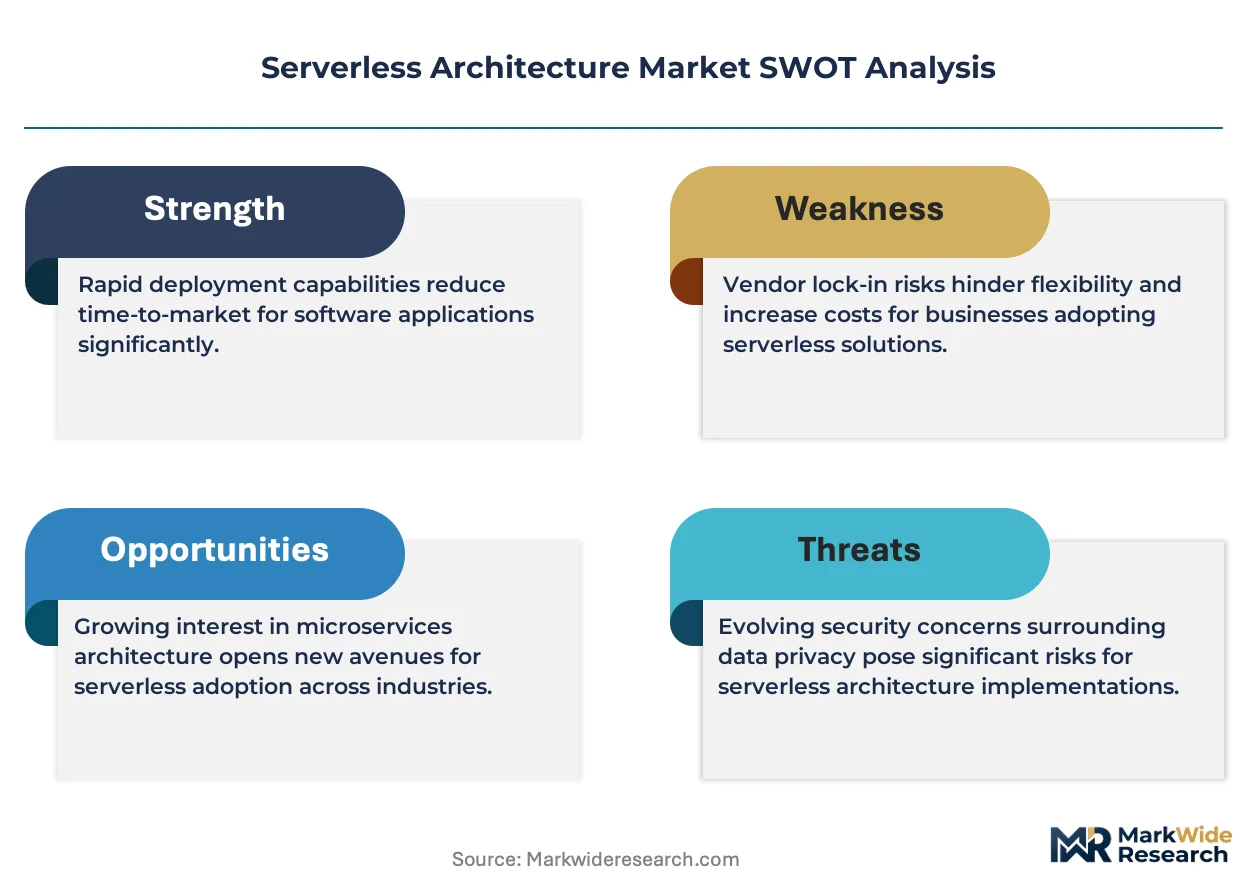
Hyperscaler infrastructure investments are compressing margins for mid-tier platform providers while function-as-a-service platforms capture enterprise workloads from traditional virtualized environments. This capital concentration is rotating competitive dynamics toward ecosystem lock-in and developer tooling sophistication.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for machine learning inference workloads are accelerating enterprise migration to managed serverless environments with built-in audit trails.
- Financial services real-time processing:Payment networks and trading platforms are adopting event-driven architectures to eliminate infrastructure provisioning delays during transaction spikes.
- Edge computing convergence:Distributed function deployment is enabling sub-50-millisecond response times for IoT telemetry processing and autonomous system coordination.
Market Restraints
- Cold-start latency thresholds:Millisecond-scale initialization delays prevent serverless adoption in high-frequency trading and industrial control systems where deterministic response is mandatory.
- Vendor concentration risk:Three hyperscalers control over eighty percent of function-as-a-service capacity, creating single-point-of-failure exposure for multi-region applications.
- Data egress cost structures:Cross-availability-zone traffic pricing creates unpredictable spend volatility for data-intensive workloads with distributed storage patterns.
Strategic Opportunities
- Sovereign cloud deployments:Germany, France, and Spain are mandating data residency for public sector workloads, creating localized serverless infrastructure requirements outside hyperscaler core regions.
- Container-native standardization:Kubernetes-based event-driven autoscaling is converging with serverless function packaging, enabling portable workload migration across cloud boundaries.
- Backend-as-a-Service mobile expansion:Pre-built authentication and database APIs are penetrating Southeast Asian fintech applications where developer scarcity constrains custom backend construction.
Industry Challenges
- Observability tooling gaps:Distributed tracing across ephemeral function instances requires specialized expertise that most enterprise DevOps teams have not yet developed.
- Legacy integration complexity:Mainframe and monolithic application dependencies force hybrid architectures that compromise the cost and operational benefits of pure serverless migration.
- FedRAMP authorization timelines:US federal agencies face 12-18 month certification cycles that delay serverless adoption for classified and controlled unclassified workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serverless Architecture Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $180.29 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Function as a Service, Backend as a Service, Event-Driven Computing, API Management End User: Small Enterprises, Medium Enterprises, Large Enterprises, Startups Application: Web Applications, Mobile Applications, Data Processing, IoT Applications |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, Alibaba Cloud, Oracle Cloud, IBM Cloud, Red Hat, Cloudflare, Tencent Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serverless Architecture Market Emerging Trajectories
Serverless platforms are embedding artificial intelligence inference capabilities directly into function runtimes, compressing the architecture stack for intelligent applications. This convergence is eliminating separate model-serving infrastructure while raising new compliance obligations for algorithmic transparency.
WebAssembly runtimes are displacing traditional container-based function isolation in latency-sensitive workloads. Gaming backends and real-time bidding platforms are adopting Wasm-based execution for sub-millisecond cold starts. This technology is displacing Docker and microVM architectures in performance-critical serverless segments where startup overhead directly impacts revenue.
The EU AI Act's risk classification framework is mandating human oversight mechanisms for high-risk automated decision systems deployed on serverless infrastructure. Financial services and healthcare applications must implement explainability pipelines and audit logging that persist across ephemeral function instances. European enterprises are responding by selecting providers with pre-certified compliance tooling rather than building custom governance stacks.
Enterprise buyers are consolidating serverless procurement under centralized platform engineering teams rather than distributing adoption across individual development squads. This organizational shift is displacing shadow IT function deployments and forcing standardization on approved runtime environments. The pattern is most visible in US financial services and healthcare verticals where compliance oversight requirements have intensified following SEC cybersecurity disclosure rules and HIPAA enforcement actions.
Serverless Architecture Market Segmentation
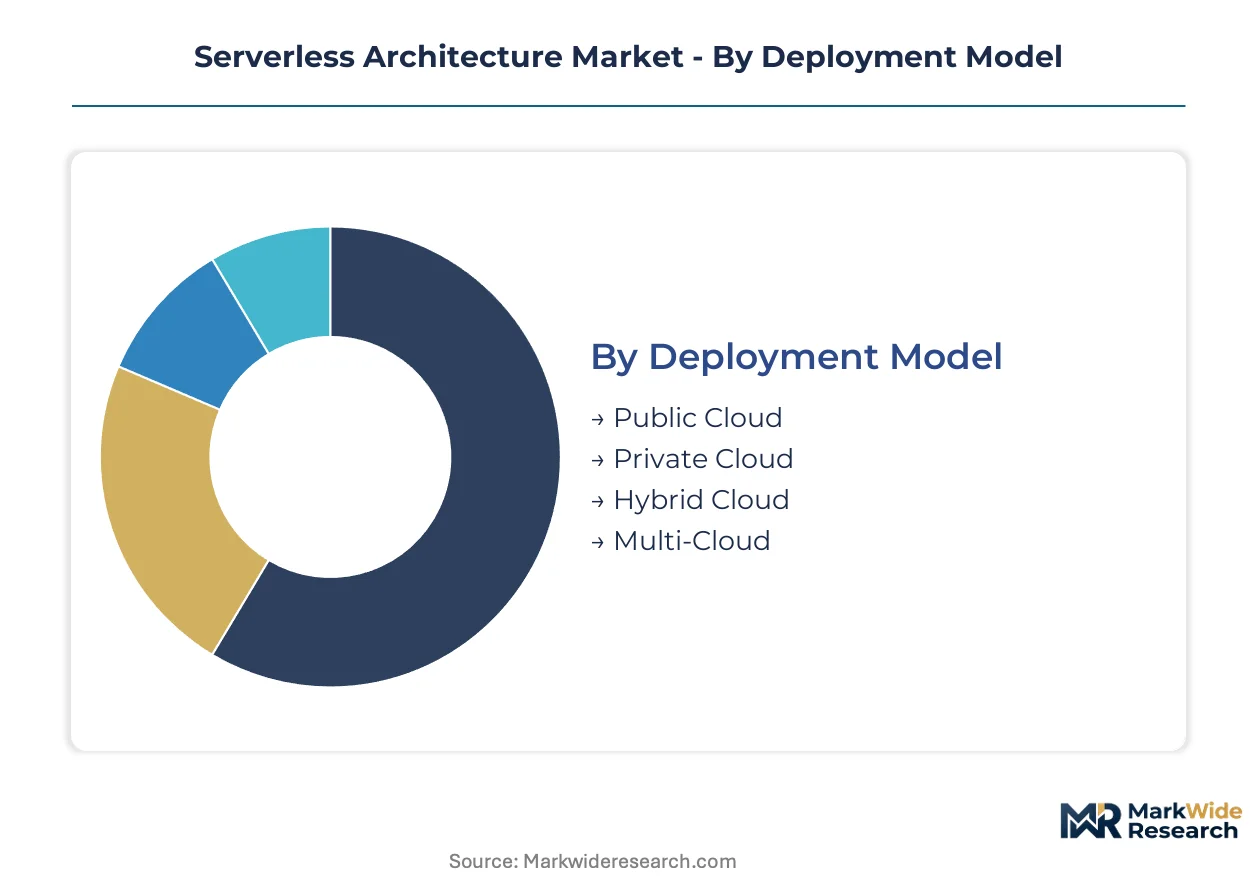
Serverless architecture procurement patterns diverge sharply across deployment models and service types. Enterprise buyers segment workloads by compliance sensitivity, latency tolerance, and integration complexity with legacy systems.
Deployment Model:
Substitution pressure from container-native platforms and edge computing architectures is reshaping deployment preferences across enterprise segments.
- Public Cloud:Managed function runtimes on hyperscaler infrastructure eliminate operational overhead for variable workloads. Financial services firms in the United States concentrate demand here for FedRAMP-authorized payment processing pipelines.
- Private Cloud:On-premises function platforms serve defense contractors and intelligence agencies with air-gapped security requirements. German automotive manufacturers deploy private serverless for connected vehicle telemetry to satisfy GDPR data residency mandates.
- Hybrid Cloud:Split orchestration between on-premises Kubernetes and public function runtimes. Healthcare providers use hybrid deployments to keep patient records local while bursting analytics to cloud functions.
- Multi-Cloud:Workload distribution across AWS, Azure, and Google Cloud to mitigate vendor concentration risk. Fintech startups in Singapore adopt multi-cloud serverless to satisfy MAS operational resilience guidelines.
Public Cloud anchors the volume base while Multi-Cloud gains share at the steepest rate.
Service Type:
Margin compression in commoditized function execution is pushing vendors toward higher-value abstraction layers.
- Function as a Service:Event-triggered code execution in ephemeral containers with millisecond billing granularity. European enterprises migrating from virtual machines under EU AI Act compliance deadlines drive demand concentration.
- Backend as a Service:Pre-built authentication, database, and storage APIs for mobile and web applications. Southeast Asian super-app developers in Indonesia and Vietnam adopt BaaS to overcome backend engineering scarcity.
- Event-Driven Computing:Asynchronous processing architectures triggered by message queues, stream feeds, or state changes. Real-time fraud detection systems at Indian payment networks deploy event-driven functions for sub-100-millisecond response.
- API Management:Gateway, rate limiting, and developer portal services for serverless endpoint exposure. Brazilian neobanks use managed API layers to secure Open Banking compliance with Banco Central do Brasil regulations.
Function as a Service dominates current revenue while Backend as a Service climbs fastest among service types.
End User:
Procurement centralization under platform engineering teams is fragmenting adoption patterns across organizational size tiers.
- Small Enterprises:Low-code function platforms and managed BaaS for web presence and e-commerce operations. Shopify merchants and independent software vendors in Canada leverage small-team serverless deployments.
- Medium Enterprises:Hybrid adoption combining lift-and-shift virtualization with selective function migration. Australian mid-market retailers use medium-enterprise serverless for seasonal demand spikes without capital expenditure.
- Large Enterprises:Multi-region, multi-cloud function orchestration with dedicated platform engineering teams. Japanese automotive conglomerates deploy large-enterprise serverless for connected factory and supply chain optimization.
- Startups:Cloud-native function architectures from inception with minimal infrastructure investment. Israeli cybersecurity startups build entirely on serverless stacks to preserve runway and accelerate time-to-market.
Large Enterprises anchor the volume base while Startups expand most quickly as venture funding prioritizes capital-efficient infrastructure.
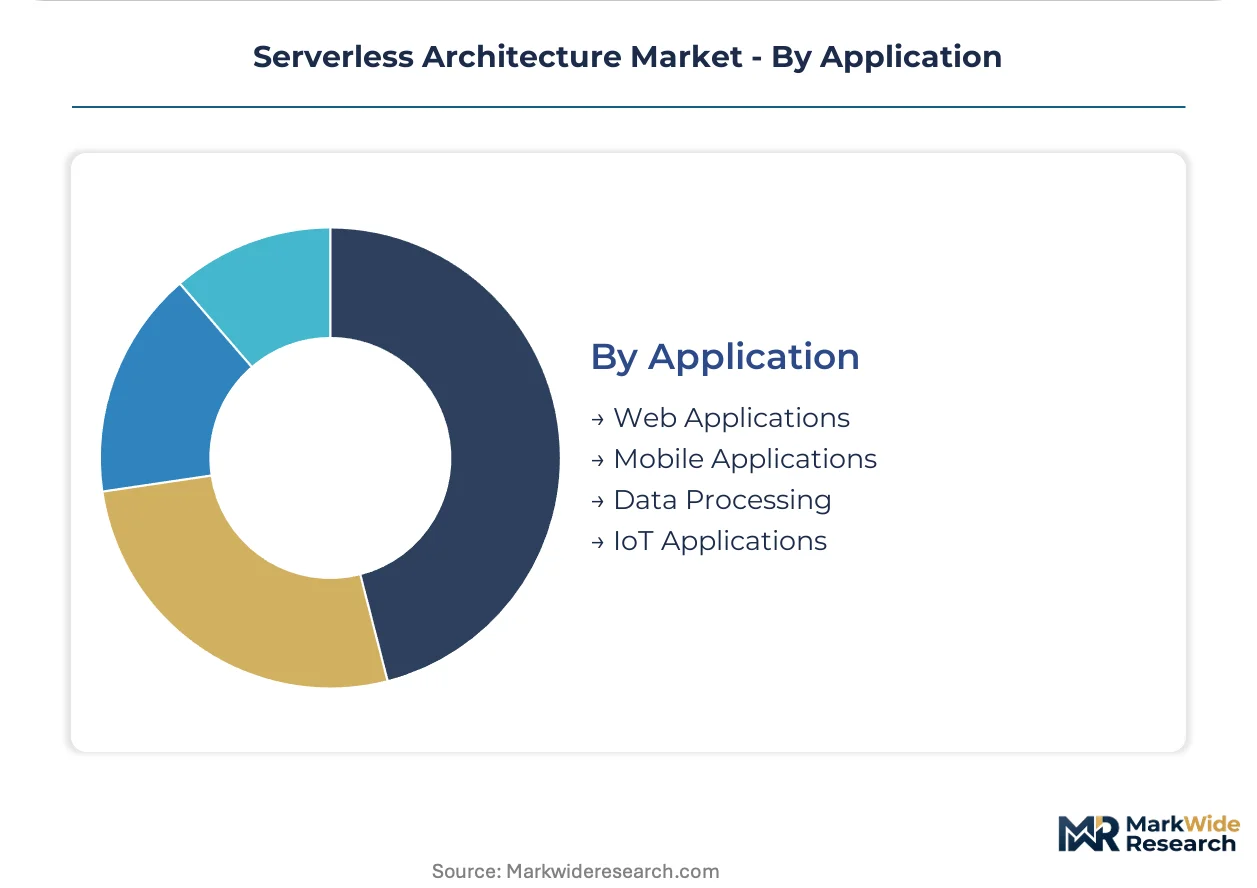
Application:
Latency requirements and data gravity are segmenting workload placement across use case categories.
- Web Applications:Server-side rendering, authentication, and dynamic content generation through edge-deployed functions. French media publishers use web application serverless for personalized content delivery under CNIL consent management rules.
- Mobile Applications:Synchronized data, push notifications, and social features via BaaS and function backends. Nigerian fintech mobile wallets rely on serverless architectures for USSD and smartphone application parity.
- Data Processing:ETL pipelines, stream analytics, and machine learning inference on ephemeral compute. South Korean e-commerce platforms process petabyte-scale clickstream data through serverless data processing.
- IoT Applications:Telemetry ingestion, device command dispatch, and edge preprocessing for constrained sensors. Saudi smart city initiatives deploy IoT serverless for million-device sensor networks under Vision 2030 digital infrastructure programs.
Web Applications anchor the volume base while IoT Applications gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FedRAMP authorization scarcity commands premium margins, while European buyers face compliance-driven cost inflation from GDPR and EU AI Act implementation timelines.
United States
Hyperscaler data center expansion in Northern Virginia and Oregon drives enterprise migration from on-premises infrastructure. SEC cybersecurity disclosure rules and FedRAMP authorization pathways shape vendor qualification timelines for financial services and federal workloads. Silicon Valley fintech clusters deploy serverless payment processing pipelines with sub-100-millisecond latency requirements.
Germany
Automotive manufacturers and industrial conglomerates demand sovereign cloud deployments for connected vehicle telemetry. GDPR data residency mandates and BSI certification standards reshape procurement decisions toward localized infrastructure. Munich and Stuttgart engineering clusters build private serverless environments for supply chain optimization and factory automation.
United Kingdom
Financial services firms in the City of London accelerate function-as-a-service adoption for real-time payment clearing. FCA operational resilience requirements and post-Brexit data adequacy negotiations influence multi-cloud architecture decisions. London-based neobanks and insurtech startups consolidate serverless procurement under centralized platform engineering teams.
Japan
Automotive conglomerates deploy serverless architectures for connected factory and predictive maintenance workloads. METI data governance guidelines and APPI privacy amendments drive vendor selection toward domestic hyperscaler partnerships. Tokyo-Osaka industrial corridors integrate edge-deployed functions with legacy mainframe systems for hybrid manufacturing environments.
Singapore
Fintech startups and super-app developers adopt multi-cloud serverless to satisfy MAS operational resilience guidelines. Cross-border data flow restrictions between ASEAN markets fragment deployment strategies toward jurisdiction-specific function instances. Marina Bay financial district anchors regional demand for low-latency payment processing and regulatory sandbox experimentation.
Serverless Architecture Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the serverless architecture market. Hyperscalers with billion-dollar infrastructure investments dominate function-as-a-service capacity while specialized platform providers compete on developer experience and compliance tooling. Three structural tiers emerge: hyperscaler ecosystems with integrated edge networks, container-native specialists emphasizing portability, and regional cloud providers with sovereign data residency offerings. Competitive dynamics center on strategic partnerships with systems integrators and vertical integration into managed Kubernetes orchestration layers.
Within the hyperscaler tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify divergent architectural philosophies. AWS leverages Lambda ecosystem depth and edge computing integration to sustain enterprise developer loyalty. Microsoft anchors hybrid cloud deployments through Azure Functions and Kubernetes event-driven autoscaling for regulated industries. Google differentiates with Cloud Run's container-native approach and tight data warehouse integration for analytics-intensive workloads. These three entities collectively control function-as-a-service capacity concentration while competing on cold-start latency, runtime language support, and pre-certified compliance tooling for GDPR and FedRAMP mandates.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| Alibaba Cloud |
| Oracle Cloud |
| IBM Cloud |
| Red Hat |
| Cloudflare |
| Tencent Cloud |
| Others |
Supply Flow & Price Mechanics
FedRAMP authorization timelines stretching 12-18 months compress pricing power toward hyperscaler incumbents while fragmenting procurement across jurisdiction-specific deployments. This lead-time band concentrates buyer leverage among enterprises with pre-certified compliance stacks, forcing mid-tier providers into cost-absorbing customization cycles.
Pricing Analysis
The customization-premium spread between standard function-as-a-service consumption and sovereign-cloud configured deployments commands substantial separation. Pricing stratifies across premium, standard, and economy tiers based on certification grade—FedRAMP High versus Moderate versus self-attested—and geographic delivery cost for data-resident workloads. Cost compression in standard tiers is intensifying because hyperscaler infrastructure investments compress margins for undifferentiated execution. Small enterprises exhibit highest price sensitivity, while defense contractors and financial services firms absorb premiums for air-gapped and FedRAMP-authorized environments.
Supply Chain Analysis
Just-in-time capacity provisioning dominates hyperscaler infrastructure strategy, though strategic stockpiling of GPU and specialized AI inference silicon has intensified for serverless-hosted machine learning workloads. Compute capacity concentrates in the United States, Germany, and Singapore where data center buildouts anchor regional function-as-a-service availability. Raw material dependencies span advanced semiconductors, liquid cooling systems, and renewable energy interconnects. Single-source vulnerability in custom AI accelerator supply chains threatens expansion timelines. Distribution runs through direct enterprise sales teams and systems integrator partnerships for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity constrains enterprise adoption velocity, with organizations competing for scarce DevOps specialists capable of orchestrating ephemeral function architectures across multi-cloud boundaries.
For Market Incumbents: Fortify ecosystem lock-in through deeper Kubernetes event-driven autoscaling integration and pre-certified compliance tooling for EU AI Act and FedRAMP mandates. Expand capacity in sovereign cloud regions—Germany, France, Spain—to preempt regulatory fragmentation. Counter container-native portability threats by embedding proprietary observability and cost-management layers.
For New Entrants and Emerging Players: Multi-cloud orchestration tooling gaps expose white-space opportunity where hyperscalers under-serve workload portability needs. Southeast Asian fintech backend-as-a-service penetration remains shallow relative to developer demand. Attack through vertical-specific compliance wrappers for healthcare and financial services that abstract hyperscaler complexity.
For Investors and Strategic Acquirers: Carve-out targets emerge from enterprise software parents divesting function-platform assets misaligned with core revenue streams. Long-term viability hinges on differentiation durability against hyperscaler absorption. Monitor WebAssembly runtime adoption curves as inflection signal for container displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | GDPR and EU AI Act mandates in Germany, France, and Spain create localized infrastructure requirements. |
| WebAssembly Runtime Integration | Sub-millisecond cold starts for gaming and real-time bidding displace Docker in latency-critical segments. |
| Backend-as-a-Service Expansion | Pre-built APIs penetrate Southeast Asian fintech where backend engineering scarcity constrains development. |
| Observability Platform Acquisition | Distributed tracing expertise addresses enterprise DevOps capability gaps across ephemeral function instances. |
| Hybrid Kubernetes Orchestration | Event-driven autoscaling convergence enables portable workload migration across cloud boundaries. |
Methodological Framework
A standing panel of platform engineering directors, cloud procurement officers, DevOps team leads, and compliance auditors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against hyperscaler capex disclosures, SEC filings, FedRAMP authorization databases, and EU regulatory filings. Bottom-up deployment model sizing and top-down market aggregation were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from segmented growth trajectory analysis incorporating infrastructure investment cycles, regulatory implementation timelines, and enterprise migration velocity patterns.
Forecasts assume regulatory continuity in EU AI Act, GDPR, and FedRAMP regimes; material policy shifts would require re-modeling. Cross-border data flow restrictions, sovereign cloud mandates, and algorithmic transparency enforcement intensity represent specific risk factors. Revision becomes warranted when hyperscaler concentration thresholds or WebAssembly adoption rates cross inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Legaltech Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Online Dating Market
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
Video Management System Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Computerized Maintenance Management System Market