
 Legaltech Market | 2026-2036
Legaltech Market Size, Share, and Industry Trends Forecast 2026-2036
Legaltech Market Outlook
Attorney talent scarcity is reorganizing how legal services firms allocate technology budgets, forcing automation investments that compress billable-hour dependencies. RELX Group sustains dominant positioning through deep integration of legal research and risk analytics workflows. Thomson Reuters competes by embedding generative AI across Westlaw and Practical Law product suites. Harvey specializes in large language model applications purpose-built for elite law firm partnerships.
Legaltech encompasses software platforms, artificial intelligence systems, and cloud infrastructure that automate or augment legal workflows including document review, contract lifecycle management, and predictive case analytics. These systems process unstructured legal text through natural language processing pipelines trained on judicial opinions, regulatory filings, and transactional documents to extract obligations, risks, and precedent relationships. E-discovery and contract management segments occupy the largest revenue pools given litigation volume and enterprise procurement standardization. Artificial Intelligence within the technology dimension is capturing disproportionate investment as law firms deploy generative models for brief drafting and regulatory interpretation. Cloud-based deployment leads adoption among mid-size firms seeking to avoid capital-intensive on-premise infrastructure.
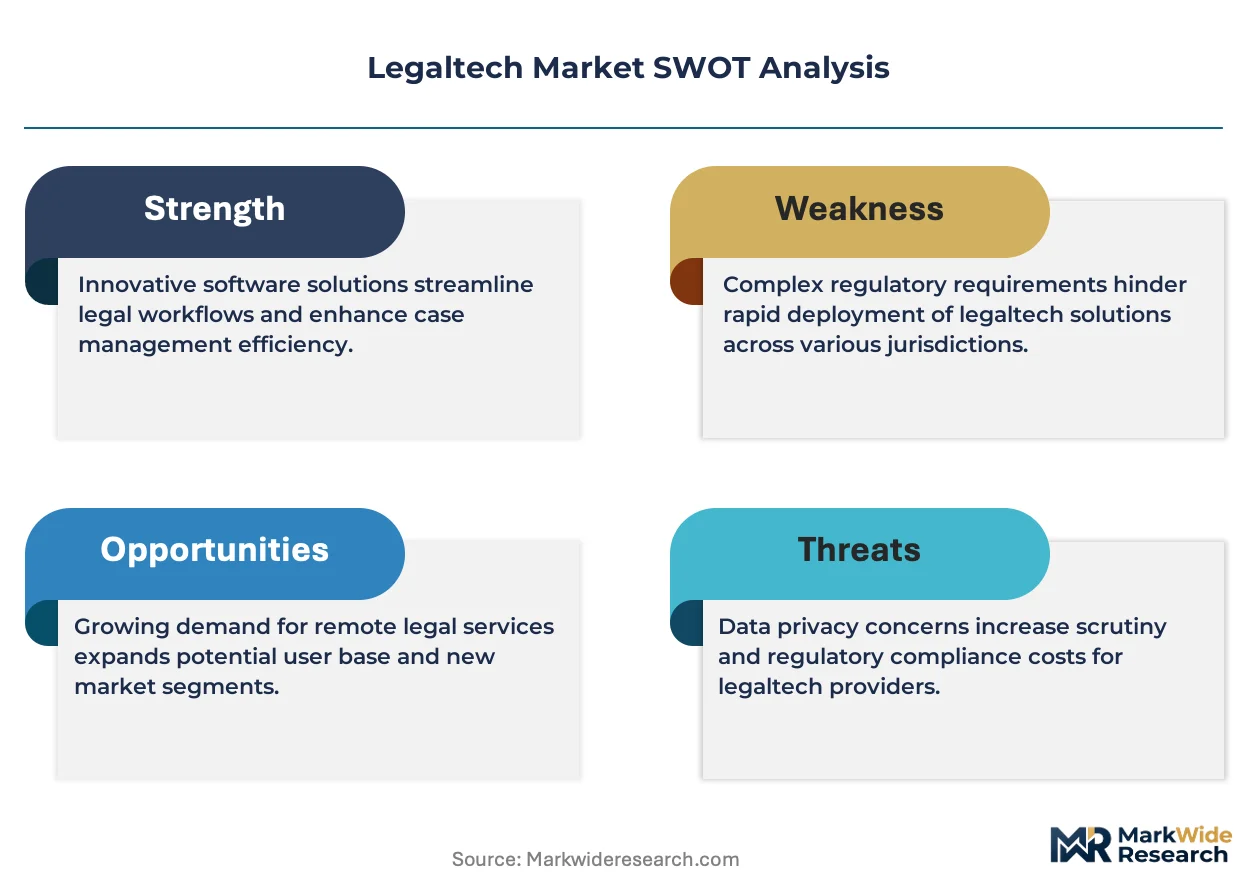
The EU AI Act imposes risk-tiered compliance obligations on legal AI systems that influence judicial or administrative outcomes, compelling vendors to implement human-in-the-loop architectures and algorithmic transparency documentation. The United States Federal Trade Commission and state bar associations are scrutinizing unauthorized practice of law claims against automated advisory tools, creating jurisdictional fragmentation in product deployment. Stakeholders must monitor evolving bar ethics opinions on AI-assisted representation to anticipate where liability frameworks will permit autonomous legal technology deployment.
Market Dynamics
The EU AI Act's risk-tiered compliance framework is compelling legal technology vendors to reengineer product architectures around human-in-the-loop validation and algorithmic transparency documentation. This regulatory pressure cascades through procurement criteria at corporate legal departments and law firms, reshaping competitive positioning across contract analytics, e-discovery, and predictive litigation tools.
Growth Catalysts
- EU AI Act High-Risk System Obligations:Mandatory human oversight and audit trail requirements for AI systems influencing judicial outcomes are driving replacement cycles for legacy automation tools across European legal departments.
- Attorney Talent Scarcity:Shrinking associate pipelines at elite law firms are compressing billable-hour dependencies and forcing accelerated deployment of document review automation and contract generation systems.
- Regulatory Sandbox Expansion:Mature deployment frameworks in the United Kingdom, Australia, and Singapore are reducing go-to-market friction for legal AI vendors seeking jurisdictional proof points.
Market Restraints
- Cloud Infrastructure Concentration:Dominance of hyperscale providers in legaltech backend architecture creates single-point vulnerability for data residency and sovereignty requirements in cross-border litigation.
- Unauthorized Practice of Law Risk:State bar association scrutiny of automated advisory tools in the United States generates jurisdictional fragmentation that complicates product standardization and multi-state deployment.
- Training Data Access Costs:Proprietary judicial opinion databases and sealed transactional document repositories command premium licensing fees that compress margins for natural language processing model development.
Strategic Opportunities
- Mid-Market Law Firm Underpenetration:Firms with 50-200 attorneys in the United States lack dedicated legal operations functions, creating whitespace for managed service wrappers around contract lifecycle management platforms.
- Convergence of Generative AI and Knowledge Graphs:Integration of large language model outputs with structured precedent databases enables hallucination-resistant brief drafting tools for appellate practices.
- CSRD-Driven Contract Analytics:Corporate Sustainability Reporting Directive disclosure requirements in Europe are mandating supply chain due diligence that legal departments must operationalize through automated obligation extraction.
Industry Challenges
- Prompt Engineering Talent Scarcity:Legal domain expertise combined with large language model fine-tuning skills remains concentrated at boutique consultancies and vendor engineering teams, limiting in-house deployment velocity.
- Legacy Practice Management Integration:Decades-old time-and-billing systems at established law firms resist API connectivity, forcing expensive middleware development for workflow orchestration.
- Algorithmic Bias Audit Complexity:Validating fairness across demographic dimensions in sentencing prediction and judicial outcome forecasting lacks standardized methodologies, delaying product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legaltech Market |
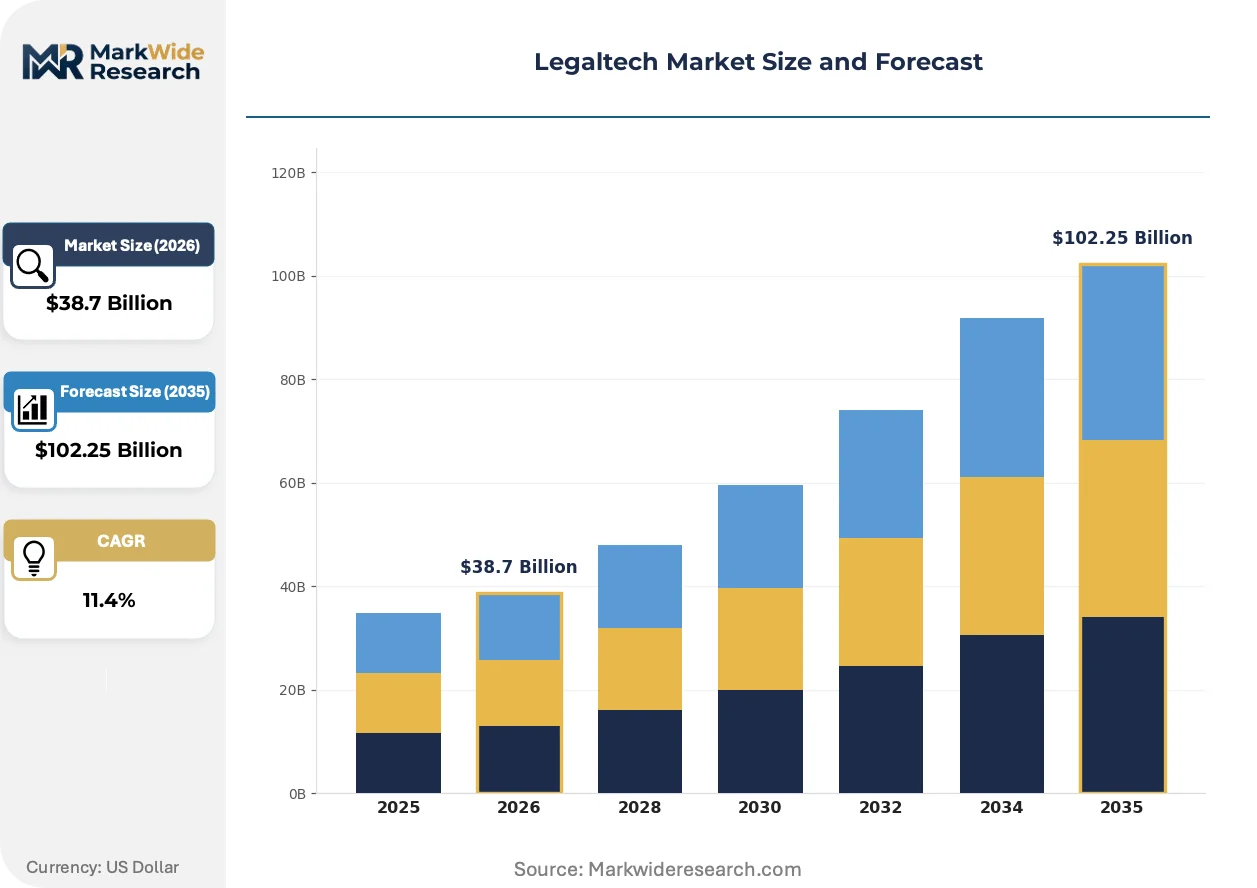
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Management, E-Discovery, Document Automation, Legal Research Technology: Artificial Intelligence, Blockchain, Cloud Computing, Data Analytics Client Type: Law Firms, Corporate Legal Departments, Government Agencies, Nonprofits Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Thomson Reuters, RELX Group, DocuSign, iManage, Clio, Everlaw, Relativity, Harvey, Filevine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legaltech Market Strategic Shifts
Generative AI capabilities are fragmenting established competitive moats in legal research and document automation, compressing the value capture window for incumbent knowledge management platforms. Three intersecting developments are reshaping how legal services firms and corporate departments source, deploy, and monetize technology.
Retrieval-augmented generation architectures are fragmenting the brief-drafting software category by enabling real-time citation verification against proprietary case law databases. Mid-size litigation boutiques in the United States are adopting these tools at twelve-month replacement cycles, collapsing the traditional three-year enterprise software refresh timeline. The structural consequence is compressing maintenance revenue streams for incumbent research platforms while expanding consumption-based pricing experimentation.
REACH-style chemical disclosure obligations are extending into supply chain contract terms across European manufacturing legal departments, mandating automated clause extraction and renegotiation workflows. The industrial consequence is repositioning contract lifecycle management vendors as compliance infrastructure rather than productivity tools. German automotive and French luxury goods legal teams are most affected, deploying AI-powered obligation mapping to meet 2026 disclosure deadlines.
General counsel procurement patterns are rotating toward outcome-based engagements that unbundle software licenses from implementation and change management services. Corporate legal departments in Australia and the United Kingdom are replacing perpetual seat licenses with matter-volume pricing for e-discovery and contract analytics. This shift is most visible in financial services and energy sector verticals where legal operations functions have procurement autonomy.
Legaltech Market Segmentation
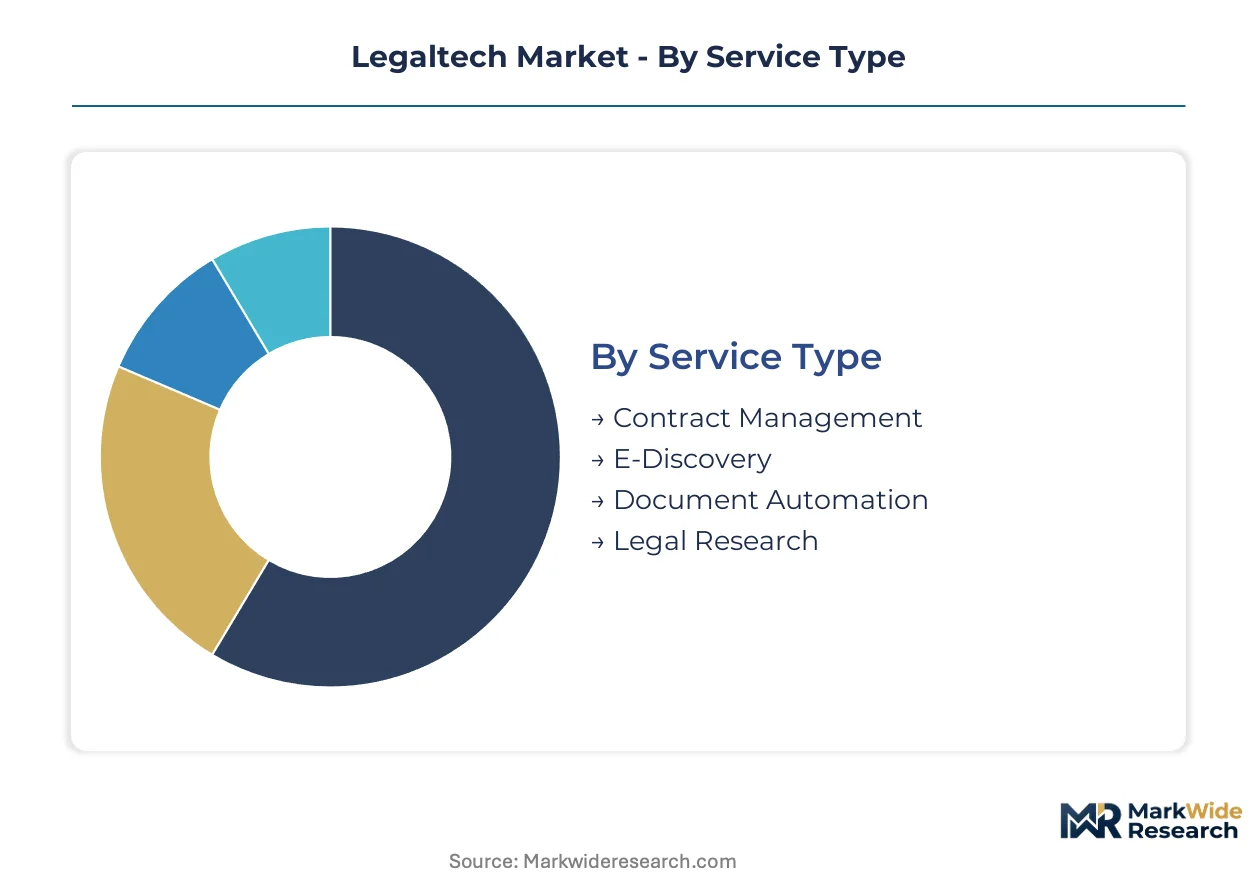
Segmentation in legaltech reveals how procurement authority, technical architecture, and regulatory exposure fragment addressable markets. Vendors must align pricing and implementation models to distinct buyer workflows rather than pursuing horizontal platform strategies.
Service Type:
Margin pools concentrate in high-stakes litigation support and enterprise contract infrastructure where switching costs lock in multi-year engagements.
- Contract Management:Platforms governing negotiation, execution, and obligation monitoring across procurement and sales agreements. Corporate legal departments at German automotive manufacturers and French luxury goods houses are deploying AI-powered clause extraction to meet CSRD supply chain disclosure mandates.
- E-Discovery:Systems processing electronically stored information for litigation readiness, review, and production. United States-based litigation boutiques and insurance carriers drive demand as discovery volume expands and Federal Rules of Civil Procedure tighten processing timelines.
- Document Automation:Template-driven generation of transactional documents, pleadings, and correspondence. Mid-size law firms lacking dedicated legal operations functions represent whitespace for managed service wrappers.
- Legal Research:Databases and analytical tools for case law, statute, and regulatory retrieval. Traditional subscription models face pressure from retrieval-augmented generation tools that fragment established competitive moats.
Contract Management holds installed capacity. E-Discovery is rotating up the share rankings.
Technology:
Investment intensity clusters where natural language processing pipelines intersect with proprietary legal corpora.
- Artificial Intelligence:Machine learning systems for predictive analytics, generative drafting, and intelligent document classification. EU AI Act high-risk system obligations are compelling vendors to reengineer architectures around human-in-the-loop validation and algorithmic transparency documentation.
- Cloud Computing:Scalable infrastructure for document storage, collaborative editing, and remote access. Mid-size firms in the United States and United Kingdom favor cloud deployment to avoid capital-intensive on-premise infrastructure.
- Blockchain:Distributed ledger applications for immutable contract records and smart contract execution. Narrow adoption concentrates in structured finance and trade documentation where multiparty verification reduces settlement risk.
- Data Analytics:Statistical and visualization tools for litigation outcome forecasting, spend analysis, and operational benchmarking. Corporate legal departments with procurement autonomy are expanding adoption of matter-volume pricing models tied to analytical outputs.
Artificial Intelligence commands development budgets. Cloud Computing is climbing the fastest among deployment infrastructure choices.
Client Type:
Procurement sophistication and budget scale vary dramatically across buyer categories, forcing tiered go-to-market approaches.
- Law Firms:Partnership-governed organizations billing time or delivering fixed-fee outcomes. Elite firms in the United States and United Kingdom are deploying large language model applications for brief drafting, while mid-market partnerships lack dedicated legal operations functions.
- Corporate Legal Departments:In-house teams managing enterprise risk and commercial transactions. Australian and United Kingdom-based general counsel are rotating toward outcome-based engagements that unbundle software licenses from implementation services.
- Government Agencies:Public sector legal offices handling regulatory enforcement, administrative proceedings, and legislative drafting. Procurement cycles extend longer than private sector counterparts but offer volume stability.
- Nonprofits:Mission-driven organizations with constrained technology budgets and high pro bono coordination needs. Price-sensitive demand concentrates in document automation for repetitive immigration, housing, and family law matters.
Law Firms hold installed capacity. Corporate Legal Departments are gaining share fastest as insourcing accelerates.
Deployment:
Data residency requirements and legacy system integration complexity shape architecture decisions across jurisdictions.
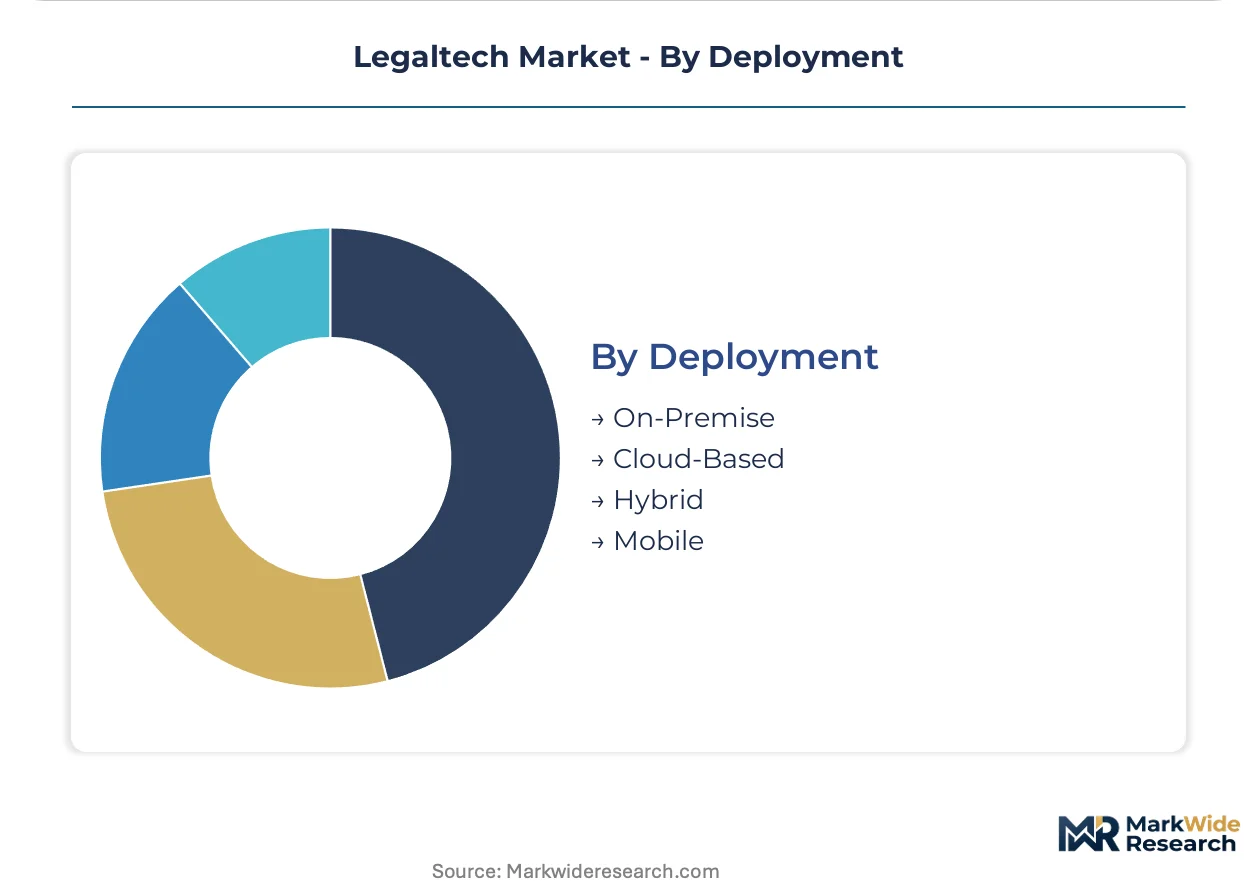
- Cloud-Based:Vendor-managed infrastructure with subscription access. Dominates adoption among mid-size firms seeking to avoid capital expenditure and internal IT burden.
- On-Premise:Self-hosted systems within client data centers. Persists at elite firms and financial institutions with stringent data sovereignty requirements or sealed proceeding obligations.
- Hybrid:Mixed architecture with sensitive workloads on-premise and collaborative tools in cloud environments. Emerging preference for cross-border litigation where data residency rules conflict.
- Mobile:Smartphone and tablet access for remote document review and client communication. Feature parity lags desktop platforms but expands for time-sensitive litigation and field investigation workflows.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings as data sovereignty complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC anchors the dominant geography through scrutiny of unauthorized practice of law claims against automated advisory tools. State bar associations across the United States generate jurisdictional fragmentation that complicates multi-state product deployment. This regulatory patchwork concentrates vendor investment in jurisdictions with clearer compliance pathways.
United States
Elite law firms in New York and Washington deploy large language model applications for brief drafting and regulatory interpretation. The FTC and state bar associations scrutinize automated advisory tools, creating compliance complexity for vendors. Corporate legal departments in Texas and California rotate toward outcome-based engagements that unbundle software licenses from implementation services.
United Kingdom
Mature regulatory sandboxes in London reduce go-to-market friction for legal AI vendors seeking jurisdictional proof points. The Solicitors Regulation Authority and Information Commissioner's Office shape compliance frameworks for algorithmic decision systems. Financial services legal teams in the City of London pioneer matter-volume pricing models for e-discovery and contract analytics.
Germany
Automotive manufacturers in Stuttgart and Munich deploy AI-powered clause extraction to meet CSRD supply chain disclosure mandates. The Federal Financial Supervisory Authority and data protection regulators impose strict audit requirements on automated legal systems. Corporate legal departments at industrial conglomerates in North Rhine-Westphalia operationalize automated obligation extraction for regulatory compliance.
Australia
General counsel in Sydney and Melbourne expand adoption of cloud-based contract lifecycle management platforms. The Australian Securities and Investments Commission and state law societies develop guidance on AI-assisted legal services. Mid-size law firms in Brisbane and Perth favor cloud deployment to avoid capital-intensive on-premise infrastructure.
Singapore
The Monetary Authority of Singapore and Infocomm Media Development Authority cultivate regulatory sandboxes for legal technology experimentation. Corporate legal departments at regional headquarters deploy predictive analytics for litigation outcome forecasting. Law firms in the central business district integrate generative AI tools for cross-border transactional work.
Legaltech Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Legaltech competitive structure. The upper tier captures disproportionate value through deep integration of legal research, risk analytics, and workflow automation. Specialists concentrate in large language model applications, contract lifecycle management, and e-discovery processing. Competitive moves center on embedding generative AI across existing product suites and reengineering architectures for EU AI Act compliance.
Within the integrated research and analytics tier, RELX Group and Thomson Reuters occupy positions that exemplify platform consolidation strategies. Harvey represents the specialist archetype purpose-built for elite law firm partnerships. These three anchors illustrate how competitive positioning fragments across workflow depth versus technical specialization.
| Leading Market Players |
|---|
| Thomson Reuters |
| RELX Group |
| DocuSign |
| iManage |
| Clio |
| Everlaw |
| Relativity |
| Harvey |
| Filevine |
| Others |
Value Chain & Pricing Dynamics
Retrieval-augmented generation architectures replacing traditional knowledge management platforms simultaneously concentrate vendor development spending in the United States and United Kingdom while compressing pricing power for legacy research database subscriptions. This substitution dynamic reshapes supply geography toward cloud hyperscaler regions and pricing economics toward consumption-based models.
Pricing Analysis
Geographic price spreads widen between North American and Asia-Pacific deployments, with United States-based corporate legal departments absorbing premium SaaS tiers while Australian mid-size firms favor standardized cloud packages. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and human-in-the-loop service bundling. Cost compression in the standard tier intensifies because generative AI commoditizes basic document automation. Nonprofit legal aid organizations exhibit highest price sensitivity; elite law firm partnerships demonstrate lowest sensitivity due to billable-hour recovery mechanisms.
Supply Chain Analysis
Just-in-time provisioning dominates cloud infrastructure deployment, though EU AI Act compliance requirements are forcing strategic stockpiling of audit documentation and algorithmic transparency artifacts. Software development concentrates in the United States, United Kingdom, and Israel, with natural language processing model training drawing from proprietary judicial opinion databases in the United States and United Kingdom. Single-source vulnerability concentrates in hyperscale cloud providers for backend compute. Distribution runs through direct enterprise sales teams and legal technology consultancies serving mid-market law firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legaltech sits in early-cycle expansion as attorney talent scarcity forces automation investments that displace traditional billable-hour economics. EU AI Act implementation accelerates replacement demand for non-compliant legacy systems.
For Market Incumbents: Shield installed base relationships by embedding generative AI capabilities into existing workflow platforms before specialist LLM vendors capture brief-drafting market share. Accelerate certification investment for EU AI Act high-risk system compliance to preempt regulatory displacement. Prioritize API development for legacy practice management integration to reduce middleware friction that drives churn.
For New Entrants and Emerging Players: Anchor in mid-market law firm whitespace across the United States, where 50-200 attorney partnerships lack dedicated legal operations functions and managed service wrappers around contract lifecycle management platforms remain underpenetrated. Target outcome-based pricing experimentation in Australian and United Kingdom corporate legal departments where procurement autonomy enables matter-volume models. Lead with CSRD-driven contract analytics specialization to capture German automotive and French luxury goods compliance mandates.
For Investors and Strategic Acquirers: EU AI Act high-risk system obligations reshape the acquisition landscape toward vendors with pre-built human-in-the-loop architectures and algorithmic audit capabilities. Five-to-ten year viability favors platforms combining proprietary legal corpora with retrieval-augmented generation technical stacks. Target acquisition archetype: specialist LLM applications with elite law firm referenceability and compliance-ready documentation pipelines. Monitor state bar association ethics opinion trajectories as signal for where autonomous legal technology deployment liability frameworks will stabilize.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Human-in-the-loop validation systems preempt regulatory displacement in European legal departments. |
| Retrieval-Augmented Generation Integration | Real-time citation verification against proprietary case law databases fragments incumbent research moats. |
| Mid-Market Managed Service Launch | Legal operations function outsourcing captures 50-200 attorney firm whitespace in United States. |
| CSRD Contract Analytics Specialization | Automated obligation extraction meets German automotive supply chain disclosure mandates. |
| Outcome-Based Pricing Transition | Matter-volume models align vendor incentives with corporate legal department procurement autonomy in Australia. |
Study Parameters
Initial hypotheses were tested against primary input from general counsel, legal operations directors, law firm managing partners, and legal technology procurement officers and refined through secondary validation against vendor SEC filings, state bar association ethics opinions, EU regulatory documentation, and legal technology trade publications. Bottom-up triangulation across deployment data and top-down cross-checks against technology spending surveys anchored market sizing.
Variance decomposition across service type, technology stack, client category, and deployment architecture shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves and pricing trajectory modeling. Forecast inputs incorporated attorney headcount projections, litigation volume trends, and regulatory sandbox expansion timelines.
Material uncertainties — judicial outcome forecasting bias validation methodologies, state-level unauthorized practice of law enforcement variance, hyperscale cloud provider concentration risk — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory clarity trajectories and enterprise procurement cycle normalization. Practitioners should keep alternative scenarios live as EU AI Act implementing guidance and United States state bar ethics opinions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Clothing Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Business Transcription Market
Digital Solutions
Virtual Closet Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
Advanced Drill Data Management Solutions Market