
 Computerized Maintenance Management System Market | 2026-2036
Computerized Maintenance Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Computerized Maintenance Management System Market Intelligence
Modular subscription packaging is repositioning how mid-sized manufacturers evaluate CMMS procurement, shifting from perpetual licenses toward tiered SaaS bundles that bundle mobile access with predictive analytics. IBM Maximo leverages deep enterprise integration to anchor complex asset-intensive deployments. MaintainX competes through intuitive mobile-first interfaces that reduce technician onboarding friction. Fiix extends its Rockwell Automation parentage into manufacturing floor connectivity, while UpKeep specializes in vertical workflow templates for facilities teams.
A computerized maintenance management system constitutes software that schedules, tracks, and optimizes equipment maintenance through work order automation, asset registry management, and spare parts inventory control, typically integrating with SCADA or ERP systems via API protocols. Cloud-based deployment leads segment growth as manufacturers retire on-premise servers to reduce IT overhead, while hybrid architectures retain traction among defense and healthcare buyers with data residency requirements. The end-user dimension shows manufacturing commanding the largest installed base, though healthcare facilities management represents the fastest expansion corridor as Joint Commission audit pressures intensify.
OSHA machine safety mandates and FDA 21 CFR Part 11 electronic record requirements shape validation protocols for CMMS implementations in regulated environments, while EU Machinery Directive compliance documentation drives European demand for audit-trail functionality. ISO 55000 asset management standards increasingly appear in RFP criteria for public infrastructure operators across Germany, Australia, and Brazil. Stakeholders must weigh interoperability investments against vendor lock-in risks as platform consolidation accelerates through native IoT partnerships rather than acquisition strategies.
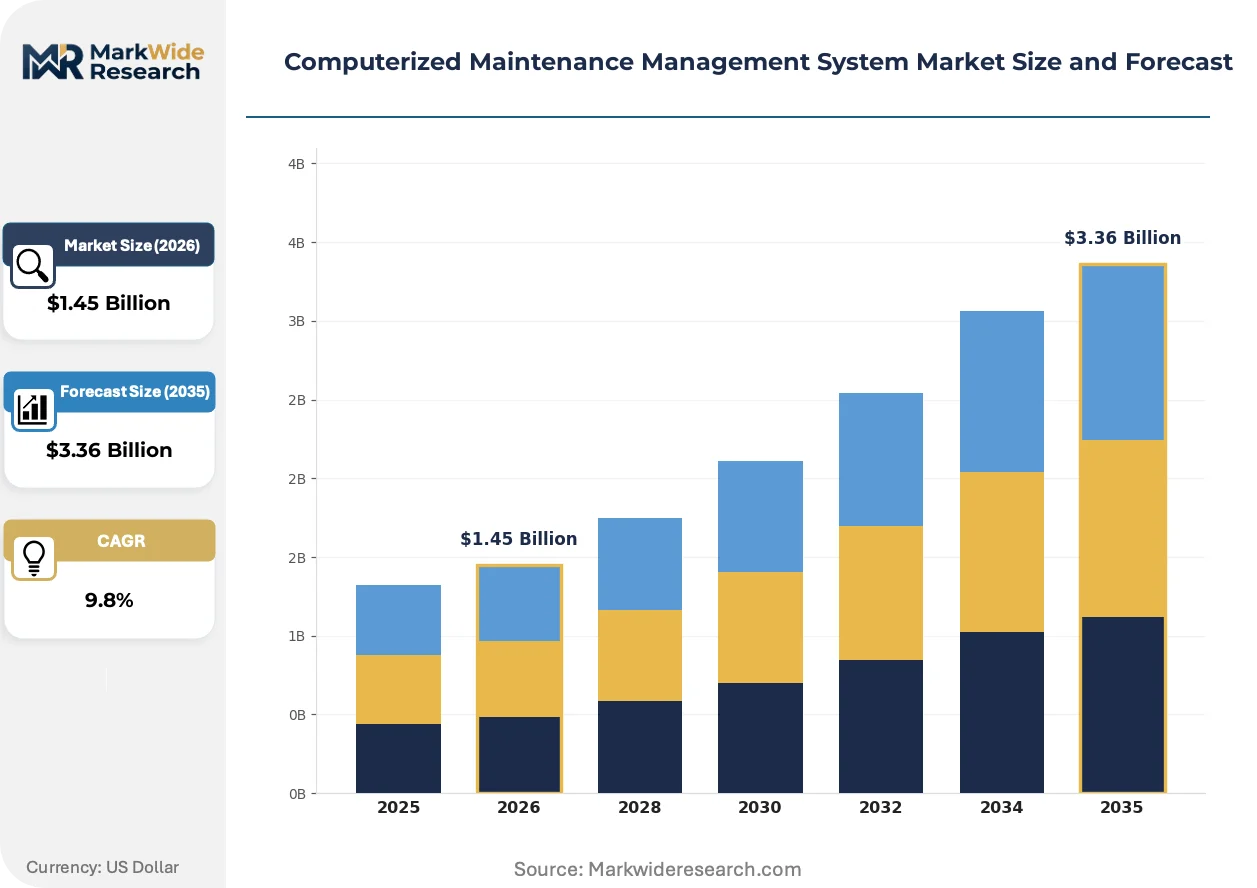
Market Dynamics
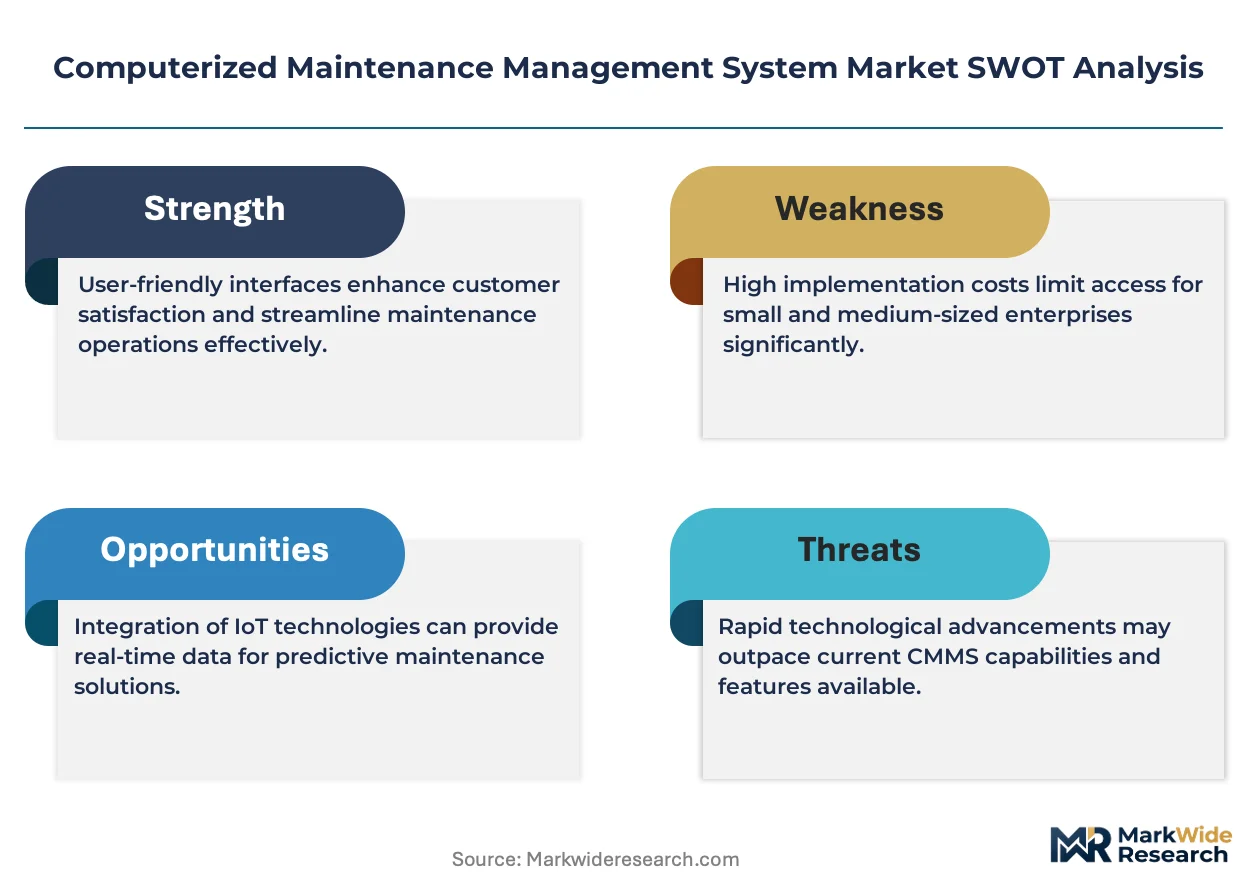
Cloud-native architectures are dismantling the installed base of on-premise CMMS deployments as manufacturers prioritize IT cost reduction and remote accessibility over data sovereignty controls.
Growth Catalysts
- OSHA machine safety mandates:US manufacturing facilities face escalating audit frequencies that require digitized maintenance logs and automated compliance documentation, forcing legacy paper-based operations toward certified CMMS platforms.
- IoT sensor proliferation:Predictive maintenance algorithms now process vibration, thermal, and acoustic data streams from industrial equipment, converting unplanned downtime into scheduled interventions across automotive and chemical processing plants.
- Japan's industrial asset density:Aging infrastructure in Japanese manufacturing clusters generates concentrated demand for asset lifecycle management tools that extend equipment operational life beyond original design specifications.
Market Restraints
- Data residency requirements:Defense contractors and healthcare systems in Germany and France face contractual barriers to cloud migration under national security frameworks that restrict cross-border data flows.
- Integration complexity:Legacy SCADA systems deployed during the 1990s lack standardized API protocols, forcing expensive middleware development for CMMS connectivity in heavy industrial environments.
- Skill scarcity:Maintenance technicians with dual competencies in mechanical systems and software configuration command premium wages that compress implementation margins for system integrators.
Strategic Opportunities
- Brazilian infrastructure privatization:Concession agreements for airports, ports, and utilities mandate ISO 55000-compliant asset management systems, creating first-mover advantages for CMMS providers with Portuguese-language localization.
- Digital twin convergence:Real-time equipment modeling integrated with CMMS work order automation enables simulation-driven maintenance scheduling that reduces spare parts inventory carrying costs.
- EU Green Deal alignment:Carbon footprint tracking requirements for industrial equipment are embedding energy efficiency metrics into maintenance KPI dashboards across German and Dutch manufacturing facilities.
Industry Challenges
- Technician onboarding friction:Mobile interface complexity creates adoption resistance among veteran maintenance crews accustomed to paper work orders, extending pilot-to-production timelines.
- FDA 21 CFR Part 11 validation:Pharmaceutical manufacturers face 12-18 month compliance certification cycles for electronic record systems that delay CMMS deployment in validated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computerized Maintenance Management System Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile Deployment Model: Public Cloud, Private Cloud, SaaS, On-Premises End User: Manufacturing, Healthcare, Transportation, Facilities Management Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | Limble CMMS, Asset Panda, UpKeep, Fabrico, eMaint (Fluke Reliability), IBM Maximo, MaintainX, Factory AI, Fiix (Rockwell Automation), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computerized Maintenance Management System Market Strategic Shifts & Innovations
Artificial intelligence is compressing maintenance decision cycles from days to hours by automating fault diagnosis and spare parts procurement recommendations without human intervention.
Edge computing architectures for CMMS platforms are converging with 5G private networks to enable millisecond-latency equipment monitoring in steel mills and petrochemical refineries. Mining operators in Western Australia are deploying these configurations to eliminate connectivity dead zones in underground extraction environments. The technology is converging with digital work instruction systems to deliver context-aware repair protocols directly to technician wearables.
REACH chemical substance restrictions are forcing European manufacturers to overhaul lubricant and coolant specifications, requiring CMMS platforms to track formulation changes and disposal compliance across asset registries. Automotive suppliers in Germany face particular pressure to document substance substitutions in maintenance histories. The regulation is accelerating demand for materials database integrations that flag non-compliant spare parts before procurement.
Subscription-based CMMS procurement is displacing perpetual license purchases as mid-sized manufacturers prioritize operational expenditure predictability over capital deployment. Industrial distributors are bundling software access with maintenance service contracts to capture recurring revenue streams. This pattern is most visible in United States metal fabrication shops where cash flow sensitivity favors monthly SaaS payments.
Computerized Maintenance Management System Market Segmentation
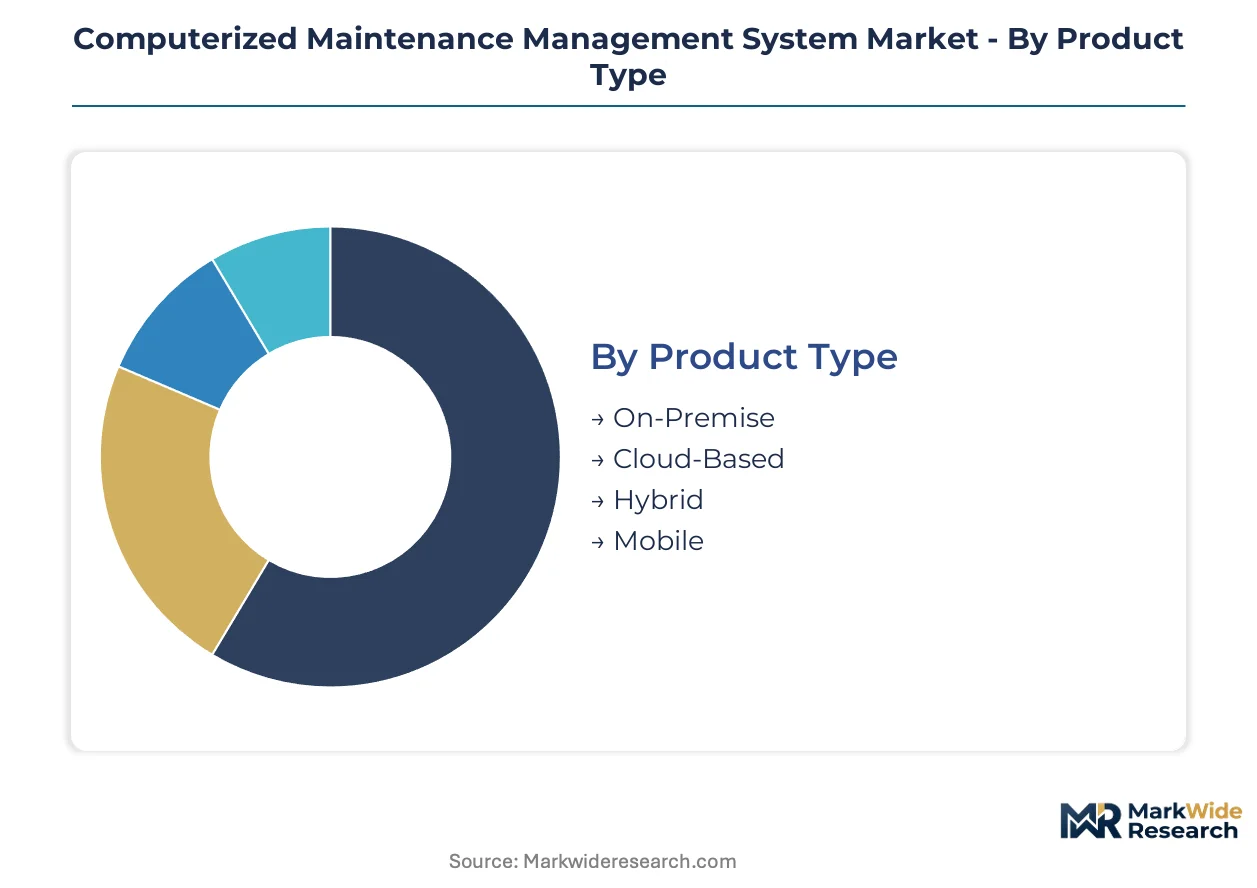
CMMS procurement patterns diverge sharply by infrastructure maturity and regulatory exposure. Buyers select deployment architectures based on IT legacy burden, data sovereignty constraints, and workforce mobility requirements rather than feature parity alone.
Product Type:
Architectural choices reflect trade-offs between control granularity and operational agility.
- On-Premise:Installed software running on customer-managed servers with full configuration autonomy. Defense contractors in Germany and healthcare systems in France retain this model to satisfy national data residency frameworks that restrict cross-border server locations.
- Cloud-Based:Browser-accessible platforms with vendor-managed infrastructure and automatic feature updates. Mid-sized manufacturers in the United States favor this architecture to eliminate server maintenance overhead and enable remote technician access.
- Hybrid:Split configurations keeping sensitive asset data on-premise while routing mobile workflows through cloud gateways. Japanese automotive suppliers deploy this pattern to protect proprietary equipment specifications while maintaining field workforce connectivity.
- Mobile:Native applications optimized for smartphone and tablet interfaces with offline synchronization capabilities. Facilities teams in Brazilian port concessions adopt these tools to manage maintenance in connectivity-constrained environments.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Deployment Model:
Commercial packaging determines how buyers capitalize software investments and scale user access.
- Public Cloud:Shared infrastructure with multi-tenant isolation and consumption-based pricing. Metal fabrication shops across the United States prefer this model for cash flow predictability and rapid user expansion without capital deployment.
- Private Cloud:Dedicated virtual environments with single-tenant isolation and customizable security policies. Australian mining operators in Western Australia specify this architecture to maintain operational technology separation from enterprise IT networks.
- SaaS:Subscription licensing with bundled maintenance, support, and continuous feature delivery. German automotive suppliers favor monthly arrangements that align software costs with production volume fluctuations.
- On-Premises:Perpetual licensing with upfront capital expenditure and annual maintenance contracts. Pharmaceutical manufacturers in Switzerland retain this model to satisfy FDA 21 CFR Part 11 validation requirements for fixed software baselines.
Revenue concentration favors SaaS. Procurement complexity peaks with On-Premises.
End User:
Vertical specialization drives feature prioritization and integration depth requirements.
- Manufacturing:Asset-intensive production environments requiring SCADA integration and predictive maintenance algorithms. Chemical processing plants in the Netherlands deploy these systems to convert vibration and thermal sensor data into scheduled interventions.
- Healthcare:Facilities and clinical engineering teams managing Joint Commission audit pressures and equipment lifecycle compliance. Hospital systems in the United States prioritize electronic work order documentation to satisfy accreditation survey requirements.
- Transportation:Fleet and infrastructure operators tracking mobile asset condition across distributed locations. Airport concession holders in Brazil mandate ISO 55000-compliant systems for runway and terminal equipment management.
- Facilities Management:Commercial and institutional property teams coordinating preventive maintenance across building systems. Dutch manufacturing facilities embed energy efficiency metrics into maintenance KPI dashboards to satisfy EU Green Deal alignment requirements.
Installed base dominance belongs to Manufacturing. Steepest expansion trajectory appears in Healthcare.
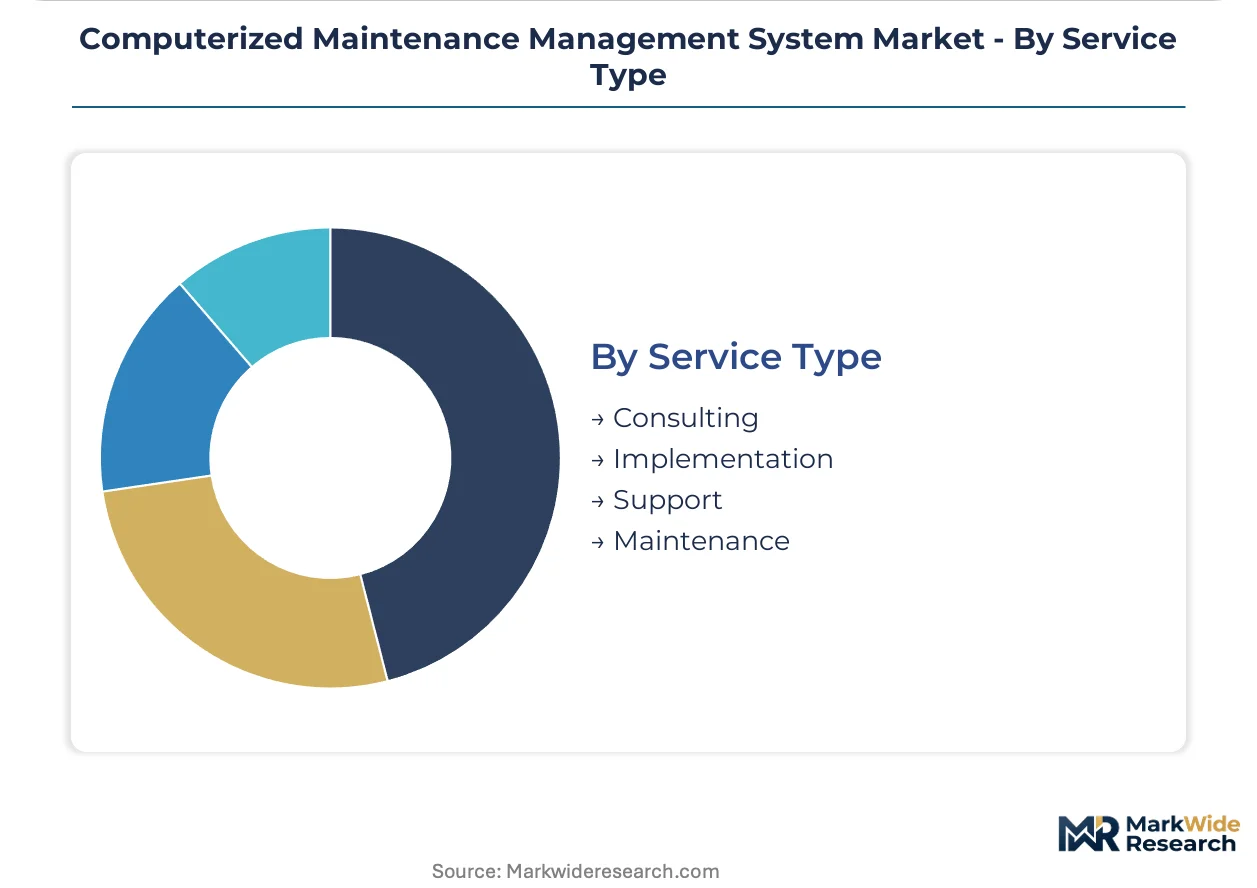
Service Type:
Professional services separate platform deployment from sustained operational value extraction.
- Consulting:Pre-implementation assessment of maintenance workflows, asset hierarchies, and integration architecture. System integrators in Japan command premium rates for technicians with dual competencies in mechanical systems and software configuration.
- Implementation:Data migration, system configuration, user training, and go-live support. Heavy industrial environments in Germany require expensive middleware development to connect 1990s-era SCADA systems with modern API protocols.
- Support:Ongoing technical assistance, troubleshooting, and version management. Cloud-native vendors bundle this into subscription pricing while on-premise deployments charge annual maintenance fees.
- Maintenance:Platform updates, security patching, and performance optimization. Healthcare buyers in the United States face 12-18 month compliance certification cycles that delay deployment in validated environments.
Margin compression hits Implementation. Recurring revenue concentrates in Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest CMMS consumption volume, while software development and platform engineering concentrate in technology clusters across North America and Western Europe. Manufacturing asset density and regulatory compliance burdens determine regional adoption intensity.
United States
OSHA machine safety mandates and FDA 21 CFR Part 11 requirements drive pharmaceutical and food processing facilities toward validated CMMS platforms. Hospital systems in the Midwest and Southeast prioritize electronic work order documentation to satisfy Joint Commission audit pressures. Automotive suppliers in Michigan and chemical processors along the Gulf Coast deploy predictive maintenance modules processing vibration and thermal sensor data.
Germany
EU Machinery Directive compliance documentation and ISO 55000 asset management standards shape procurement criteria for industrial operators. REACH chemical substance restrictions force manufacturers to track lubricant formulation changes across asset registries. Automotive suppliers in Baden-Württemberg and chemical processors in North Rhine-Westphalia represent concentrated demand for audit-trail functionality.
Japan
Aging industrial infrastructure generates concentrated demand for asset lifecycle management tools that extend equipment operational life. METI industrial digitization programs accelerate cloud migration among small and mid-sized manufacturers. Automotive clusters in Toyota City and steel mills in the Chiba industrial corridor deploy hybrid architectures protecting proprietary specifications while enabling field workforce connectivity.
Brazil
Infrastructure privatization concessions for airports, ports, and utilities mandate ISO 55000-compliant asset management systems. ANVISA pharmaceutical regulations and national data residency frameworks influence platform selection for healthcare and defense applications. Port operators in Santos and airport authorities in São Paulo state adopt mobile-native CMMS tools for connectivity-constrained environments.
Australia
Western Australian mining operators specify private cloud architectures maintaining operational technology separation from enterprise IT networks. TGA medical device regulations and state-level workplace safety codes drive healthcare facility adoption. Iron ore extraction sites in the Pilbara region deploy edge computing configurations with 5G private networks to eliminate underground connectivity dead zones.
Computerized Maintenance Management System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise software divisions of industrial automation groups anchor complex asset-intensive deployments through deep ERP and SCADA integration capabilities. Venture-backed SaaS challengers displace legacy on-premise installations with mobile-first interfaces and rapid implementation timelines. Platform consolidation accelerates through native IoT partnerships rather than acquisition strategies, while subscription packaging shifts procurement from capital expenditure to operational expenditure models.
Within the enterprise integration tier, IBM Maximo and Fiix exemplify archetypes leveraging parentage in industrial software and automation hardware respectively. MaintainX and UpKeep occupy positions among mobile-native specialists reducing technician onboarding friction through intuitive smartphone interfaces. Limble CMMS and Asset Panda represent the mid-market SaaS vector prioritizing rapid deployment and tiered subscription accessibility for facilities teams without dedicated IT support resources.
| Leading Market Players |
|---|
| Limble CMMS |
| Asset Panda |
| UpKeep |
| Fabrico |
| eMaint (Fluke Reliability) |
| IBM Maximo |
| MaintainX |
| Factory AI |
| Fiix (Rockwell Automation) |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon footprint tracking mandates gate qualified supply access and premium-tier pricing power for CMMS vendors serving Dutch and German manufacturing facilities. Compliance documentation requirements for energy efficiency metrics in maintenance KPI dashboards separate certified platform providers from uncertified competitors, concentrating pricing power among vendors with embedded sustainability reporting modules.
Pricing Analysis
Cost-down pressure on mid-market SaaS tiers accelerates because metal fabrication shops across the United States favor monthly payment predictability over capital deployment. Three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by ISO 55000 certification grade and predictive analytics module depth. Pricing pressure stems from subscription packaging standardization reducing customization premiums. Facilities teams without dedicated IT support resources exhibit highest price sensitivity, while pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation requirements demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel CMMS vendors to qualify multiple hyperscaler partners, with software development and platform engineering concentrated in technology clusters across the United States, Germany, and Japan. Raw material dependencies center on semiconductor components for edge computing devices, lithium-ion cells for mobile hardware, and specialized sensors for IoT integration. Supply chain risk traces to single-source vulnerability in legacy SCADA protocol translation middleware. Distribution runs through direct vendor sales for enterprise deployments and industrial distributor networks for mid-market SaaS bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 21 CFR Part 11 electronic record requirements create a barrier-to-entry moat for validated platform providers serving pharmaceutical and food processing facilities.
For Market Incumbents: Acquire predictive analytics algorithm libraries to anchor defensible positioning against mobile-native challengers. Fortify ERP and SCADA integration depth to exploit legacy system connectivity complexity that compresses implementation margins for new entrants. Deepen native IoT partnerships rather than pursuing acquisition strategies to reduce vendor lock-in risks.
For New Entrants and Emerging Players: Mobile-first interfaces with offline synchronization capabilities offer the most penetrable wedge for Brazilian port operators and Australian mining sites facing connectivity-constrained environments. Target healthcare facilities management in the United States where Joint Commission audit pressures intensify electronic work order documentation demand. Pursue vertical workflow templates as the primary go-to-market angle to reduce technician onboarding friction.
For Investors and Strategic Acquirers: Brazilian infrastructure privatization concession announcements are the leading indicator that ISO 55000-compliant asset management system mandates will accelerate procurement cycles. Long-term viability favors vendors with Portuguese-language localization and hybrid architecture capabilities serving data residency-constrained buyers. Watch for 5G private network deployment milestones in Western Australian mining corridors as the signal for edge computing CMMS convergence inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native IoT sensor partnerships with Rockwell Automation and Siemens reduce middleware development burdens for chemical processors. |
| Geographic Expansion | Portuguese-language localization captures first-mover advantage in Brazilian airport and port concession agreements. |
| Product Launch | Digital twin convergence modules enable simulation-driven maintenance scheduling for Japanese automotive suppliers. |
| Strategic Partnership | 5G private network alliances with Australian mining operators eliminate underground connectivity dead zones. |
| Acquisition of Specialist Firm | Predictive analytics algorithm libraries anchor defensible positioning against mobile-native challengers in mid-market. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with maintenance directors, plant engineers, IT procurement officers, and aftermarket service heads. Secondary validation drew from FDA 510(k) filings, EMA submission databases, OSHA enforcement records, and ISO certification registries. Bottom-up deployment model sizing and top-down industrial software market triangulation reconciled volume estimates.
Data-stream reconciliation across deployment architecture, end-user vertical, organization size, integration complexity, and regional adoption pattern dimensions shaped the analytical framework. CAGRs were derived from slope-interpolation of validated data points across the projection horizon. Industry-specific forecast inputs included METI industrial digitization program acceleration rates and EU Machinery Directive compliance documentation adoption curves.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, hyperscaler service discontinuations, and unanticipated regulatory harmonization failures. Forecasts reflect documented assumptions about cloud migration velocity and IoT sensor price depreciation trajectories. Deviation in OSHA audit frequency or FDA validation timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Germany Smart Office Market
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Asia-Pacific Data Monetization Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
UX Services Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Global Cloud Supply Chain Management Market