
 Ad Intelligence Software Market | 2026-2036
Ad Intelligence Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ad Intelligence Software Market Insights
Data science talent scarcity is reorganizing how vendors build and sell ad intelligence platforms. Similarweb leverages its digital intelligence heritage to anchor enterprise competitive analysis workflows. AdClarity competes through specialized visibility into programmatic and social ad ecosystems. Moat by Oracle sustains brand safety measurement leadership through deep integration with media verification infrastructure.
Ad intelligence software encompasses platforms that collect, process, and visualize competitive advertising data across digital channels, typically operating through API-based data ingestion, machine learning classification of creative assets, and real-time dashboard rendering to inform media planning and competitive strategy. Competitive analysis and audience insights represent mature margin pools where buyers pay premium subscriptions for granular creative and placement visibility, while predictive analytics emerges as the fastest-expanding segment as advertisers demand forward-looking spend forecasting rather than retrospective reporting. Cloud-based and SaaS deployment models dominate new procurement, though hybrid architectures persist among financial services and healthcare advertisers with segmented data governance requirements.
FDA oversight of health-related advertising claims, FCC guidance on digital political ad disclosures, and GDPR data processing constraints collectively shape product design and market access for ad intelligence vendors serving regulated industries. The EU AI Act introduces additional compliance layers for automated decision-making in ad targeting and budget allocation tools. Stakeholders must monitor how fragmentation between privacy regimes affects cross-border data availability and platform interoperability.
Market Dynamics
GDPR data processing constraints and the EU AI Act are forcing ad intelligence vendors to re-architect data pipelines and automated decision-making systems, compressing margins while creating compliance differentiation among platforms.
Growth Catalysts
- Programmatic advertising spend concentration:Retailers in the United States demand real-time competitive ad monitoring across e-commerce platforms, pulling procurement toward specialized intelligence tools.
- GDPR compliance frameworks:European privacy regulations create procurement urgency for privacy-preserving ad intelligence architectures that maintain competitive visibility without personal data processing.
- Machine learning classification:Automated creative asset tagging and placement analysis reduces manual research hours for media planning teams, expanding addressable buyer segments.
Market Restraints
- First-party data scarcity:Browser cookie deprecation and mobile identifier restrictions limit cross-platform tracking fidelity, degrading competitive spend estimates.
- API rate limiting:Platform gatekeepers impose throttling on data extraction endpoints, constraining refresh frequency for real-time dashboards.
- Cloud infrastructure costs:Real-time processing of petabyte-scale ad impression logs requires continuous compute scaling, pressuring SaaS unit economics.
Strategic Opportunities
- Retail media networks:Closed-loop attribution on Amazon, Walmart, and Target advertising platforms creates demand for specialized competitive intelligence outside traditional programmatic channels.
- Connected TV ad intelligence:Streaming platform advertising growth outpaces available competitive monitoring tools, opening whitespace for creative and placement tracking.
- Outcome-based pricing models:Media agencies seek subscription structures tied to measurable competitive advantage rather than seat-based SaaS fees.
Industry Challenges
- Data science talent scarcity:Machine learning engineers with advertising domain expertise command premium compensation, constraining vendor R&D velocity.
- Cross-border data fragmentation:Divergent privacy regimes between the United States, European Union, and China prevent unified global competitive datasets.
- Legacy system integration:Enterprise media planning software requires custom API development for ad intelligence platform connectivity, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ad Intelligence Software Market |
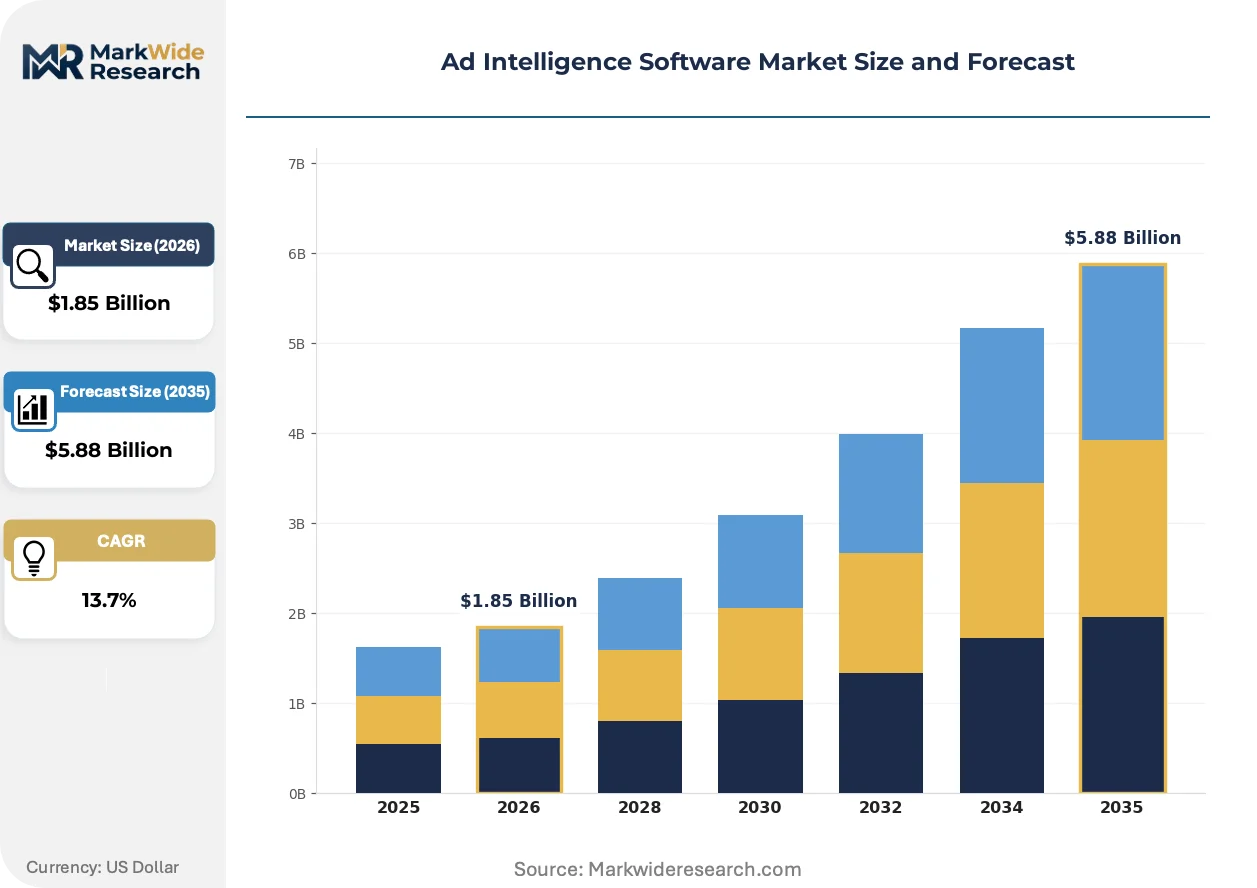
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Competitive Analysis, Campaign Management, Audience Insights Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Customer Type: SMEs, Large Enterprises, Marketing Agencies, Advertisers End User: Retail, E-Commerce, Media & Entertainment, Technology |
| Companies Covered | Adbeat, Admetricks, Similarweb, AdMobiSpy, Poltio, AdClarity, iSpionage, Integral Ad Science, Moat by Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ad Intelligence Software Market Trends and Innovations
Privacy-preserving computation methods and automated creative analysis are compressing the latency between competitive observation and strategic response, while regulatory fragmentation forces architectural specialization.
Real-time creative intelligence engines ingest and classify advertisement assets across social, programmatic, and retail media channels using computer vision and natural language processing. E-commerce platforms and direct-to-consumer brands adopt these tools fastest, demanding hourly refresh cycles during promotional windows. Static quarterly competitive reports are supplanting by always-on monitoring interfaces that trigger automated alerts on competitor spend shifts.
The EU AI Act imposes transparency obligations on automated systems used for ad targeting and budget allocation, requiring explainability documentation and human oversight protocols. Vendors serving European advertisers must embed audit trails and decision logging into product architectures. Financial services and healthcare advertisers face the steepest compliance burden, as their existing FDA and internal governance frameworks intersect with the new AI Act requirements.
Media agencies consolidate vendor relationships, demanding unified platforms that span competitive intelligence, brand safety, and verification rather than point solutions. Procurement committees now evaluate total cost of ownership across overlapping toolsets, compressing supplier counts. This concentration is most visible in the United States, where holding company-level enterprise agreements are displacing individual brand-level software subscriptions.
Ad Intelligence Software Market Segmentation
Ad intelligence software vendors architect pricing and feature tiers around how buyers consume competitive data. Deployment constraints and customer sophistication levels determine platform configuration requirements across the value chain.
Product Type:
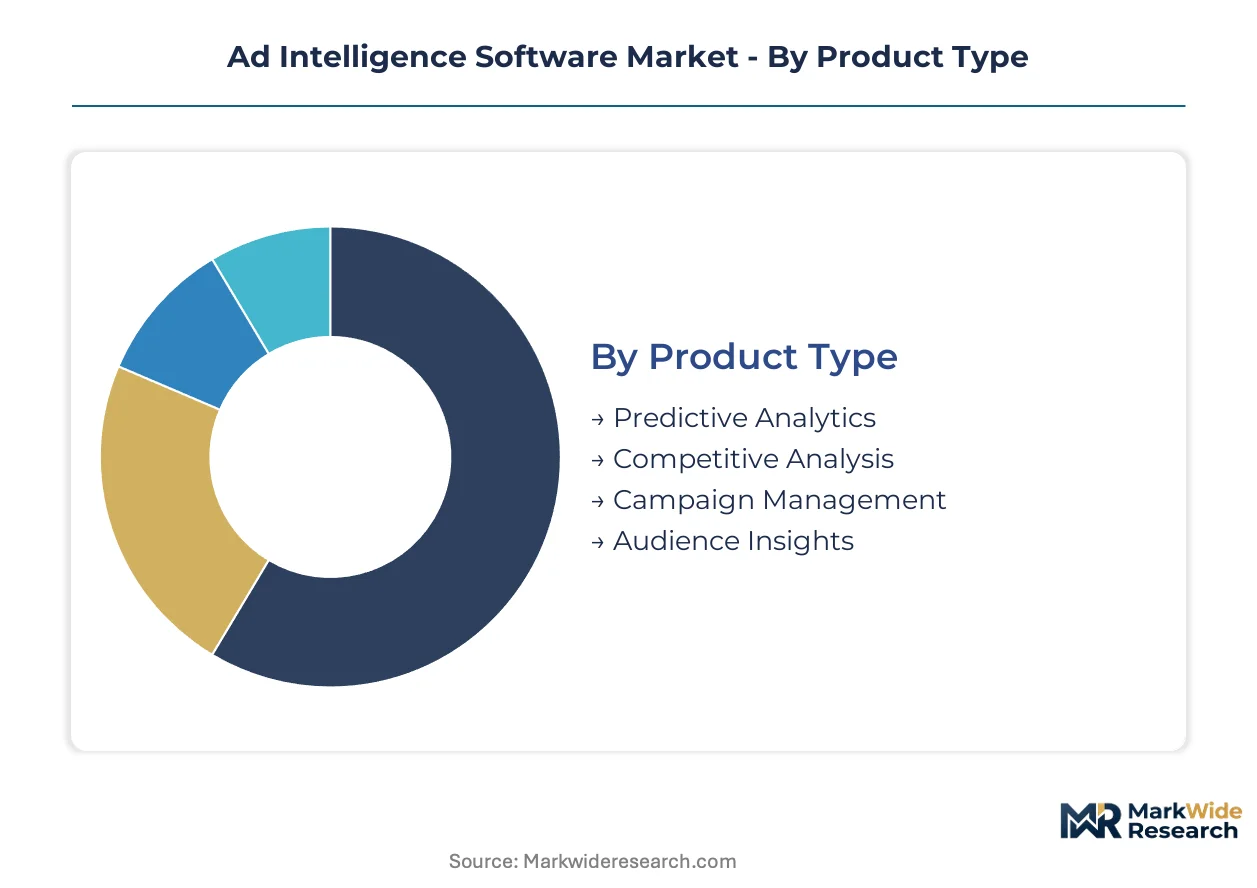
Premium subscriptions concentrate in competitive analysis and audience insights where granular creative visibility commands sustained pricing power.
- Competitive Analysis:Platforms ingest and classify rival advertisement assets across programmatic, social, and retail media channels using machine learning pipelines. Retailers in the United States pay premium rates for real-time spend monitoring during promotional windows, though API rate limiting constrains refresh frequency.
- Audience Insights:Segmentation engines process impression-level data to map competitor targeting strategies and demographic reach. E-commerce platforms demand these capabilities most intensely as they optimize customer acquisition against rival direct-to-consumer brands.
- Predictive Analytics:Forward-looking spend forecasting models reduce reliance on retrospective reporting.
- Campaign Management:Integrated workflow tools connecting intelligence to media planning execution.
The dominant share belongs to Competitive Analysis, while Predictive Analytics is closing the gap fastest.
Deployment Model:
Cloud infrastructure economics favor SaaS delivery, though regulated industries sustain hybrid architectures for data sovereignty compliance.
- Cloud-Based:Elastic compute resources process petabyte-scale ad impression logs without capital expenditure. Media agencies consolidate procurement around cloud-native platforms that eliminate on-premises maintenance overhead.
- SaaS:Subscription licensing with API-based data ingestion and dashboard rendering dominates new customer acquisition. GDPR constraints force European deployments toward privacy-preserving architectures that minimize personal data processing.
- Hybrid:Segmented data governance separates sensitive competitive intelligence from operational systems.
- On-Premises:Legacy financial services and healthcare advertisers retain air-gapped installations.
SaaS deployments capture the largest customer base, with Cloud-Based solutions expanding most quickly among mid-market buyers.
Customer Type:
Enterprise procurement committees evaluate total cost of ownership across overlapping intelligence toolsets, compressing vendor counts.
- Large Enterprises:Holding company-level agreements span multiple brands and markets, demanding unified competitive intelligence, brand safety, and verification platforms. United States-based retailers drive the steepest feature requirements for real-time monitoring.
- Marketing Agencies:Outcome-based pricing structures replace seat-based subscriptions as procurement criteria shift toward measurable competitive advantage.
- SMEs:Self-service interfaces with reduced customization needs.
- Advertisers:Direct brand procurement of point solutions for specific channel monitoring.
Large Enterprises command the deepest vendor relationships, while Marketing Agencies are gaining procurement influence fastest.
End User:
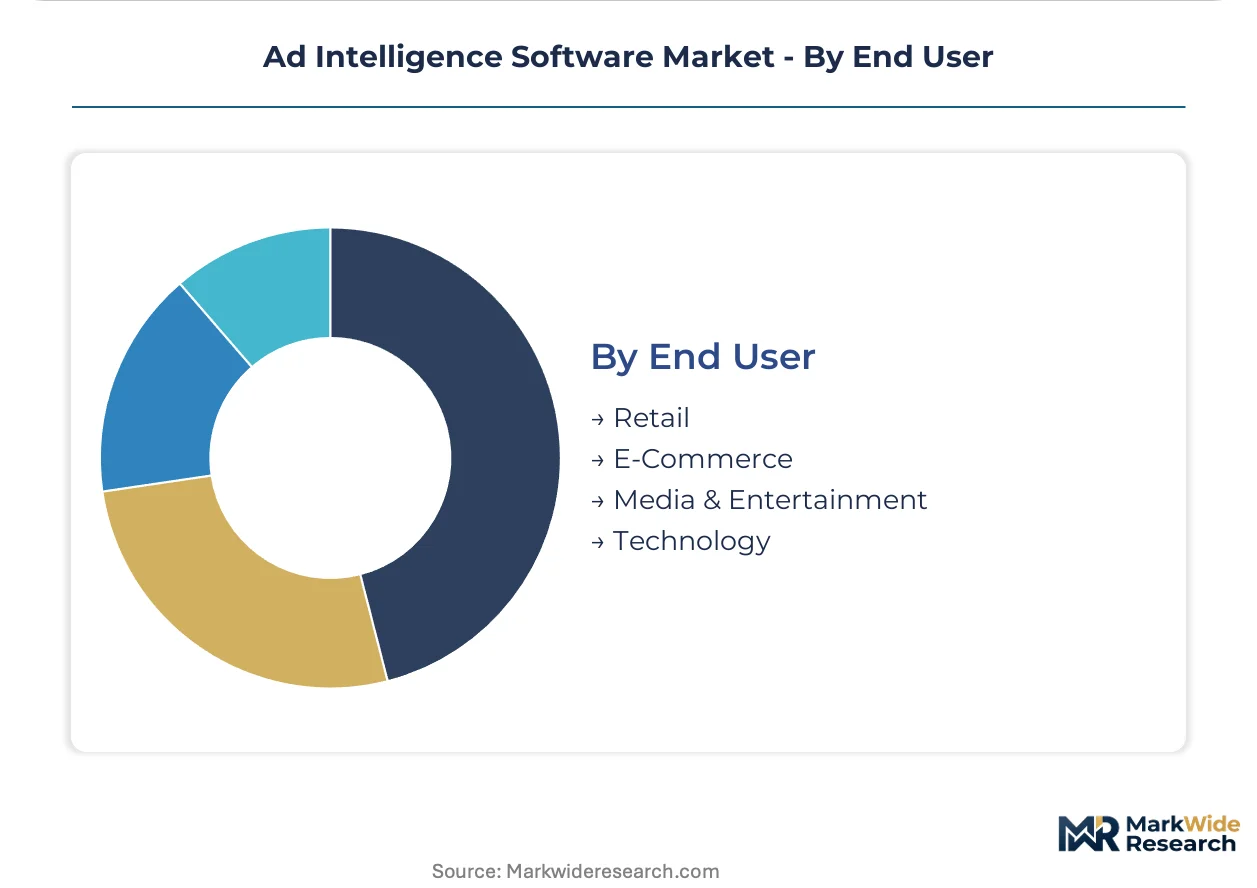
E-commerce platform growth generates the steepest demand curve for closed-loop competitive intelligence outside traditional programmatic channels.
- E-Commerce:Amazon, Walmart, and Target advertising platforms operate as walled gardens requiring specialized data extraction methods. Direct-to-consumer brands demand hourly refresh cycles during peak promotional periods.
- Retail:Brick-and-mortar chains use ad intelligence to coordinate digital and physical promotional calendars. United States retailers concentrate procurement pull through consolidated martech stacks.
- Media & Entertainment:Streaming platform advertising growth outpaces available competitive monitoring tools.
- Technology:B2B software vendors track competitor messaging and channel mix shifts.
E-Commerce holds the dominant position, with Retail climbing fastest as omnichannel coordination requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidance on digital political ad disclosures anchors procurement urgency in the United States, while GDPR and the EU AI Act reshape European vendor architectures. Demand concentrates where programmatic advertising spend and martech consolidation intersect.
United States
Programmatic advertising spend concentration and retailer demand for real-time competitive monitoring drive procurement velocity. FCC disclosure requirements for digital political advertising add compliance layers to platform design. New York and San Francisco media technology clusters host the densest vendor development activity.
Germany
GDPR enforcement through CNIL-aligned state regulators creates procurement urgency for privacy-preserving competitive intelligence architectures. The EU AI Act transparency obligations for automated ad targeting systems impose additional product requirements. Berlin and Munich advertising technology hubs concentrate R&D investment in explainable AI for media planning.
United Kingdom
Media agency consolidation and holding company-level enterprise agreements compress vendor counts while expanding contract values. The Information Commissioner's Office guidance on competitive data processing shapes platform data sourcing methods. London's Soho and Shoreditch districts anchor the densest concentration of ad tech development and agency procurement decision-making.
France
ANSM and CNIL regulatory frameworks intersect with EU AI Act requirements for automated decision-making in advertising systems. Retail media network expansion at Carrefour and other domestic platforms drives specialized competitive intelligence demand. Paris advertising technology clusters concentrate vendor relationships with luxury and FMCG brand headquarters.
Japan
METI industrial policy supports advertising technology modernization as part of broader digital transformation initiatives. Domestic platform gatekeepers impose API rate limiting that constrains real-time competitive data extraction. Tokyo's Roppongi and Shibuya districts host the primary concentration of media agency technology procurement and vendor development.
Ad Intelligence Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the ad intelligence software market. The upper tier combines competitive intelligence, brand safety, and verification capabilities into unified enterprise platforms. Specialists concentrate on single-channel visibility or regional market coverage. M&A activity consolidates point solutions into comprehensive suites, while strategic partnerships with retail media networks open closed-loop attribution channels.
Within the integrated platform tier, Similarweb and Oracle exemplify archetypes that anchor enterprise competitive analysis through deep data infrastructure and media verification integration. AdClarity occupies a specialist position representing vendors that concentrate visibility on programmatic and social advertising ecosystems. These three companies illustrate how geographic origin and corporate structure—publicly traded technology platforms versus focused competitive intelligence specialists—determine strategic positioning in procurement negotiations with media agencies and large enterprises.
| Leading Market Players |
|---|
| Adbeat |
| Admetricks |
| Similarweb |
| AdMobiSpy |
| Poltio |
| AdClarity |
| iSpionage |
| Integral Ad Science |
| Moat by Oracle |
| Others |
Pricing and Supply Chain Analysis
GDPR compliance certification gates both vendor qualification and subscription pricing tiers in European procurement, compressing margins for non-compliant architectures while enabling premium positioning for privacy-preserving platforms. United States buyers pay spreads of 40-60% above European equivalents for real-time data refresh capabilities, reflecting API infrastructure costs and competitive intensity differentials.
Pricing Analysis
United States-based retailers pay the steepest premiums for hourly refresh cycles during promotional windows, while European buyers face compressed pricing due to GDPR-constrained data processing. Three-tier pricing structure across premium, standard, and economy levels segments by data granularity, API call volume, and integration complexity. Cost compression in the standard tier intensifies because cloud infrastructure scaling pressures SaaS unit economics. Marketing agencies exhibit the highest price sensitivity, demanding outcome-based structures, while large enterprises absorb premium tiers for unified platform consolidation.
Supply Chain Analysis
Just-in-time data ingestion dominates cloud-native deployments, though financial services and healthcare advertisers maintain strategic stockpiles through hybrid architectures for compliance segmentation. Supply concentrates in the United States, Germany, and the United Kingdom, where programmatic advertising spend density and martech development clusters anchor vendor R&D. Raw material dependencies span cloud compute capacity from hyperscalers, machine learning engineering talent pools, and API access agreements with platform gatekeepers. Single-source vulnerability runs through dominant cloud infrastructure providers. Distribution runs through direct enterprise sales teams and media agency holding company partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ad intelligence software market sits at a high-growth inflection as the EU AI Act mandates explainability documentation for automated media planning systems, forcing architectural reinvention across competitive platforms.
For Market Incumbents: Secure API rate limit agreements with platform gatekeepers before throttling intensifies, protecting real-time dashboard refresh capabilities that anchor premium pricing. Invest in privacy-preserving computation R&D to maintain European market access as GDPR enforcement tightens. For New Entrants and Emerging Players: Lead with connected TV ad intelligence specialization, where streaming platform advertising growth outpaces available competitive monitoring tools. Target mid-market e-commerce direct-to-consumer brands with self-service interfaces priced below enterprise tiers, using retail media network partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: The EU AI Act reshapes the acquisition landscape toward vendors with embedded audit trails and human oversight protocols already operational. Long-term viability favors platforms spanning competitive intelligence, brand safety, and verification rather than point solutions. Watch for consolidation signals when media agency holding companies reduce vendor counts below three per functional category.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Migration | GDPR and EU AI Act compliance enables continued European market participation for SaaS vendors. |
| Retail Media Network Partnership | Amazon and Walmart closed-loop attribution access unlocks competitive intelligence outside programmatic channels. |
| Machine Learning Engineer Recruitment | Advertising domain expertise in data science talent pools accelerates automated creative classification development. |
| Connected TV Monitoring Capability Buildout | Streaming platform advertising growth creates whitespace for creative and placement tracking specialization. |
| Outcome-Based Pricing Model Pilot | Media agency procurement committees favor subscription structures tied to measurable competitive advantage. |
Research Methodology
A standing panel of media agency procurement directors, ad tech platform engineers, brand marketing executives, and competitive intelligence product managers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings of publicly traded ad technology vendors, IAB programmatic spend reports, and hyperscaler cloud infrastructure disclosures. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against end-user procurement patterns.
Consistency checks validated segment-level outputs against external benchmarks including media agency holding company technology spend disclosures and martech stack consolidation surveys. The analytical framework modeled deployment model, organization size, vertical industry, data integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from historical growth trajectory analysis adjusted for regulatory inflection impacts. Forecast inputs incorporated API rate limiting trends and cloud infrastructure cost curves specific to real-time data processing workloads.
The analysis sits within stated boundaries; outcomes outside sustained programmatic advertising spend concentration or accelerated privacy regulation enforcement would require recalibration. Forecasts reflect documented assumptions regarding platform gatekeeper data access policies and machine learning talent availability. Revision becomes warranted when cross-border data fragmentation severity crosses thresholds that prevent unified global competitive dataset construction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Web Performance Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
G2P Systems Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Online Voting System Market
Digital Solutions
Transport Management System Market