
 Cloud Electronic Design Automation Market | 2026-2036
Cloud Electronic Design Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Electronic Design Automation Market Analysis
The gap between premium full-platform suites and commodity point-tool access is shifting procurement patterns across the Cloud Electronic Design Automation landscape. Cadence Design Systems leverages deep integration between analog and digital workflows to anchor high-margin enterprise contracts. AWS competes on elastic compute pricing for burst verification workloads. Synopsys differentiates through AI-driven design optimization layers that extend beyond baseline cloud hosting.
Cloud Electronic Design Automation delivers semiconductor design, simulation, and verification capabilities through distributed computing infrastructure, enabling nanometer-scale chip development without on-premise server farms. The technology serves fabs, fabless designers, and system architects who require parallel processing of billion-transistor layouts. Public cloud deployment leads in volume among startups and mid-size design houses seeking pay-per-use elasticity, while hybrid cloud configurations capture margin pools at top-tier semiconductor companies managing proprietary IP. Verification tools represent the fastest-growing solution type as chip complexity outpaces traditional simulation capacity.
FDA oversight of software-as-a-medical-device intersects with FCC equipment authorization rules for chips destined for wireless and automotive radar systems, tightening validation requirements for EDA outputs. The EU AI Act and REACH chemical disclosure standards for semiconductor materials further constrain how European design houses select cloud infrastructure. Stakeholders must monitor evolving export control classifications for advanced node design automation to anticipate access restrictions on China-bound workflows.
Market Dynamics
Semiconductor design teams are migrating compute-intensive verification workloads to cloud infrastructure as transistor counts at 3nm and below exceed on-premise simulation capacity. This structural migration is compressing traditional perpetual-license software models and forcing vendors to re-architect pricing around consumption metrics.
Growth Catalysts
- AI Chip Complexity:Generative AI accelerators require billion-transistor layouts that demand elastic parallel processing. Cloud EDA platforms provide burst capacity without capital-intensive server farms.
- EU AI Act Compliance:European semiconductor designers face mandatory algorithmic transparency requirements for chips embedded in high-risk AI systems. Cloud-based verification trails satisfy audit documentation standards.
- Foundry Ecosystem Concentration:Taiwan, South Korea, and the United States host advanced node production. Proximate cloud regions reduce latency for design-to-tapeout workflows.
Market Restraints
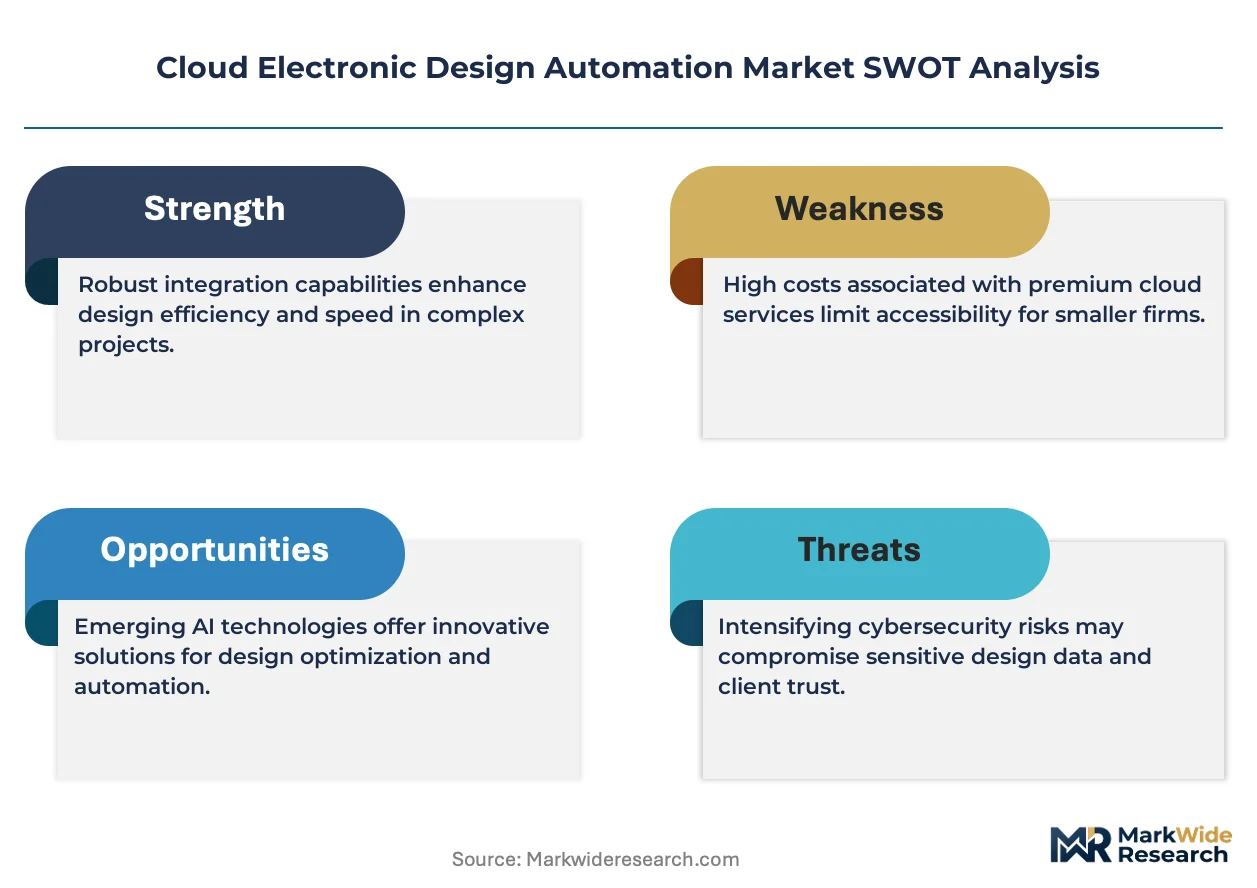
- Data Sovereignty Friction:China's MIIT cross-border data transfer rules restrict where simulation data can reside. Design houses face architectural constraints on multi-region cloud deployments.
- Specialized Talent Scarcity:Cloud-native EDA engineering requires rare hybrid skills spanning semiconductor physics and distributed systems architecture. Compensation inflation concentrates expertise at top-tier vendors.
- Hybrid Integration Costs:Legacy on-premise toolchains at established semiconductor companies require expensive middleware layers. Total cost of ownership often exceeds pure-cloud alternatives.
Strategic Opportunities
- India Design Services:The country's PLI scheme for semiconductor manufacturing is spawning fabless startups. These entrants lack legacy infrastructure and represent greenfield cloud EDA adoption.
- Automotive Functional Safety:ISO 26262 certification requirements for autonomous vehicle chips favor cloud platforms with embedded traceability. Vendors can bundle compliance tooling as premium tiers.
- Photonics-Electronics Convergence:Silicon photonics design requires multi-physics simulation. Cloud elasticity accommodates intermittent high-fidelity optical-electrical co-simulation workloads.
Industry Challenges
- IP Leakage Risk Management:Proprietary cell libraries and process design kits represent crown-jewel assets. Cloud migration requires zero-trust security architectures that add implementation complexity.
- Multi-Cloud Orchestration:Enterprise procurement teams demand workload portability across AWS, Azure, and Google Cloud. EDA vendors must maintain functional parity across divergent infrastructure APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Electronic Design Automation Market |
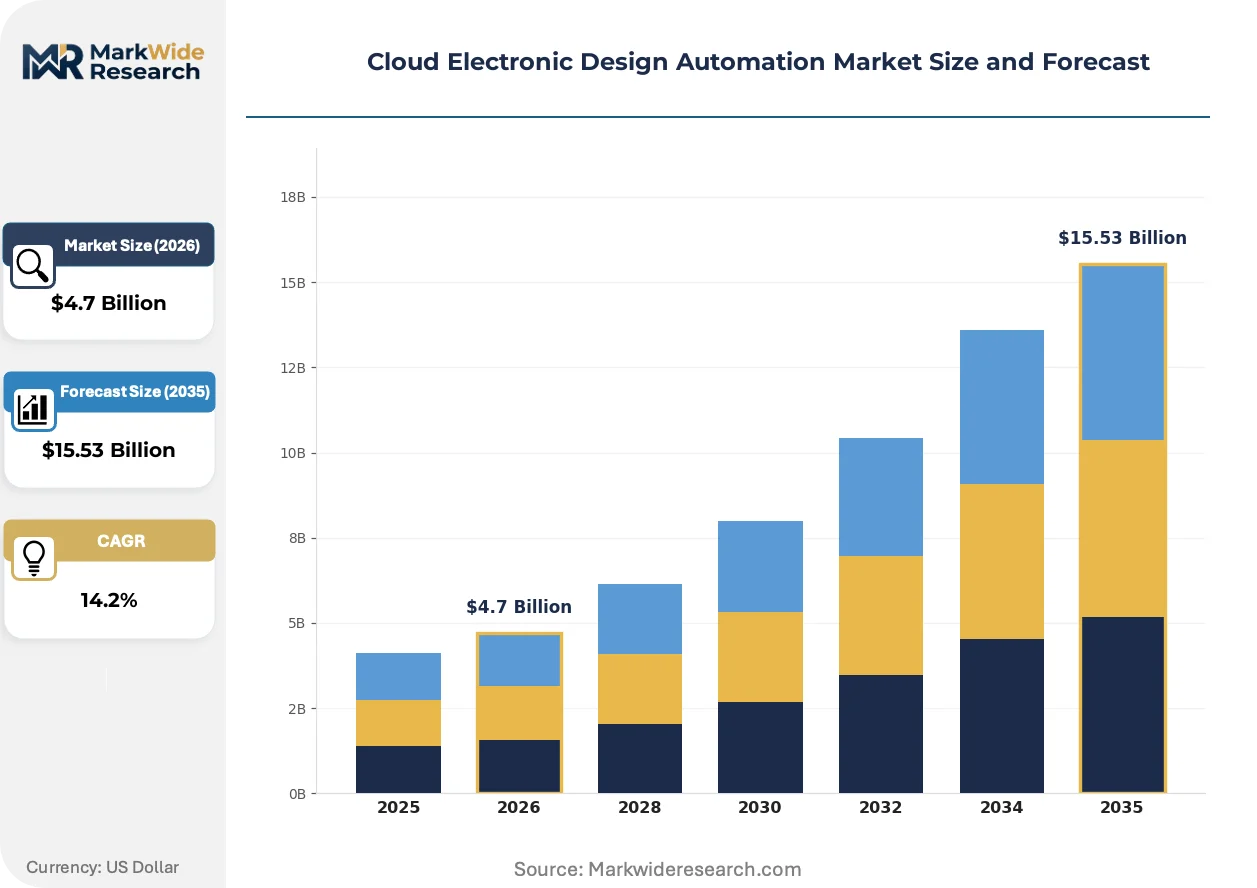
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Analog Design, Digital Design, Mixed-Signal Design, Verification Tools End User: Semiconductor Companies, System Integrators, OEMs, Design Houses Application Sector: Telecommunications, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Keysight Technologies, Arteris, Synopsys, Microsoft Azure, AWS, Cadence Design Systems, Mentor Graphics, Google Cloud Platform, ANSYS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Electronic Design Automation Market Emerging Trajectories
Computational lithography and AI-assisted place-and-route are converging with cloud-native delivery models. This convergence is altering how design teams provision resources and how vendors capture value.
GPU-accelerated electromagnetic simulation is absorbing finite element analysis workloads previously executed on CPU clusters. Fabless designers in the United States and China are adopting these platforms for 5G mmWave and automotive radar chip development. The technology is absorbing margin from traditional field-solver licensing by bundling compute with software.
The EU AI Act's risk classification system imposes documentation burdens on chips embedded in automated decision-making systems. European design houses must maintain algorithmic audit trails from architecture through verification. Automotive and medical device semiconductor segments are responding by selecting cloud platforms with native compliance logging.
Consumption-based licensing is displacing traditional enterprise agreements among mid-size design houses. Engineering managers now prefer metered access that scales with tapeout schedules rather than fixed annual commitments. This behavioral shift is most visible in Germany and Israel where startup density intersects with sophisticated procurement functions.
Cloud Electronic Design Automation Market Segmentation
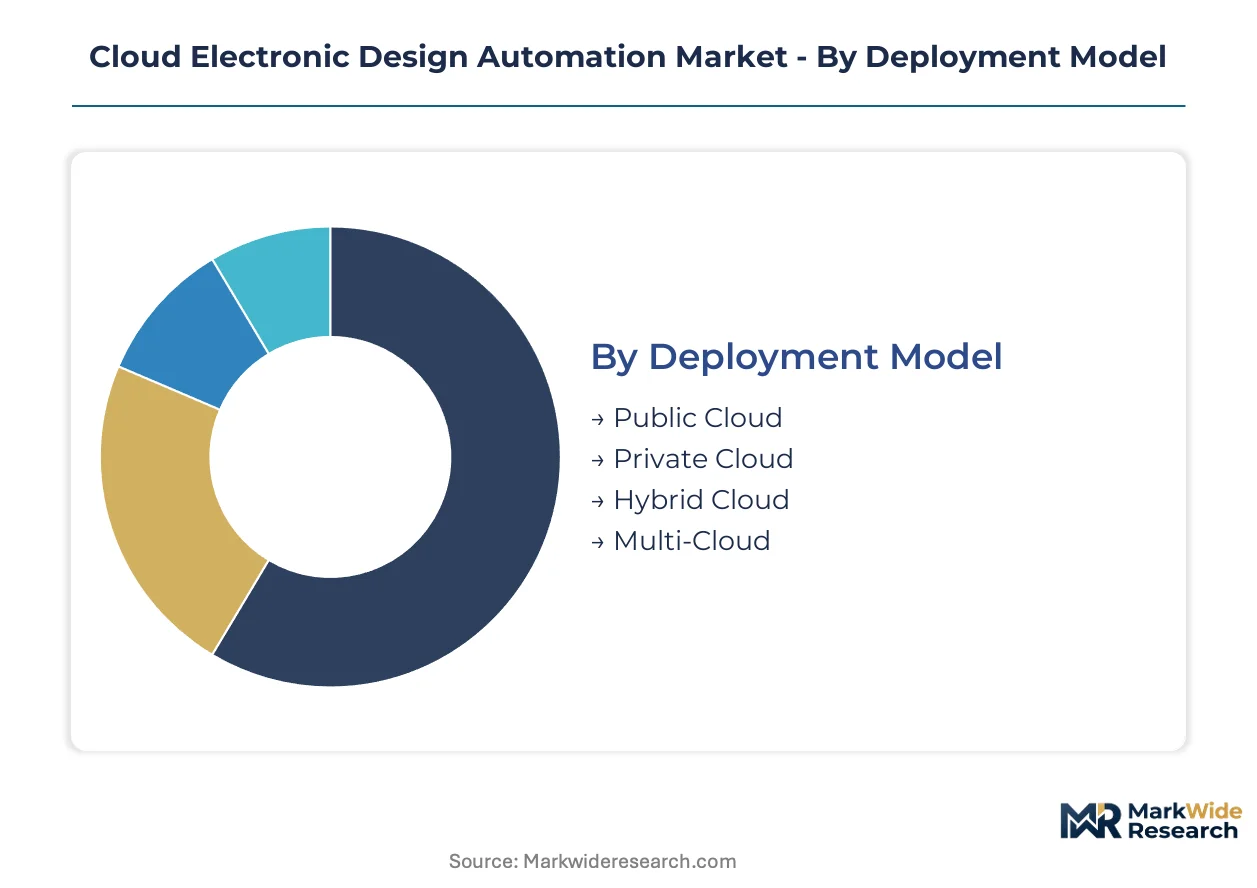
Cloud Electronic Design Automation procurement patterns diverge sharply across deployment preferences, design disciplines, and end-user sophistication. Buyers prioritize elastic capacity for burst verification workloads, while regulatory constraints reshape infrastructure selection.
Deployment Model:
Cost tier separates risk-tolerant startups from IP-protective enterprises.
- Public Cloud:Shared infrastructure delivers pay-per-use elasticity for simulation bursts. Fabless startups in Israel and Germany favor this model for tapeout cycles without capital commitment. AWS, Azure, and Google Cloud compete on GPU instance pricing for electromagnetic workloads.
- Hybrid Cloud:Split architectures keep proprietary cell libraries on-premise while bursting verification to cloud. Top-tier semiconductor companies in the United States and Taiwan accept higher integration costs to satisfy IP protection mandates. Middleware layers add implementation complexity.
- Private Cloud:Dedicated infrastructure serves defense contractors and classified foundry partnerships. Air-gapped environments satisfy export control requirements for advanced node development. Capital intensity limits adoption to government-funded programs.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud reduces vendor lock-in. Enterprise procurement teams in Germany demand functional parity across divergent APIs. Orchestration overhead constrains deployment to mature IT organizations.
Public Cloud leads volumes today; Hybrid Cloud is gaining share fastest.
Solution Type:
Application complexity dictates tool selection, with verification demands outpacing design capacity.
- Verification Tools:Functional, formal, and physical verification suites process billion-transistor layouts through distributed simulation farms. Cloud elasticity accommodates peak demand during pre-tapeout signoff. AI accelerator designs in the United States and China drive steepest expansion trajectory.
- Digital Design:Place-and-route, synthesis, and timing closure tools target nanometer-scale logic implementation. AI-assisted optimization layers from Synopsys and Cadence command premium pricing. Foundry-certified flows anchor enterprise contracts.
- Analog Design:Custom layout, schematic capture, and SPICE simulation serve precision circuits in automotive radar and medical devices. Germany's automotive semiconductor cluster sustains specialized demand. Cloud migration lags digital workflows due to iteration intensity.
- Mixed-Signal Design:Co-simulation of analog and digital domains requires tight integration between previously siloed toolchains. Silicon photonics convergence in Taiwan and South Korea creates intermittent high-fidelity workload spikes.
Verification Tools dominate revenue today; Mixed-Signal Design is climbing the fastest.
End User:
Customer maturity shapes procurement sophistication and contract structure.
- Semiconductor Companies:Integrated device manufacturers and fabless designers consume the broadest platform suites. Perpetual-license conversion to consumption-based models compresses vendor margins. Foundry ecosystem proximity drives cloud region selection.
- Design Houses:Specialized service providers deliver tapeout expertise to system companies lacking in-house capability. India's PLI-spawned fabless startups represent greenfield cloud adoption without legacy migration burden.
- OEMs:Automotive and aerospace system companies bring chip design in-house for supply security. ISO 26262 and DO-254 certification requirements favor platforms with embedded traceability. Compliance tooling bundles command premium tiers.
- System Integrators:Defense and telecommunications contractors aggregate EDA access for subcontractor ecosystems. Multi-tenant security architectures and FedRAMP authorization constrain vendor qualification.
Semiconductor Companies anchor spending today; OEMs are expanding most quickly.
Application Sector:
Regulatory intensity and performance requirements fragment demand patterns.
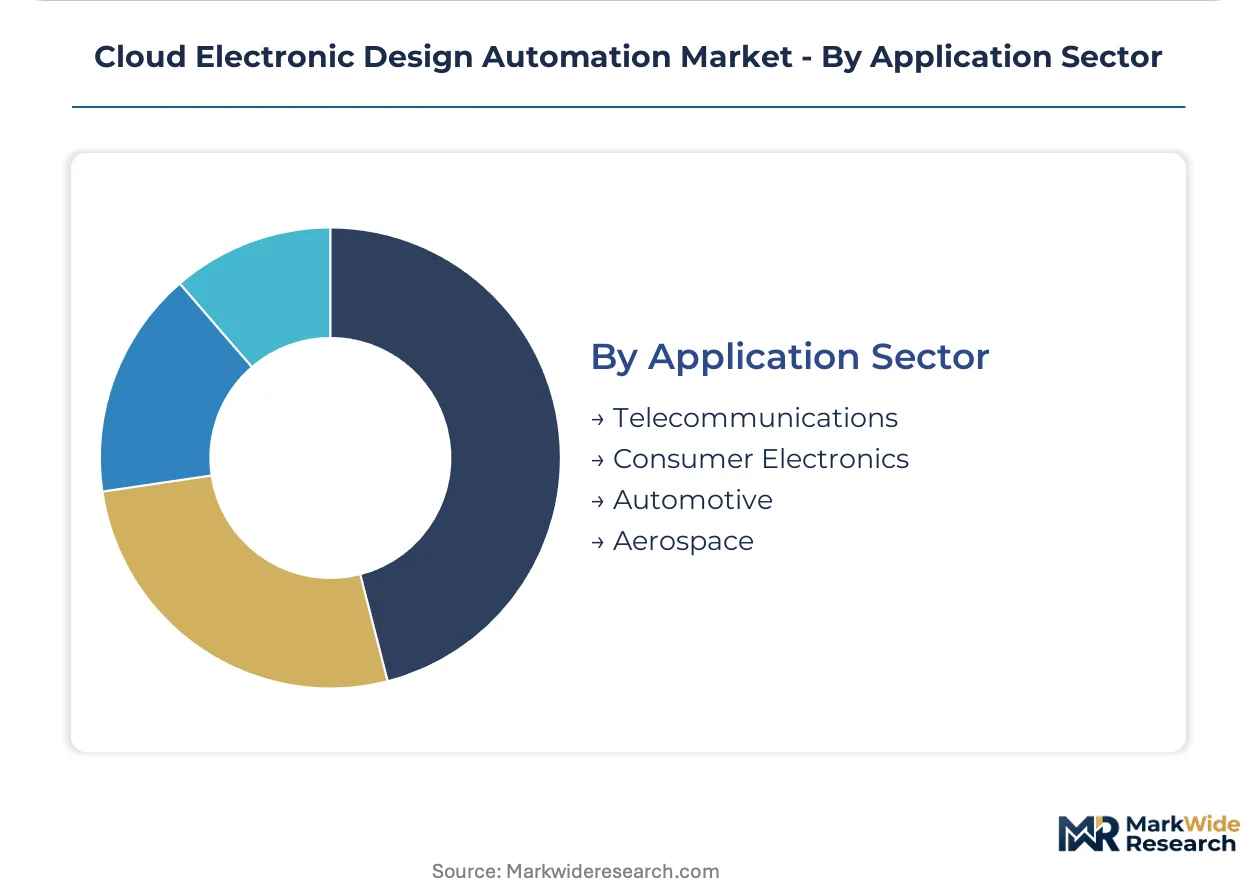
- Automotive:Autonomous vehicle chips and electric powertrain controllers demand functional safety certification. ISO 26262 traceability requirements favor cloud platforms with native audit logging. German design houses prioritize compliance-embedded workflows.
- Telecommunications:5G mmWave baseband and RF front-end development requires electromagnetic simulation at scale. FCC equipment authorization rules tighten validation requirements for cloud-generated design outputs.
- Consumer Electronics:Smartphone and wearable chip designs prioritize time-to-market over absolute performance. Shorter tapeout cycles favor elastic cloud capacity over capital-intensive on-premise farms.
- Aerospace:Satellite and avionics semiconductors face DO-254 and DO-178C certification burdens. Radiation-hardened design flows remain predominantly on-premise due to ITAR and export control sensitivity.
Consumer Electronics leads volume today; Automotive is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud EDA talent concentrates in three distinct corridors: Silicon Valley's verification engineering pools, Taiwan's foundry-adjacent design centers, and Germany's automotive semiconductor clusters. Each geography cultivates specialized workforce capabilities that shape local procurement patterns.
United States
AI accelerator startups in Austin and San Diego drive burst-capacity verification demand. FCC equipment authorization rules tighten validation documentation for wireless chip exports. The Silicon Valley-San Jose corridor hosts the densest concentration of cloud-native EDA engineering talent.
China
MIIT cross-border data transfer rules constrain multi-region simulation deployments for advanced node designs. Domestic cloud providers compete with hyperscalers on sovereign infrastructure compliance. Shanghai and Beijing design houses prioritize local data residency for proprietary cell libraries.
Germany
Automotive functional safety requirements under KBA oversight favor platforms with embedded ISO 26262 traceability. Munich and Stuttgart semiconductor clusters sustain specialized analog-mixed-signal demand. Engineering managers prefer consumption-based contracts aligned with tapeout schedules.
Taiwan
Foundry ecosystem proximity reduces latency for design-to-tapeout workflows at TSMC-adjacent facilities. The Hsinchu Science Park anchors the highest density of advanced node design activity. Local cloud regions serve burst verification for 3nm and below transistor layouts.
India
PLI scheme incentives spawn fabless startups lacking legacy on-premise infrastructure. BIS semiconductor standards shape quality certification requirements for domestic design houses. Bengaluru and Hyderabad emerge as greenfield cloud EDA adoption centers without migration burden.
Cloud Electronic Design Automation Market Vendor Landscape
Capital-heavy foundry operators compete with asset-light fabless designers for platform influence, compressing vendor margins across the Cloud EDA landscape. The vendor base stratifies into three tiers: full-platform suite providers, point-tool specialists, and infrastructure-as-a-service hyperscalers. Dominant competitive moves include consumption-based pricing re-architecture and multi-cloud API parity investments.
Within the full-platform tier, Cadence Design Systems and Synopsys exemplify integrated workflow providers anchoring high-margin enterprise contracts. AWS occupies a distinct position among hyperscalers competing on elastic compute pricing for electromagnetic simulation bursts. These three entities represent the primary competitive anchors shaping procurement negotiations across semiconductor design houses.
| Leading Market Players |
|---|
| Keysight Technologies |
| Arteris |
| Synopsys |
| Microsoft Azure |
| AWS |
| Cadence Design Systems |
| Mentor Graphics |
| Google Cloud Platform |
| ANSYS |
| Others |
Supply Flow & Price Mechanics
GPU-accelerated electromagnetic simulation is compressing traditional field-solver licensing economics while concentrating compute procurement among hyperscalers with captive silicon foundry partnerships. This technology transition simultaneously erodes perpetual-license margins and anchors supply influence among AWS, Azure, and Google Cloud.
Pricing Analysis
Bundled compute-plus-software offerings from hyperscalers are displacing unbundled tool licensing among mid-size design houses. Three-tier pricing structure across enterprise, professional, and developer levels separates foundry-certified flows from commodity simulation access. Cost compression in the professional tier is intensifying because Cadence and Synopsys are matching consumption-based elasticity. Fabless startups in Israel and Germany exhibit highest price sensitivity; defense contractors with air-gapped requirements show lowest.
Supply Chain Analysis
Certification gating through FedRAMP authorization and ISO 26262 traceability requirements constrains vendor qualification for automotive and aerospace procurement. Taiwan, South Korea, and the United States anchor advanced node EDA tool development. Supply draws from specialized GPU foundry capacity, high-bandwidth memory modules, and proprietary process design kits. Single-source vulnerability concentrates in TSMC's leading-edge fabrication for AI training chips. Distribution runs through direct enterprise sales with foundry partnership co-selling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT-constrained domestic cloud infrastructure and Germany's ISO 26262-preferenced procurement creates divergent margin pools for platform vendors. The cost differential stems from compliance overhead versus sovereign data residency requirements.
For Market Incumbents: Deploy multi-cloud API parity investments to neutralize hyperscaler bundling threats. Cadence and Synopsys must accelerate consumption-based pricing re-architecture before AWS captures electromagnetic simulation bursts. Foundry-certified flow exclusivity remains the defensive moat against commodity compute erosion.
For New Entrants and Emerging Players: Begin with India's PLI-spawned fabless startups as greenfield cloud-native adopters lacking legacy migration burden. Photonics-electronics co-simulation represents the most penetrable white space given intermittent high-fidelity workload spikes. Partner with domestic cloud providers in China to satisfy MIIT data residency mandates.
For Investors and Strategic Acquirers: Valuations sit cheapest among point-tool specialists with automotive functional safety certification. Long-term viability hinges on 5-10 year automotive semiconductor content expansion. Watch for MIIT relaxation on cross-border data transfers as inflection signal for China market re-entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud API Parity Investment | Enables workload portability across AWS, Azure, and Google Cloud for enterprise procurement teams. |
| Consumption-Based Pricing Re-architecture | Aligns vendor revenue with tapeout schedules preferred by German and Israeli engineering managers. |
| Automotive Functional Safety Certification | ISO 26262 traceability embeds compliance tooling as premium tier for autonomous vehicle chip demand. |
| Photonics-Electronics Convergence Platform | Silicon photonics multi-physics simulation captures intermittent workload spikes in Taiwan and South Korea. |
| India Design Services Partnership | PLI scheme fabless startups represent greenfield adoption without legacy on-premise infrastructure burden. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's semiconductor design centers. The study combines interviews with EDA platform engineers, foundry partnership managers, cloud procurement officers, and automotive functional safety leads with secondary validation from SEC filings, hyperscaler capex disclosures, and foundry process roadmaps. Bottom-up and top-down triangulation cross-checks segment sizing against aggregate market estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation models deployment mode, solution type, end-user sophistication, and application sector regulatory intensity. CAGRs derive from elasticity-adjusted adoption curves and foundry capacity expansion timelines. AI accelerator design complexity and EU AI Act compliance documentation burdens serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including explicit export control enforcement actions and foundry process node delays beyond announced roadmaps. Forecasts reflect assumptions about hyperscaler infrastructure expansion and regulatory stability. A model refresh is warranted upon material change in China cross-border data transfer enforcement or automotive semiconductor certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
US Transcription Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
United States ICT Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Load Balancer Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Decision Support System Market