
 Restaurant POS Terminals Market | 2026-2036
Restaurant POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant POS Terminals Market Analysis
Multi-source procurement for payment hardware is hardening as restaurant chains reduce dependency on single vendors. NCR Corporation anchors its position through captive manufacturing of fixed terminals and kitchen display systems. Toast, Inc. differentiates via vertical integration into software subscriptions and payment processing. Square, Inc. competes aggressively on mobile POS form factors targeting independent cafes and food trucks.
Restaurant POS terminals combine touchscreen interfaces, payment card readers, and order-routing software to process transactions and synchronize kitchen operations in foodservice environments. Fixed POS units typically integrate thermal printers, cash drawers, and dual displays with processor speeds above 1.8 GHz to sustain sub-second transaction authorization. Mobile POS and cloud-based POS are expanding fastest as operators prioritize tableside ordering and centralized menu management across locations. Self-service kiosks command higher average selling prices but face longer replacement cycles in quick-service deployments.
FCC certification governs wireless communication modules in US-sold terminals, while PCI DSS mandates encrypt payment data at the point of interaction. EMA and national data protection authorities across Europe enforce GDPR-compliant transaction logging, constraining cloud storage architectures. Operators must monitor evolving contactless payment standards and regional certification timelines when planning hardware refresh schedules.
Market Dynamics
PCI Security Standards Council contactless payment mandates are forcing hardware refresh cycles across restaurant chains, compressing replacement timelines from five-year cycles to three-year intervals as operators race to maintain certification compliance.
Growth Catalysts
- Contactless payment mandates:PCI DSS contactless certification requirements in North America and Europe are compelling terminal upgrades at quick-service restaurants and full-service dining chains.
- Cloud POS migration:Centralized menu management and real-time analytics are pulling independent operators toward subscription-based software platforms.
- Kitchen integration demand:Quick-service restaurants are deploying order-routing systems that synchronize front-of-house terminals with kitchen display systems to reduce ticket times.
Market Restraints
- Semiconductor supply concentration:Processor and wireless module fabrication concentrates in East Asian foundries, exposing terminal manufacturers to allocation volatility.
- GDPR compliance friction:European data protection authorities enforce transaction logging constraints that complicate cloud storage architectures for multi-national operators.
- Mobile wallet substitution:Smartphone-based payment applications reduce dependency on dedicated terminal hardware at food trucks and pop-up venues.
Strategic Opportunities
- Self-service kiosk expansion:Quick-service chains in the United States are deploying customer-facing ordering stations to reduce labor costs and lift average ticket values.
- Tableside ordering penetration:Full-service restaurants are adopting handheld tablets to capture orders at the point of decision and reduce server table turns.
- IRA energy incentives:United States operators can offset terminal fleet electrification and low-power hardware upgrades through federal efficiency credits.
Industry Challenges
- FCC certification timelines:Wireless module approvals for new terminal models face backlog delays that extend product launch windows by four to six months.
- Legacy system integration:Established point-of-sale databases and proprietary kitchen protocols resist seamless migration to cloud-native architectures.
- Payment security expertise scarcity:End-to-end encryption implementation and tokenization management require specialized engineering talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant POS Terminals Market |
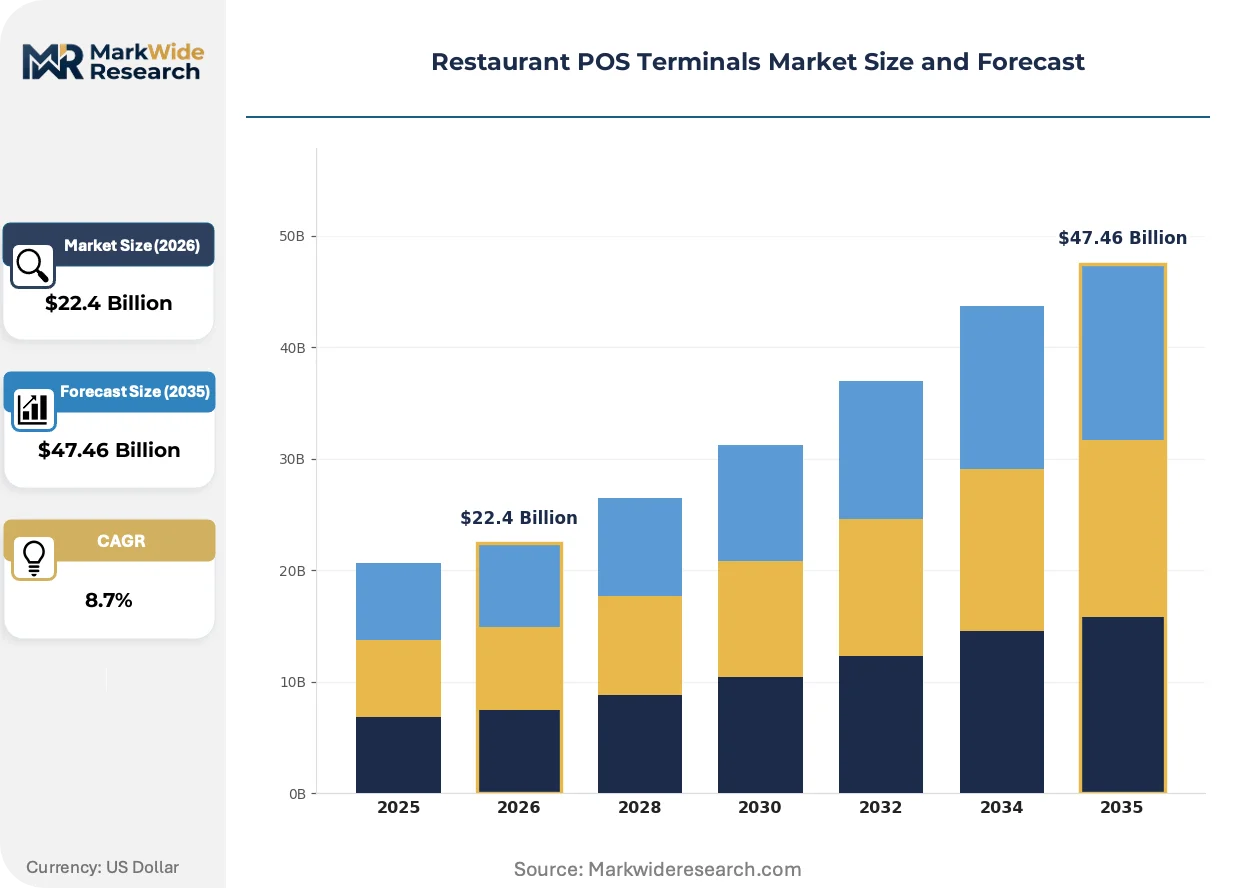
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $47.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Self-Service Kiosks, Cloud-Based POS Technology: Contactless Payments, NFC, QR Code, EMV Chip End User: Full-Service Restaurants, Quick Service Restaurants, Cafes, Food Trucks Deployment: On-Premise, Cloud, Hybrid, Managed Service |
| Companies Covered | NCR Corporation, Toast, Inc., Oracle Corporation, Square, Inc., Diebold Nixdorf, ParTech, Inc., PAX Technology, Revel Systems, Lightspeed Commerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant POS Terminals Market Emerging Trajectories
Restaurant point-of-sale architecture is converging around unified commerce platforms that collapse transaction processing, inventory management, and labor scheduling into single-pane dashboards. This consolidation is redrawing vendor competitive boundaries.
Android-based operating systems are consolidating control over terminal software stacks, displacing legacy Windows Embedded platforms across mid-market deployments. Independent cafes and regional chains are adopting these open-ecosystem devices to reduce licensing costs and enable custom application development. The shift is compressing margins for proprietary operating system licensors while expanding addressable market for white-label hardware manufacturers.
FCC certification requirements for 5G and Wi-Fi 6E modules are tightening electromagnetic compatibility testing protocols for terminals sold in the United States. Manufacturers must submit expanded documentation on radio frequency emissions, extending pre-market approval timelines. Quick-service restaurant chains with aggressive deployment schedules are responding by front-loading hardware procurement to buffer against regulatory delays.
Franchise networks are consolidating vendor relationships to secure volume pricing and standardized support terms across multi-state operations. Independent operators and small chains are losing access to tier-one service tiers as manufacturers prioritize enterprise accounts with minimum order commitments. The concentration is most visible in the United States, where large franchise systems account for the majority of annual terminal procurement volume.
Restaurant POS Terminals Market Segmentation
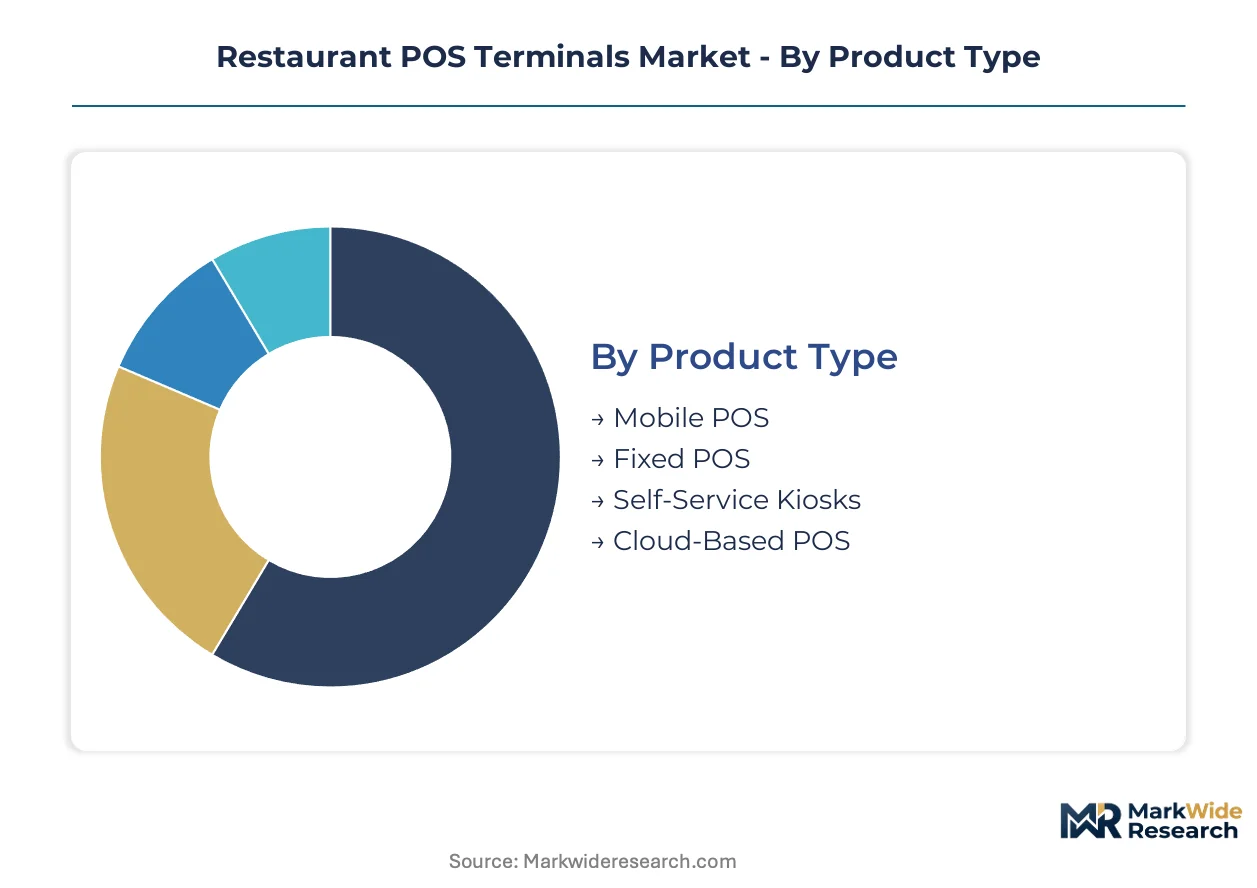
Restaurant POS terminal procurement patterns diverge sharply across hardware form factors, payment protocols, and operational models. Chains calibrate segment mix against table-turn velocity, labor cost structure, and PCI compliance timelines.
Product Type:
Hardware refresh cycles vary dramatically by terminal mobility and installation footprint, with replacement timelines stretching from eighteen months for handheld units to seven years for fixed counter installations.
- Mobile POS:Handheld tablets and smartphone peripherals process payments tableside via Bluetooth-connected card readers. Full-service restaurants in the United States deploy these for order capture at the point of decision, reducing server steps and lifting check averages through real-time upsell prompts.
- Fixed POS:Counter-mounted terminals integrate thermal printers, cash drawers, and dual displays running processors above 1.8 GHz. Quick-service restaurants standardize on these for sub-second transaction authorization and reliable kitchen display system synchronization during peak throughput windows.
- Self-Service Kiosks:Customer-facing ordering stations command premium unit economics but face extended replacement cycles.
- Cloud-Based POS:Browser-native software layers reduce on-device processing requirements and enable centralized menu management.
Fixed POS sits at the top of the volume ranking, with Cloud-Based POS climbing the fastest.
Technology:
Payment authentication protocols are stratifying by transaction value thresholds and customer demographic profiles, with contactless methods displacing magnetic stripe infrastructure.
- Contactless Payments:Tap-to-pay cards and wearable devices transmit encrypted tokens via radio frequency. PCI Security Standards Council mandates in North America and Europe are accelerating terminal upgrades at quick-service chains to maintain certification compliance.
- NFC:Near-field communication enables smartphone wallet integration at distances under four centimeters. European operators favor this protocol for GDPR-compliant tokenization that minimizes persistent data storage.
- QR Code:Scannable matrix patterns route payments through proprietary apps without dedicated hardware.
- EMV Chip:Embedded microprocessors generate dynamic transaction codes for counterfeit protection.
EMV Chip retains the largest installed base, though Contactless Payments is expanding most quickly.
End User:
Operational tempo and average ticket size shape terminal specification requirements across dining formats.
- Full-Service Restaurants:Sit-down establishments prioritize tableside ordering tablets and split-check functionality. United States casual dining chains invest in handheld deployments to compress table turns and capture liquor orders at peak decision moments.
- Quick Service Restaurants:High-velocity counters demand ruggedized fixed terminals with integrated kitchen routing. Franchise networks drive standardization and volume procurement across multi-state operations.
- Cafes:Independent coffee shops favor compact mobile form factors for line-busting during morning rushes.
- Food Trucks:Mobile vendors rely on smartphone-based processing with minimal hardware footprint.
Quick Service Restaurants anchor procurement volume, while Full-Service Restaurants are gaining share fastest.
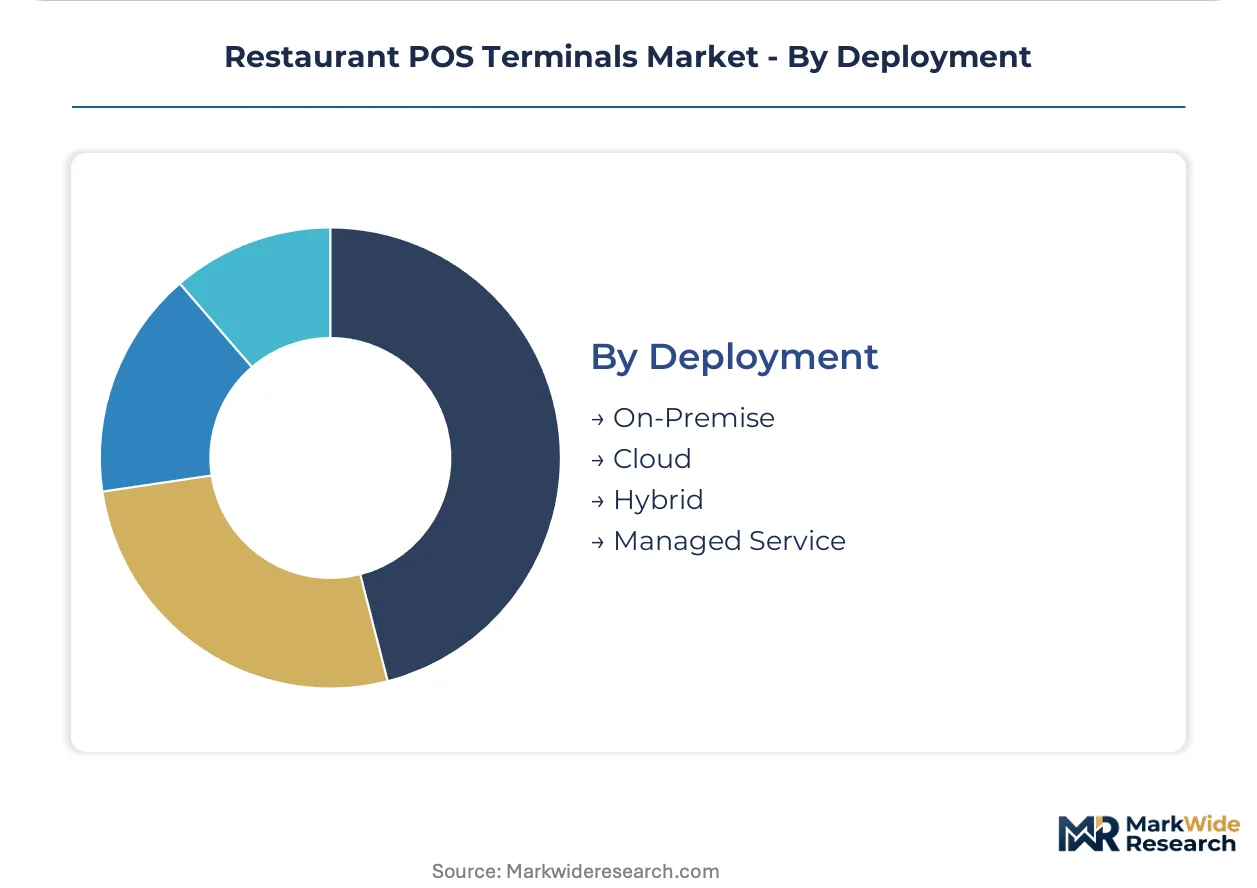
Deployment:
Data architecture decisions hinge on connectivity reliability, IT staffing levels, and multi-location visibility requirements.
- On-Premise:Local servers maintain transaction databases and menu configurations within facility boundaries. Established chains with legacy point-of-sale databases resist migration due to proprietary kitchen protocol integration costs.
- Cloud:Centralized hosting enables real-time analytics and remote menu updates across locations. Independent operators adopt these subscription platforms to reduce upfront capital expenditure and access enterprise-grade features.
- Hybrid:Edge processing with cloud synchronization balances offline resilience with centralized reporting.
- Managed Service:Third-party providers assume hardware maintenance and security patch responsibility.
On-Premise retains dominant share, with Cloud showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal manufacturers are relocating final assembly to jurisdictions with streamlined FCC-equivalent certification pathways, exploiting gaps in electromagnetic compliance costs between North American and Asian regulatory regimes.
United States
Franchise networks in Texas and Florida drive standardized procurement across thousands of quick-service locations. FCC certification timelines for 5G-enabled terminals now stretch six months, compressing hardware refresh windows. Chicago-based integrators specialize in kitchen display system synchronization for high-velocity chains.
Canada
Full-service restaurants in Toronto and Vancouver adopt tableside ordering tablets to address labor shortages in hospitality sectors. Health Canada coordinates with FCC on electromagnetic compatibility standards, reducing duplicate testing burdens. Montreal clusters host payment security consultants serving cross-border operators.
Germany
GDPR enforcement by federal data protection authorities constrains cloud storage architectures for multi-national restaurant groups. KBA-equivalent technical inspections govern wireless module approvals. Bavaria's industrial corridor manufacturers supply ruggedized fixed terminals to Central European quick-service chains.
United Kingdom
Contactless payment mandates from the Financial Conduct Authority accelerate terminal replacements at London's high-street dining clusters. Post-Brexit divergence from CE marking creates dual certification burdens for hardware importers. Manchester-based software integrators specialize in subscription-based POS platforms for independent operators.
China
Domestic quick-service chains in Shanghai and Shenzhen deploy self-service kiosks with facial recognition payment integration. MIIT certification for Wi-Fi 6E modules requires expanded radio frequency documentation. Guangdong Province foundries fabricate processor boards for terminal manufacturers serving Southeast Asian export markets.
Restaurant POS Terminals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native software layers and mobile form factors. The vendor base stratifies across three tiers: captive manufacturers with in-house fabrication, vertically integrated software-hardware platforms, and white-label hardware assemblers serving regional distributors. Two dominant competitive moves define current positioning: strategic partnerships between terminal makers and payment processors, and portfolio diversification into kitchen display systems and labor management software.
Within the captive manufacturing tier, NCR Corporation anchors North American supply through fixed terminal and kitchen system production. Toast, Inc. and Square, Inc. exemplify the vertically integrated platform model, combining hardware distribution with subscription software and payment processing revenue streams. These three entities represent divergent strategic bets on whether restaurant operators prioritize standardization, all-in-one convenience, or mobile flexibility.
| Leading Market Players |
|---|
| NCR Corporation |
| Toast, Inc. |
| Oracle Corporation |
| Square, Inc. |
| Diebold Nixdorf |
| ParTech, Inc. |
| PAX Technology |
| Revel Systems |
| Lightspeed Commerce |
| Others |
Supply Flow & Price Mechanics
Payment security engineering talent concentrated in San Francisco and Boston commands premium compensation that widens pricing spreads between certified and uncertified terminal tiers. Labor-cost differentials in firmware development and PCI compliance consulting propagate through hardware pricing, separating subscription-integrated platforms from basic terminal resellers.
Pricing Analysis
Distributor margins on fixed POS terminals compress pricing by fifteen to twenty percent below direct OEM rates for franchise networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by PCI certification grade and kitchen integration depth. Pricing pressure stems from Toast and Square subsidizing hardware to capture payment processing revenue. Independent cafes exhibit highest price sensitivity; enterprise quick-service chains prioritize total cost of ownership over unit price.
Supply Chain Analysis
Reverse logistics flows for terminal refurbishment concentrate in Shenzhen and Dongguan, where certified remanufacturing facilities restore PCI-compliant devices for secondary markets. Processor and wireless module fabrication draws from Taiwan, South Korea, and mainland China. Single-source vulnerability in advanced node semiconductors threatens allocation stability. Distribution runs through authorized resellers and direct enterprise contracts, with cloud-native vendors bypassing traditional hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
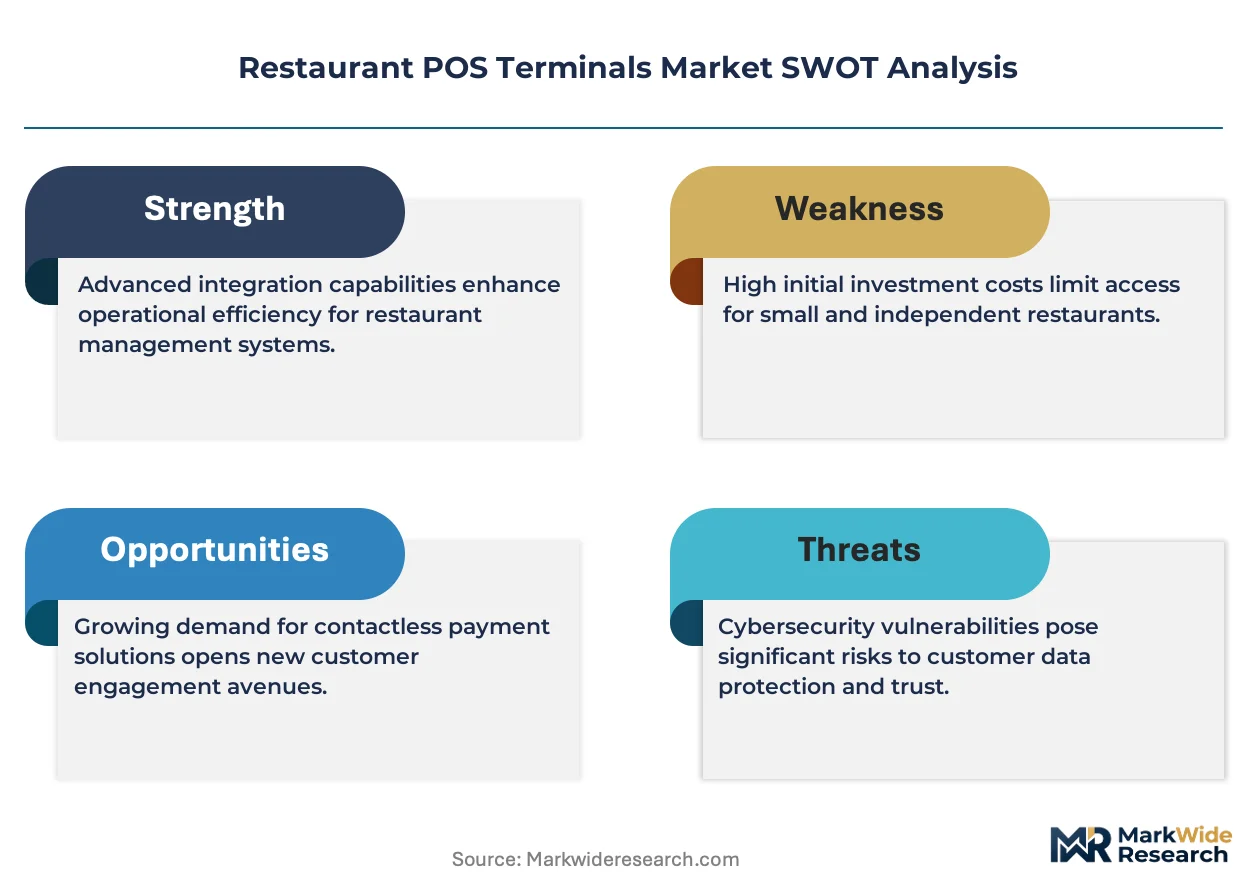
The restaurant POS terminal market functions as a regulatory compounder where PCI DSS contactless mandates force recurring hardware refresh cycles. FCC certification timelines and GDPR compliance constraints generate sustained demand for certified replacement units.
For Market Incumbents: Extend kitchen display system integration to deepen account stickiness against cloud-native entrants. Captive manufacturing of payment modules defends margin position against white-label assemblers. Investment in FCC pre-certification buffering reduces launch delays that cede share to agile competitors.
For New Entrants and Emerging Players: Independent full-service restaurants in secondary US metropolitan areas represent an underserved buyer archetype with limited access to tier-one service tiers. Tableside ordering tablets for mid-market casual dining chains offer penetrable white-space with lower certification barriers than quick-service kiosk deployments. Partner with regional payment processors for co-branded go-to-market programs.
For Investors and Strategic Acquirers: Payment processors seeking merchant lock-in are the most active acquirer in this space, valuing terminal installed base for processing revenue capture. Targets with cloud-native software stacks and existing PCI certifications offer strongest long-term viability. Monitor FCC certification backlog durations as inflection indicator for hardware vendor pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Display System Integration | Synchronizes order routing with front-of-house terminals, reducing ticket times at high-velocity quick-service chains. |
| PCI DSS Certification Investment | Maintains compliance eligibility as contactless mandates compress replacement cycles across North America and Europe. |
| Cloud-Native Platform Migration | Enables centralized menu management and real-time analytics for multi-location franchise operators. |
| 5G Module Certification | Extends FCC approval timelines but future-proofs hardware against connectivity obsolescence in US deployments. |
| Self-Service Kiosk Expansion | Captures labor cost savings and lifts average ticket values through automated upsell prompts at quick-service counters. |
Methodological Framework
Bottom-up restaurant operator modeling reconciled against top-down terminal shipment tracking forms the analytical core of this study. Primary interviews with quick-service franchise technology officers, full-service restaurant IT directors, payment security consultants, and POS reseller channel managers combined with secondary validation from PCI Security Standards Council certification databases, FCC equipment authorization filings, and SEC 10-K disclosures from publicly traded vendors. Triangulation across these sources calibrated segment-level penetration rates and replacement cycle assumptions.
Input-output matrices mapped terminal form factor demand against semiconductor supply allocations and certification timeline constraints. Segmentation dimensions modeled include hardware mobility class, payment authentication protocol, deployment architecture, and end-user operational format. CAGRs derived from logistic diffusion curves fitted to historical replacement patterns and regulatory mandate implementation schedules. Forecast inputs incorporated kitchen integration adoption rates and cloud POS subscription conversion trends.
Underlying measurement precision varies by segment; quick-service restaurant procurement carries tighter precision than food truck and pop-up venue estimates due to franchise disclosure requirements. Forecasts reflect assumptions about PCI compliance deadline adherence and FCC certification processing efficiency. Practitioners should monitor semiconductor allocation volatility and contactless payment mandate enforcement intensity for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Policy Orchestration Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Video Management System Market
Digital Solutions
Personality Assessment Solutions Market