
 Sales Acceleration Technology Market | 2026-2036
Sales Acceleration Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Acceleration Technology Market Intelligence
The EU AI Act is pivoting enterprise procurement criteria toward transparent, auditable sales automation tools. Salesforce Sales Cloud leverages its integrated CRM-to-engagement stack to anchor large-account deployments across regulated industries. Gong specializes in conversation intelligence that sustains premium pricing through differentiated revenue attribution capabilities.
Sales acceleration technology encompasses software platforms that orchestrate prospecting, engagement sequencing, predictive scoring, and revenue analytics through API-native architectures and real-time data pipelines. Its primary commercial purpose is compressing sales cycle duration while improving conversion predictability through behavioral signal processing and automated touch optimization. CRM and sales intelligence segments lead current revenue pools, while workflow automation represents the fastest-expanding margin opportunity as enterprises consolidate point solutions. Public cloud deployment dominates new implementations, though hybrid configurations are gaining traction among financial services buyers with data residency requirements.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively shape product roadmaps by mandating explainable algorithms, consent audit trails, and incident reporting capabilities. HIPAA and state-level privacy statutes in the United States add compliance layers for healthcare and insurance verticals. Stakeholders must monitor evolving algorithmic accountability standards to determine whether to build native compliance architecture or absorb third-party certification costs.
Market Dynamics
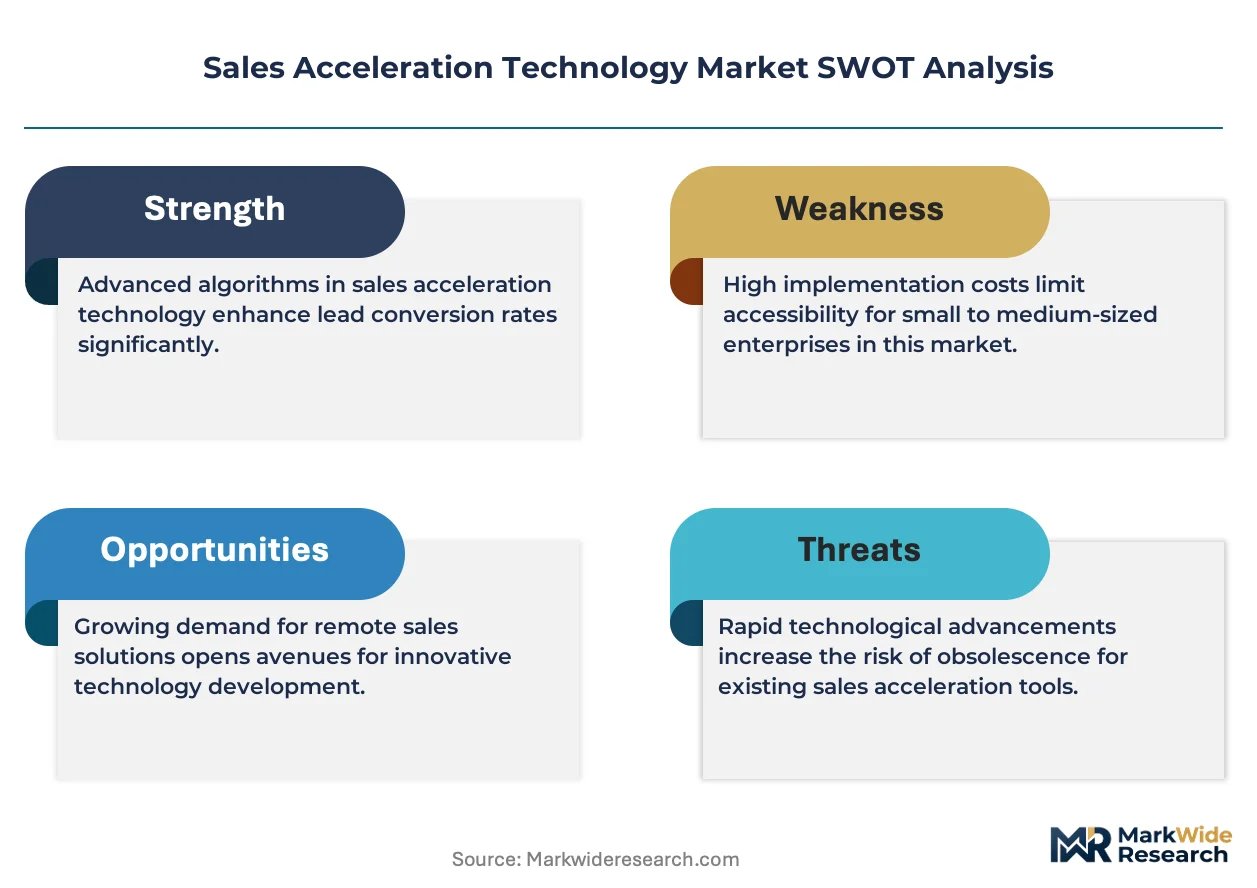
The EU AI Act is forcing enterprise sales teams to abandon black-box algorithms in favor of explainable scoring models, creating procurement friction for vendors lacking audit-ready architectures.
Growth Catalysts
- Algorithmic Transparency Mandates:The EU AI Act creates immediate replacement demand for legacy engagement platforms as enterprises face compliance deadlines for high-risk system documentation.
- Healthcare Vertical Expansion:HIPAA-covered entities in the United States are deploying conversation intelligence to automate compliance documentation while accelerating provider sales cycles.
- API-Native Consolidation:Enterprise IT architecture teams are collapsing point solutions into unified stacks, favoring vendors with native CRM connectivity over isolated workflow tools.
Market Restraints
- Data Residency Requirements:Financial services buyers in Germany and India are mandating hybrid or on-premise deployments, constraining pure SaaS expansion and elevating infrastructure costs.
- Consent Audit Trail Burden:GDPR and emerging US state privacy statutes impose engineering overhead for multi-touch sequencing platforms, slowing feature velocity for mid-market vendors.
- Technical Talent Scarcity:MLOps engineers with dual expertise in sales operations and regulatory compliance command premium compensation, compressing margins for implementation-heavy contracts.
Strategic Opportunities
- Indian Digital Infrastructure Buildout:Domestic SaaS procurement is accelerating as RBI-regulated financial institutions modernize customer acquisition technology stacks.
- Revenue Attribution Convergence:First-party data integration with marketing automation platforms is creating new pricing power for vendors bundling predictive scoring across the funnel.
- SEC Cybersecurity Disclosure Alignment:Incident reporting capabilities are becoming competitive differentiators as public company procurement teams prioritize vendors with pre-built compliance modules.
Industry Challenges
- Legacy CRM Integration Complexity:Custom field mapping and historical data migration for on-premise Salesforce or SAP instances consume 40-60% of implementation timelines.
- Explainability Engineering Gap:Few vendors have built native interpretability layers for deep learning models, forcing expensive retrofitting as the EU AI Act enforcement timeline advances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Acceleration Technology Market |
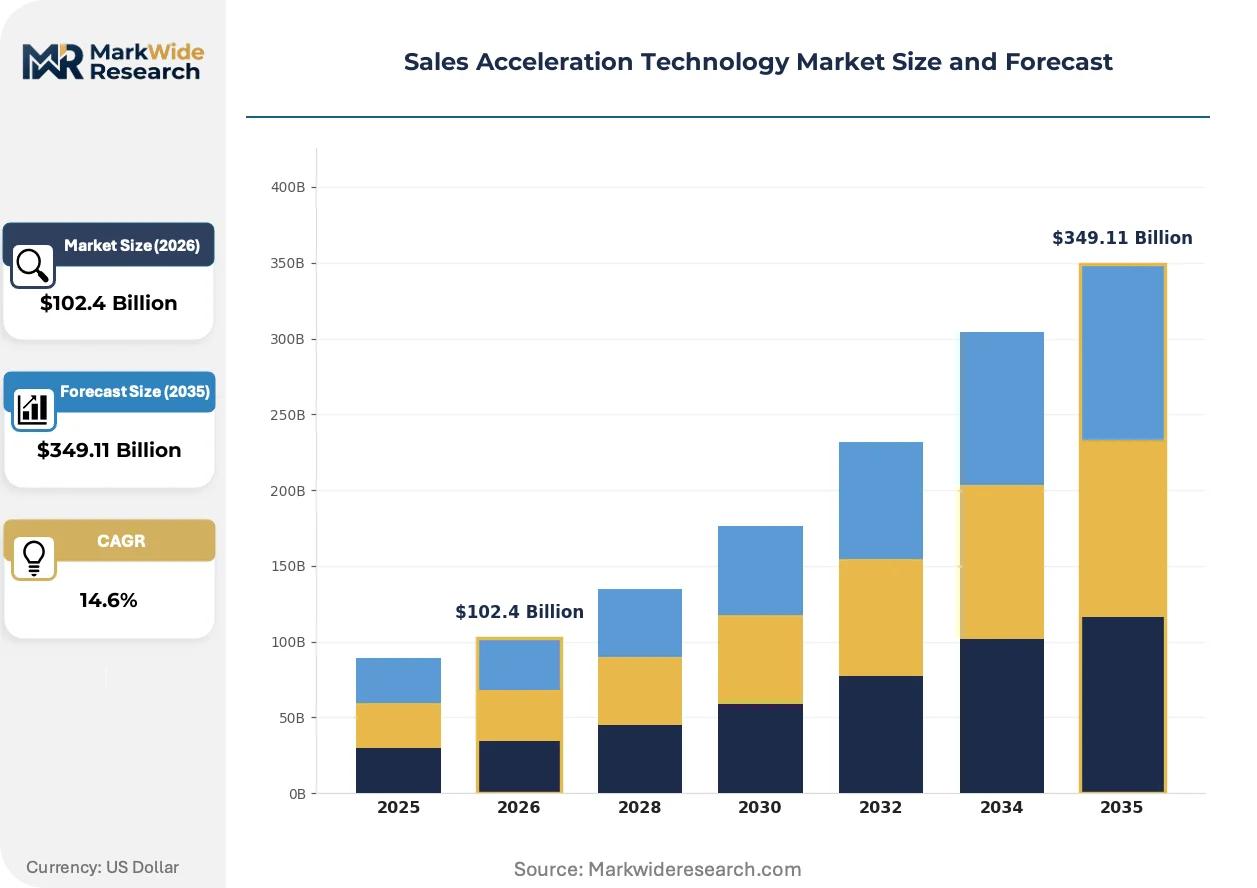
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $349.11 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: CRM, Sales Intelligence, Lead Generation, Workflow Automation Deployment Model: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud End User: SMBs, Enterprises, Startups, Service Providers Sales Channel: Direct Sales, Channel Partners, Online Marketplaces, Resellers |
| Companies Covered | Apollo.io, Salesforce Sales Cloud, HubSpot, Snov.io, ZoomInfo, Outreach, Gong, Freshsales, Salesloft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Acceleration Technology Market Strategic Shifts & Innovations
Real-time behavioral signal processing is collapsing the latency between prospect intent detection and seller response, compressing traditional multi-day nurture sequences into minutes.
Conversation intelligence platforms are unifying voice, email, and chat transcript analysis into single-pane revenue attribution models. Mid-market SaaS buyers in the United States are adopting these stacks fastest, replacing disconnected call recording and email tracking point solutions. The structural consequence is margin compression for standalone vendors lacking native CRM integration, as procurement teams consolidate vendor relationships.
GDPR enforcement actions by CNIL in France and parallel investigations by Germany's data protection authorities are elevating consent management to core platform architecture. Vendors must now engineer granular opt-in workflows and automated deletion capabilities by default. Healthcare and insurance verticals face the steepest compliance burden, driving preference toward vendors with pre-validated HIPAA and GDPR dual certification.
Enterprise buying committees are demanding usage-based pricing with guaranteed ROI thresholds, displacing traditional seat-based subscription models. This pattern concentrates among Fortune 500 technology and financial services buyers with mature procurement functions. Germany and the United States exhibit the fastest adoption of outcome-aligned contracts, with vendors accepting partial payment deferral contingent on pipeline generation metrics.
Sales Acceleration Technology Market Segmentation
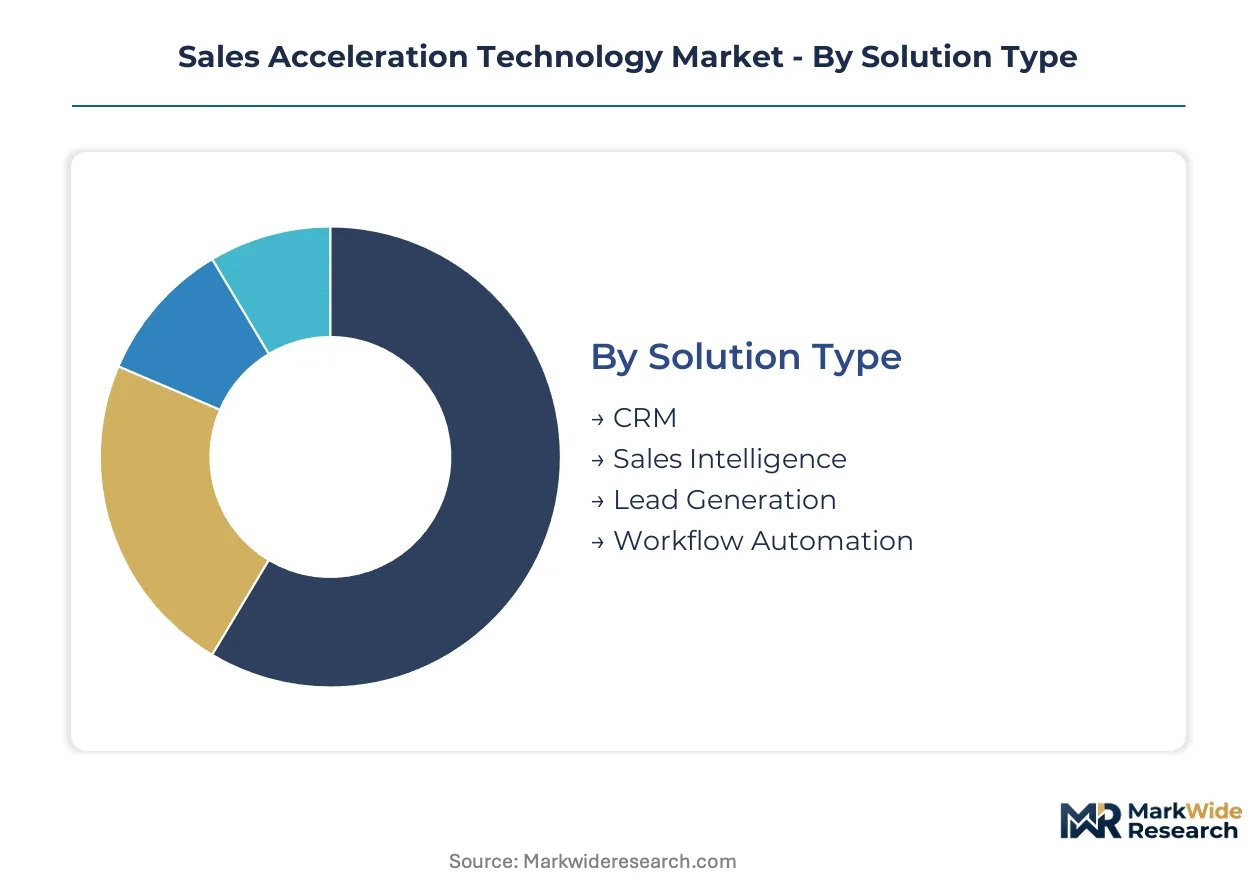
Segmentation in sales acceleration technology reveals how procurement priorities diverge between integrated platform buyers and point-solution adopters. Understanding these splits enables vendors to align product architecture with the dominant purchasing patterns in regulated versus unregulated verticals.
Solution Type:
Standalone solutions dominate mid-market procurement, while embedded modules anchor enterprise renewals through CRM consolidation strategies.
- CRM:Core customer data repositories with native engagement orchestration capabilities anchor enterprise technology stacks. United States financial services buyers prioritize Salesforce-integrated deployments to satisfy SEC cybersecurity disclosure requirements through pre-built audit modules.
- Sales Intelligence:Predictive scoring engines and firmographic enrichment tools deliver revenue attribution capabilities that sustain premium pricing. German automotive manufacturers deploy these systems to compress B2B sales cycles while maintaining GDPR-compliant consent audit trails.
- Lead Generation:Prospecting automation platforms with multi-touch sequencing capabilities.
- Workflow Automation:API-native process orchestration tools collapsing point solutions into unified stacks.
CRM leads volumes today; workflow automation is gaining share fastest.
Deployment Model:
Cost tier stratification separates high-compliance buyers willing to absorb infrastructure overhead from price-sensitive adopters prioritizing speed-to-value.
- Public Cloud:Multi-tenant SaaS architectures with automatic updates and elastic scaling dominate new implementations. Indian fintech startups favor these deployments to accelerate customer acquisition technology modernization without capital expenditure.
- Hybrid Cloud:Split configurations separating sensitive data on-premise while leveraging cloud analytics. German banking regulators mandate these architectures for sales acceleration tools processing customer financial data.
- Private Cloud:Single-tenant dedicated environments with custom security postures.
- On-Premise:Self-hosted installations with full data sovereignty controls.
Public cloud leads volumes today; hybrid cloud is expanding most quickly.
End User:
Customer maturity determines feature complexity tolerance and integration depth requirements across the buyer spectrum.
- Enterprises:Fortune 500 procurement teams demand usage-based pricing with guaranteed ROI thresholds and native CRM connectivity. United States technology buyers increasingly defer partial payment contingent on pipeline generation metrics.
- SMBs:Resource-constrained organizations prioritizing rapid deployment over customization. Indian domestic SaaS procurement concentrates here as RBI-regulated institutions modernize acquisition stacks.
- Startups:Venture-backed companies with high-velocity sales motions and limited IT resources.
- Service Providers:Agencies and consultancies delivering sales acceleration as managed services.
Enterprises lead volumes today; SMBs are climbing the fastest.
Sales Channel:
Channel economics vary sharply by buyer sophistication and implementation complexity requirements.
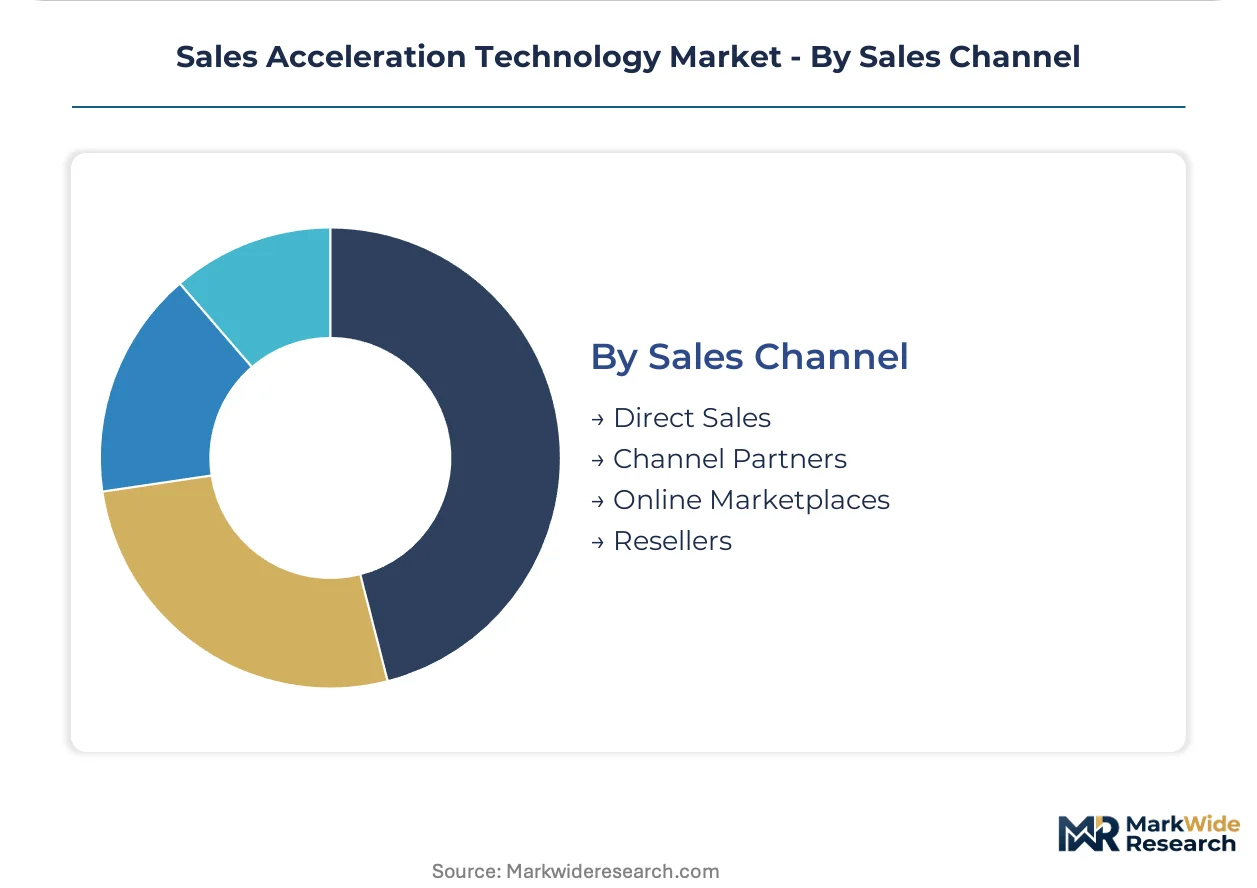
- Direct Sales:Vendor field teams managing complex enterprise procurement with compliance documentation. Healthcare vertical buyers in the United States require direct engagement for HIPAA-validated solution architectures.
- Channel Partners:Systems integrators bundling sales acceleration with broader digital transformation services. German mid-market manufacturers rely on these relationships for on-premise SAP integration expertise.
- Online Marketplaces:Self-service procurement platforms with instant provisioning capabilities.
- Resellers:Value-added distributors extending geographic reach through local relationships.
Direct sales leads volumes today; channel partners are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep pools of MLOps engineers with dual expertise in sales operations and regulatory compliance anchor demand concentration in the United States, Germany, and India. These talent clusters concentrate procurement decisions for AI-powered sales engagement platforms.
United States
Fortune 500 technology and financial services buyers with mature procurement functions drive usage-based pricing adoption with guaranteed ROI thresholds. SEC cybersecurity disclosure rules prioritize vendors with pre-built audit modules and incident reporting capabilities. Healthcare verticals in Boston and San Francisco concentrate HIPAA-validated solution architectures for conversation intelligence deployment.
Germany
Automotive manufacturers and banking regulators mandate hybrid cloud architectures separating sensitive customer financial data on-premise while leveraging cloud analytics. GDPR enforcement actions by CNIL in France and parallel investigations by Germany's data protection authorities elevate consent management to core platform architecture. Industrial clusters in Bavaria and Baden-Württemberg compress B2B sales cycles through predictive scoring engines with audit-ready interpretability layers.
India
RBI-regulated financial institutions modernize customer acquisition technology stacks through domestic SaaS procurement acceleration. PLI scheme incentives support fintech startup adoption of public cloud deployments without capital expenditure. Mumbai and Bengaluru anchor the fastest-climbing SMB segment as venture-backed companies prioritize rapid deployment over customization.
United Kingdom
Enterprise buying committees in London's financial services corridor demand native CRM connectivity and outcome-aligned contracts with partial payment deferral. GDPR compliance requirements shape procurement criteria toward transparent, auditable sales automation tools. The Southeast England technology cluster concentrates mid-market SaaS buyers replacing disconnected call recording and email tracking point solutions.
Japan
METI industrial digitization programs accelerate API-native consolidation strategies among manufacturing exporters. Conservative procurement patterns favor embedded modules over standalone solutions for CRM consolidation. The Tokyo-Osaka corridor anchors enterprise renewals through integrated platform purchases with native engagement orchestration capabilities.
Sales Acceleration Technology Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the sales acceleration technology landscape. The vendor base stratifies between integrated platform incumbents with native CRM connectivity and point-solution specialists facing margin compression from consolidation pressures. Three archetypes dominate: full-stack CRM-engagement suites, conversation intelligence pure-plays, and workflow automation API-native tools. M&A activity concentrates on acquiring explainable AI capabilities for EU AI Act compliance, while strategic partnerships proliferate around first-party data integration with marketing automation platforms.
Within the full-stack tier, Salesforce Sales Cloud and HubSpot occupy positions anchoring large-account deployments through integrated CRM-to-engagement stacks. Gong exemplifies the conversation intelligence archetype sustaining premium pricing through differentiated revenue attribution capabilities. These three companies represent the structural divide between embedded module strategies and standalone platform approaches reshaping competitive dynamics.
| Leading Market Players |
|---|
| Apollo.io |
| Salesforce Sales Cloud |
| HubSpot |
| Snov.io |
| ZoomInfo |
| Outreach |
| Gong |
| Freshsales |
| Salesloft |
| Others |
Cost & Logistics Intelligence
The EU AI Act's explainability mandates gate qualified supply for premium-tier sales acceleration platforms, compressing margins for vendors lacking audit-ready architectures while rewarding certified providers with pricing power in regulated European and North American procurement cycles.
Pricing Analysis
Bundled platform suites command 40-60% premiums over unbundled point solutions as enterprise buyers consolidate vendor relationships. Pricing stratifies across premium, standard, and economy tiers based on compliance certification grade and native CRM integration depth. Cost compression in the mid-market tier is intensifying because GDPR consent audit trail engineering consumes development resources. SMB buyers in India exhibit highest price sensitivity, while Fortune 500 financial services buyers in the United States accept outcome-aligned contracts with deferred payment structures.
Supply Chain Analysis
Single-source vulnerability sits with MLOps engineering talent concentrated in the United States, Germany, and India, where dual expertise in sales operations and regulatory compliance commands premium compensation. Cloud infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, while API middleware components source from Israel and Estonia. Tariff exposure on cross-border data transfers elevates costs for hybrid deployment configurations. Distribution runs through direct enterprise field teams and systems integrator channel partners with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Europe create 25-35% cost disadvantages versus Indian SaaS vendors serving RBI-regulated financial institutions with lighter regulatory burdens.
For Market Incumbents: Lock in explainable AI architecture investments before enforcement deadlines harden procurement criteria. Consolidate point-solution competitors to absorb consent audit trail capabilities and defend margin position against API-native challengers. Prioritize hybrid cloud infrastructure partnerships in Germany to satisfy data residency mandates without sacrificing analytics performance. For New Entrants and Emerging Players: Systems integrators with SAP and Salesforce implementation expertise represent the fastest channel to enterprise procurement committees. White-space concentrates in HIPAA-validated conversation intelligence for United States healthcare verticals and GDPR-compliant lead generation for German automotive suppliers. Position around pre-built compliance modules rather than retrofitting legacy architectures. For Investors and Strategic Acquirers: Roll-up economics work for conversation intelligence pure-plays because revenue attribution capabilities sustain premium pricing through differentiated pipeline analytics. Long-term viability hinges on first-party data integration with marketing automation platforms. Watch for EU AI Act enforcement actions as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | EU AI Act compliance deadlines force retrofitting or replacement of black-box scoring models in enterprise deployments. |
| Hybrid Cloud Infrastructure Partnership | German banking regulators mandate on-premise data separation for customer financial information processing. |
| HIPAA-Validated Solution Certification | Healthcare vertical buyers in Boston and San Francisco require documented compliance for conversation intelligence procurement. |
| First-Party Data Integration | Marketing automation platform connectivity creates pricing power for predictive scoring across the full funnel. |
| Systems Integrator Channel Alliance | German mid-market manufacturers rely on SAP integration expertise for on-premise deployment timelines. |
Research Approach
Multiple input streams — primary interviews with CTOs, IT procurement officers, and sales operations leaders; secondary validation through SEC cybersecurity disclosures, hyperscaler capex reports, and EU regulatory filings; plus channel partner operational data — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical spending patterns were cross-referenced against panel input from platform vendors and enterprise buyers to anchor projections across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory exposure, and integration complexity. CAGRs were derived from elasticity-adjusted adoption curves and compliance-driven replacement cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement timing, MLOps talent availability, and data localization policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
In-App Purchase Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Australia System Integration Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Poland ICT Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Japan Digital Twin Market