
 DevOps Market | 2026-2036
DevOps Market Size, Share, and Industry Trends Forecast 2026-2036
DevOps Market Intelligence
The transition toward platform-based managed services from project-based consulting is reshaping the landscape for service providers. This shift emphasizes subscription models and continuous improvement over discrete project delivery. IBM Consulting leverages its extensive hybrid cloud portfolio to deliver integrated DevOps platforms. Accenture competes on the scale of its global delivery network and industry-specific accelerators. ThoughtWorks differentiates through its focus on agile software development principles and engineering culture transformation for enterprise clients.
DevOps represents a set of practices that combines software development and IT operations to shorten the systems development life cycle and provide for continuous delivery. The methodology aims to automate software builds, testing, and deployment through integrated toolchains. Its primary commercial purpose is to enable organizations to deliver applications and services at high velocity. Within the solution segment, Continuous Integration and Continuous Delivery (CI/CD) pipelines form the foundational components of most implementations. The market's deployment model shows a clear preference for Cloud-based and Hybrid Cloud environments over legacy on-premises setups.
Data governance regulations like Europe's GDPR and the US HIPAA framework influence toolchain selection and data management practices within DevOps workflows. In China, directives from the MIIT regarding data security and software standards add another layer of compliance for development teams operating in that market. Stakeholders must decide whether to build in-house platform engineering capabilities or rely on specialized external IT service providers for implementation and management.
Market Dynamics
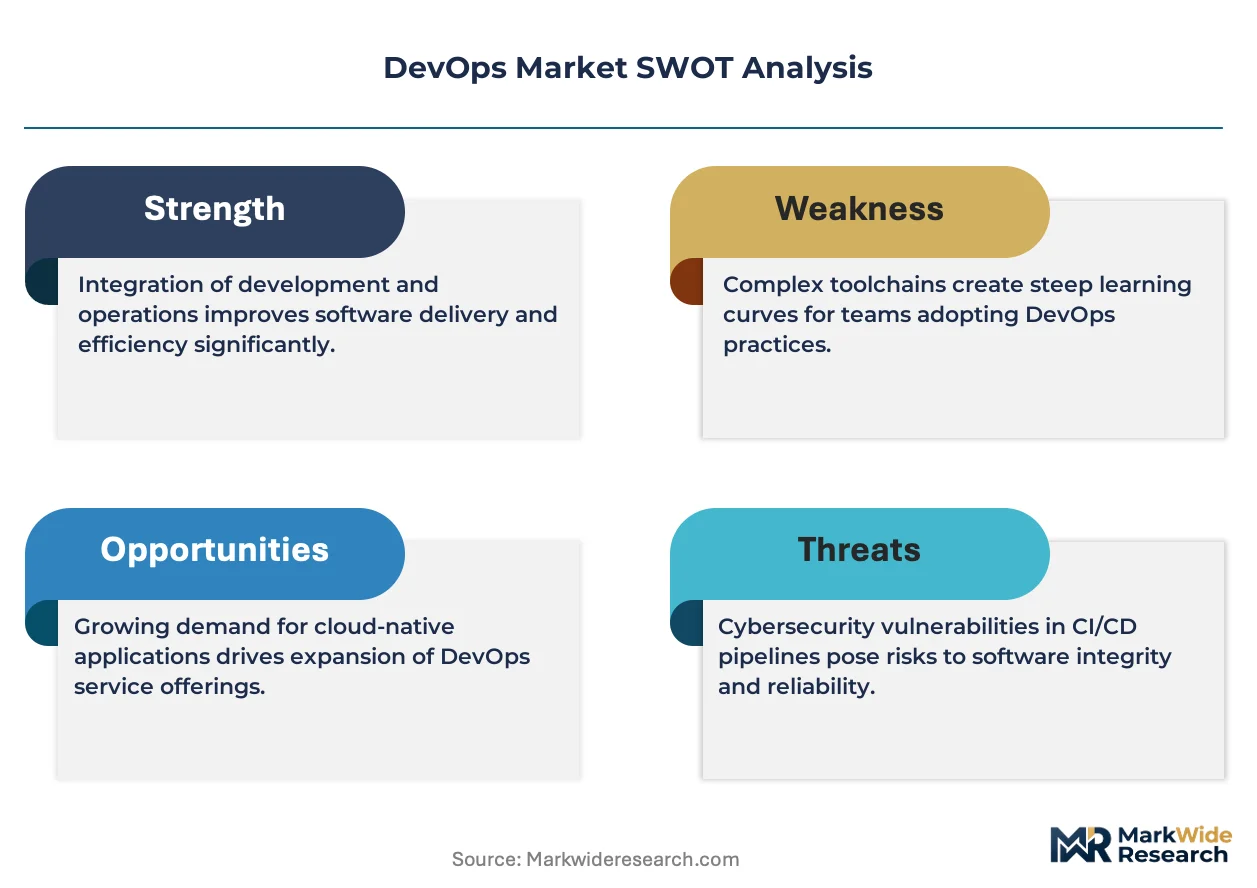
The central force shaping the DevOps market is the institutionalization of regulatory compliance within the software development lifecycle. Mandates like the EU AI Act and HIPAA are elevating automated governance and auditable pipelines from best practices to legal requirements for market access.
Growth Catalysts
- CI/CD Pipelines:The adoption of Continuous Integration and Continuous Delivery pipelines forms the technical foundation for market growth, enabling the automation of software builds, testing, and deployment that is central to the DevOps value proposition.
- Banking & Finance Sector Demand:Financial institutions require secure and high-velocity application delivery to compete. This sector's stringent security and compliance needs drive investment in sophisticated, auditable DevOps toolchains and platforms.
- EU AI Act:New European legislation mandates transparency and documentation for AI systems. This directly favors DevOps practices that provide automated logging, version control, and reproducible software builds throughout the development lifecycle.
Market Restraints
- Toolchain Integration Costs:Integrating a heterogeneous mix of open-source and commercial tools into a seamless pipeline creates significant technical complexity and cost, acting as a barrier for organizations without specialized engineering talent.
- Legacy System Inertia:The difficulty of applying modern DevOps practices to deeply embedded monolithic mainframe systems, particularly in insurance and government sectors, slows down enterprise-wide adoption and limits the achievable benefits.
- Platform Engineering Talent Scarcity:A shortage of engineers with combined expertise in hybrid cloud management, container orchestration, and security automation creates a bottleneck, concentrating advanced capabilities within a few technology hubs and large enterprises.
Strategic Opportunities
- MLOps and AIOps Integration:Extending DevOps principles to machine learning workflows (MLOps) and using AI for IT operations (AIOps) presents a significant growth vector, creating demand for platforms that can automate model deployment and operational monitoring.
- Compliance-as-Code Solutions:Data governance frameworks like GDPR in Europe and HIPAA in the US create an opportunity for specialized tools that codify compliance rules and automate evidence collection directly within the CI/CD pipeline.
- Public Sector Modernization:Government digital transformation initiatives in countries like India and Brazil offer a substantial opportunity for deploying DevOps platforms to improve the speed and reliability of public service delivery.
Industry Challenges
- Cross-Functional Skill Gaps:A persistent shortage of professionals who possess a hybrid skill set spanning software development, infrastructure operations, and cybersecurity protocols remains a primary operational challenge for adopting organizations.
- Cultural Resistance to Change:Overcoming entrenched organizational silos and fostering a collaborative culture between development, operations, and security teams is often more difficult than implementing the technology itself.
- Security Vulnerability Management:Securing a complex, fast-moving software supply chain against vulnerabilities in open-source components and third-party dependencies presents a continuous and resource-intensive operational burden for development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DevOps Market |
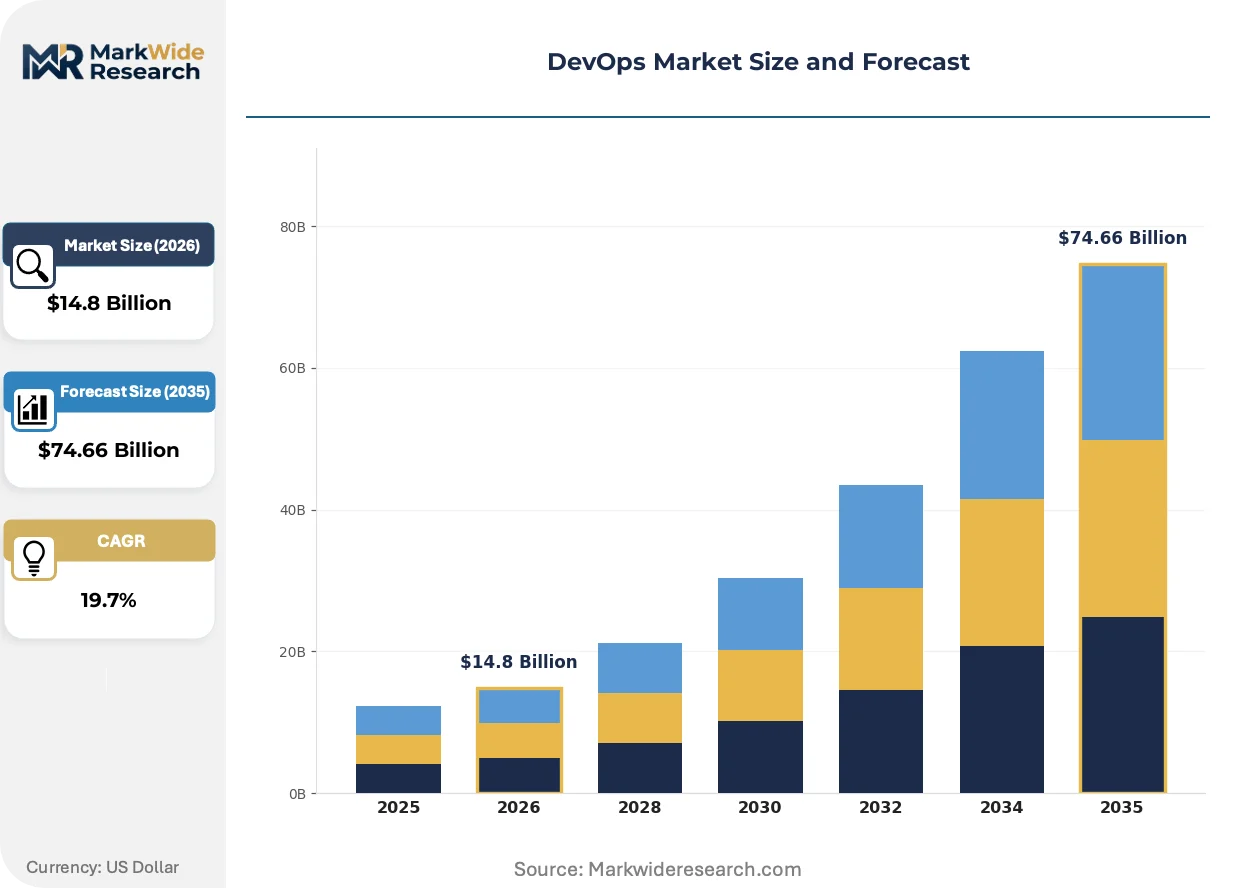
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $74.66 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid Cloud, Multi-cloud, Edge Computing Solution: Continuous Integration, Continuous Delivery, Infrastructure as Code, Automated Testing, Monitoring & Logging Application: Banking & Finance, Telecommunications, Media & Entertainment, Manufacturing, Government End User: IT Service Providers, Software Vendors, E-commerce Companies, Educational Institutions, Consulting Firms |
| Companies Covered | Cognizant, CloudBees, Accenture, Capgemini, TCS, IBM Consulting, ThoughtWorks, Xebia, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DevOps Market Strategic Shifts & Innovations
Integrated platform engineering is supplanting the traditional model of assembling toolchains from discrete components. This shift favors vendors that can provide a unified, managed environment for coding, building, deploying, and operating software, reducing complexity for enterprise adopters.
Infrastructure as Code (IaC) provides the capability to manage and provision computing infrastructure through machine-readable definition files. Enterprise IT departments and cloud-native organizations are standardizing on IaC to achieve consistency across development, testing, and production environments. This technology is virtualizing the entire server and network configuration process, compressing deployment cycles and eliminating manual setup errors.
China's MIIT directives on software supply chain security impose new requirements on development teams operating within that market. These regulations mandate greater visibility into and control over the use of open-source and third-party software components. The software composition analysis (SCA) and binary repository segments are directly impacted, as tools must now provide verifiable evidence of code provenance and security scanning.
A notable behavioral shift is the enterprise pivot from project-based consulting engagements to subscription-based managed DevOps platforms. This model replaces one-time systems integration work with a continuous service relationship focused on platform health, evolution, and achieving specific business outcomes. The trend is most pronounced in the financial services and telecommunications sectors, where long-term operational stability and predictable costs are critical.
DevOps Market Segmentation
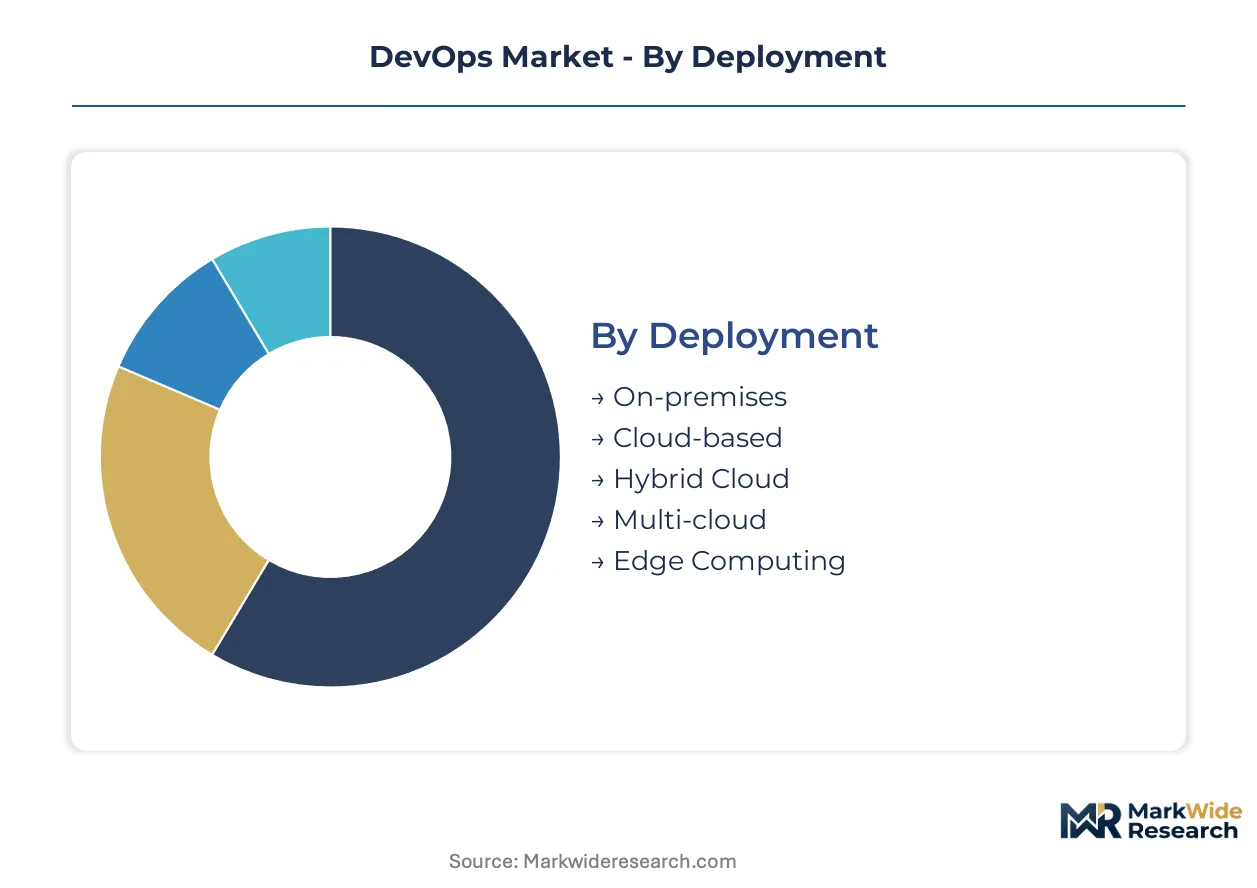
The DevOps market is segmented to reveal the diverse requirements and adoption patterns across various operational environments, technical solutions, application domains, and end-user types. Understanding these distinctions is crucial for providers to tailor offerings that meet specific client needs and regulatory demands.
Deployment:
The speed of infrastructure provisioning and deployment cycle times varies significantly across different DevOps deployment models.
- On-premises:This model involves hosting DevOps tools and infrastructure within an organization's own data centers, offering maximum control but often slower provisioning cycles due to physical hardware dependencies.
- Cloud-based:Utilizing public cloud providers for DevOps tools and infrastructure enables rapid scaling and reduces operational overhead, supporting high-velocity application delivery for modern enterprises. Cloud-based deployments are favored by organizations seeking agility and reduced capital expenditure.
- Hybrid Cloud:This approach combines on-premises infrastructure with public or private cloud services, allowing organizations to leverage existing investments while gaining cloud flexibility. Financial institutions and government agencies often adopt hybrid cloud for sensitive data management.
- Multi-cloud:Employing multiple cloud providers for different services or redundancy, multi-cloud strategies enhance resilience and avoid vendor lock-in. Companies with diverse application portfolios often use this model for optimized resource allocation.
- Edge Computing:Extending DevOps practices to devices and localized data centers closer to the data source, edge computing supports low-latency applications. Industrial IoT and telecommunications sectors increasingly implement edge computing for real-time processing.
Cloud-based deployments anchor the volume base while Hybrid Cloud gains share at the steepest rate.
Solution:
The complexity of software applications dictates the specific DevOps solutions required to achieve efficient and reliable delivery.
- Continuous Integration:This foundational practice involves frequently merging code changes into a central repository, followed by automated builds and tests. It is essential for maintaining code quality and detecting integration issues early in the development lifecycle.
- Continuous Delivery:Building upon CI, CD automates the entire software release process, ensuring that code changes are always ready for deployment to production environments. This enables organizations to deliver new features and bug fixes with speed and consistency, particularly within the Banking & Finance sector.
- Infrastructure as Code:Managing and provisioning computing infrastructure through machine-readable definition files standardizes environments and eliminates manual configuration errors. Enterprise IT departments standardize on IaC for consistency across development, testing, and production.
- Automated Testing:Integrating various testing types, including unit, integration, and performance tests, into the CI/CD pipeline ensures software quality without manual intervention. This solution reduces human error and accelerates feedback loops for development teams.
- Monitoring & Logging:Tools that collect, aggregate, and analyze application and infrastructure performance data provide real-time insights into system health and user experience. These solutions are critical for proactive issue detection and root cause analysis in complex distributed systems.
Continuous Integration and Continuous Delivery solutions represent the most mature offerings, driving foundational automation across development lifecycles.
Application:
Regulatory frameworks and industry-specific compliance requirements heavily influence DevOps adoption and implementation strategies across various application sectors.
- Banking & Finance:This sector demands highly secure, compliant, and rapidly deployed applications to support digital banking and trading platforms. DevOps practices address stringent regulatory requirements like GDPR and HIPAA, ensuring auditable and secure software delivery.
- Telecommunications:DevOps enables telcos to quickly deploy new network services, manage complex infrastructure, and support evolving 5G and IoT technologies. This sector requires high availability and scalable solutions for continuous service innovation.
- Media & Entertainment:Companies in this sector leverage DevOps for agile content delivery, streaming platform management, and personalized user experiences. Rapid deployment of new features and updates is critical for competitive advantage.
- Manufacturing:DevOps supports the digital transformation of manufacturing processes, including smart factory initiatives and industrial IoT applications. It facilitates faster software updates for operational technology and supply chain optimization.
- Government:Public sector modernization initiatives, such as those in India and Brazil, utilize DevOps to improve the speed and reliability of public service delivery. Compliance with national data security directives, like China's MIIT, is a significant driver.
Banking & Finance applications demand high-velocity delivery with stringent security, while Government initiatives focus on modernizing public service platforms.
End User:
The strategic intent behind DevOps adoption varies significantly among different end-user segments, from internal capability building to external service delivery.
- IT Service Providers:These firms offer DevOps consulting, implementation, and managed services to clients, often leveraging their expertise in cloud platforms and automation tools. Demand is concentrating in technology hubs like Bangalore and Austin.
- Software Vendors:Companies that develop and sell software products use DevOps to accelerate their own product release cycles, enhance software quality, and deliver continuous updates to customers. Their focus is on internal efficiency and product innovation.
- E-commerce Companies:These businesses rely on DevOps to maintain highly available, scalable, and rapidly evolving online platforms. Continuous deployment of new features and marketing campaigns is crucial for customer engagement and sales.
- Educational Institutions:Universities and research facilities adopt DevOps for managing complex IT environments, developing custom applications, and supporting academic research projects. They prioritize cost-effective and collaborative development tools.
- Consulting Firms:Specialized consulting firms guide enterprises through DevOps transformations, focusing on cultural change, process optimization, and toolchain selection. They differentiate through agile principles and engineering culture transformation.
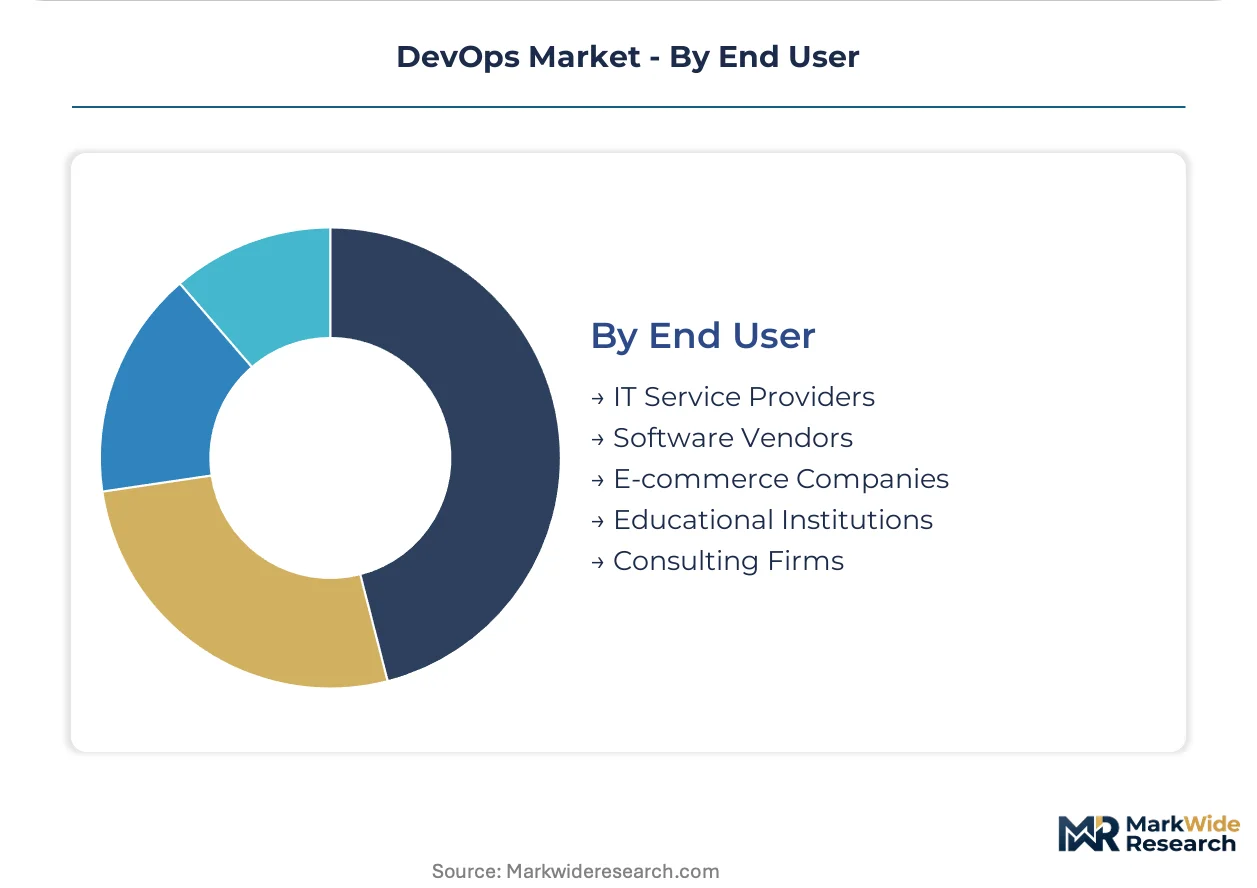
IT Service Providers and Consulting Firms are central to talent concentration, driving implementation and managed services for diverse clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major internet exchange points and extensive cloud infrastructure underwrite the United States' pivotal role in DevOps market evolution. This advanced digital backbone supports widespread adoption across diverse industries. Organizations prioritize efficient software delivery and robust security protocols.
United States
Financial institutions and major technology firms drive significant demand for sophisticated DevOps solutions. HIPAA regulations and other data privacy frameworks necessitate auditable and secure development pipelines. Silicon Valley and Austin serve as major innovation hubs, concentrating talent and investment in advanced platform engineering capabilities.
India
IT service providers and government digital transformation initiatives fuel substantial DevOps adoption across India. The country's national cybersecurity policies and digital India programs encourage secure and rapid application deployment. Bangalore and Hyderabad are critical centers for IT talent, attracting investments in managed DevOps services.
Germany
Manufacturing and automotive sectors in Germany require highly reliable and automated software delivery processes. GDPR compliance and national data protection laws mandate stringent controls over development and deployment. Munich and Berlin are emerging as key innovation clusters for industrial IoT and cloud-native DevOps platforms.
China
The Chinese market exhibits strong demand for DevOps solutions driven by rapid digital transformation and domestic cloud growth. Directives from the MIIT regarding data security and software standards shape toolchain selection and compliance. Beijing and Shanghai are central to the development of localized DevOps platforms and talent pools.
United Kingdom
Financial services and public sector modernization efforts propel DevOps market expansion within the United Kingdom. GDPR and other national regulatory frameworks emphasize transparent and auditable software development. London remains a global financial technology hub, fostering innovation in secure and high-velocity application delivery.
DevOps Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing niche tools for specific pipeline stages. The market structure is tiered, with large consulting firms and managed service providers at the top, supported by specialized software vendors. Archetypes include global IT service giants, focused platform engineering firms, and open-source tool maintainers. Strategic partnerships and portfolio diversification are dominant competitive moves.
Global IT service giants like Accenture and IBM Consulting exemplify the comprehensive platform integration archetype, leveraging extensive hybrid cloud portfolios and global delivery networks to deliver integrated DevOps platforms for enterprise clients. ThoughtWorks occupies a position as a specialized consulting firm, differentiating through its focus on agile software development principles and engineering culture transformation for enterprise clients, often targeting complex enterprise modernization projects. These firms collectively anchor the high-value managed services segment, providing end-to-end solutions and addressing complex client needs across various sectors, from finance to telecommunications.
| Leading Market Players |
|---|
| Cognizant |
| CloudBees |
| Accenture |
| Capgemini |
| TCS |
| IBM Consulting |
| ThoughtWorks |
| Xebia |
| Deloitte |
| Others |
Cost & Logistics Intelligence
Underutilized cloud infrastructure capacity across major hyperscalers drives competitive pricing for DevOps platform services. This utilization pressure influences vendor strategies and service bundling.
Pricing Analysis
Volume-based subscription tiers dominate DevOps platform pricing, reflecting service consumption and feature sets. Price differentiation stems from customization levels for enterprise clients and the depth of after-sales managed services. Pricing softness runs through the entry-level segment due to robust open-source toolchain alternatives. E-commerce companies exhibit high price sensitivity, while Banking & Finance prioritizes security and compliance over cost.
Supply Chain Analysis
Export control regimes, particularly those impacting advanced semiconductor technology, indirectly influence the supply of underlying cloud infrastructure for DevOps platforms. The talent supply concentrates in technology hubs like the United States, India, and China. Critical dependencies include cloud infrastructure providers and the availability of specialized engineering talent for platform development. A structural risk is the scarcity of platform engineering talent, creating bottlenecks. Distribution runs through direct enterprise sales and extensive networks of IT service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DevOps market requires a strategic substitution defense against the rise of low-code/no-code platforms that promise rapid application delivery without extensive engineering. Incumbents must navigate this threat by emphasizing advanced governance and integration capabilities.
For Market Incumbents: Build defensible platform moats through deep integration of compliance-as-code solutions directly into managed DevOps offerings. Consolidate market position by acquiring specialized MLOps and AIOps firms to extend automation capabilities across new workflows. This counters cultural resistance to change and mitigates the platform engineering talent scarcity by embedding intelligence. R&D investments in AI-driven automation provide a critical lever against emerging low-code alternatives.
For New Entrants and Emerging Players: Build out niche compliance-as-code solutions tailored for specific regulatory frameworks like the EU AI Act, targeting underpenetrated mid-market enterprises. Focus on specialized MLOps platforms designed for industries with high AI adoption, such as financial services. The most penetrable segment consists of organizations struggling with evolving governance requirements. Partnering with regional IT service providers offers an effective go-to-market angle for localized support.
For Investors and Strategic Acquirers: Capital is best deployed toward managed service providers demonstrating strong platform engineering capabilities and intellectual property in compliance-as-code solutions. Long-term value resides in firms offering integrated security and auditable DevOps pipelines across complex hybrid cloud environments. Acquisition targets include specialists in MLOps integration or those with deep expertise in specific regulatory compliance. Increased regulatory enforcement actions for software supply chain security serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies disparate toolchains, reducing complexity for enterprise adopters. |
| AI-Driven Automation | Accelerates software delivery and enhances operational efficiency within CI/CD pipelines. |
| Compliance-as-Code Development | Automates adherence to stringent regulations like the EU AI Act and HIPAA. |
| MLOps Specialization | Extends DevOps principles to machine learning workflows, supporting AI system deployment. |
| Hybrid Cloud Portfolio Expansion | Caters to diverse enterprise deployment needs, leveraging existing IT investments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, industry reports from major IT service providers, and government digital transformation initiatives. Primary interviews engaged CTOs, IT procurement officers, platform engineers, and regulatory compliance leads across various sectors. This approach ensured robust data validation through both bottom-up market sizing and top-down market share analysis.
Forecast inputs considered include the evolving regulatory landscape, particularly EU AI Act implementation timelines, and projected hybrid cloud adoption rates across industries. The analytical framework models market dynamics across the analysis window, segmenting by deployment model, solution type, application domain, and end-user type. Compound Annual Growth Rates (CAGRs) are derived from historical growth trends, technological adoption curves, and anticipated investment patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers or open-source consortia would shift outcomes. These projections reflect current assumptions regarding geopolitical stability and technological development. Material shifts in global data governance regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Association Management Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Absence Management Software Market
Software & Services
Network Documentation Software Market
Software & Services
Virtual Studio Software Market
Software & Services
3D Animation Software Market
Software & Services
Strategy Management Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Content Marketing Software Market
Software & Services
Enterprise Application Market
Software & Services
Lab Automation Software Market