
 Parking Management Systems Market | 2026-2036
Parking Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Management Systems Market Outlook
ISO 9001 quality management certification is reorganizing vendor eligibility for municipal procurement contracts. SKIDATA leverages its European installed base to sustain long-term service agreements with airport authorities. JustPark competes on consumer-facing mobile payment density across United Kingdom urban centers.
Parking management systems coordinate vehicle entry, occupancy detection, payment processing, and enforcement through sensor networks, barrier controls, and centralized software platforms operating with sub-second transaction latency. Cloud-based solutions are capturing margin pools from legacy standalone deployments as municipalities prioritize real-time data analytics and remote management capabilities. IoT Devices represent the fastest-growing technology segment, displacing wired infrastructure in retrofit installations across aging commercial complexes.
FCC equipment authorization governs wireless sensor communications in the United States, while GDPR shapes data retention policies for European cloud-based payment platforms. Municipal procurement standards increasingly mandate open API architectures to prevent vendor lock-in. Stakeholders must monitor evolving cybersecurity disclosure requirements as connected parking infrastructure becomes a target for ransomware operators.
Market Dynamics
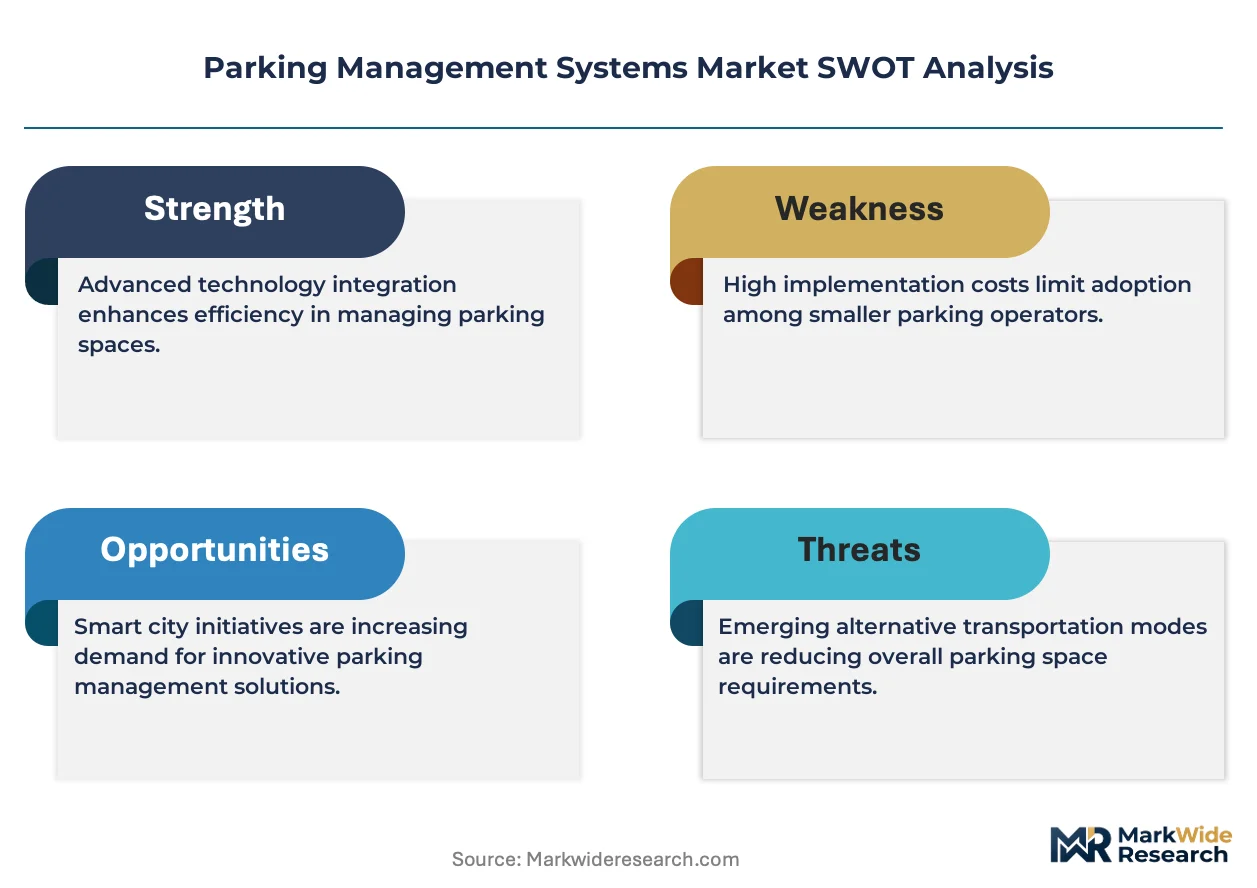
Cloud migration is compressing hardware margins while expanding recurring software revenue pools across municipal and commercial parking operators. FCC equipment authorization requirements for wireless sensor networks add compliance layers that favor established vendors with regulatory expertise over new entrants.
Growth Catalysts
- Smart City Infrastructure Mandates:Municipal procurement standards in the United States increasingly require open API architectures and real-time data analytics capabilities, accelerating replacement of legacy standalone systems.
- GDPR-Compliant Payment Platforms:European cloud-based payment integration creates vendor preference for solutions with certified data retention frameworks, driving platform consolidation across United Kingdom urban centers.
- Airport Modernization Programs:Federal Aviation Administration facility upgrade timelines in the United States are synchronizing with parking system lifecycle replacements, creating concentrated demand windows for integrated entry-control and revenue management suites.
Market Restraints
- Copper and Semiconductor Input Volatility:IoT sensor manufacturing depends on stable pricing for microcontrollers and RF components, with supply concentration in East Asian foundries creating procurement risk for Western system integrators.
- Cybersecurity Disclosure Requirements:Emerging SEC rules for critical infrastructure operators impose incident reporting burdens that inflate compliance costs for cloud-connected parking platforms serving municipal clients.
- Legacy Wired Infrastructure Lock-In:Aging commercial complexes with installed conduit systems face asymmetric replacement economics that slow wireless retrofit adoption despite superior total cost of ownership profiles.
Strategic Opportunities
- Underpenetrated Indian Metropolitan Markets:Smart Cities Mission funding in India creates procurement windows for integrated parking management where legacy manual enforcement still dominates revenue collection.
- Vehicle-to-Infrastructure Convergence:Integration of parking reservation APIs with connected vehicle platforms and municipal traffic management systems enables dynamic pricing and congestion-responsive availability.
- Outcome-Based Municipal Contracts:Revenue-sharing arrangements replacing capital purchase models align vendor incentives with enforcement yield optimization, penetrating budget-constrained city governments.
Industry Challenges
- RF Engineering Talent Scarcity:FCC Part 15 certification expertise for wireless sensor networks concentrates among specialized consultants, extending product development timelines for hardware vendors without in-house electromagnetic compliance capabilities.
- ISO 9001 Certification Timeline Compression:Municipal procurement eligibility increasingly requires quality management certification, forcing mid-tier vendors to absorb audit costs and documentation burdens before contract participation.
- Legacy Payment System Integration:Decades-old parking meter networks and proprietary cash-handling infrastructure resist API-based modernization, requiring custom middleware development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Management Systems Market |
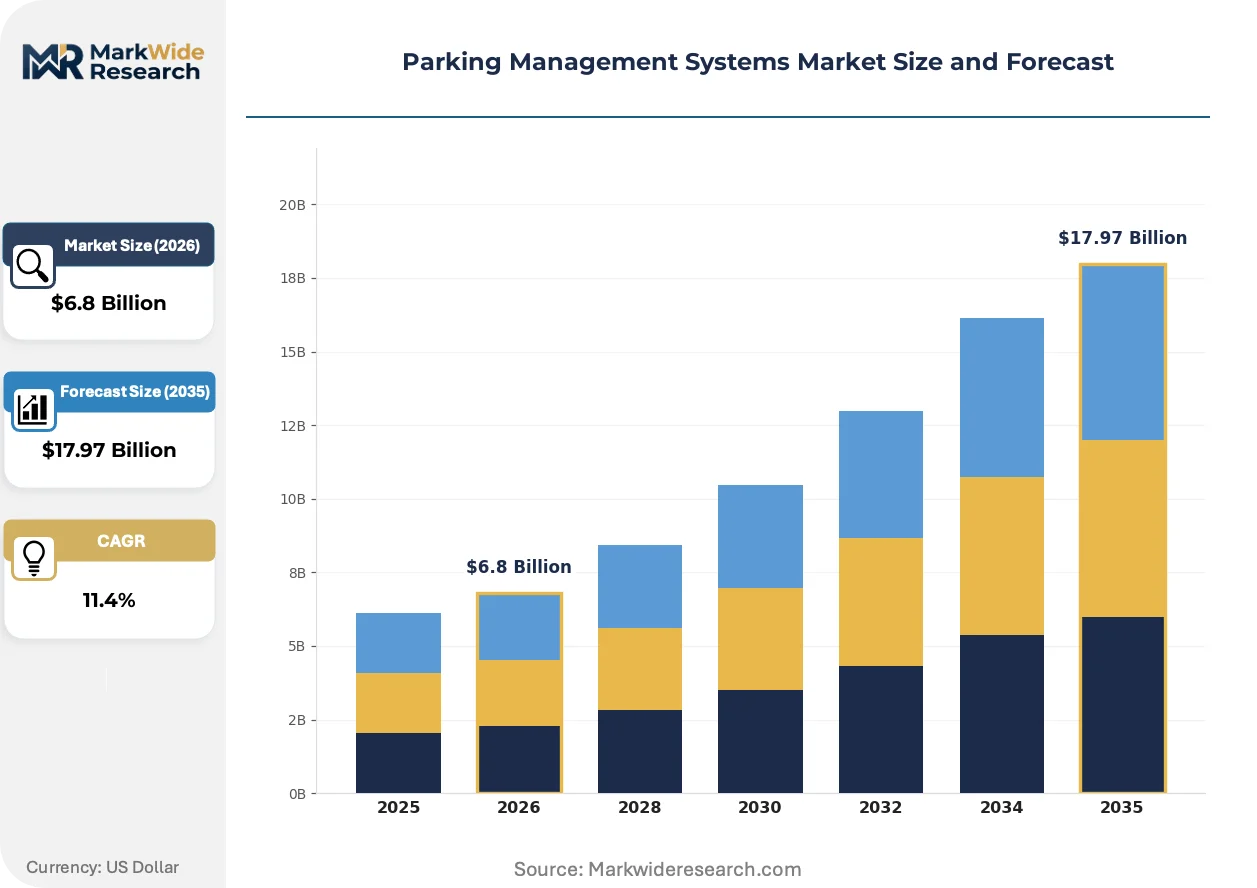
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-street Parking, Off-street Parking, Valet Parking, Residential Parking Technology: Mobile Payment, RFID, Cloud-based Solutions, IoT Devices End User: Municipalities, Commercial Complexes, Airports, Educational Institutions Deployment: Web-based, Mobile Applications, Standalone Systems, Integrated Systems |
| Companies Covered | JustPark, AirGarage, SKIDATA, Parkanizer, Wayleadr, Parkable, Get My Parking, Nayax, SpotHero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Management Systems Market Strategic Shifts
Edge computing architectures are redistributing processing loads from centralized cloud platforms to distributed sensor gateways. This shift reduces transaction latency for occupancy detection and payment authorization while creating new hardware categories at the network periphery.
Ultrasonic and magnetic sensing technology is miniaturizing into surface-mount packages that install without pavement cutting or lane closure permits. Airport authorities and retail parking operators are adopting these retrofit-friendly sensors at accelerated replacement cycles. The form factor reduction is compressing installation labor costs and enabling battery-powered deployments where conduit access is prohibitively expensive.
FCC equipment authorization for unlicensed spectrum operation in the 902-928 MHz band is tightening emission mask requirements for wireless parking sensors. Manufacturers must redesign RF front ends and resubmit for certification, favoring vendors with dedicated regulatory affairs functions. United States municipal procurements increasingly specify certified hardware exclusively, filtering out uncertified imports.
Subscription pricing for software platforms is displacing perpetual license sales across municipal and commercial parking operations. Procurement officers prefer operational expenditure treatment that aligns costs with revenue collection, while vendors capture predictable recurring revenue. This model shift is most visible in United States metropolitan areas where municipal budget volatility discourages large capital appropriations for parking infrastructure.
Parking Management Systems Market Segmentation
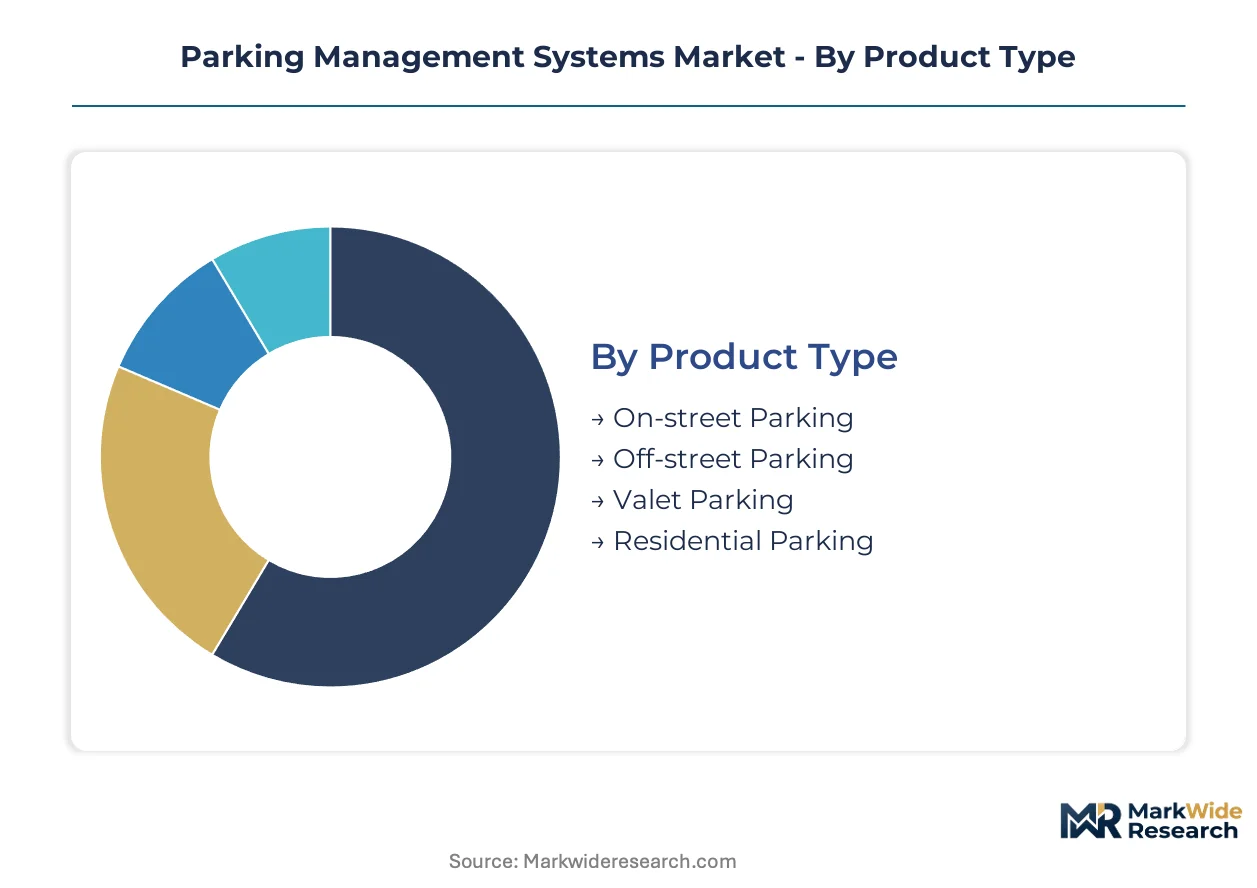
Parking management systems fragment across four structural dimensions that determine procurement channels, margin profiles, and vendor positioning. Product type governs hardware-software mix and installation complexity. Technology selection drives recurring revenue potential and regulatory compliance burden.
Product Type:
On-street systems flow through municipal procurement channels with extended sales cycles and ISO certification requirements. Off-street deployments reach commercial operators through system integrators and direct vendor relationships.
- On-street Parking:Curb-side meter networks and enforcement platforms integrate with municipal traffic management systems. Demand concentrates in United States metropolitan areas implementing congestion pricing pilots, with FCC Part 15 certification mandatory for wireless sensor deployment.
- Off-street Parking:Garage and lot management systems combine barrier controls, payment kiosks, and occupancy displays. Airport authorities in the United States drive specification upgrades through FAA-synchronized facility modernization programs.
- Valet Parking:Ticketless vehicle retrieval and inventory management platforms serve premium hospitality and healthcare facilities.
- Residential Parking:Access control and visitor management systems target multi-tenant housing complexes with subscription-based service models.
Off-street Parking dominates installed base. On-street Parking is where expansion concentrates.
Technology:
Technology cost tiers separate premium integrated platforms from point solutions, with cloud migration compressing hardware margins while expanding software recurring revenue.
- Mobile Payment:Smartphone-native transaction processing eliminates kiosk hardware and reduces cash-handling infrastructure. United Kingdom urban centers show dense consumer adoption, with GDPR-compliant data retention frameworks creating vendor preference concentration.
- IoT Devices:Battery-powered wireless sensors with surface-mount installation reduce pavement cutting and lane closure permits. Retrofit-friendly form factors are climbing the fastest in aging commercial complexes where conduit access is prohibitively expensive.
- Cloud-based Solutions:Centralized software platforms enable remote management and real-time analytics for distributed parking assets.
- RFID:Long-range identification for hands-free entry control persists in airport and corporate campus deployments.
Cloud-based Solutions dominate installed base. IoT Devices represent the steepest expansion trajectory.
End User:
End user application patterns separate high-volume transaction environments from specialized access control scenarios, with procurement authority residing in facilities management, IT, or transportation departments.
- Municipalities:City government parking operations require open API architectures and real-time data analytics capabilities. United States procurement standards increasingly mandate these specifications, accelerating legacy system replacement.
- Airports:Federal Aviation Administration facility upgrade timelines synchronize with parking system lifecycle replacements. Integrated entry-control and revenue management suites capture concentrated demand windows.
- Commercial Complexes:Retail and office parking operators prioritize total cost of ownership and rapid deployment timelines.
- Educational Institutions:Campus parking management combines student permit systems with event-based dynamic pricing.
Municipalities dominate installed base. Airports represent the most concentrated near-term demand window.
Deployment:
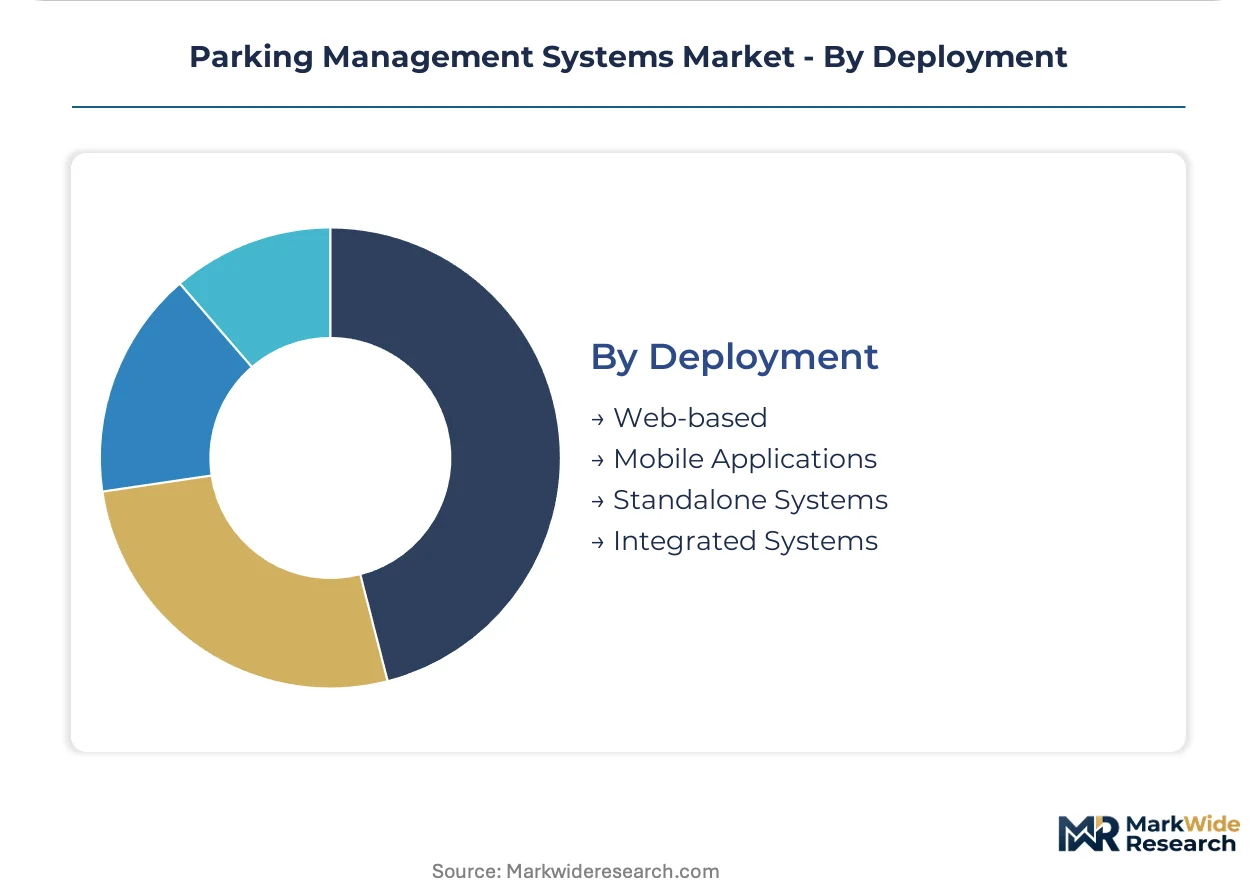
Deployment maturity stages separate legacy standalone installations from converged platform architectures, with customer type influencing upgrade urgency and budget availability.
- Integrated Systems:Unified hardware-software platforms with centralized management dashboards and API extensibility. Municipal procurement standards in the United States increasingly require this architecture to prevent vendor lock-in.
- Mobile Applications:Consumer-facing parking discovery, reservation, and payment interfaces. United Kingdom urban centers show dense deployment as operators compete on payment convenience.
- Web-based:Browser-accessible management portals for remote configuration and reporting.
- Standalone Systems:Legacy point solutions without network connectivity or centralized oversight capabilities.
Standalone Systems dominate legacy installed base. Integrated Systems are gaining share fastest as municipalities mandate open architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement officers concentrate purchasing authority in transportation departments of congested metropolitan areas, with airport authorities and commercial real estate operators representing secondary buyer archetypes. Smart city funding streams and federal facility modernization programs synchronize replacement cycles across major urban centers. Regulatory compliance burdens vary sharply by jurisdiction, filtering vendor participation.
United States
FAA-synchronized airport upgrades and congestion pricing pilots in New York, San Francisco, and Los Angeles drive system replacements. FCC Part 15 certification mandates for wireless sensors filter procurement eligibility. Chicago's Department of Transportation exemplifies municipal demand, specifying open API architectures to prevent vendor lock-in across 36,000 metered spaces.
United Kingdom
GDPR-compliant payment platforms create vendor preference concentration as London boroughs consolidate procurement. Consumer-facing mobile payment density determines operator competitiveness. Manchester's Transport for Greater Manchester coordinates parking integration with congestion charging zones, mandating real-time occupancy data feeds.
Germany
ISO 9001 quality certification reorganizes municipal eligibility for city government contracts. KBA vehicle registration data integration enables automated enforcement linkages. Munich's airport authority drives specification upgrades through integrated entry-control suites serving 46 million annual passengers.
India
Smart Cities Mission funding creates procurement windows where manual enforcement still dominates revenue collection. BIS standards for electronic payment systems shape vendor qualification. Bengaluru's municipal corporation exemplifies underpenetrated demand, piloting sensor networks across 10,000 on-street spaces with revenue-sharing contract structures.
China
MIIT IoT standards and dual carbon goals accelerate wireless retrofit adoption in aging commercial districts. GB standards for intelligent transportation systems harmonize municipal procurement. Shenzhen's transportation bureau leads deployment density, integrating 300,000 parking spaces into unified cloud platforms with real-time traffic management convergence.
Parking Management Systems Market Competitive Environment
Player mix skews toward specialized parking technology vendors with established regulatory affairs functions and recurring service revenue streams. Market structure shows moderate consolidation around vendors with FCC certification expertise and European GDPR compliance frameworks. Two strategic archetypes dominate: hardware-integrated platform providers with sensor manufacturing capabilities, and software-native operators competing on mobile payment density. Competitive moves center on municipal revenue-sharing contract capture and airport authority long-term service agreement renewal.
Within the mobile payment density tier, JustPark and SpotHero exemplify consumer-facing platform strategies competing on transaction volume across United Kingdom and United States urban centers. SKIDATA anchors the hardware-integrated archetype, leveraging European installed base relationships with airport authorities. These three occupy positions reflecting divergent geographic and technological positioning without overlapping core competence domains.
| Leading Market Players |
|---|
| JustPark |
| AirGarage |
| SKIDATA |
| Parkanizer |
| Wayleadr |
| Parkable |
| Get My Parking |
| Nayax |
| SpotHero |
| Others |
Value Chain & Pricing Dynamics
Wireless sensor miniaturization replacing wired infrastructure simultaneously redistributes manufacturing gravity toward East Asian electronics clusters and compresses hardware margins across Western system integrators. This substitution dynamic intensifies pricing pressure on legacy equipment vendors while elevating procurement risk for municipal buyers dependent on certified component flows.
Pricing Analysis
Cost-plus contracts with copper and semiconductor price indexation dominate municipal procurement agreements. Three-tier pricing structure across FCC-certified premium sensors, standard cloud-platform subscriptions, and economy standalone hardware separates vendor tiers. Pricing pressure stems from cloud migration compressing hardware margins while expanding recurring software revenue pools. Municipal transportation departments exhibit highest price sensitivity due to budget volatility, whereas airport authorities prioritize integration reliability over unit cost.
Supply Chain Analysis
China and Taiwan anchor microcontroller and RF component fabrication for IoT sensor manufacturing. Battery cell production draws from South Korean suppliers, while surface-mount packaging concentrates in Malaysian electronics facilities. Single-source vulnerability around FCC Part 15 certification expertise creates procurement bottlenecks for Western integrators. Distribution runs through system integrators serving municipal procurement channels and direct vendor relationships with airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parking management platforms are crossing an inflection where open API interoperability transforms competitive moats from hardware lock-in to ecosystem density, with municipal procurement mandates accelerating this shift toward integrated platform economics.
For Market Incumbents: Fortify regulatory affairs capabilities around FCC Part 15 certification and GDPR-compliant data frameworks to defend municipal contract eligibility against emerging software-native competitors. Deepen backward integration into sensor manufacturing to capture margin pools eroding at the hardware tier, while extending long-term service agreements with airport authorities to anchor recurring revenue streams against cloud-platform displacement. For New Entrants and Emerging Players: ISO 9001 certification fast-track through specialized audit consultants enables participation in municipal procurement windows previously closed to uncertified vendors. Target Indian metropolitan markets under Smart Cities Mission funding where manual enforcement still dominates and revenue-sharing contract structures reduce capital barriers. Pursue mobile payment density accumulation in United Kingdom urban centers as the primary go-to-market wedge against established hardware vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vendors with recurring service revenue and regulatory certification expertise over pure hardware manufacturers. Five-to-ten year viability hinges on cloud-platform subscription conversion and municipal outcome-based contract penetration. Acquisition targets should display FCC certification in-house capabilities and airport authority relationship depth. Watch for inflection signals in vehicle-to-infrastructure API integration mandates from transportation departments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open API architectures prevent vendor lock-in across Chicago's 36,000 metered spaces. |
| Certification Investment | FCC Part 15 expertise filters procurement eligibility for United States municipal contracts. |
| Geographic Expansion | Smart Cities Mission funding creates procurement windows in Indian metropolitan markets. |
| Strategic Partnership | Vehicle-to-infrastructure convergence with connected vehicle platforms enables dynamic pricing. |
| Acquisition of Specialist Firm | RF engineering talent scarcity favors acquiring electromagnetic compliance capabilities. |
Study Parameters
Operator-level perspectives from municipal transportation planners, airport facilities managers, parking system integrators, and IoT hardware procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, municipal procurement records, and airport authority modernization disclosures. Bottom-up sensor deployment counts triangulated against top-down cloud-platform subscription revenue estimates.
Sensitivity analysis tested forecast robustness across copper price volatility scenarios and wireless sensor adoption curves. Segmentation dimensions modeled include product type, technology tier, end-user application, and deployment architecture across the projection horizon. CAGRs derived from installed base replacement cycles synchronized with smart city funding timelines and FAA facility upgrade programs. Forecast inputs incorporated IoT device penetration rates and subscription pricing conversion velocity.
Decision-makers should treat outputs as directional under assumptions of stable municipal procurement standards and continued FCC spectrum allocation; material deviation in regulatory frameworks or cybersecurity disclosure requirements would warrant model refresh. Recalibration cycles align with material shifts in smart city funding appropriations and airport modernization program timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Utility Cases Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Social Networking App Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Intelligent Virtual Store Design Solution Market