
 Global Asset Reliability Software Market | 2026-2036
Global Asset Reliability Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asset Reliability Software Market Foresight
Buyer concentration among oil and gas supermajors is repositioning procurement power toward integrated enterprise platforms. Siemens AG leverages its digital twin portfolio to anchor long-term service contracts with energy majors. SAP SE competes through deep ERP integration that unifies maintenance spend with financial planning cycles. IBM Corporation differentiates via hybrid cloud architectures that bridge legacy SCADA systems with modern analytics layers.
Asset reliability software encompasses predictive analytics engines, condition monitoring systems, and maintenance optimization platforms that ingest vibration, thermal, and operational data to forecast equipment failure before production disruption occurs. These systems typically process sensor streams at sub-second intervals, applying machine learning models to threshold deviations that indicate bearing wear, lubrication breakdown, or electrical insulation degradation across rotating and static assets. Cloud-based deployment leads solution delivery, while predictive analytics commands the fastest expansion as operators shift from calendar-based to condition-directed maintenance paradigms. Maintenance optimization modules retain the deepest margin pools due to recurring algorithm tuning and domain-specific consulting attach rates.
OSHA process safety mandates in the United States, EU F-Gas Regulation leakage monitoring requirements, and Japan METI energy efficiency standards collectively compel facilities to adopt continuous equipment surveillance. China's GB standards for industrial safety and NMPA-equivalent equipment certification in process industries further tighten compliance-driven software procurement. Stakeholders must weigh sovereign data residency rules against cloud-native platform agility when architecting multi-site reliability programs.
Market Dynamics
Energy majors are consolidating procurement around integrated digital twin platforms that bundle predictive analytics with long-term service commitments, compressing vendor selection cycles and locking out point-solution providers.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are forcing industrial operators to upgrade from black-box maintenance tools to auditable predictive systems.
- Offshore wind expansion:Remote turbine installations in the North Sea and US Atlantic coast demand continuous condition monitoring to minimize helicopter-based maintenance trips.
- Digital thread architectures:Unified data models connecting design, operations, and maintenance phases are reducing mean time to repair across process industries.
Market Restraints
- SCADA integration complexity:Legacy control systems in US refineries and German chemical plants require costly middleware layers to interface with modern analytics platforms.
- Sensor hardware concentration:Vibration and thermal monitoring equipment sourcing concentrates among Japanese and German component suppliers, creating procurement bottlenecks.
- Cybersecurity certification delays:IEC 62443 compliance timelines for industrial software are extending sales cycles by six to twelve months in critical infrastructure sectors.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for semiconductor and pharmaceutical production are creating first-mover advantages for predictive maintenance vendors establishing local data centers.
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing facilities require novel reliability models for electrochemical degradation monitoring.
- Edge-to-cloud orchestration:Converging 5G private networks with containerized analytics is enabling sub-50-millisecond failure detection at brownfield industrial sites.
Industry Challenges
- Reliability engineering talent scarcity:Competent data scientists with domain expertise in rotating machinery are commanding premium compensation and extending implementation timelines.
- Multi-site deployment standardization:Oil and gas supermajors operating across Brazil, Nigeria, and Kazakhstan struggle to harmonize reliability data formats across acquired subsidiaries.
- Model drift management:Machine learning algorithms trained on baseline equipment conditions require continuous revalidation as operating envelopes shift, consuming ongoing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asset Reliability Software Market |
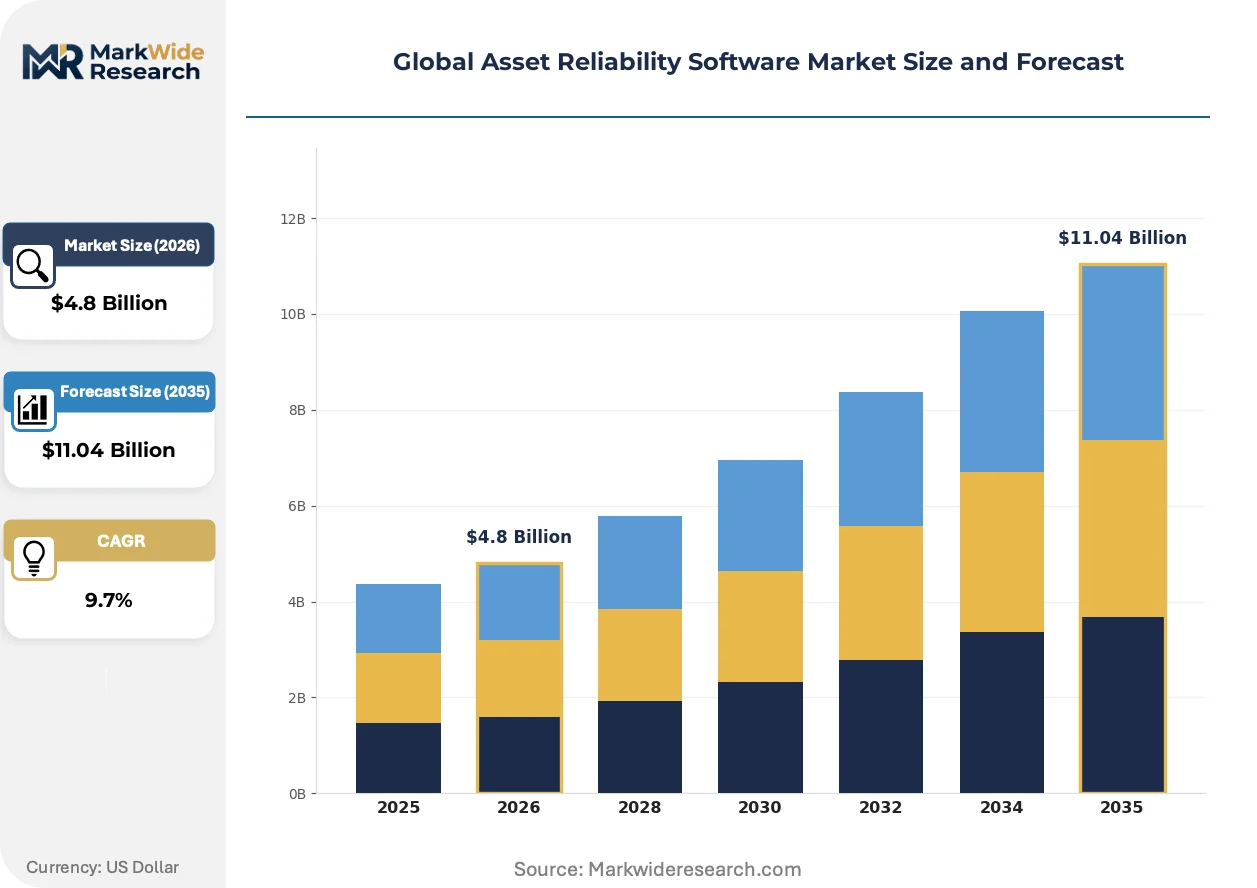
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge, Virtualized Solution Offering: Predictive Analytics, Condition Monitoring, Risk Management, Maintenance Optimization, Data Integration Application: Manufacturing Plants, Energy Facilities, Transportation Networks, Mining Operations, Telecommunications Systems End User: Oil & Gas Companies, Utilities Operators, Construction Firms, Chemical Processors, Aerospace Service Providers |
| Companies Covered | Honeywell International Inc., Bentley Systems, Inc., Siemens AG, Schneider Electric SE, General Electric Company, SAP SE, Aspen Technology, Inc., ABB Ltd, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asset Reliability Software Market Shifts & Advancements
Physics-informed neural networks are merging first-principles engineering models with operational data streams, creating predictive systems that require less historical failure data to achieve acceptable accuracy thresholds.
Edge-deployed inference engines are overtaking cloud-centric architectures for vibration analysis in upstream oil and gas operations. Supermajors operating Permian Basin assets are mandating local processing to comply with sovereign data requirements. This shift is compressing latency from seconds to milliseconds while fragmenting vendor consolidation strategies.
The EU F-Gas Regulation leakage monitoring mandates are compelling chemical and refrigeration facilities to install continuous thermal imaging and pressure anomaly detection systems. Industrial operators in Germany and the Netherlands are prioritizing platforms with pre-configured compliance reporting modules. Refrigeration-intensive food processing and cold chain logistics represent the most affected application segments.
Subscription-based reliability analytics are displacing perpetual license models among mid-sized manufacturing operators. Channel partners in the US Midwest and Southeast are bundling hardware installation with recurring software access. Metal fabrication and automotive component suppliers exhibit the strongest preference for operational expenditure structures over capital-intensive deployments.
Global Asset Reliability Software Market Segmentation
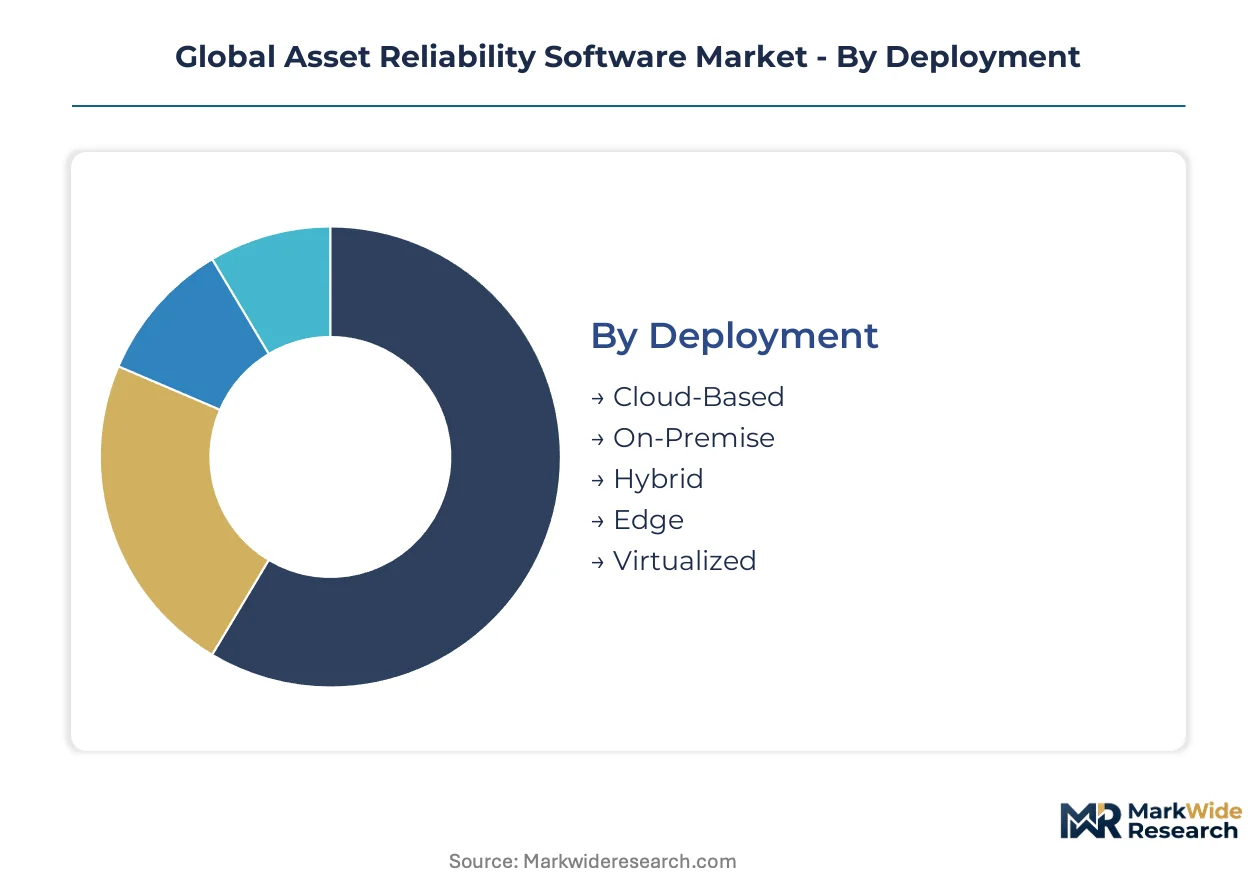
Asset reliability software vendors configure delivery models and feature sets around operational technology maturity, data sovereignty constraints, and maintenance workflow complexity. Segmentation choices directly determine integration architecture, pricing mechanics, and customer lifetime value profiles across industrial verticals.
Deployment:
Customization intensity varies sharply across deployment modes, with sovereign data requirements and latency tolerance dictating infrastructure decisions.
- Cloud-Based:Multi-tenant architectures with elastic compute scaling dominate new procurement among mid-sized manufacturers seeking minimal IT overhead. US utility operators and German chemical processors favor this model for centralized fleet analytics, though EU AI Act audit requirements are forcing vendors to enhance algorithmic transparency documentation.
- Edge:Containerized inference engines deployed directly on industrial gateways process vibration and thermal streams at sub-50-millisecond latency. Permian Basin oil operators and North Sea wind farm developers mandate edge processing to satisfy sovereign data residency rules while enabling real-time failure detection.
- On-Premise:Air-gapped installations persist in defense-adjacent aerospace facilities and critical infrastructure with IEC 62443 cybersecurity mandates.
- Hybrid:Orchestrated workloads split model training in cloud environments from inference execution at plant level.
- Virtualized:Software-defined infrastructure abstracts hardware dependencies for rapid disaster recovery scenarios.
Leading the category by volume: Cloud-Based. Growing fastest: Edge.
Solution Offering:
Margin concentration tracks algorithmic sophistication and consulting attach rates rather than license scale alone.
- Predictive Analytics:Machine learning engines ingest multi-sensor streams to forecast bearing wear, lubrication breakdown, and electrical insulation degradation. Demand concentrates among oil and gas supermajors transitioning from calendar-based to condition-directed maintenance paradigms.
- Maintenance Optimization:Workload scheduling algorithms balance spare parts inventory, technician dispatch, and production continuity constraints. This segment commands the deepest recurring revenue pools through continuous algorithm tuning and domain-specific engineering services.
- Condition Monitoring:Real-time threshold surveillance for vibration, thermal, and pressure anomalies.
- Risk Management:Quantified failure probability models for insurance and regulatory compliance documentation.
- Data Integration:Protocol translation layers bridging legacy SCADA with modern analytics architectures.
Predictive Analytics claims the steepest expansion trajectory as physics-informed neural networks reduce dependence on historical failure datasets. Maintenance Optimization retains the highest margin profile.
Application:
Site-specific regulatory exposure and asset criticality determine platform configuration complexity.
- Energy Facilities:Grid infrastructure operators deploy digital twin platforms to model transformer aging and transmission line thermal loading. US utility modernization programs and EU Green Deal grid reinforcement mandates are accelerating procurement cycles.
- Manufacturing Plants:Discrete and process manufacturers implement vibration monitoring for CNC machining centers and continuous process vessels. India's PLI scheme beneficiaries in semiconductor and pharmaceutical production represent emerging demand concentration.
- Transportation Networks:Rail signaling and fleet maintenance systems prioritize predictive capabilities.
- Mining Operations:Remote pit equipment surveillance reduces unplanned extraction halts.
- Telecommunications Systems:Base station power and cooling reliability underpins 5G network availability.
Energy Facilities anchor category volume. Manufacturing Plants are climbing fastest on automation investment waves.
End User:
Procurement sophistication correlates with asset base scale and regulatory inspection intensity.
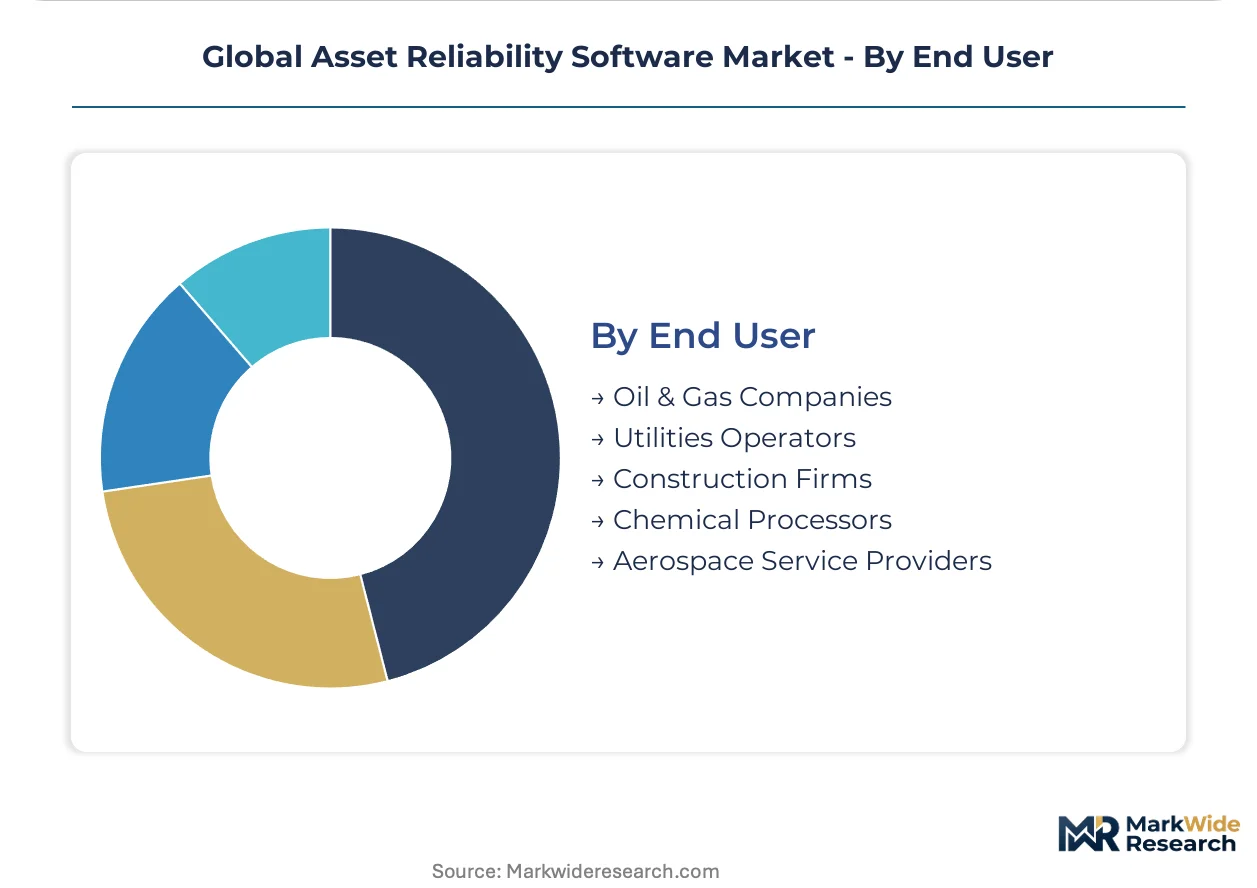
- Oil & Gas Companies:Supermajors consolidate vendor selection around integrated digital twin platforms bundling predictive analytics with decade-long service commitments. OSHA process safety mandates and EPA emissions monitoring requirements compel continuous equipment surveillance.
- Utilities Operators:Transmission and distribution entities modernize aging infrastructure with condition monitoring investments. FERC reliability standards and state-level renewable integration targets in Texas and California shape procurement specifications.
- Chemical Processors:EU F-Gas Regulation leakage monitoring and Japan METI energy efficiency standards drive thermal imaging deployments.
- Construction Firms:Heavy equipment fleet management adopts subscription-based reliability analytics.
- Aerospace Service Providers:MRO operations implement model-based prognostics for engine and landing gear systems.
Oil & Gas Companies dominate procurement value. Utilities Operators are gaining share fastest on grid infrastructure reinvestment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utility operators and German chemical processors concentrate procurement for asset reliability platforms, with demand clustering around grid modernization mandates and process safety compliance. Sovereign data requirements and aging infrastructure replacement cycles shape regional deployment preferences.
United States
FERC reliability standards and state-level renewable integration targets in Texas and California accelerate utility procurement of digital twin platforms. OSHA process safety mandates compel Gulf Coast refineries to upgrade predictive maintenance systems. The Permian Basin anchors edge-computing deployments as supermajors mandate local processing for sovereign data compliance.
Germany
EU F-Gas Regulation leakage monitoring requirements drive thermal imaging adoption across chemical and refrigeration facilities. The EU AI Act forces industrial operators to abandon black-box maintenance tools for auditable predictive systems. The Rhine-Ruhr industrial corridor concentrates demand for condition monitoring in steel and chemical processing plants.
China
GB standards for industrial safety and NMPA-equivalent equipment certification tighten compliance-driven software procurement in process industries. Dual carbon goals accelerate predictive maintenance adoption in power generation and heavy manufacturing. The Yangtze River Delta clusters smart factory investments integrating reliability analytics with automated production lines.
India
PLI scheme incentives for semiconductor and pharmaceutical production create first-mover opportunities for predictive maintenance vendors establishing local data centers. CEA grid modernization directives push transmission operators toward condition monitoring investments. Gujarat and Maharashtra host the fastest-growing manufacturing automation clusters demanding subscription-based reliability analytics.
Japan
METI energy efficiency standards mandate continuous equipment surveillance across process industries. JIS certification requirements shape procurement specifications for maintenance optimization platforms. The Chubu region around Nagoya concentrates automotive and precision machinery demand for vibration monitoring and predictive analytics integration.
Global Asset Reliability Software Market Competitive Landscape
United States software vendors anchor one tier; European industrial automation specialists hold another. Market structure tilts toward consolidated procurement as oil and gas supermajors compress vendor selection cycles around bundled digital twin platforms. Three archetypes dominate: ERP-integrated suite providers, hybrid cloud infrastructure vendors, and edge-native condition monitoring specialists. M&A activity concentrates on predictive analytics capabilities, while strategic partnerships bridge legacy SCADA integration gaps.
Among Germany-based industrial conglomerates, Siemens AG occupies a position exemplifying the digital twin platform archetype with long-term service contract anchoring. SAP SE represents the ERP-integrated suite model unifying maintenance spend with financial planning cycles. IBM Corporation sits within the hybrid cloud infrastructure tier, bridging legacy control systems with modern analytics layers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bentley Systems, Inc. |
| Siemens AG |
| Schneider Electric SE |
| General Electric Company |
| SAP SE |
| Aspen Technology, Inc. |
| ABB Ltd |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Horizontal consolidation among Japanese and German sensor hardware suppliers anchors both supply security and pricing power for vibration and thermal monitoring equipment. This supplier concentration compresses margins for software vendors while elevating procurement costs for end-users integrating condition monitoring systems.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin pools reside in maintenance optimization modules with consulting attach rates. Price differentiation rests on algorithmic sophistication and IEC 62443 cybersecurity certification tiers. Pricing pressure stems from mid-sized manufacturers demanding operational expenditure structures over capital-intensive perpetual licenses. Metal fabrication and automotive component suppliers exhibit the highest price sensitivity, whereas oil and gas supermajors prioritize integrated digital twin platforms with decade-long service commitments.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States manage hub-and-spoke patterns for sensor hardware and edge computing gateways. Component sourcing draws from Taiwanese semiconductor foundries, German precision engineering clusters, and Japanese vibration sensor specialists. Single-source vulnerability concentrates in electromechanical sensor supply for offshore wind turbine monitoring. Distribution runs through industrial automation channel partners bundling hardware installation with software access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around bundled digital twin platforms as EU AI Act compliance mandates force point-solution providers toward acquisition or exit.
For Market Incumbents: Acquire predictive analytics capabilities with physics-informed neural network architectures to defend against edge-native specialists. Secure IEC 62443 certification ahead of sales cycle extensions in critical infrastructure sectors. Cement long-term service contracts with oil and gas supermajors before procurement compression eliminates standalone vendors. For New Entrants and Emerging Players: Launch via subscription-based reliability analytics targeting India's PLI scheme beneficiaries in semiconductor and pharmaceutical manufacturing. Prioritize Gujarat and Maharashtra manufacturing clusters with localized data center infrastructure. Partner with industrial automation distributors in the US Midwest to bundle hardware installation with recurring software access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by ERP-integrated suite providers seeking maintenance optimization capabilities. Five-to-ten year viability favors vendors with sovereign data residency architectures and pre-configured EU F-Gas Regulation compliance modules. Watch for inflection when hydrogen economy infrastructure investments trigger novel electrochemical degradation monitoring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Physics-informed neural network capabilities reduce historical failure data dependence for oil and gas operators. |
| Platform Integration | ERP-embedded maintenance spend unification captures procurement cycles at German chemical processors. |
| Geographic Expansion | Local data centers in India satisfy CEA grid modernization directives and PLI scheme localization requirements. |
| Strategic Partnership | Legacy SCADA middleware bridges compress implementation timelines at US refineries and German chemical plants. |
| Product Launch | Edge-deployed inference engines with sub-50-millisecond latency meet Permian Basin sovereign data mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across reliability engineering directors, plant maintenance managers, IT procurement officers, and industrial automation channel partners. Bottom-up modeling triangulated against top-down sectoral expenditure analysis from EIA grid investment disclosures, EU Green Deal implementation trackers, and Japan METI energy efficiency compliance databases.
Granularity-level modeling deployed deployment mode, solution offering, application vertical, and end-user sophistication tier as primary segmentation dimensions across the analysis window. CAGRs derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and predictive maintenance adoption curve modeling. Physics-informed neural network penetration rates and edge computing infrastructure capex trajectories informed technology diffusion assumptions.
Regulatory enforcement delays, sensor hardware procurement bottlenecks, and reliability engineering talent scarcity are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Spain Digital Twin Market
Digital Solutions
Product Information Management Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Electronic Discovery Market