
 Global Content Recommendation Engine Market | 2026-2036
Global Content Recommendation Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Content Recommendation Engine Market Analysis
Monolithic recommendation architectures is fragmenting into modular, API-first microservices that allow platforms to swap models without rebuilding entire stacks. Google LLC leverages its tensor processing infrastructure to dominate latency-sensitive video recommendation workloads. Amazon Web Services anchors enterprise deployments through its managed personalization services integrated with broader cloud ecosystems. Taboola Inc. competes in the publisher-centric content discovery layer, sustaining margin through direct inventory relationships with news organizations.
A content recommendation engine is a computational system that applies statistical learning algorithms to user behavioral signals—clickstreams, dwell time, purchase history, and implicit feedback matrices—to predict and rank items most likely to engage a specific individual. These systems typically process inference requests within 50-200 milliseconds to serve real-time interfaces without perceptible latency. Deep Learning segments command premium pricing due to neural architecture search and transformer-based sequence modeling requirements that demand specialized GPU clusters. Collaborative Filtering retains volume leadership in e-commerce deployments where sparse user-item matrices benefit from matrix factorization efficiency. Cloud-Based deployment absorbs the fastest expansion as media companies abandon on-premises inference farms for elastic auto-scaling.
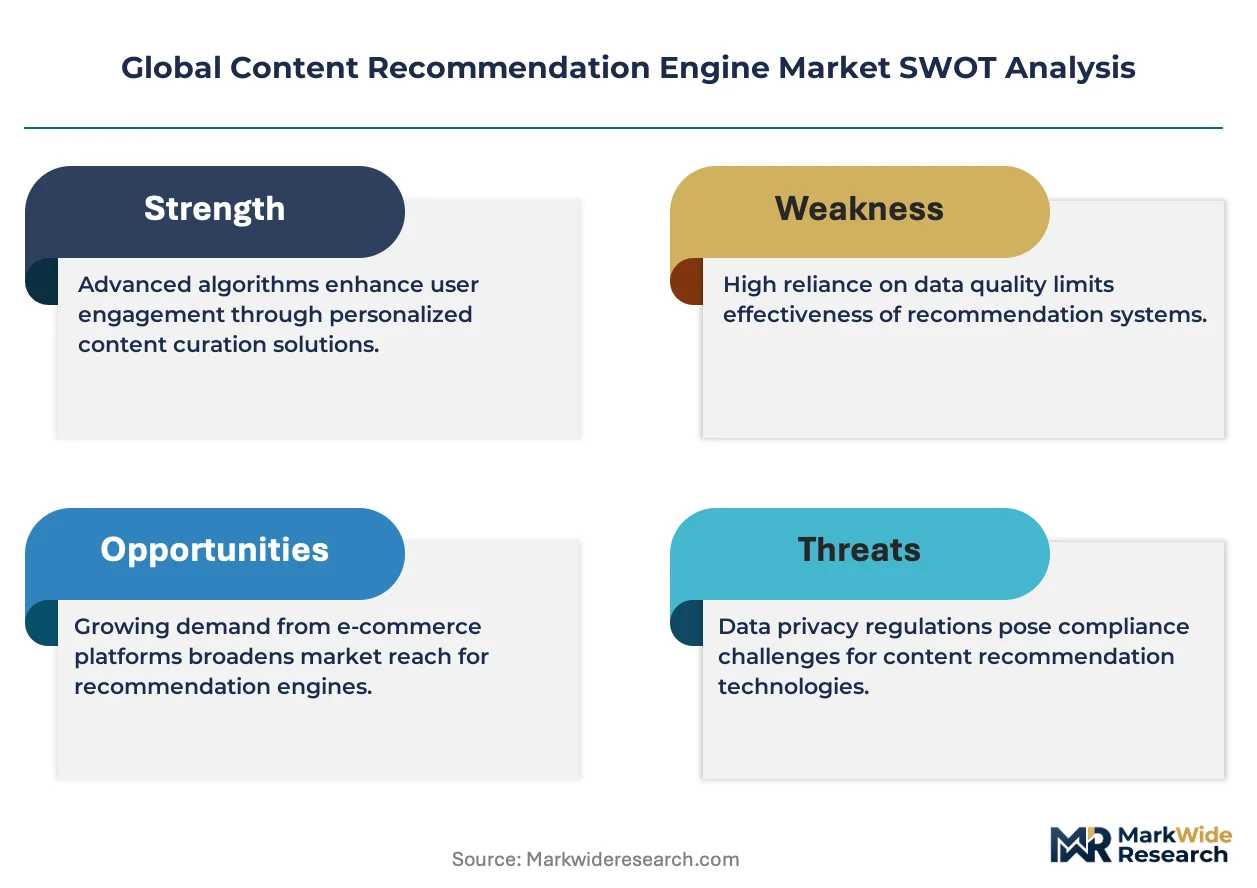
The EU AI Act mandates explainability thresholds for high-risk automated decision systems, directly shaping product roadmaps for engines deployed in European media and publishing markets. The FDA has issued guidance on software as a medical device that intersects with health-adjacent recommendation systems, while China's SAMR enforces algorithmic recommendation provisions under its 2022 regulations. Stakeholders must monitor divergence between prescriptive transparency regimes and performance-optimized black-box architectures, as compliance investments will separate deployable platforms from legacy stacks.
Market Dynamics
Streaming platforms are dismantling monolithic recommendation stacks in favor of modular, API-first microservices that permit rapid model swapping without full-stack rebuilds. This architectural fragmentation is compressing vendor switching costs and redistributing competitive advantage toward specialized inference providers.
Growth Catalysts
- EU AI Act transparency mandates:European publishers now face explainability requirements for algorithmic curation systems. This regulatory pressure is accelerating procurement of compliant recommendation engines across Germany, France, and the Netherlands.
- Real-time video inference demand:Latency budgets below 100 milliseconds for personalized video thumbnails are driving specialized GPU cluster deployments. Streaming services in the United States and South Korea are expanding edge inference footprints to meet this threshold.
- Cloud-based auto-scaling adoption:Media companies are abandoning fixed-capacity on-premises inference farms. Elastic Kubernetes orchestration is now the default deployment pattern for mid-market broadcasters in Brazil and India.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in training-grade silicon creates procurement bottlenecks for transformer-based sequence models. Foundry capacity constraints in Taiwan extend lead times for specialized inference accelerators.
- Data localization requirements:China's SAMR algorithmic recommendation provisions and India's draft data protection framework impose cross-border transfer restrictions. Multi-tenant cloud architectures face reconfiguration costs to satisfy jurisdictional data sovereignty rules.
- Matrix factorization efficiency ceilings:Collaborative filtering architectures hit scaling limits when user-item matrices exceed 10^9 interactions. Sparse embedding techniques struggle with cold-start problems in long-tail content catalogs.
Strategic Opportunities
- Healthcare-adjacent content curation:FDA guidance on software as a medical device is creating compliant recommendation pathways for patient education platforms. Wellness apps in the United States are integrating clinically validated content ranking systems.
- Publisher-centric discovery layers:News organizations are reclaiming audience relationships from platform intermediaries. Direct inventory relationships with European media groups are opening independent recommendation service contracts.
- Federated learning architectures:Privacy-preserving model training across distributed device clusters is converging with differential privacy techniques. Mobile-first markets in Indonesia and Nigeria present greenfield deployment scenarios for on-device personalization.
Industry Challenges
- Neural architecture search talent scarcity:Production-grade transformer optimization requires specialized machine learning engineering expertise. Competition for GPU kernel optimization specialists is inflating compensation benchmarks in Silicon Valley and Shenzhen.
- Legacy CMS integration friction:Decades-old content management systems in established publishing houses lack real-time API endpoints. Middleware development for SOAP-to-REST translation consumes 30-40% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Content Recommendation Engine Market |
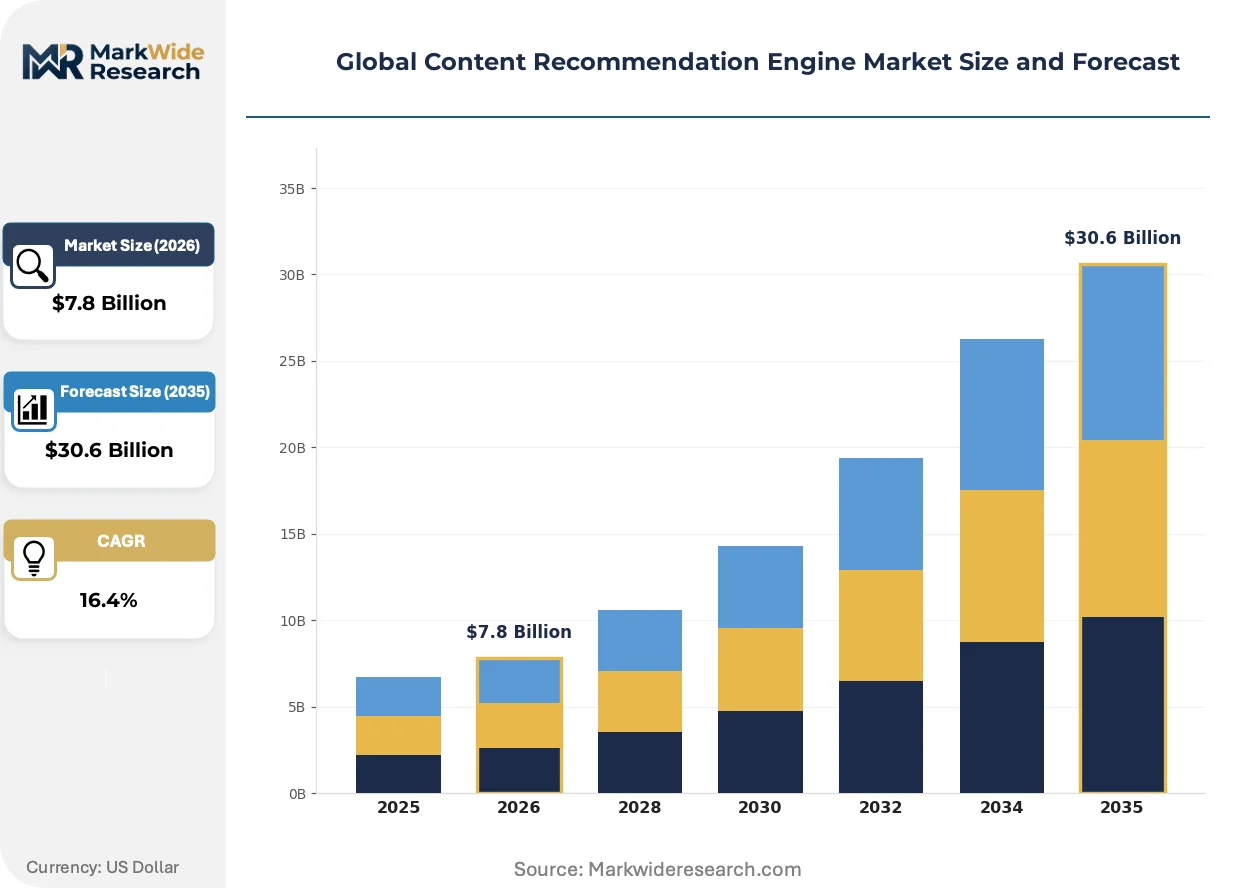
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $30.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Collaborative Filtering, Deep Learning, Natural Language Processing End User: E-Commerce, Media & Entertainment, News & Publishing, Social Media Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Application: Personalized Marketing, Content Discovery, User Engagement, Recommendation Systems |
| Companies Covered | Amazon Web Services, Google LLC, International Business Machines Corporation, Adobe Inc., Taboola Inc., Outbrain Inc., Dynamic Yield Ltd, Salesforce Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Content Recommendation Engine Market Emerging Trajectories
Transformer-based sequence models are compressing recommendation latency while expanding contextual understanding of user sessions. This capability expansion is reshaping competitive requirements across video, audio, and interactive content verticals.
Self-supervised learning for content embeddings is migrating from research environments into production pipelines at scale. Major streaming platforms in the United States and Japan are adopting contrastive learning techniques for cold-start item representation. This migration from supervised feature engineering is collapsing the time-to-value for new content catalog ingestion from months to days.
The EU AI Act's risk classification framework for automated decision systems is forcing architectural disclosures from black-box recommendation providers. Publishers operating in France and Germany must now maintain technical documentation sufficient for regulator audit. Deep learning segments are responding by investing in attention-weight visualization tools and counterfactual explanation generators.
Enterprise procurement of recommendation infrastructure is consolidating around outcome-based performance contracts rather than per-request pricing. Media buyers in the United Kingdom and Australia are demanding engagement-rate guarantees with clawback provisions. This contractual evolution is displacing pure SaaS subscription models and aligning vendor incentives with measurable audience retention outcomes.
Global Content Recommendation Engine Market Segmentation
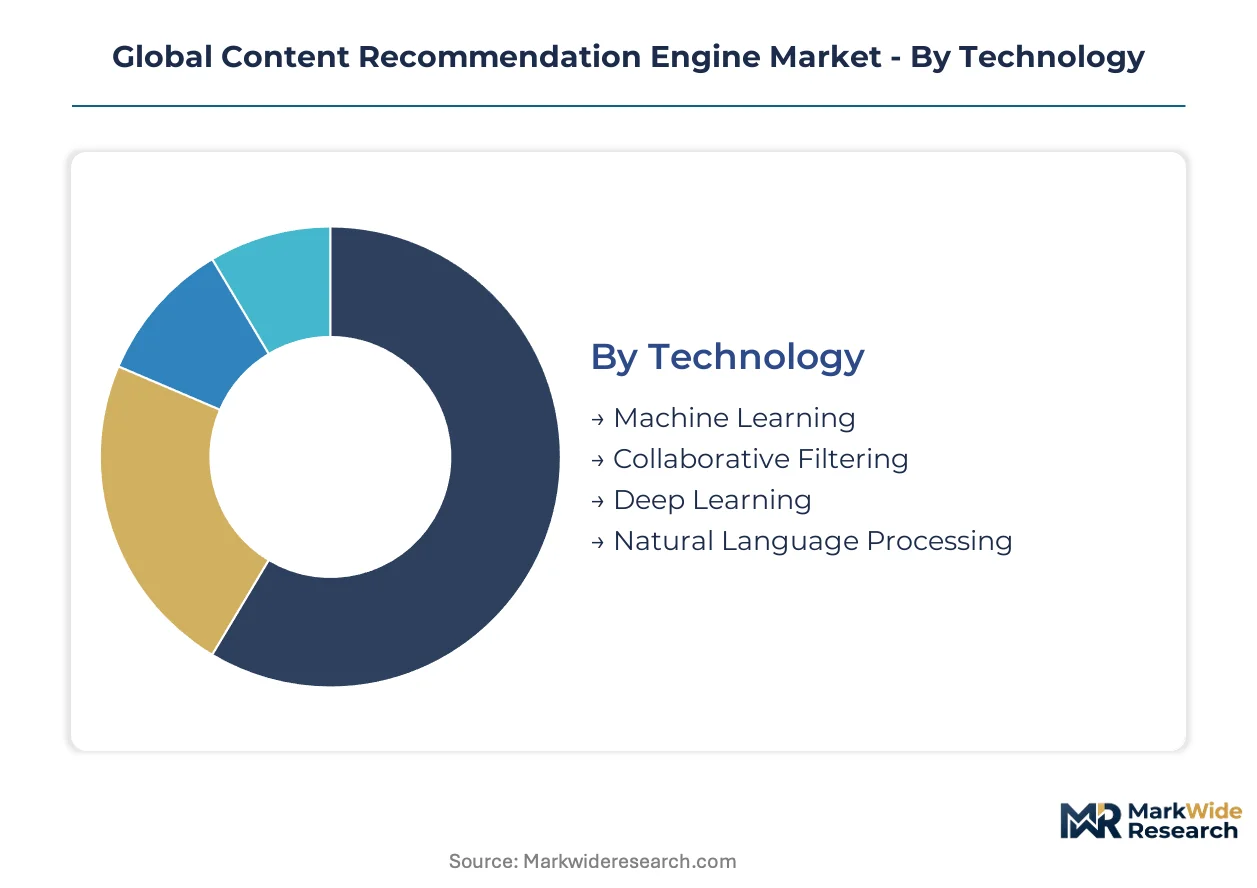
Recommendation engine architectures fragment across technology maturity curves, deployment cost structures, and latency requirements. Each segmentation dimension carries distinct procurement cycles and vendor switching economics that reshape competitive positioning.
Technology:
Model refresh cycles range from weekly retraining for real-time collaborative filters to quarterly architecture searches for deep learning stacks. Cycle speed directly correlates with infrastructure burn rate and talent intensity.
- Deep Learning:Transformer-based sequence models with neural architecture search demand specialized GPU clusters and kernel optimization expertise. Streaming platforms in the United States and South Korea deploy these for sub-100 millisecond video thumbnail personalization. Talent scarcity in Silicon Valley and Shenzhen inflates implementation costs.
- Collaborative Filtering:Matrix factorization techniques process sparse user-item interactions through efficient latent factor decomposition. E-commerce deployments across Germany and Japan favor this approach for mature catalogs with dense interaction histories. Scaling limits emerge when matrices exceed 10^9 interactions.
- Machine Learning:Gradient-boosted decision trees and logistic regression ensembles serve mid-latency recommendation tasks. Brazilian broadcasters integrate these through elastic Kubernetes orchestration.
- Natural Language Processing:BERT-derived embeddings and transformer encoders extract semantic content features for text-heavy discovery. News organizations in France deploy these for article-to-article matching pipelines.
Collaborative Filtering anchors the volume base while Deep Learning gains share at the steepest rate.
End User:
Customer procurement authority concentrates with CTOs in media conglomerates versus CMOs in retail environments. Budget approval velocity varies accordingly.
- Media & Entertainment:Streaming services demand real-time inference for personalized video thumbnails and autoplay sequences. Edge deployment footprints expand across the United States and South Korea to meet sub-100 millisecond latency budgets. GPU cluster procurement dominates capital allocation.
- E-Commerce:Product recommendation modules integrate with inventory management and pricing engines. German and Japanese retailers prioritize matrix factorization efficiency for dense transaction histories. Cart abandonment recovery drives engagement metric contracts.
- News & Publishing:Editorial teams reclaim audience relationships from platform intermediaries. French and Dutch publishers procure explainable ranking systems to satisfy EU AI Act audit requirements. Direct inventory relationships sustain margin for independent discovery layers.
- Social Media:Feed ranking systems process billions of daily interactions through distributed inference farms. Content moderation integration shapes architectural requirements in regulated jurisdictions.
E-Commerce anchors the volume base while News & Publishing climbs the fastest amid regulatory-driven replacement cycles.
Deployment:
Capital commitment intensity descends from fixed on-premises infrastructure to metered SaaS consumption. Migration patterns track cloud maturity in customer IT organizations.
- Cloud-Based:Elastic auto-scaling through managed Kubernetes services eliminates fixed-capacity inference farms. Mid-market broadcasters in Brazil and India default to this pattern. AWS Personalize and Google Cloud Recommendation AI anchor enterprise procurement.
- SaaS:Outcome-based performance contracts with engagement-rate guarantees displace per-request pricing. Media buyers in the United Kingdom and Australia demand clawback provisions for retention shortfalls.
- Hybrid:Sensitive user data remains on-premises while model training leverages cloud burst capacity. China's SAMR algorithmic recommendation provisions drive this architecture for cross-border operators.
- On-Premises:Fixed-capacity GPU clusters serve latency-sensitive workloads in regulated environments. Legacy broadcasters in established European markets maintain these deployments for content sovereignty compliance.
On-Premises anchors the volume base while Cloud-Based expands most quickly as media companies abandon captive infrastructure.
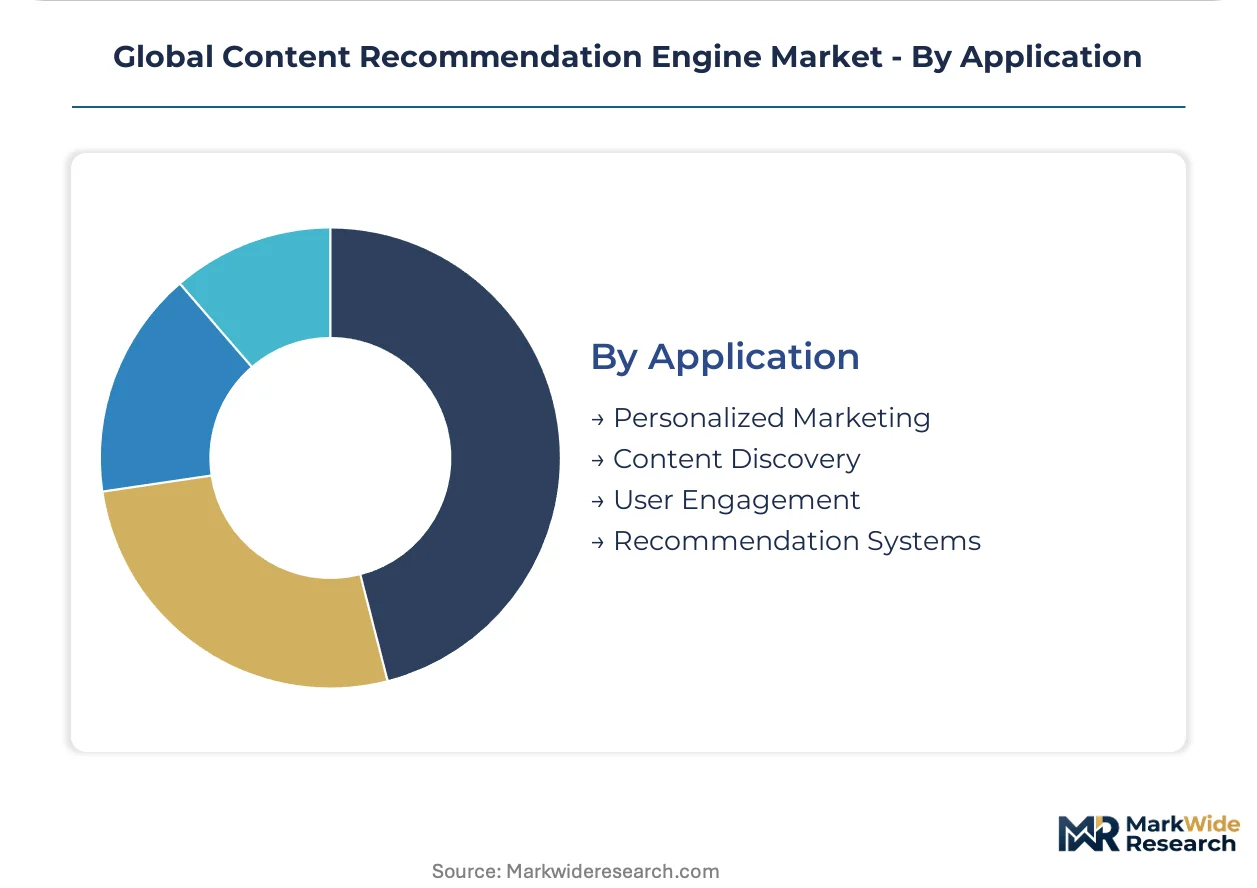
Application:
Use case technical requirements diverge across batch prediction versus real-time serving constraints. Integration complexity with existing content pipelines varies substantially.
- Recommendation Systems:Core ranking infrastructure integrates with content management systems and user profile stores. SOAP-to-REST middleware consumes 30-40% of implementation timelines in legacy publishing houses. Real-time API endpoints enable sub-200 millisecond serving.
- Content Discovery:Cold-start item representation through self-supervised contrastive learning collapses ingestion timelines. Major streaming platforms in the United States and Japan deploy these techniques for new catalog arrivals.
- Personalized Marketing:Email and push notification targeting leverages batch inference with relaxed latency constraints. Engagement optimization focuses on send-time personalization and creative selection.
- User Engagement:Session-level interaction modeling predicts churn and prompts retention interventions. Wellness apps in the United States integrate clinically validated pathways under FDA software guidance.
Recommendation Systems anchors the volume base while Content Discovery shows the steepest expansion trajectory as platforms compress new content time-to-value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscalers export recommendation infrastructure to streaming platforms in South Korea and Japan, while European publishers import compliance-ready systems to satisfy transparency mandates. This trade corridor shapes deployment patterns across three continents.
United States
Streaming services in Los Angeles and New York Metro drive sub-100 millisecond video thumbnail personalization through edge GPU clusters. The FTC enforces algorithmic transparency in consumer-facing recommendation systems. Seattle anchors cloud-managed personalization services through AWS infrastructure dominance.
Germany
Frankfurt-based broadcasters procure explainable ranking systems to satisfy EU AI Act audit requirements for algorithmic curation. The KBA coordinates with federal media regulators on automated decision system oversight. Berlin hosts independent discovery layer startups serving Dutch and French publisher contracts.
South Korea
Seoul streaming platforms expand edge inference footprints for real-time K-content personalization across Southeast Asian export markets. The MFDS intersects with wellness app recommendation systems under software medical device guidance. Pangyo Techno Valley concentrates transformer optimization engineering talent.
Japan
Tokyo broadcasters adopt contrastive learning for cold-start anime catalog ingestion, collapsing content pipeline timelines. METI promotes trustworthy AI frameworks affecting recommendation engine procurement standards. Osaka-Kyoto corridor houses legacy publisher CMS integration specialists.
Brazil
São Paulo mid-market broadcasters default to elastic Kubernetes orchestration for cloud-based recommendation deployment. ANVISA guidance shapes health-adjacent content curation compliance pathways. Rio de Janeiro media groups pilot federated learning architectures for privacy-preserving personalization.
Global Content Recommendation Engine Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Hyperscale cloud providers anchor enterprise procurement through integrated personalization services, while independent discovery layers sustain margin through direct publisher relationships. The market consolidates around infrastructure-integrated specialists, API-first microservice vendors, and content-discovery intermediaries. Competitive moves center on modular architecture licensing and outcome-based performance contracting with engagement guarantees.
Within the infrastructure-integrated tier, Amazon Web Services and Google LLC exemplify channel dominance through tensor processing and managed cloud ecosystems. Taboola Inc. occupies the independent discovery layer position, anchoring publisher-centric content recommendation through direct inventory relationships with news organizations.
| Leading Market Players |
|---|
| Amazon Web Services |
| Google LLC |
| International Business Machines Corporation |
| Adobe Inc. |
| Taboola Inc. |
| Outbrain Inc. |
| Dynamic Yield Ltd |
| Salesforce Inc. |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
NVIDIA's dominance in training-grade GPU silicon concentrates upstream supply leverage, pushing margin pools downstream toward cloud-managed inference services and specialized kernel optimization consultancies. Transformer-based model deployments absorb premium pricing power while collaborative filtering commoditizes at volume tiers.
Pricing Analysis
Next-generation transformer architectures command three-to-fourfold premiums over legacy matrix factorization stacks. Three-tier pricing structure across premium deep-learning inference, standard machine-learning ensembles, and economy collaborative-filtering tiers stratifies the market. Price differentiation hinges on latency guarantees under 100 milliseconds and EU AI Act explainability certification. Cost compression in the standard tier intensifies as elastic Kubernetes orchestration democratizes deployment. Mid-market broadcasters in Brazil and India exhibit highest price sensitivity; streaming platforms in the United States and South Korea demonstrate lowest sensitivity due to engagement-rate guarantee contracts.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive capacity for advanced inference accelerators, with trailing-edge production concentrated in mainland China. Taiwan, South Korea, and the United States anchor geographic supply concentration for specialized GPU clusters. Raw material dependencies include HBM memory stacks from SK Hynix and Micron, CoWoS packaging substrates, and rare earth elements for magnetics in cooling systems. Single-source vulnerability around NVIDIA's CUDA ecosystem creates procurement bottlenecks for transformer optimization. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales arms of AWS, Google Cloud, and Azure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Production-grade neural architecture search expertise sits as the binding constraint, with fewer than five thousand engineers globally capable of optimizing transformer kernels for sub-100 millisecond inference. This scarcity redistributes competitive advantage toward employers offering equity-heavy compensation and dedicated GPU cluster access.
For Market Incumbents: Build switching-cost moats through deep CMS integration and proprietary content embedding pipelines. Incumbents should anchor enterprise procurement with outcome-based performance contracts featuring engagement-rate guarantees and clawback provisions. Threat from API-first microservice vendors demands defensive API standardization efforts. Vertical integration into edge inference hardware through custom ASIC partnerships secures latency advantages for video thumbnail personalization workloads. For New Entrants and Emerging Players: Pursue publisher-centric discovery layers in European markets where EU AI Act transparency mandates displace black-box incumbents. The most penetrable white-space sits with mid-market news organizations in France, Germany, and the Netherlands seeking explainable ranking systems. Federated learning architectures for privacy-preserving mobile personalization present greenfield opportunities in Indonesia and Nigeria. Go-to-market should emphasize rapid SOAP-to-REST middleware deployment for legacy publishing CMS integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed recommendation infrastructure specialists carrying 2018-2021 vintage cloud deployment toolkits. Long-term viability across the next decade favors platforms with EU AI Act compliance documentation and transformer optimization talent density. Acquisition targets should exhibit direct inventory relationships with news organizations and clinically validated content pathways under FDA software guidance. Watch GPU cluster utilization rates as an inflection indicator for demand elasticity in streaming verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Architecture Search Talent Acquisition | Kernel optimization expertise at Pangyo Techno Valley and Shenzhen commands equity premiums above cash compensation. |
| EU AI Act Compliance Certification | Technical documentation for regulator audit opens procurement pathways with Frankfurt broadcasters and Berlin publishers. |
| Edge Inference Footprint Expansion | Sub-100 millisecond latency guarantees secure contracts with Seoul streaming platforms exporting K-content to Southeast Asia. |
| Federated Learning Architecture Deployment | On-device personalization satisfies China's SAMR data localization provisions while reducing cloud inference costs. |
| Outcome-Based Performance Contracting | Engagement-rate guarantees with clawback provisions displace per-request pricing for UK and Australian media buyers. |
Methodological Framework
The analysis maps deep learning inference stacks, collaborative filtering architectures, and federated learning deployments, each validated through CTOs at streaming platforms, machine learning engineering directors, and procurement officers at mid-market broadcasters. Primary interviews with cloud infrastructure specialists and publisher technology executives combined with secondary validation from SEC filings of hyperscaler capex disclosures, EU AI Act regulatory documentation, and FDA software guidance repositories. Bottom-up triangulation across vendor pricing disclosures and top-down reconciliation against cloud service revenue segments anchored market sizing.
Assumption sets held regulatory enforcement timelines and GPU foundry capacity expansion plans fixed while varying enterprise cloud migration velocity and publisher in-housing propensity across the projection horizon. Segmentation dimensions modeled include technology generation, deployment architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves weighted by cloud infrastructure spend growth and content catalog expansion rates. Forecast inputs incorporated transformer model parameter growth trajectories and edge inference latency requirement tightening.
Macroeconomic conditions sit as an overlay; deviation in digital advertising spend and enterprise IT budget cycles would shift the trajectory. Forecasts reflect documented assumptions around GPU supply normalization and regulatory harmonization between EU AI Act transparency mandates and performance-optimized black-box architectures. Quarterly review of hyperscaler capex allocation and foundry utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Incidence Management Software Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
System Integrator Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
AQI App Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Self Service Technology Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Asia Pacific Smart Card Market