
 Global Competitive Intelligence Tools Market | 2026-2036
Global Competitive Intelligence Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Competitive Intelligence Tools Market Foresight
GDPR enforcement is rebalancing the cost-of-entry calculus for competitive intelligence platforms serving European enterprise clients. Kompyte leverages automated battlecard generation to sustain engagement with mid-market SaaS vendors. Crayon dominates real-time competitor tracking through persistent web monitoring and alert infrastructure. AlphaSense anchors institutional research workflows with proprietary natural language processing applied to earnings transcripts and regulatory filings.
Competitive intelligence tools comprise software systems that aggregate, structure, and analyze competitor data from public and proprietary sources, typically incorporating machine learning classification with sub-second query response times for real-time alerting. These platforms serve commercial strategy functions by surfacing pricing movements, product launches, and market positioning shifts before they fully materialize in public reporting. Cloud-based deployment leads adoption among consulting firms and market research agencies that require elastic compute for large-scale data mining and trend analysis workloads. On-premise configurations persist in financial analyst environments where benchmarked data cannot leave controlled infrastructure, preserving margin pools for vendors with hardened security certifications. Predictive analytics and SWOT analysis modules represent the fastest-growing solution types as business enterprises seek anticipatory rather than reactive competitive positioning.
FDA disclosure requirements for pharmaceutical pipeline reporting create structured data feeds that competitive intelligence platforms routinely ingest, shaping product design around regulatory filing timelines. EMA transparency policies and SEC EDGAR filing mandates similarly standardize the information landscape that these tools parse, reducing data acquisition friction while raising the bar for differentiation through synthesis quality. Stakeholders must monitor how the EU AI Act's risk classification system applies to automated competitor profiling, as compliance obligations will separate deployable architectures from legacy scraping approaches.
Market Dynamics
The EU AI Act's risk classification system for automated decision-making is restructuring vendor architectures, forcing platforms to demonstrate auditability and human oversight in competitor profiling workflows.
Growth Catalysts
- EMA Transparency Policies:Standardized disclosure timelines for pharmaceutical pipeline data create predictable ingestion schedules that competitive intelligence platforms optimize around.
- Cloud Elasticity:Consulting firms in Frankfurt and Munich deploy auto-scaling compute for large-scale sentiment analysis and trend detection workloads.
- Natural Language Processing:Proprietary NLP engines applied to SEC EDGAR filings compress signal-to-noise ratios in earnings transcript analysis.
Market Restraints
- GDPR Enforcement:Cross-border data transfer restrictions elevate compliance costs for platforms serving multi-jurisdictional enterprise clients.
- On-Premise Infrastructure:Financial analyst environments require air-gapped deployments that limit vendor margin expansion through SaaS pricing models.
- Data Source Fragmentation:Proprietary filing formats across national regulators impose parsing overhead that synthetic data standardization has not resolved.
Strategic Opportunities
- India's PLI Scheme:Manufacturing incentives for electronics and pharmaceuticals are generating competitor facility investment data that local platforms can monetize.
- Real-Time Alerting:Sub-second query response requirements in algorithmic trading desks create premium pricing tiers for low-latency competitor signal detection.
- CSRD Mandates:Corporate sustainability reporting directives in the European Union are expanding structured ESG data volumes available for competitive benchmarking.
Industry Challenges
- Machine Learning Engineering Talent:Scarcity of specialists capable of tuning classification models for domain-specific competitor signals constrains product roadmap velocity.
- Legacy System Integration:Enterprise CRM and ERP environments require custom API development that extends deployment timelines and elevates professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Competitive Intelligence Tools Market |
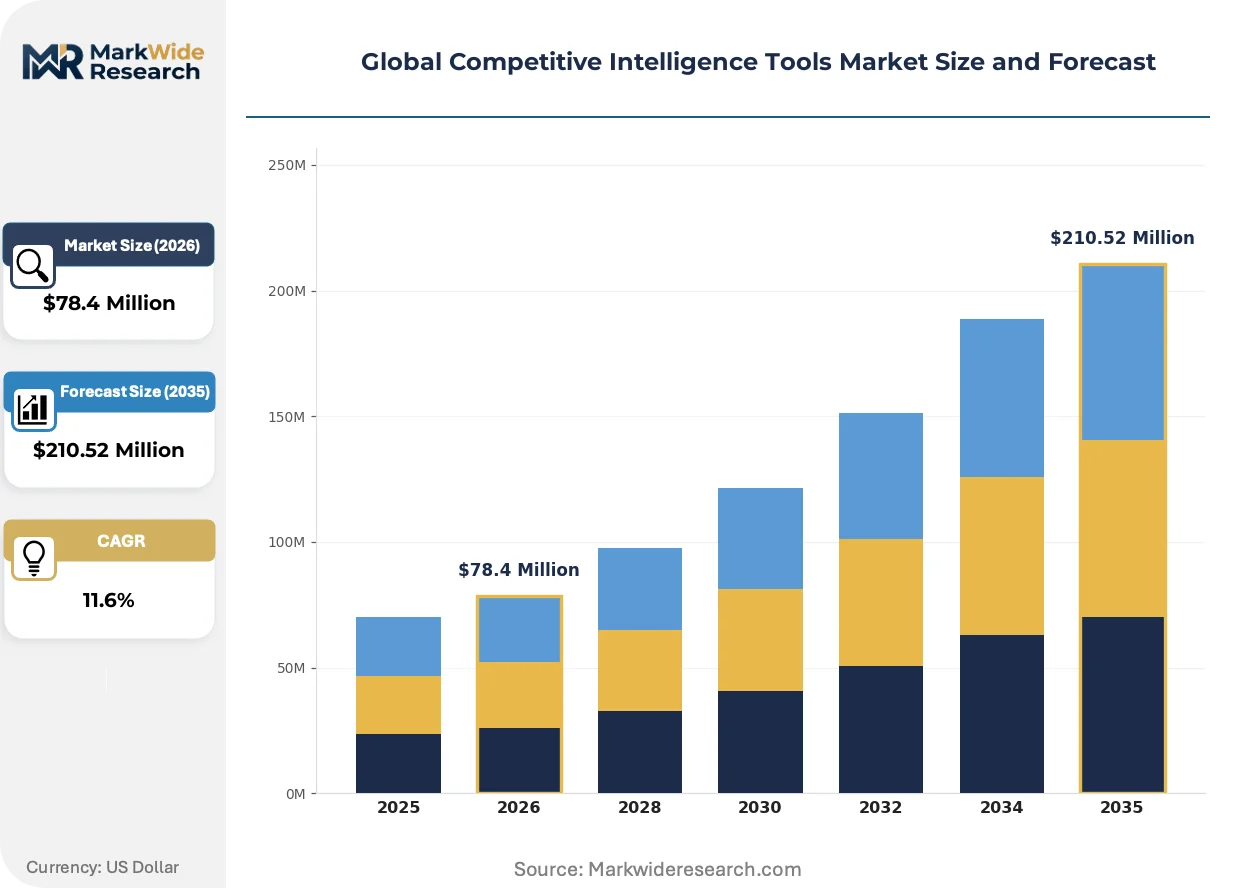
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $210.52 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Mining, Predictive Analytics, Benchmarking, Market Intelligence, SWOT Analysis, Trend Analysis Deployment Mode: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud End User: Consulting Firms, Market Research Agencies, Business Enterprises, Technology Providers, Financial Analysts Application Area: Competitor Tracking, Product Launch Analysis, Pricing Strategy, Customer Segmentation, Risk Assessment |
| Companies Covered | Kompyte, ZoomInfo, Crayon, Similarweb, Semrush, Klue, Contify, Valona Intelligence, AlphaSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Competitive Intelligence Tools Market Shifts & Advancements
Generative models are compressing the cycle from raw competitor signal detection to strategic insight delivery, reshaping how commercial strategy teams consume intelligence.
Large language models are automating battlecard generation and executive briefing synthesis. Mid-market SaaS vendors adopt these capabilities fastest, replacing manual analyst curation with self-refreshing competitive positioning documents. The technology is automating the translation of unstructured web data into structured competitive threat assessments.
The EU AI Act's high-risk system classification applies to automated competitor profiling that influences strategic decisions. Vendors must implement human-in-the-loop review mechanisms and algorithmic transparency documentation. German industrial clusters are piloting compliant architectures ahead of enforcement deadlines.
Subscription fatigue among enterprise buyers is fragmenting procurement into modular, best-of-breed purchases. Standalone predictive analytics modules displace full-suite competitive intelligence platforms in mid-market accounts. This pattern concentrates most visibly in United States pharmaceutical and technology verticals.
Global Competitive Intelligence Tools Market Segmentation
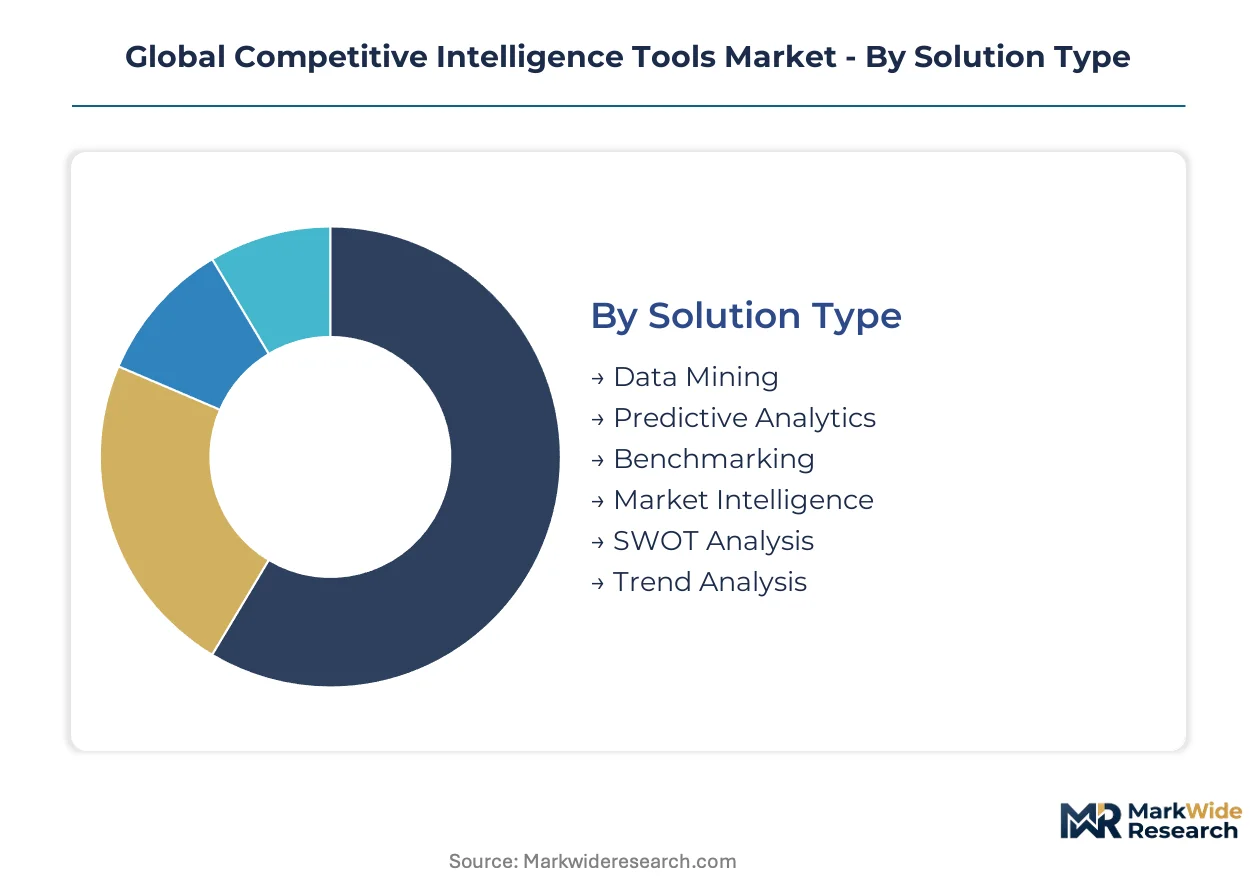
Segmentation in competitive intelligence tools reflects divergent buyer priorities across security postures, analytical sophistication, and workflow integration requirements. Procurement patterns cluster around deployment risk tolerance and the granularity of competitor signal detection needed.
Solution Type:
Buyer selection here hinges on the analytical maturity of the strategy function and the velocity of decision cycles required.
- Predictive Analytics:Machine learning models forecast competitor moves from pattern recognition in historical data. Pharmaceutical pipeline teams in the United States deploy these modules to anticipate rival FDA filing timelines. The steepest expansion trajectory in this category reflects enterprise demand for anticipatory rather than reactive positioning.
- SWOT Analysis:Automated synthesis of competitor strengths, weaknesses, opportunities, and threats from multi-source data aggregation. German industrial clusters around Frankfurt and Munich prioritize these capabilities for quarterly strategic reviews. Regulatory filing mandates from EMA and SEC standardize the input data streams these tools parse.
- Data Mining:Large-scale extraction and structuring of unstructured competitor signals from web, regulatory, and proprietary sources.
- Benchmarking:Comparative performance measurement against peer sets using standardized operational and financial metrics.
- Market Intelligence:Broad-scope monitoring of industry structure, share shifts, and macro positioning trends.
- Trend Analysis:Time-series detection of emerging patterns in competitor behavior and market evolution.
Predictive Analytics leads on scale; SWOT Analysis leads on momentum.
Deployment Mode:
Security certification requirements and data residency constraints determine architecture choice more than cost considerations alone.
- Cloud-Based:Elastic compute infrastructure enabling auto-scaling for sentiment analysis and large-scale trend detection workloads. Consulting firms in Frankfurt and Munich favor this mode for variable project-based demand. GDPR cross-border transfer restrictions elevate compliance architecture costs for multi-jurisdictional deployments.
- On-Premise:Air-gapped installations within controlled infrastructure preventing data egress to external environments. Financial analyst environments in the United States mandate these configurations for benchmarked datasets. Margin compression for vendors results from inability to monetize through SaaS recurring revenue models.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud elasticity for non-critical workloads.
- SaaS:Fully managed multi-tenant platforms with standardized feature sets and rapid deployment timelines.
- Private Cloud:Single-tenant dedicated infrastructure combining control with outsourced maintenance.
Cloud-Based captures the largest installed base; Hybrid is gaining share fastest among regulated enterprises.
End User:
Procurement authority and use case specificity vary sharply across these buyer types, shaping product packaging and sales motion design.
- Consulting Firms:Project-based deployments requiring rapid reconfiguration for diverse client competitive contexts. Frankfurt and Munich-based strategy consultancies drive enterprise procurement of benchmarking modules. Cloud elasticity supports variable compute demands across concurrent engagements.
- Business Enterprises:In-house strategy functions seeking persistent competitor monitoring integrated with CRM and ERP workflows. Pharmaceutical companies in the United States expand adoption of pipeline tracking platforms. Legacy system integration requirements extend deployment timelines and elevate professional services dependency.
- Market Research Agencies:Syndicated and custom competitive intelligence production for external client delivery.
- Technology Providers:Product strategy teams monitoring rival feature releases and pricing movements.
- Financial Analysts:Investment research workflows requiring real-time signal detection for algorithmic trading desks.
Consulting Firms dominate current revenue; Business Enterprises are expanding most quickly as in-house capabilities mature.
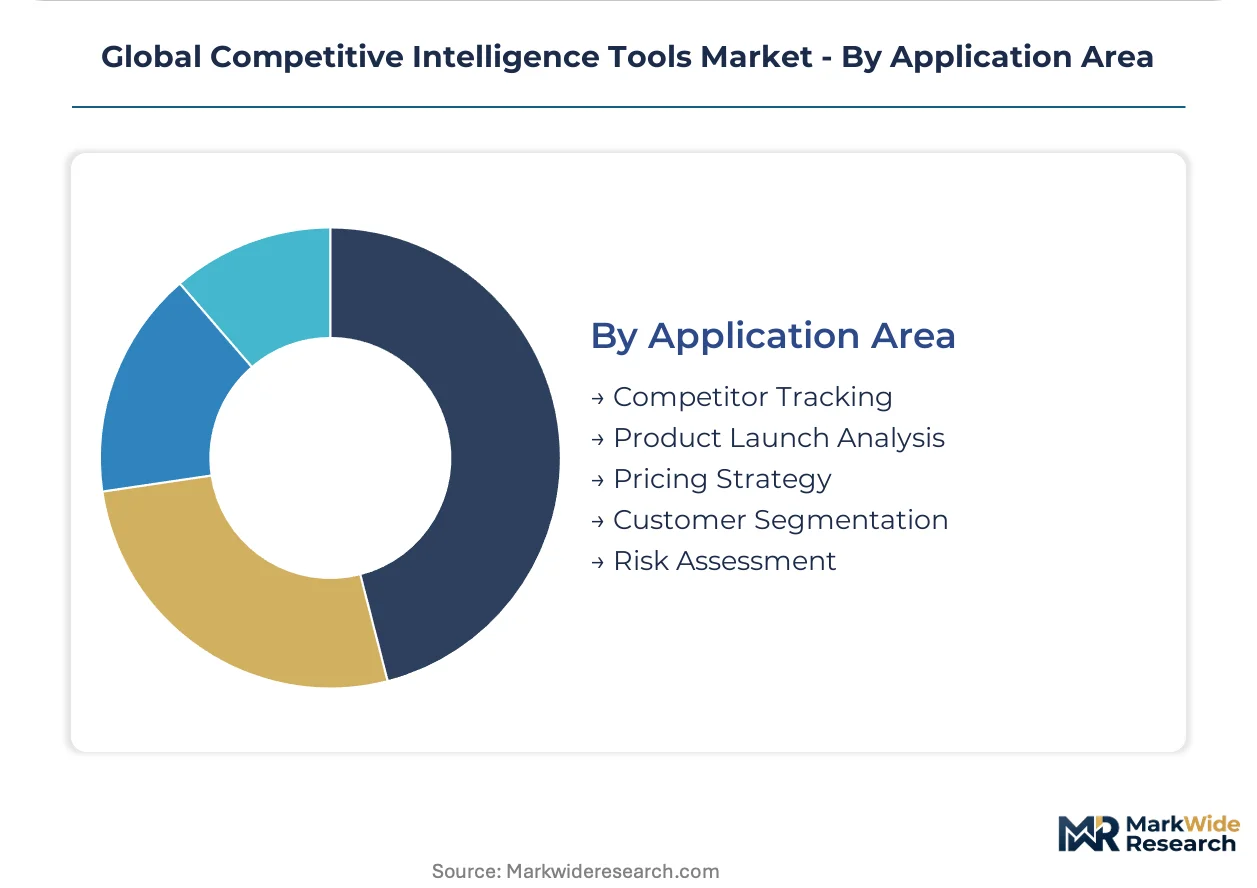
Application Area:
Functional use case determines data source requirements, alert latency specifications, and integration depth with adjacent systems.
- Competitor Tracking:Persistent monitoring of rival pricing, product launches, and market positioning shifts through automated web surveillance. Real-time alerting infrastructure with sub-second query response times commands premium pricing tiers. EU AI Act compliance obligations are restructuring vendor architectures for automated profiling workflows.
- Pricing Strategy:Dynamic analysis of competitor price movements and promotional patterns to inform revenue optimization. Mid-market SaaS vendors adopt self-refreshing competitive positioning documents fastest. Subscription fatigue is fragmenting procurement into modular best-of-breed purchases.
- Product Launch Analysis:Systematic tracking of rival go-to-market timing, messaging, and channel strategies.
- Customer Segmentation:Competitive benchmarking of target account profiles and penetration strategies.
- Risk Assessment:Evaluation of competitor financial health, litigation exposure, and supply chain vulnerabilities.
Competitor Tracking anchors the largest deployment base; Pricing Strategy is climbing the fastest as dynamic repricing becomes standard practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineering talent pools in the United States, Germany, and India anchor competitive intelligence platform development. These concentrations shape where vendors architect compliance-ready systems and where enterprise procurement authority concentrates.
United States
Pharmaceutical pipeline teams and algorithmic trading desks drive demand for predictive analytics modules. SEC EDGAR filing mandates standardize the regulatory data streams these platforms ingest. Boston and San Francisco Bay Area clusters host the densest concentrations of NLP engineering talent tuning competitor signal classification models.
Germany
Industrial manufacturing headquarters in Frankfurt and Munich require SWOT analysis automation for quarterly strategic reviews. EU AI Act risk classifications force vendors to demonstrate auditability in automated competitor profiling workflows. Baden-Württemberg engineering clusters pilot compliant architectures ahead of enforcement deadlines.
United Kingdom
London-based consulting firms and financial analyst environments sustain demand for real-time alerting infrastructure. GDPR cross-border transfer restrictions elevate compliance architecture costs for multi-jurisdictional deployments. The Square Mile and Canary Wharf trading floors command sub-second query response specifications.
India
PLI scheme incentives for electronics and pharmaceuticals generate facility investment data that local platforms monetize. CDSCO disclosure timelines create structured feeds for competitor pipeline tracking. Bengaluru and Hyderabad technology corridors concentrate SaaS engineering talent for cloud-native competitive intelligence development.
Japan
METI industrial policy frameworks encourage manufacturing enterprises to adopt predictive competitor positioning systems. PMDA pharmaceutical disclosure requirements standardize rival drug development timeline data. Tokyo and Osaka metropolitan areas concentrate enterprise procurement authority for benchmarking and trend analysis solutions.
Global Competitive Intelligence Tools Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and analytical sophistication tiers. The vendor base organizes around three strategic archetypes: real-time monitoring platforms, NLP-powered research workflows, and automated battlecard generators. Consolidation pressure intensifies as subscription fatigue fragments procurement into modular best-of-breed purchases. Dominant competitive moves include portfolio diversification into adjacent workflow automation and strategic partnerships with CRM and ERP incumbents.
Within the automated battlecard generation tier, Kompyte occupies a position serving mid-market SaaS vendor workflows. Crayon exemplifies real-time competitor tracking specialization through persistent web monitoring infrastructure. AlphaSense anchors the institutional research workflow segment with proprietary natural language processing applied to earnings transcripts and regulatory filings.
| Leading Market Players |
|---|
| Kompyte |
| ZoomInfo |
| Crayon |
| Similarweb |
| Semrush |
| Klue |
| Contify |
| Valona Intelligence |
| AlphaSense |
| Others |
Supply & Pricing Matrix
Generative model integration into competitive intelligence platforms compresses feature development cycles while concentrating engineering talent in United States, Germany, and India technology corridors. This dual effect simultaneously reduces marginal delivery costs for cloud-native vendors and elevates compensation premiums for machine learning specialists, reshaping how procurement economics distribute across deployment modes.
Pricing Analysis
Full-suite competitive intelligence platforms face unbundling pressure as subscription fatigue drives mid-market buyers toward modular predictive analytics and SWOT automation modules. SaaS-tiered pricing stratifies across premium, standard, and economy levels based on query response latency specifications and data source breadth. Cost compression in the standard tier intensifies because generative capabilities commoditize battlecard generation. Consulting firms in Frankfurt and Munich exhibit the highest price sensitivity due to project-based procurement cycles, while algorithmic trading desks in London tolerate premium tiers for sub-second alerting infrastructure.
Supply Chain Analysis
Dual-sourcing requirements for NLP model training infrastructure compel competitive intelligence vendors to qualify multiple cloud compute providers across United States, Ireland, and Singapore data center regions. Proprietary model development draws from annotated earnings transcript repositories, regulatory filing databases, and web-scraped competitor signals. Single-source vulnerability concentrates in specialized machine learning engineering talent pools, particularly for domain-specific classification tuning. Distribution runs through direct enterprise sales teams for on-premise deployments and self-service marketplaces for cloud-native SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Competitive Intelligence Tools Market compounds steadily as regulatory disclosure mandates from FDA, EMA, and SEC continuously expand structured data volumes available for platform ingestion. This institutional data growth provides predictable demand tailwinds regardless of macroeconomic cyclicality.
For Market Incumbents: Acquire specialized NLP engineering teams to defend against generative model commoditization of basic competitive monitoring. Consolidate position through backward integration into proprietary data source relationships, particularly around SEC EDGAR and EMA filing pipelines that emerging entrants cannot easily replicate. Secure ISO 27001 and SOC 2 Type II certifications ahead of EU AI Act enforcement to maintain pricing power in German industrial accounts.
For New Entrants and Emerging Players: Real-time alerting infrastructure with sub-second latency presents a technology-first wedge into algorithmic trading desk budgets that incumbent platforms underserve. Target India's PLI scheme-driven manufacturing intelligence segment, where facility investment data remains fragmented and local language processing creates natural moats. Deploy API-first architectures that embed directly into Salesforce and HubSpot workflows, bypassing lengthy procurement cycles for standalone platform evaluations.
For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific competitive intelligence specialists because GDPR compliance costs disproportionately burden sub-scale vendors and create forced seller dynamics. Focus acquisition screens on platforms with proven EMA or FDA data feed integrations and recurring revenue concentration above seventy percent. Watch CDSCO disclosure standardization in India as the inflection signal for emerging market platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM and ERP embedding reduces friction in pharmaceutical pipeline tracking workflows. |
| Acquisition of Specialist Firm | NLP engineering talent scarcity makes targeted team purchases more efficient than organic hiring. |
| Geographic Expansion | Frankfurt and Munich industrial clusters offer concentrated procurement authority for SWOT automation. |
| Product Launch | Generative battlecard modules capture mid-market SaaS vendor budgets faster than legacy suites. |
| Strategic Partnership | Cloud provider alliances secure reserved compute capacity for variable sentiment analysis workloads. |
Research Methodology
Bottom-up consulting firm and pharmaceutical enterprise demand modeling reconciled against top-down competitive intelligence vendor revenue tracking forms the analytical core of this study. Primary interviews with competitive intelligence platform product managers, strategy consulting partners, pharmaceutical pipeline analysts, and financial research technology procurement officers combined with secondary validation against SEC 10-K filings, EMA transparency reports, FDA disclosure databases, and hyperscaler AI infrastructure capex disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side capacity and pricing observations.
Historical trendline analysis of competitive intelligence software subscription revenue patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include solution type, deployment mode, end-user category, and application area, with additional granularity for regulatory data source integration depth. CAGRs derived from fitted growth curves incorporating EMA and SEC filing volume trajectories, cloud infrastructure cost decline curves, and EU AI Act compliance cost estimates as industry-specific forecast inputs.
The model holds under stable regulatory disclosure mandates and continued cloud infrastructure cost efficiency gains; deviation in GDPR enforcement intensity or EU AI Act risk classification interpretations would shift the outlook materially. Deviation in machine learning engineering talent availability or generative model capability commoditization velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Digital Notepad Market
Digital Solutions
IT Service Management Market
Digital Solutions
Game Engines Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Digital Onboarding Software Market