
 Global Document Scanning Services Market | 2026-2036
Global Document Scanning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Document Scanning Services Market Foresight
Reseller networks and direct enterprise sales channels are reshaping how document scanning services reach end buyers. HabileData leverages offshore delivery centers to compete on cost for bulk scanning contracts. TRANSFORM Solutions anchors its position through specialized indexing workflows for legal and financial clients. TECHSPEED INC differentiates by controlling quality certification processes across its North American operations.
Document scanning services encompass the digitization of physical records through optical character recognition, high-resolution image capture, and metadata tagging to create searchable electronic archives. Resolution thresholds of 300-600 DPI and color-depth specifications determine output fidelity for compliance-ready digital files. Bulk scanning and data extraction segments lead current revenue generation, while cloud-based delivery models represent the fastest-growing structural category as enterprises abandon capital-intensive on-premise infrastructure. Managed services capture concentrated margin pools through multi-year archival contracts with government agencies and healthcare systems.
FDA 21 CFR Part 11 requirements in the United States, GDPR data-processing standards in Europe, and India's IT Act digital signature provisions collectively elevate demand for audit-trail-compliant scanning workflows. ISO 27001 certification has become a baseline market-access requirement rather than a competitive differentiator for service providers. Stakeholders must monitor how generative AI integration into data extraction tools alters pricing power and workforce composition across delivery models.
Market Dynamics
Cloud-native archival architectures are compressing capital requirements for enterprise digitization, forcing service providers to abandon on-premise hardware models in favor of consumption-based revenue streams.
Growth Catalysts
- FDA 21 CFR Part 11:Healthcare providers in the United States face mandatory audit trails for electronic records, accelerating demand for compliant scanning workflows with embedded metadata verification.
- GDPR Article 17 (Right to Erasure):European enterprises require searchable digital archives to execute data-deletion requests efficiently, elevating indexing precision standards across contract specifications.
- Optical Character Recognition Advancement:Machine-learning-enhanced OCR engines now achieve sub-one-percent error rates on degraded paper sources, expanding addressable volume into historical backfile conversions previously deemed uneconomical.
Market Restraints
- High-Volume Scanner Hardware Concentration:Production-grade scanning equipment manufacturing concentrates among Japanese and German capital-goods suppliers, exposing service providers to extended lead times and currency-hedging costs.
- Skilled Technician Scarcity:Document preparation, quality assurance, and exception handling require trained operators; labor pools with archival-handling expertise remain geographically concentrated in South Asia and Eastern Europe.
- Legacy File Format Entrenchment:Government agencies and regulated industries mandate TIFF/PDF/A retention standards, constraining innovation toward modern container formats that offer superior compression and searchability.
Strategic Opportunities
- India's Digital India Initiative:State-level land-record digitization programs and court-backlog clearance projects create multi-year procurement pipelines for bulk scanning vendors with ISO 27001 certification.
- Generative AI Integration:Convergence of large language models with document extraction tools enables automated entity recognition and relationship mapping, opening premium service tiers for legal-discovery and due-diligence applications.
- Subscription Archival Models:Managed-service contracts with per-page monthly storage fees displace one-time digitization revenue, improving customer lifetime value and reducing competitive pressure on upfront project pricing.
Industry Challenges
- ISO 27001 Certification Timeline:Information-security accreditation requires 6-12 months of documented controls implementation, delaying market entry for new entrants targeting healthcare and financial services verticals.
- Legacy ECM Integration Complexity:Enterprise content management systems from the 2000s lack modern API architectures, forcing custom middleware development that erodes margin on fixed-price scanning contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Document Scanning Services Market |
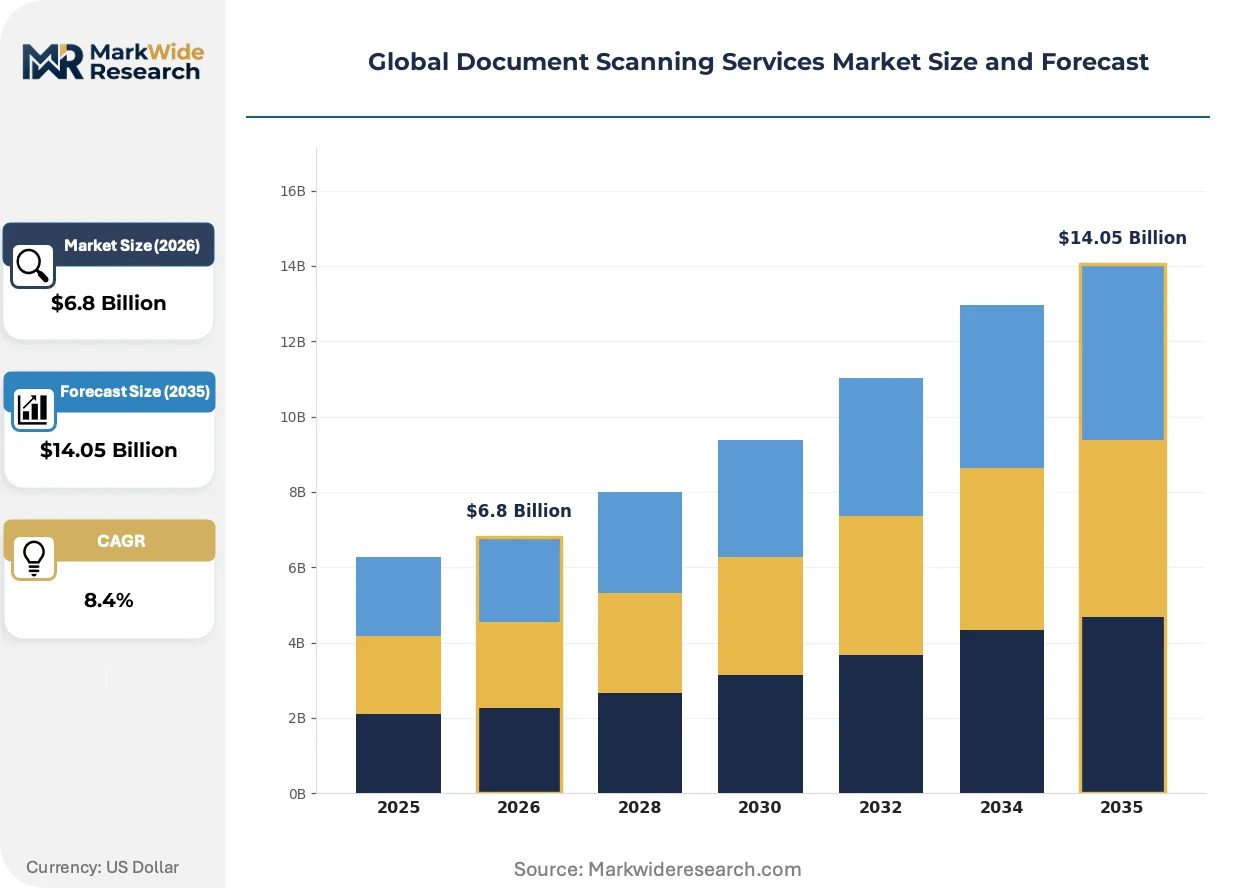
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bulk Scanning, Indexing, Data Extraction, Conversion Services, Archival Solutions End User: Legal Firms, Educational Institutions, Government Agencies, Financial Institutions, Real Estate Offices Application: Record Management, Compliance Monitoring, Digital Archiving, Workflow Automation, Content Management Delivery Model: On-premise, Cloud-based, Hybrid Solutions, Managed Services, Self-service Portals |
| Companies Covered | HabileData, TRANSFORM Solutions, TECHSPEED INC, Mountain States Imaging, Uniquesdata, Tinkogroup, DIGI-TEXX VIETNAM, eRecordsUSA, Strong Vision Data Processing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Document Scanning Services Market Shifts & Advancements
Artificial intelligence is compressing the value chain between image capture and structured data output, collapsing traditional distinctions between scanning, extraction, and analytics services.
Intelligent document processing platforms combining computer vision with natural language understanding are rendering obsolete manual indexing workflows that previously consumed sixty percent of project labor hours. Pharmaceutical manufacturers and insurance underwriters in Germany and the United States are deploying these systems for adverse-event report processing and claims adjudication. The structural consequence is margin compression for providers dependent on offshore labor arbitrage for data-entry tasks.
The EU AI Act's risk-based classification framework imposes documentation and human-oversight requirements on automated decision systems processing personal data. Scanning services that feed directly into credit-scoring, hiring, or medical-diagnosis workflows now face conformity-assessment obligations previously reserved for high-risk medical devices. French and Dutch service providers are restructuring delivery models to insert human-in-the-loop verification steps for sensitive document categories.
Enterprise buyers are consolidating vendor relationships under master service agreements that bundle digitization, hosting, and destruction certificates into single-source accountability. This pattern displaces fragmented procurement across departmental scanning budgets that characterized the 2015-2020 period. The concentration is most visible among United Kingdom National Health Service trusts and United States hospital systems pursuing supply-base rationalization initiatives.
Global Document Scanning Services Market Segmentation
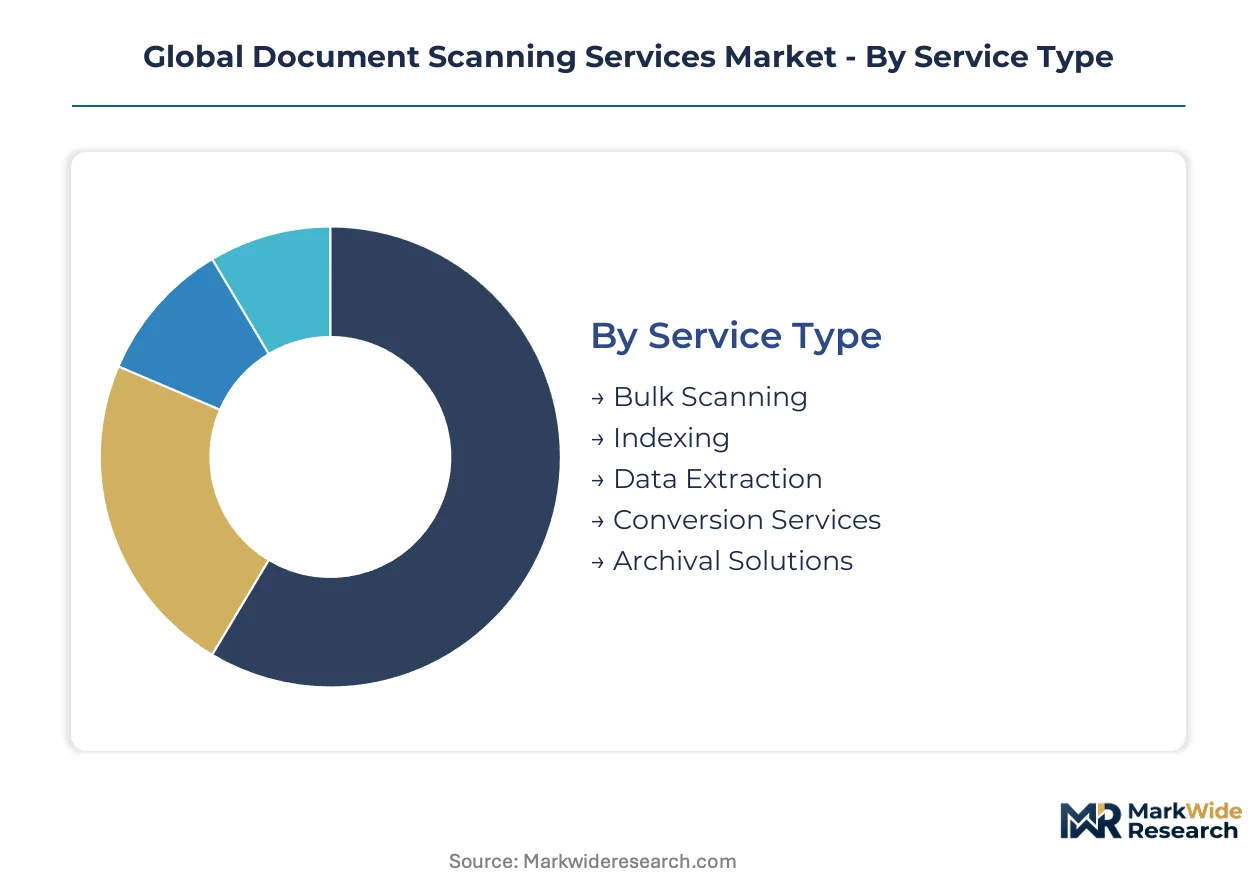
Service delivery models and end-user requirements fragment the document scanning services market into distinct operational configurations. Each segment carries unique margin profiles, certification thresholds, and technology integration demands that shape vendor specialization strategies.
Service Type:
Bulk scanning contracts turn over fastest with project-based procurement cycles, while archival solutions lock in decade-long recurring revenue streams.
- Bulk Scanning:High-volume capture of backfile documents at 300-600 DPI resolution with automated feed mechanisms. Healthcare systems in the United States deploy this for patient-chart conversions under FDA 21 CFR Part 11 audit-trail requirements. Bulk scanning anchors the volume base while data extraction gains share at the steepest rate.
- Data Extraction:Machine-learning OCR engines convert scanned images into structured datasets with sub-one-percent error rates. Insurance underwriters in Germany leverage this for claims adjudication workflows demanding entity recognition and relationship mapping.
- Indexing:Metadata tagging creates searchable taxonomies for legal-discovery and compliance retrieval. GDPR Article 17 erasure requests drive precision standards for European enterprise contracts.
- Conversion Services:Format migration from legacy TIFF to PDF/A-3 or modern container standards. Government agencies mandate retention-compatible outputs that constrain innovation toward superior compression formats.
- Archival Solutions:Multi-year managed-service contracts with per-page monthly storage fees and certificate-of-destruction documentation. India's Digital India land-record digitization programs generate multi-year procurement pipelines for ISO 27001-certified providers.
Bulk scanning commands the highest project velocity while data extraction climbs fastest on AI-enhanced automation premiums.
End User:
Cost-tier stratification separates regulated verticals with mandatory certification budgets from price-sensitive sectors prioritizing per-page economics.
- Financial Institutions:Basel III operational-risk documentation and SEC record-retention rules mandate immutable audit trails. Swiss and Singaporean private banks drive demand for blockchain-verified scanning workflows with cryptographic hashing.
- Government Agencies:FOIA compliance and permanent-record statutes require tamper-evident digitization with chain-of-custody documentation. United States National Archives and Records Administration specifications influence procurement standards across federal, state, and municipal tiers.
- Legal Firms:E-discovery preparation and privilege-log generation depend on precise Bates numbering and redaction capabilities. London and New York litigation-support vendors compete on turnaround speed for deposition-document processing.
- Educational Institutions:Alumni-record preservation and research-archive accessibility drive modest-volume contracts with stretched procurement timelines. State-university systems in India and Brazil represent emerging volume pockets.
- Real Estate Offices:Title-deed digitization and lease-abstract extraction carry lower compliance burdens but higher price elasticity. Commercial brokerages in Dubai and Mumbai prioritize rapid cloud delivery over on-premise archival depth.
Financial institutions concentrate the premium tier while government agencies provide the most predictable procurement pipelines.
Application:
Volume concentration flows toward compliance-mandated use cases with non-negotiable retention periods versus discretionary workflow-optimization projects.
- Compliance Monitoring:Real-time scanning integration with GRC platforms flags regulatory deviations through automated policy checking. EU AI Act conformity assessments now extend to document-processing workflows feeding automated decision systems.
- Record Management:Systematic classification, retention-schedule enforcement, and legal-hold administration across enterprise content repositories. Japanese pharmaceutical manufacturers deploy this for PMDA pharmacovigilance documentation.
- Digital Archiving:Long-term preservation with format migration, integrity verification, and access-path maintenance. ISO 16363-certified trustworthy repositories command 40-60 percent pricing premiums over standard cloud storage.
- Workflow Automation:Straight-through processing from mailroom capture to ERP system posting without manual intervention. Accounts-payable departments in German automotive suppliers achieve 90 percent touchless invoice processing.
- Content Management:Integration with SharePoint, OpenText, or Hyland platforms for collaborative document access and version control. Legacy ECM systems from the 2000s force costly middleware development that erodes project margins.
Compliance monitoring absorbs the steepest investment growth while record management sustains the foundational revenue base.
Delivery Model:
Customer-type stratification separates capital-constrained mid-market buyers from enterprise procurement offices with multi-year managed-service appetite.
- Managed Services:Comprehensive SLAs covering digitization, hosting, disaster recovery, and destruction with single-source accountability. United Kingdom NHS trusts consolidate fragmented departmental budgets under master service agreements.
- Cloud-based:Consumption-priced storage with API-native integration and elastic compute for extraction workloads. French and Dutch providers restructure offerings to insert human-in-the-loop verification for EU AI Act high-risk document categories.
- Hybrid Solutions:Sensitive-document on-premise processing combined with non-critical archival in multi-tenant cloud. German Mittelstand manufacturers favor this for works-council data-localization requirements.
- On-premise:Capital-intensive scanner deployment with dedicated operator teams and local storage infrastructure. Japanese and German production-scanner hardware concentration exposes buyers to extended lead times and currency-hedging costs.
- Self-service Portals:Browser-based upload with automated quality checking and downloadable output for low-volume episodic users. Small law practices in India and South Africa adopt this for ad-hoc litigation-preparation needs.
Managed services capture the most concentrated margin pools while cloud-based delivery expands most quickly among digital-native enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 requirements in the United States anchor compliance-driven digitization demand, while GDPR Article 17 and the EU AI Act reshape European procurement specifications. Procurement patterns concentrate in jurisdictions with mature regulatory frameworks and legacy paper backlogs.
United States
Healthcare systems and pharmaceutical manufacturers drive volume under FDA 21 CFR Part 11 audit-trail mandates. The SEC and IRS impose record-retention standards that elevate indexing precision requirements. Hospital networks in Texas and California consolidate fragmented departmental budgets under master service agreements with single-source accountability.
Germany
Automotive suppliers and Mittelstand manufacturers deploy straight-through processing for accounts-payable automation. The country's national data protection authority enforces GDPR Article 17 erasure protocols that demand searchable digital archives. Industrial clusters in Bavaria and Baden-Württemberg favor hybrid delivery models satisfying works-council data-localization requirements.
India
State-level land-record digitization and court-backlog clearance programs generate multi-year procurement pipelines. The national IT Act digital signature provisions and ISO 27001 certification requirements filter vendor eligibility. Service delivery centers in Maharashtra and Karnataka leverage skilled technician pools for bulk scanning contracts.
United Kingdom
National Health Service trusts pursue supply-base rationalization through consolidated master service agreements. The Information Commissioner's Office enforces GDPR compliance across public-sector digitization tenders. London litigation-support vendors compete on turnaround speed for e-discovery document processing.
France
CNIL oversight and EU AI Act high-risk system classifications impose human-in-the-loop verification requirements. Banking and insurance sectors under ACPR supervision demand immutable audit trails for credit-scoring workflows. Paris-based providers restructure delivery models to insert manual verification steps for sensitive document categories.
Global Document Scanning Services Market Competitive Landscape
Offshore delivery specialists and quality-certified regional operators split the market into distinct competitive tiers. Vendor concentration remains moderate, with no single provider commanding dominant share across service categories. Three archetypes define competitive positioning: labor-arbitrage offshore processors, compliance-focused regional specialists, and technology-integrated platform operators. Geographic expansion through delivery center establishment and strategic partnerships with enterprise content management vendors represent the dominant competitive moves.
Within the offshore tier, HabileData and Uniquesdata exemplify cost-competitive positioning for bulk scanning contracts. TECHSPEED INC anchors quality-certified North American operations, while TRANSFORM Solutions occupies a position indexing workflows for legal and financial verticals. DIGI-TEXX VIETNAM and Tinkogroup represent Southeast Asian delivery center strategies. Mountain States Imaging and eRecordsUSA sit within regional specialist archetypes serving compliance-intensive domestic clients.
| Leading Market Players |
|---|
| HabileData |
| TRANSFORM Solutions |
| TECHSPEED INC |
| Mountain States Imaging |
| Uniquesdata |
| Tinkogroup |
| DIGI-TEXX VIETNAM |
| eRecordsUSA |
| Strong Vision Data Processing |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese and German production-scanner manufacturing is extending equipment lead times and hardening pricing power for capital-goods suppliers, while service providers pass through currency-hedging costs and scarcity premiums to enterprise buyers locked into compliance-mandated digitization timelines.
Pricing Analysis
Per-page spreads between North American and South Asian delivery centers span three-to-one ratios on comparable bulk-scanning specifications, with ISO 27001 certification premiums and FDA 21 CFR Part 11 audit-trail bundling separating premium tiers from commodity project pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance grade, geographic labor arbitrage, and after-sales archival depth. Cost compression in offshore labor-dependent tiers is intensifying because intelligent document processing platforms collapse manual indexing workflows. Government agencies and regulated healthcare systems exhibit lowest price sensitivity, while commercial real estate brokerages and small educational institutions prioritize per-page economics over certification depth.
Supply Chain Analysis
Production-grade scanning hardware feeds from concentrated manufacturing bases in Japan, Germany, and Taiwan, with high-volume feed mechanisms, precision optics, and embedded firmware anchoring equipment dependencies. Service delivery draws from skilled technician pools concentrated in India, Vietnam, and Eastern Europe for document preparation and quality-assurance operations. Single-source vulnerability in Japanese capital-goods suppliers exposes providers to extended lead times and yen-dollar volatility. Distribution runs through direct enterprise sales, reseller networks, and cloud-native API integrations reaching end buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The document scanning services market is recovering from pandemic-era project deferrals as healthcare systems and government agencies clear digitization backlogs accumulated across compliance-mandated conversion timelines.
For Market Incumbents: Harden defensive positions by deepening ISO 27001 certification moats and securing multi-year archival contracts with NHS trusts and United States hospital systems before generative AI entrants erode indexing margins. Control quality certification processes across North American operations to differentiate from offshore labor-arbitrage competitors. Prioritize backward integration into cloud-native archival infrastructure to capture recurring revenue streams displacing one-time digitization projects. For New Entrants and Emerging Players: Brazil's state-university systems and South Africa's small law practices represent underpenetrated volume pockets where self-service portal adoption lags comparable markets. Target India's court-backlog clearance programs with rapid-deployment bulk-scanning capabilities undercutting established ISO 27001-certified providers on project timelines. Pursue partnership-based go-to-market models with legacy ECM vendors lacking modern API architectures. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-focused regional specialists with entrenched healthcare and financial services relationships rather than undifferentiated offshore labor processors facing margin compression from AI-enhanced extraction tools. Long-term viability rests on recurring revenue share under managed-service contracts with per-page monthly storage fees. Watch for EU AI Act conformity-assessment obligations triggering restructuring costs among automated decision-system providers as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Baseline market-access requirement for healthcare and financial services procurement filters. |
| Generative AI Platform Integration | Automated entity recognition and relationship mapping opens premium legal-discovery service tiers. |
| Cloud-Native Archival Migration | Consumption-based revenue streams displace capital-intensive on-premise hardware deployments. |
| Master Service Agreement Consolidation | United Kingdom NHS trusts and United States hospital systems rationalize fragmented vendor relationships. |
| India Delivery Center Expansion | Digital India land-record digitization programs generate multi-year procurement pipelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, GDPR regulatory filings, and ISO certification databases, combining structured interviews with healthcare compliance officers, legal-discovery operations managers, government procurement leads, and document scanning service executives with bottom-up and top-down triangulation across service-type and delivery-model segmentation.
Forecast inputs include resolution-threshold specifications, OCR error-rate improvements, cloud-storage consumption patterns, and regulatory compliance timeline accelerations across the analysis window. Segmentation dimensions modeled encompass service type, end-user vertical, application use case, and delivery model. CAGRs derive from volume projections reconciled against value-chain margin compression from AI-enhanced automation.
Practitioners should monitor EU AI Act conformity-assessment rollout and generative AI pricing-power erosion for early signals requiring forecast revision. Cross-checking against National Archives and Records Administration procurement disclosures and NHS supply-base rationalization announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Assurance Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Smart Signage Market
Digital Solutions
Digital Assistant Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Global Inventory Optimization Software Market