
 Backend-As-A-Service Market | 2026-2036
Backend-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Backend-As-A-Service Market Analysis
ISO 27001 certification is rotating as the decisive qualification gate for enterprise procurement of Backend-as-a-Service platforms, filtering vendors on information security management before contract awards. Microsoft Corporation leverages its Azure ecosystem to anchor hybrid deployment contracts across regulated industries. Amazon Web Services sustains serverless computing leadership through Lambda integration with its broader cloud stack. Google differentiates on real-time synchronization capabilities for mobile and web applications.
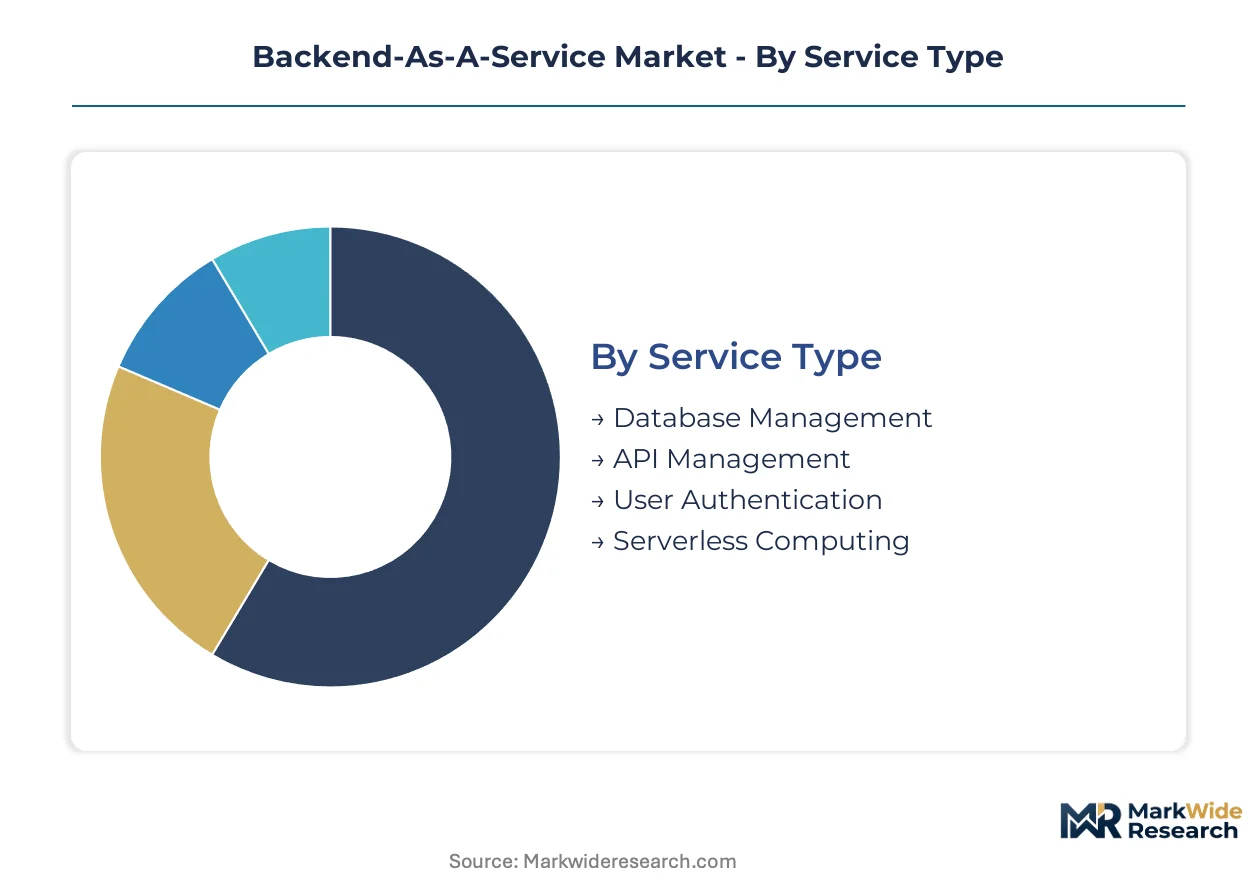
Backend-as-a-Service denotes a cloud computing model where third-party providers manage server infrastructure, databases, and application programming interfaces so developers can focus on frontend and business logic rather than backend operations. Providers typically deliver RESTful or GraphQL APIs with guaranteed uptime thresholds, automated scaling parameters, and pre-configured authentication protocols to accelerate application deployment timelines. Database Management and Serverless Computing command the largest service type revenue pools, while No-Code integration levels attract the fastest-growing developer cohort among startups and citizen developers. Public Cloud deployments dominate volume, though Hybrid Cloud configurations capture disproportionate margin from enterprises with data residency requirements.
FDA guidelines on software-as-a-medical-device, EU GDPR data localization mandates, and SEC cybersecurity disclosure rules for publicly traded firms collectively shape compliance architectures that BaaS vendors must embed. These frameworks elevate procurement scrutiny on audit trails, encryption standards, and cross-border data transfer mechanisms. Stakeholders should monitor how emerging AI governance requirements from the EU AI Act and analogous national frameworks will recertify acceptable risk thresholds for automated backend decision-making.
Market Dynamics
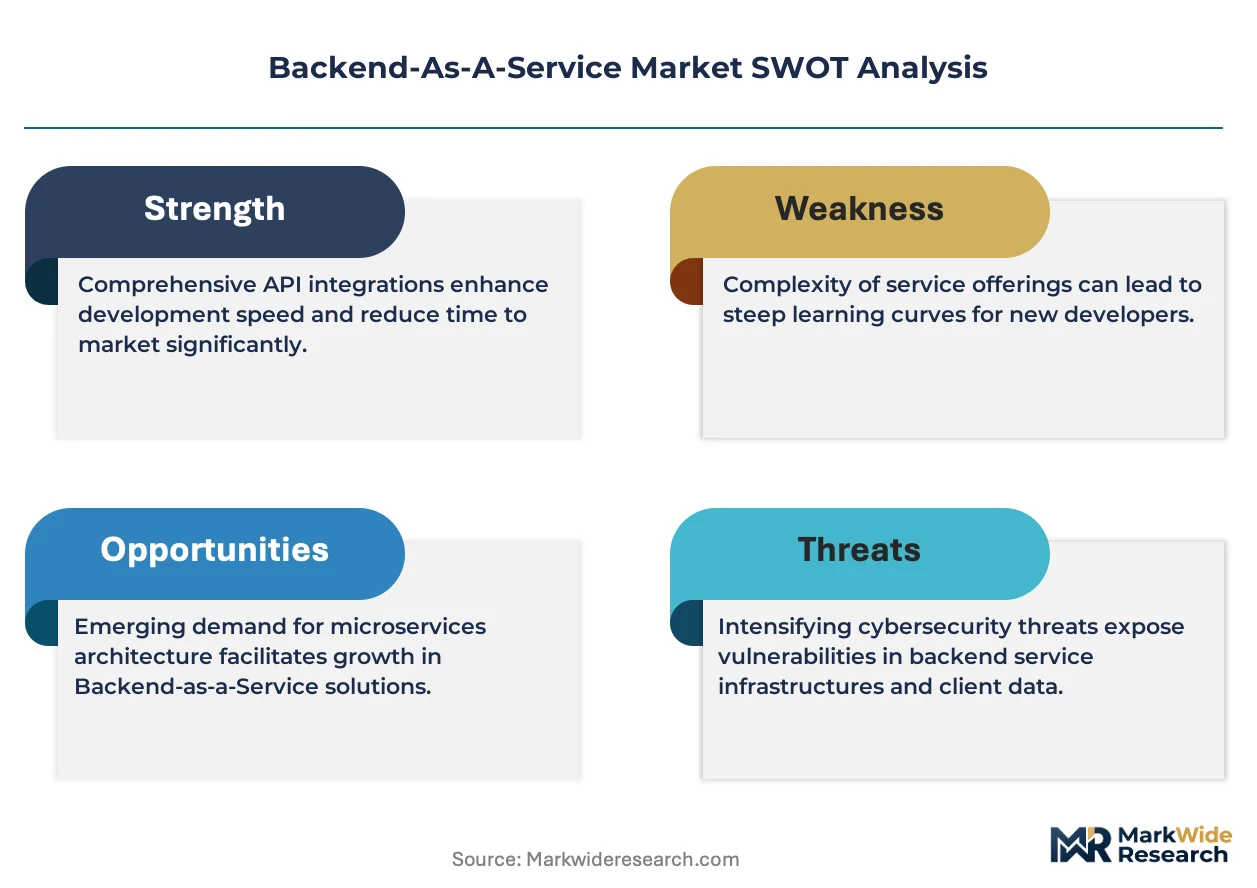
Serverless architecture adoption by mobile gaming studios is compressing deployment timelines and forcing traditional infrastructure vendors to reprice managed service contracts. The EU AI Act's risk classification framework for automated decision-making systems is recalibrating how BaaS providers architect audit trails and human oversight mechanisms for enterprise clients.
Growth Catalysts
- GDPR data localization mandates:European enterprises are migrating workloads to EU-sovereign BaaS instances to satisfy cross-border transfer restrictions, expanding addressable market for regional cloud providers.
- Real-time multiplayer gaming:San Francisco Bay Area startups building synchronous applications are consuming managed WebSocket infrastructure at scale, validating low-latency edge deployment models.
- No-code integration layers:Citizen developer platforms are abstracting database schemas into visual interfaces, accelerating backend provisioning for non-technical founders.
Market Restraints
- ISO 27001 certification costs:Mid-tier BaaS vendors face six-figure audit expenditures that compress margins before enterprise contract eligibility.
- Hyperscaler concentration:Amazon Web Services, Microsoft Azure, and Google Cloud Platform control serverless compute pricing benchmarks, limiting independent vendor differentiation.
- Lambda cold-start latency:Event-driven architectures incur 100-1000ms initialization penalties that disqualify providers from financial trading and telemetry applications.
Strategic Opportunities
- Hybrid cloud configurations:German automotive manufacturers with data residency requirements are procuring on-premise Kubernetes control planes with burst-to-cloud scaling.
- FDA software-as-a-medical-device pathways:Connected health startups require BaaS providers to pre-validate 21 CFR Part 11 audit trails, creating specialized compliance premiums.
- GraphQL-REST convergence:API gateway vendors are unifying query languages with automatic schema stitching, reducing frontend-backend contract friction.
Industry Challenges
- Distributed systems engineering talent:BaaS providers compete for Site Reliability Engineers capable of managing multi-region database replication and automated failover orchestration.
- SEC cybersecurity disclosure timelines:Publicly traded BaaS customers must report material incidents within four business days, compressing incident response contract terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backend-As-A-Service Market |
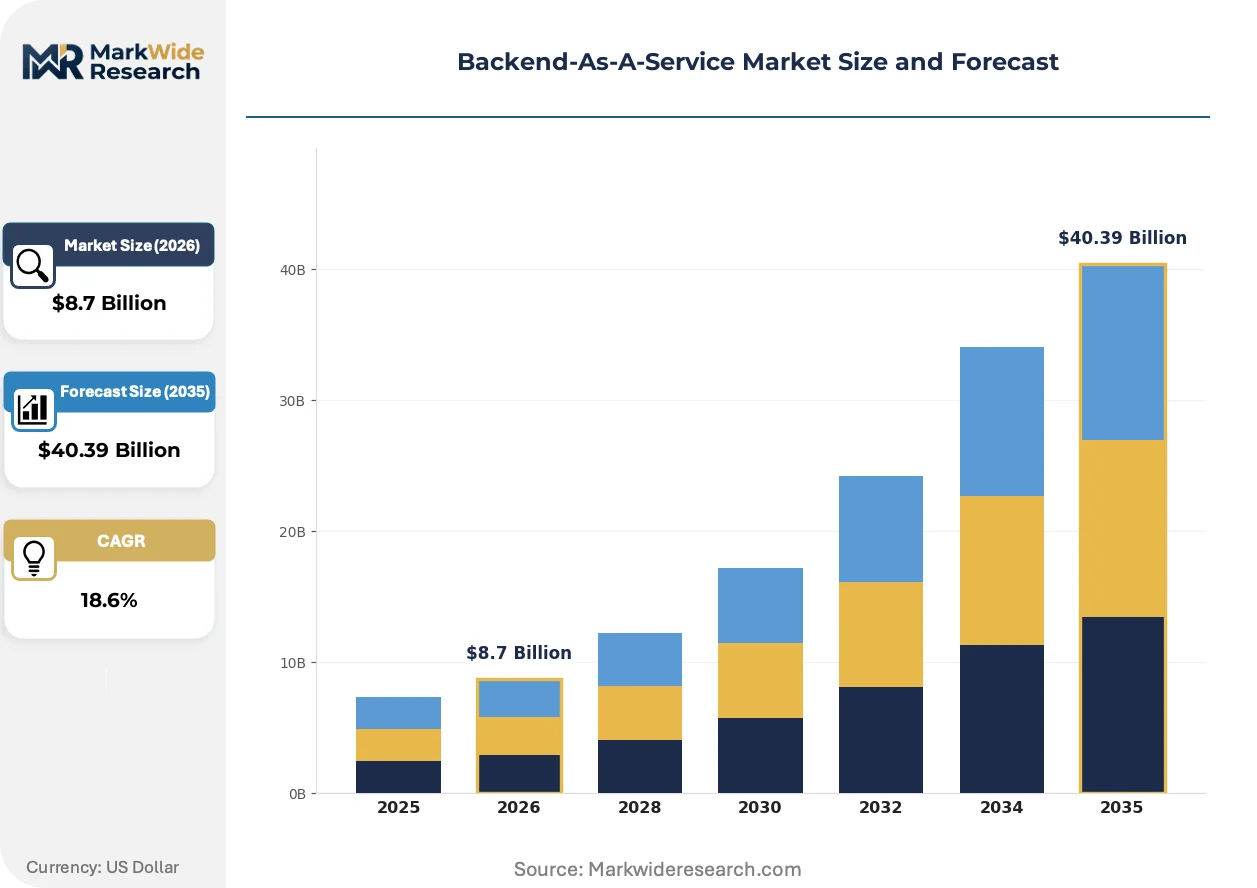
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Database Management, API Management, User Authentication, Serverless Computing Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Startups, SMEs, Enterprises, Developers Integration Level: Low-Code, No-Code, Full-Code, Custom Integrations |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google, IBM Corporation, Oracle Corporation, Firebase, Back4app, Rackspace Technology, Backendless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backend-As-A-Service Market Emerging Trajectories
Edge computing nodes are repositioning data processing topology away from centralized hyperscale regions toward metropolitan proximity zones. This architectural shift is redrawing competitive moats around latency performance rather than storage economics.
WebAssembly runtime modules are miniaturizing backend execution environments to sub-100KB footprints. Mobile gaming studios are embedding these modules into client-side prediction engines to mask network latency. The technology is miniaturizing the boundary between device and cloud compute, enabling frame-synchronized multiplayer experiences without dedicated game server infrastructure.
The EU AI Act's high-risk system obligations are mandating algorithmic impact assessments for BaaS platforms offering automated credit scoring or biometric processing. Providers must maintain technical documentation and human-in-the-loop override capabilities. European financial services and healthcare verticals are demanding contractual indemnification for conformity penalties, shifting liability allocation in master service agreements.
Consumption-based billing is displacing committed-use contracts among Series A-stage startups. Finance teams are prioritizing granular usage visibility over volume discounts. This preference is most pronounced in the United States, where venture-backed companies optimize runway visibility over three-year total cost of ownership calculations.
Backend-As-A-Service Market Segmentation
Backend-as-a-Service procurement patterns diverge sharply across organizational maturity and technical sophistication. Understanding these fault lines reveals where vendors must specialize versus where standardization wins.
Service Type:
Serverless Computing faces the most acute substitution pressure from container orchestration platforms and edge runtime modules that promise comparable abstraction without vendor lock-in.
- Database Management:Managed relational and NoSQL instances with automated backup, replication, and scaling policies. San Francisco Bay Area startups building real-time multiplayer applications consume PostgreSQL and Redis clusters at scale to support synchronous state synchronization.
- Serverless Computing:Event-driven execution environments that provision compute resources on demand without persistent server management. Mobile gaming studios leverage these functions to compress deployment timelines while offloading infrastructure overhead to managed providers.
- API Management:Gateway services handling rate limiting, authentication, and request routing across distributed microservices architectures.
- User Authentication:Pre-configured identity providers with OAuth, SAML, and biometric verification pipelines for rapid security implementation.
Database Management anchors the volume base while Serverless Computing gains share at the steepest rate.
Deployment Model:
Cost tiering separates commodity public instances from premium configurations that command 3-4x unit economics.
- Public Cloud:Multi-tenant infrastructure shared across customers with standardized SLAs and geographic redundancy. United States venture-backed startups prioritize consumption-based billing models over committed-use contracts to preserve runway visibility.
- Hybrid Cloud:Split architectures combining on-premise control planes with burst-to-cloud scaling for variable workloads. German automotive manufacturers with data residency requirements procure these configurations to satisfy EU GDPR localization mandates while maintaining elastic capacity.
- Private Cloud:Single-tenant environments with dedicated hardware isolation for regulated workloads.
- On-Premises:Fully self-managed installations within customer data centers with vendor support contracts.
Public Cloud dominates transaction volume while Hybrid Cloud expands most quickly among enterprise procurement pipelines.
End User:
Application complexity and compliance burden stratify sharply across organizational scale.
- Enterprises:Large organizations with procurement departments mandating ISO 27001 certification, audit trails, and contractual indemnification. These buyers filter vendors through information security management gates before contract awards and negotiate custom master service agreements.
- Startups:Early-stage companies prioritizing speed-to-market over long-term infrastructure control. San Francisco Bay Area synchronous application builders validate low-latency edge deployment models through aggressive managed WebSocket consumption.
- SMEs:Mid-sized businesses balancing customization needs against limited technical staffing.
- Developers:Individual practitioners and small teams selecting tools based on documentation quality and community ecosystem rather than procurement processes.
Enterprises anchor the volume base while Startups climb the fastest as venture funding concentrates in real-time application categories.
Integration Level:
Technical proficiency of the implementing team determines abstraction ceiling and customization depth.
- No-Code:Visual interfaces that abstract database schemas and API construction into drag-and-drop workflows. Citizen developer platforms accelerate backend provisioning for non-technical founders who lack dedicated infrastructure engineering resources.
- Full-Code:Complete programmatic control over backend logic, custom middleware, and proprietary data pipelines. Professional engineering teams at Series A-stage startups demand granular usage visibility and direct SDK access.
- Low-Code:Hybrid approaches with pre-built components extensible through limited scripting.
- Custom Integrations:Bespoke connector development for legacy systems and specialized third-party services.
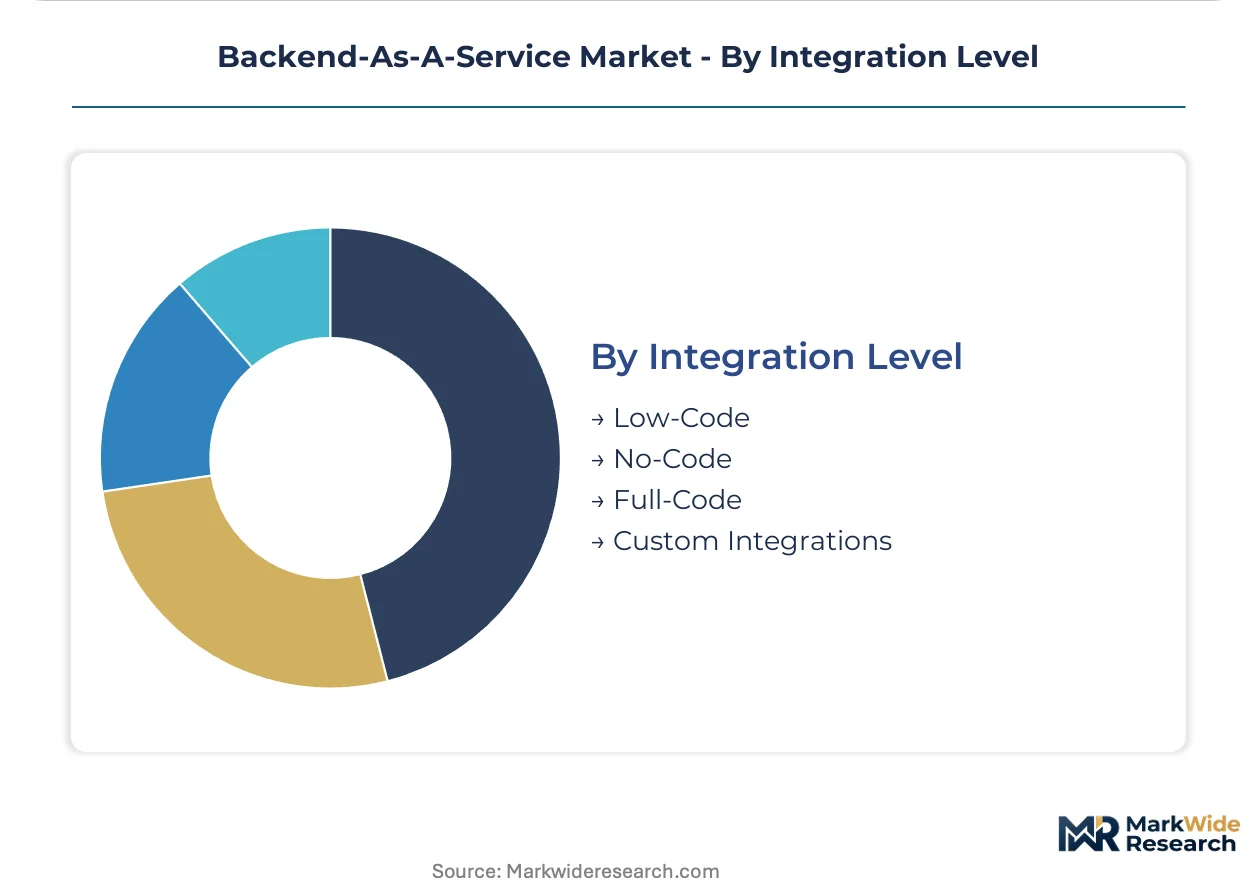
Full-Code retains the largest installed base while No-Code exhibits the steepest expansion trajectory among emerging founder demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables and the Amsterdam internet exchange anchor Europe's data sovereignty position, while submarine cables landing in California and Virginia underpin United States cloud infrastructure dominance.
United States
San Francisco Bay Area startups building real-time multiplayer applications consume managed WebSocket infrastructure at scale, validating low-latency edge deployment models. SEC cybersecurity disclosure rules for publicly traded firms compress incident response contract terms to four business days. Seattle and Northern Virginia data center clusters concentrate hyperscaler capacity expansion for serverless compute provisioning.
Germany
Automotive manufacturers with data residency requirements procure hybrid cloud configurations combining on-premise Kubernetes control planes with burst-to-cloud scaling. EU GDPR data localization mandates drive workload migration to EU-sovereign BaaS instances. Munich and Stuttgart industrial corridors anchor demand for ISO 27001-certified managed database services.
United Kingdom
London's fintech cluster demands GraphQL-REST convergence in API gateway services to reduce frontend-backend contract friction. Financial Conduct Authority operational resilience requirements elevate procurement scrutiny on audit trails and encryption standards. The Thames Valley technology corridor concentrates Series A-stage startups prioritizing consumption-based billing over committed-use contracts.
Japan
Tokyo-based mobile gaming studios embed WebAssembly runtime modules into client-side prediction engines to mask network latency. METI guidelines on data governance shape vendor selection criteria for automated backend decision-making systems. The Osaka-Kansai region hosts specialized compliance premiums for connected health applications requiring pre-validated audit trails.
India
Bengaluru's developer ecosystem drives No-code integration layer adoption among citizen developer platforms accelerating backend provisioning. RBI data localization directives for financial services expand addressable market for domestic cloud providers. Hyderabad and Pune technology parks concentrate distributed systems engineering talent for multi-region database replication services.
Backend-As-A-Service Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and latency performance, creating a tiered structure where hyperscaler scale meets boutique compliance expertise. Three strategic archetypes dominate: cloud-native platforms with serverless-first architectures, enterprise incumbents leveraging hybrid deployment credentials, and vertical specialists targeting regulated industries. Competitive moves concentrate on M&A for Kubernetes orchestration capabilities and strategic partnerships for edge node distribution.
Within the hyperscaler tier, Microsoft Corporation, Amazon Web Services, and Google occupy positions defined by ecosystem lock-in and geographic footprint breadth. Microsoft leverages its Azure ecosystem to anchor hybrid deployment contracts across regulated industries. Amazon Web Services sustains serverless computing leadership through Lambda integration with its broader cloud stack. Google differentiates on real-time synchronization capabilities for mobile and web applications.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Oracle Corporation |
| Firebase |
| Back4app |
| Rackspace Technology |
| Backendless |
| Others |
Supply Flow & Price Mechanics
Hyperscale capacity utilization above 85% in Northern Virginia and Seattle data center clusters compresses marginal costs for serverless compute, concentrating pricing power among AWS, Azure, and Google Cloud while forcing mid-tier vendors toward specialized compliance premiums. This scale asymmetry anchors price floors for commodity public cloud instances and expands spreads for ISO 27001-certified hybrid configurations.
Pricing Analysis
Volume-discount tiering structures separate committed-use contracts with 3-year terms from consumption-based billing preferred by Series A-stage startups. Price differentiation hinges on certification grade—ISO 27001 and SOC 2 Type II tiers command 40-60% premiums—and geographic delivery cost for EU-sovereign data residency. Pricing pressure stems from Lambda cold-start latency disqualifying providers from financial trading applications, forcing repricing of event-driven tiers. Early-stage startups exhibit highest price sensitivity, while German automotive manufacturers prioritize data residency over unit cost.
Supply Chain Analysis
Inventory lead times for GPU accelerators and high-bandwidth memory modules stretch 12-18 weeks, constraining edge node deployment velocity for real-time multiplayer infrastructure. Supply concentrates in Taiwan (semiconductor foundry), South Korea (memory fabrication), and the United States (hyperscale data center construction). Raw material dependencies include silicon wafers, rare earth elements for magnetics, and lithium-ion battery systems for backup power. Single-source vulnerability around TSMC advanced node production creates systemic risk. Distribution runs through direct hyperscaler marketplaces and regional systems integrators with Kubernetes certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container orchestration platforms and WebAssembly runtime modules threaten to displace serverless abstraction layers, compelling incumbents to defend through compliance depth and latency performance rather than price alone.
For Market Incumbents: Consolidate hybrid cloud credentials through on-premise Kubernetes control plane certifications for German automotive and EU financial services verticals. Deepen ISO 27001 audit trail automation to compress enterprise procurement cycles. Acquire edge computing node operators in Amsterdam and Frankfurt to defend against latency arbitrage by specialized entrants. For New Entrants and Emerging Players: Lead with EU-sovereign BaaS instances targeting GDPR data localization mandates underserved by hyperscaler standard offerings. Penetrate the FDA software-as-a-medical-device pathway for connected health startups requiring pre-validated 21 CFR Part 11 audit trails. Position through consumption-based billing transparency to capture Series A-stage startups abandoning committed-use contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists with embedded compliance workflows for regulated industries. Long-term viability rests on differentiation durability against hyperscaler price convergence. Target acquisition archetypes: Kubernetes orchestration specialists with automotive certifications and edge node operators in Tier 2 European markets. Monitor WebAssembly runtime adoption rates in Tokyo mobile gaming studios as inflection signal for serverless substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Certification | ISO 27001 and GDPR-compliant configurations capture German automotive procurement with data residency requirements. |
| Edge Node Expansion | Amsterdam and Frankfurt proximity zones reduce WebSocket latency for San Francisco Bay Area multiplayer startups. |
| FDA Compliance Pre-validation | 21 CFR Part 11 audit trail automation opens software-as-a-medical-device premiums in connected health. |
| WebAssembly Runtime Integration | Sub-100KB execution modules mask network latency for Tokyo mobile gaming studios. |
| Consumption-Based Billing Platform | Granular usage visibility attracts Series A-stage startups prioritizing runway over volume discounts. |
Methodological Framework
Initial hypotheses were tested against primary input from CTOs at San Francisco Bay Area multiplayer gaming startups, IT procurement officers at German automotive manufacturers, platform engineers at hyperscaler cloud providers, and regulatory affairs leads at connected health ventures, then refined through secondary validation against SEC cybersecurity disclosure filings, EU AI Act technical documentation, hyperscaler capex disclosures, and App Annie mobile infrastructure spend data. Bottom-up service type demand modeling and top-down cloud infrastructure investment flow analysis were triangulated to reconcile volume estimates.
Variance-decomposition across the projection horizon isolates growth contributions from serverless computing adoption, GDPR migration waves, and real-time application proliferation. Segmentation dimensions modeled include deployment model, organization maturity stage, integration complexity tier, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to technology adoption patterns and validated against hyperscaler revenue disclosures. Industry-specific forecast inputs include WebSocket connection density benchmarks and ISO 27001 certification velocity by vendor tier.
Forecasts assume regulatory continuity in EU AI Act implementation and SEC cybersecurity disclosure timelines; material policy shifts would require re-modeling. Model outputs reflect assumptions on serverless cold-start latency improvement trajectories and hyperscaler pricing discipline. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Webinar Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
HR Saas Market
Software & Services
PCB CAD Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Video Communications Software Market
Software & Services
Europe Printing Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global Chromatography Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Quality Management Software Market
Software & Services
Video Editing Software Market
Software & Services
Home Design Software Market