
 Online Dating Market | 2026-2036
Online Dating Market Size, Share, and Industry Trends Forecast 2026-2036
Online Dating Market Intelligence
Multi-source algorithm partnerships is shifting as platforms diversify their recommendation engines beyond single-vendor dependencies. Tinder leverages geographic dominance across North American and European urban centers. Bumble differentiates through women-first messaging architecture that sustains premium subscription rates. Match Group controls portfolio breadth across casual and commitment-oriented segments.
Online dating comprises digital platforms that algorithmically match users based on behavioral signals, stated preferences, and real-time interaction data, with core systems processing compatibility scores through machine learning pipelines trained on billions of swipe and message events. The primary commercial purpose is to monetize user attention and intent through tiered access to matching visibility, communication tools, and profile enhancement features. Mobile apps anchor revenue generation through in-app purchase flows and push-notification re-engagement mechanics. Subscription monetization captures the deepest user commitment, while freemium models occupy the broadest acquisition funnel. Video dating represents the fastest-growing platform type as synchronous interaction reduces catfishing friction and accelerates trust formation.
The US Federal Trade Commission scrutinizes subscription billing practices and dark-pattern interfaces that obscure cancellation pathways. GDPR and the EU AI Act constrain how European platforms deploy automated decision-making for user ranking and content moderation. India's Digital Personal Data Protection Act introduces consent-layer requirements that reshape onboarding flows for entrants targeting that market. Stakeholders must monitor whether emerging biometric verification mandates and age-assurance regulations fragment product development across jurisdictions.
Market Dynamics
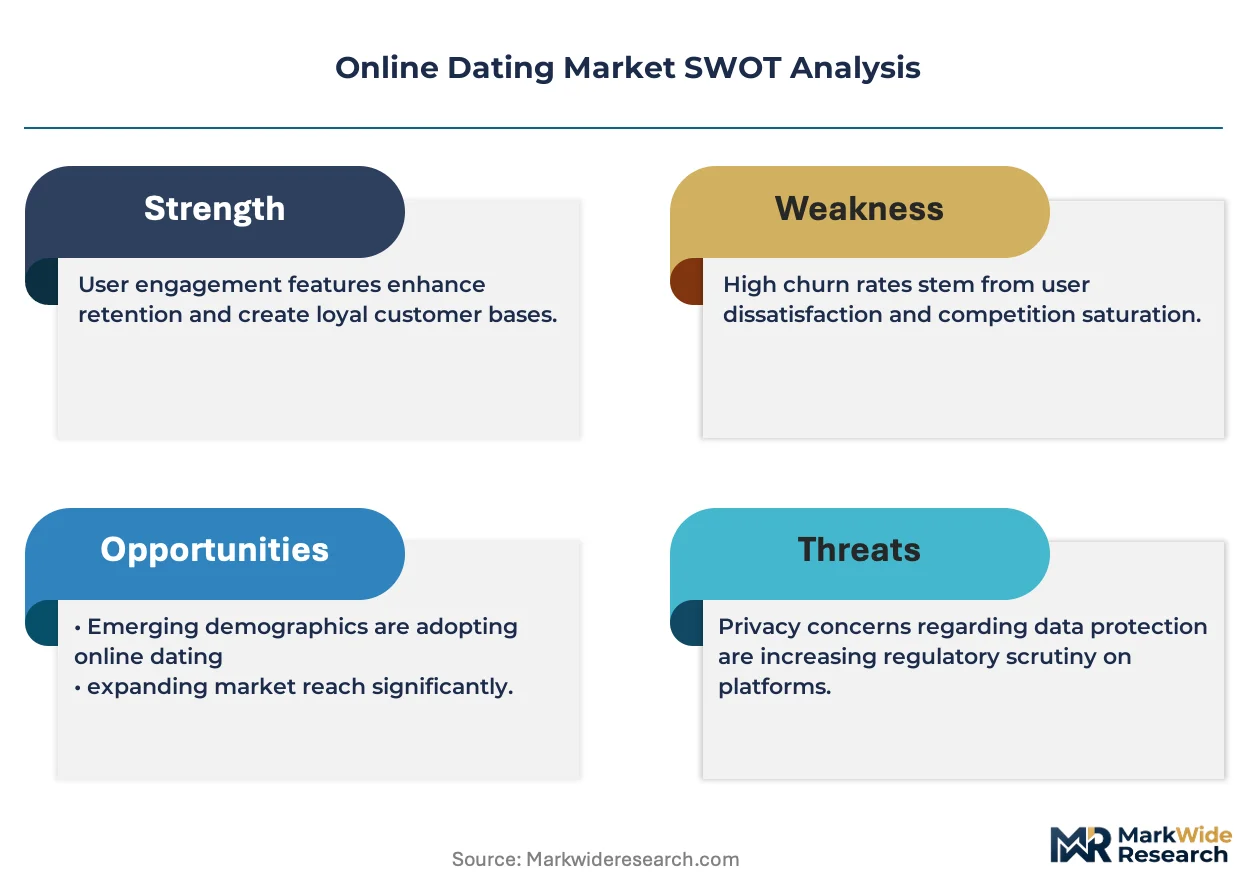
Algorithmic matching systems now face escalating pressure from biometric verification mandates and age-assurance regulations that fragment product development across jurisdictions. Platforms must rebuild core onboarding flows to satisfy divergent compliance requirements while preserving user acquisition velocity.
Growth Catalysts
- Smartphone penetration waves:India, Brazil, and Southeast Asian markets expand the addressable user base as mobile-first platforms capture younger demographics seeking casual connections.
- GDPR and evolving state privacy frameworks:Data handling requirements in Europe and the US reshape platform architecture, creating competitive moats for compliant operators.
- Video synchronous interaction:Real-time video dating reduces catfishing friction and accelerates trust formation, driving premium subscription conversion.
Market Restraints
- Regulatory fragmentation:India's Digital Personal Data Protection Act introduces consent-layer requirements that reshape onboarding flows for entrants targeting that market.
- Input cost volatility:Cloud compute and AI inference costs for real-time matching algorithms create margin pressure as user volumes scale.
- Substitution dynamics:Social audio platforms and interest-based community apps capture casual connection demand outside dedicated dating ecosystems.
Strategic Opportunities
- Underpenetrated demographics:Silver singles segments in Germany, Japan, and Australia show rising platform adoption with higher lifetime value profiles.
- Regulatory tailwinds:EU AI Act constraints on automated decision-making create openings for transparent, explainable matching systems that command premium positioning.
- Technology convergence:Integration of generative AI for conversation assistance and AR filters for virtual date environments differentiates user experience.
Industry Challenges
- Talent scarcity:Machine learning engineers with expertise in fairness-constrained recommendation systems command compensation premiums that strain R&D budgets.
- Compliance timeline compression:Biometric verification mandates in multiple jurisdictions require simultaneous infrastructure builds with uncertain implementation deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Dating Market |
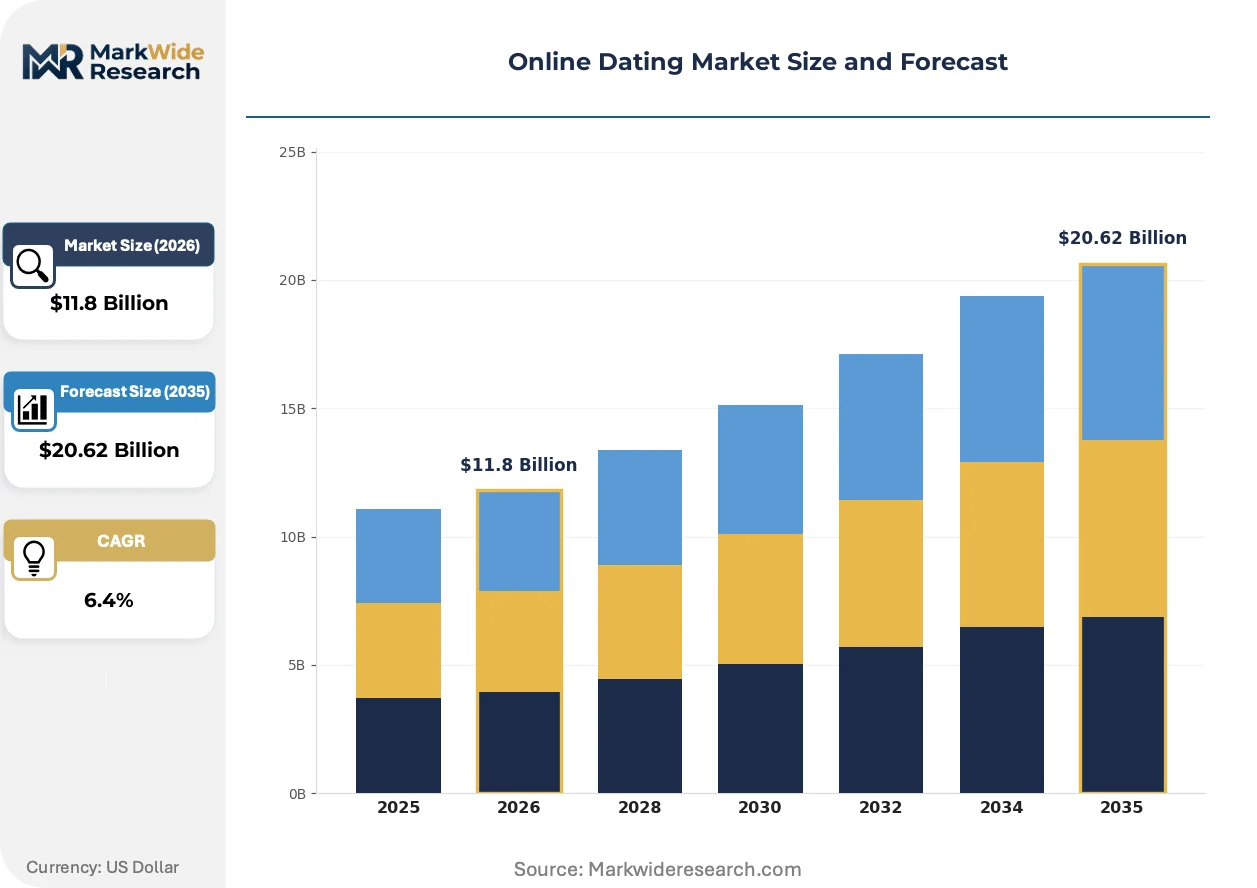
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile Apps, Desktop Websites, Social Media Integrations, Video Dating, Virtual Reality Experiences Relationship Goals: Casual Dating, Long-Term Commitment, Friendship Building, Networking, Marriage Prospecting User Demographics: Singles, Divorced Individuals, Widowed Users, LGBTQ+ Community, Seniors Monetization Model: Subscription, Freemium, Pay-per-Message, Advertising, Premium Features |
| Companies Covered | Hinge, OkCupid, Match Group, Grindr, eHarmony, Meta Platforms, Tinder, Plenty of Fish, Bumble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Dating Market Strategic Shifts & Innovations
Real-time synchronous formats and AI-augmented interaction tools are redefining how platforms capture user attention and convert engagement into subscription revenue. The competitive frontier now centers on reducing friction between discovery and meaningful connection.
Video dating infrastructure is expanding into the core product architecture of major platforms, replacing static photo galleries with short-form video profiles and live one-to-one streaming. Younger cohorts in urban India and Southeast Asia adopt these formats fastest, compressing the traditional messaging-to-meeting cycle from weeks to days. This shift is expanding into premium tier offerings that bundle virtual date scheduling and integrated payment flows.
EU AI Act provisions on automated decision-making are forcing platforms to disclose ranking factors and provide human review options for content moderation appeals. European operators must retrain machine learning pipelines to satisfy transparency requirements while maintaining matching efficacy. Video-first platforms face the steepest compliance costs as real-time content moderation systems require architectural overhaul.
Buyer preferences are tilting toward outcome-based matching guarantees that refund subscriptions after defined periods without successful connections. Nordic and Dutch markets show strongest adoption of these risk-reversed pricing models, pressuring legacy subscription architectures. This behavioral pivot is expanding into corporate wellness channels where employers subsidize employee dating benefits as retention tools.
Online Dating Market Segmentation
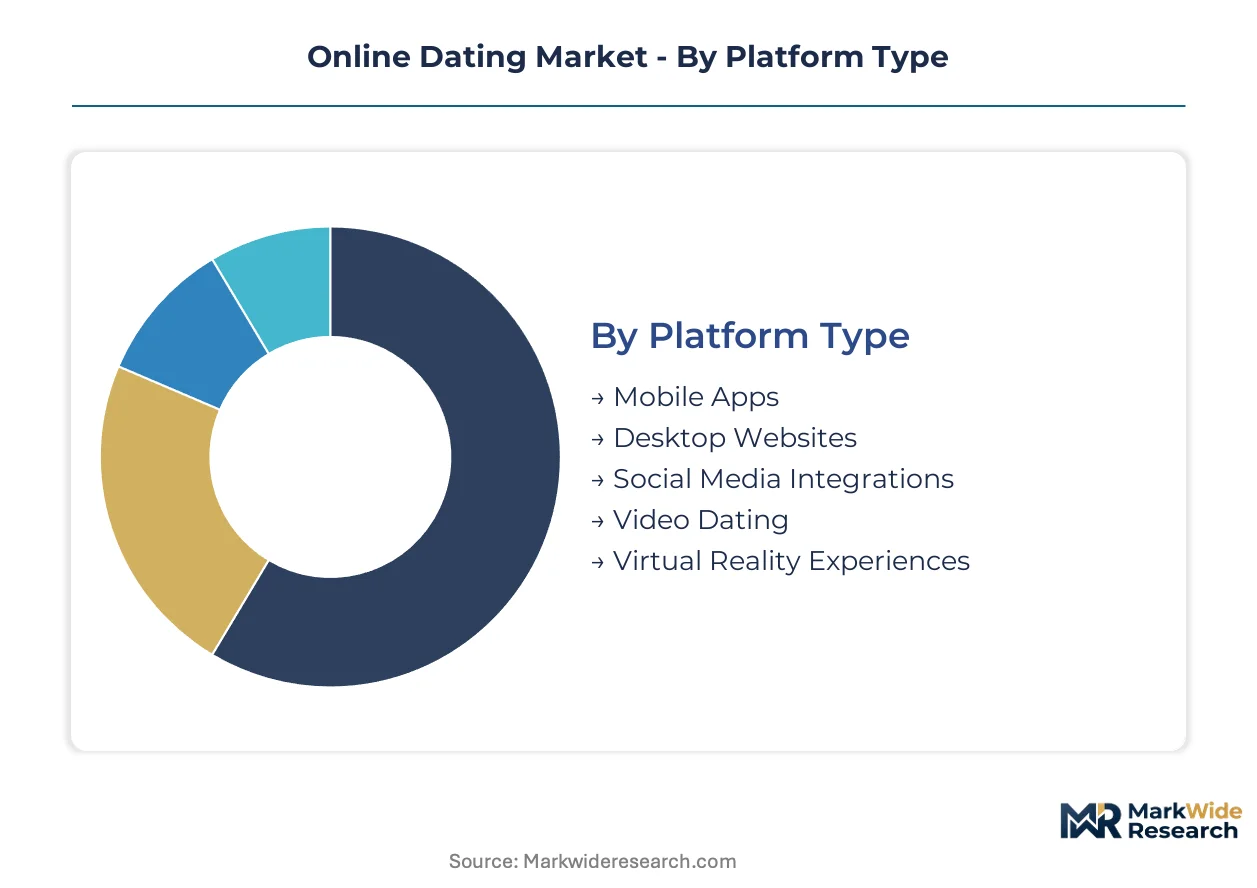
Platform architecture and user intent segmentation determine capital allocation across matching algorithms, content moderation infrastructure, and geographic expansion roadmaps. Each dimension carries distinct technical requirements and regulatory exposure that reshape competitive economics.
Platform Type:
Capital intensity peaks with immersive technology stacks requiring specialized hardware partnerships and cloud rendering capacity.
- Mobile Apps:Native iOS and Android applications dominate user acquisition through push-notification re-engagement and in-app purchase flows. Demand concentrates in India, Brazil, and Southeast Asia where smartphone penetration expands the addressable base for casual connection seekers.
- Video Dating:Synchronous streaming infrastructure reduces catfishing friction and accelerates trust formation through real-time interaction. European operators face steepest compliance costs as GDPR and EU AI Act provisions force architectural overhaul of content moderation systems.
- Desktop Websites:Browser-based platforms retain utility for detailed profile construction and extended messaging sessions.
- Social Media Integrations:Embedded matching layers leverage existing identity graphs and friend-network validation.
- Virtual Reality Experiences:Headset-dependent environments require partnerships with Meta, Apple, or specialized hardware vendors.
Most installed capacity flows through Mobile Apps. Expansion is steepest in Video Dating.
Relationship Goals:
Monetization depth varies sharply by intent tier, with commitment-oriented segments commanding subscription premiums and casual segments driving volume.
- Casual Dating:Low-friction matching prioritizes geographic proximity and immediate availability over compatibility depth. Younger demographics in urban India and Southeast Asian markets adopt these formats fastest, compressing discovery-to-meeting cycles.
- Long-Term Commitment:Extended questionnaires and behavioral compatibility scoring justify tiered subscription pricing. Silver singles segments in Germany, Japan, and Australia show rising adoption with higher lifetime value profiles.
- Friendship Building:Platonic connection modes reduce stigma barriers and expand addressable user base beyond romantic seekers.
- Networking:Professional relationship layers compete with LinkedIn and industry-specific community platforms.
- Marriage Prospecting:Culturally specific matching criteria and family-involvement features dominate South Asian and Middle Eastern market entries.
Revenue concentration sits with Long-Term Commitment. User volume leadership belongs to Casual Dating.
User Demographics:
Identity-specific features and safety infrastructure requirements fragment product development across protected-class designations.
- Singles:Core demographic driving platform economics through highest engagement frequency and subscription conversion rates.
- Divorced Individuals:Second-marriage prospecting demands age-appropriate matching pools and discretion features.
- Widowed Users:Grief-sensitive onboarding and community support integration differentiate specialized platforms.
- LGBTQ+ Community:Identity verification and anti-discrimination protocols require dedicated trust and safety investment.
- Seniors:Simplified interfaces and fraud protection address technology-confidence gaps and financial vulnerability concerns.
Platform investment prioritizes Singles. Fastest-growing engagement rates are climbing among Seniors.
Monetization Model:
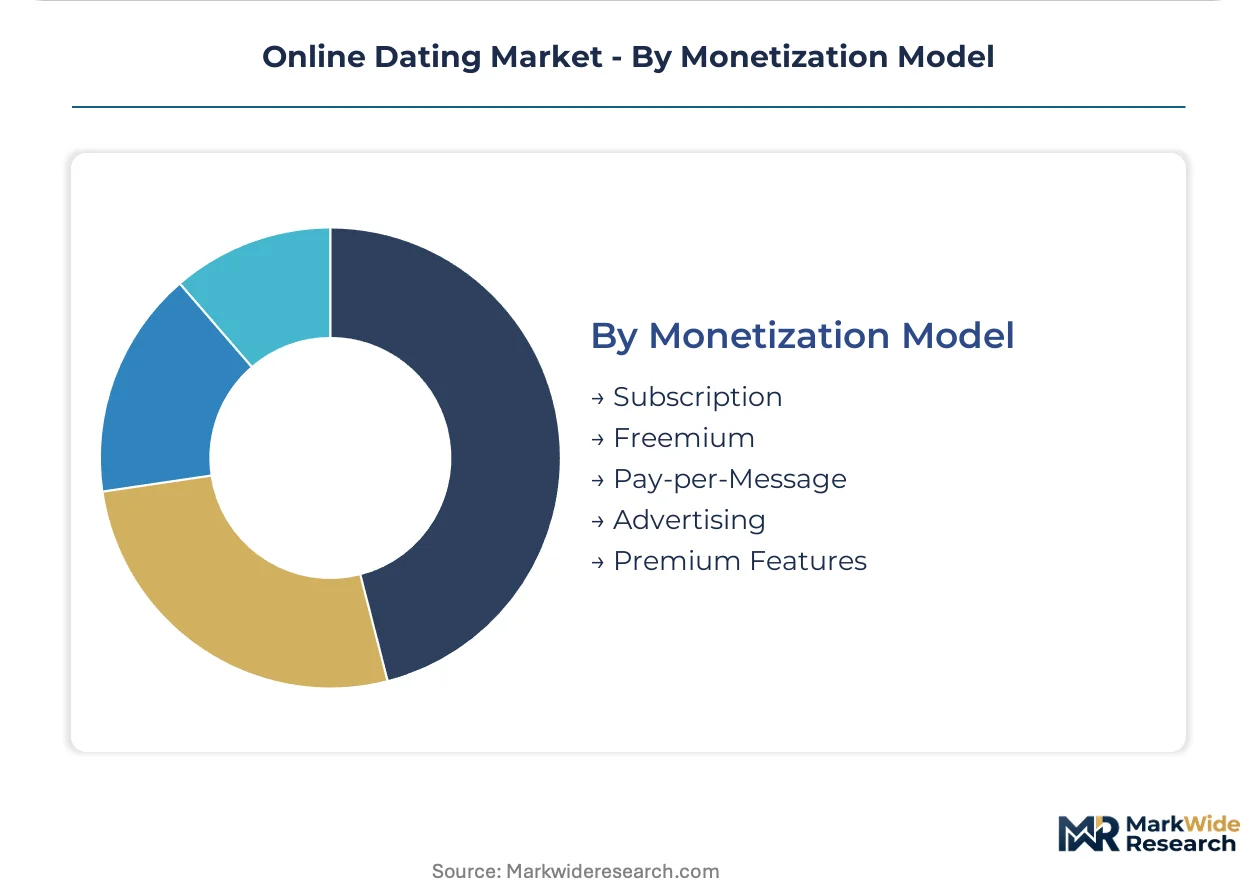
Payment flow architecture and pricing psychology determine margin structure and regulatory scrutiny exposure.
- Subscription:Recurring revenue captures deepest user commitment through unlimited messaging and enhanced visibility tiers. US Federal Trade Commission scrutiny of cancellation pathway design creates compliance cost divergence.
- Freemium:Tiered access converts broad acquisition funnels into paying users through feature gating. Nordic and Dutch markets show strongest adoption of outcome-based guarantees that refund subscriptions after defined periods without successful connections.
- Pay-per-Message:Microtransaction models dominate emerging market entries with lower credit card penetration.
- Advertising:Ad-supported tiers subsidize user acquisition in price-sensitive demographics.
- Premium Features:A-la-carte boosts and visibility enhancements capture intermittent willingness-to-pay.
Revenue stability flows through Subscription. Pricing experimentation is expanding most quickly in Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors platform engineering talent density, while user monetization concentrates across divergent regulatory environments that reshape product architecture and compliance investment.
United States
Urban coastal metros drive subscription revenue through premium tier adoption and video dating feature uptake. The FTC scrutinizes dark-pattern cancellation flows and subscription billing transparency, forcing interface redesigns. Los Angeles and New York City host concentrated product development teams building synchronous video infrastructure.
Germany
Silver singles segments in Berlin and Munich generate higher lifetime value through commitment-oriented matching demand. GDPR and the EU AI Act constrain automated decision-making for user ranking, requiring explainable algorithm architectures. Hamburg hosts specialized trust-and-safety engineering clusters serving European operators.
India
Smartphone penetration in Mumbai, Bangalore, and Delhi-NCR expands the addressable base for mobile-first casual platforms. The Digital Personal Data Protection Act introduces consent-layer requirements that reshape onboarding flows. Hyderabad emerges as a technical operations hub for video moderation and regional language support.
Brazil
São Paulo and Rio de Janeiro concentrate freemium user volume with strong in-app purchase conversion on Android devices. General Data Protection Law enforcement creates compliance divergence from European standards. Belo Horizonte develops localized machine learning pipelines for Portuguese-language compatibility scoring.
United Kingdom
London anchors European headquarters for global platform operators managing cross-border data flows. The Online Safety Bill mandates age assurance and content moderation transparency, accelerating biometric verification pilots. Manchester hosts customer experience centers handling subscription retention and dispute resolution.
Online Dating Market Key Industry Players
Global majors compete with regional champions across regulatory compliance capabilities and demographic specialization strategies. The vendor base separates into portfolio conglomerates controlling multiple app properties, single-brand specialists defending niche positioning, and social media platforms embedding dating layers within existing user graphs. Dominant competitive moves include biometric verification infrastructure partnerships and generative AI feature licensing to differentiate user experience.
Within the portfolio conglomerate tier, Match Group and Bumble exemplify scale-driven diversification across casual and commitment-oriented segments. Grindr occupies a distinct position serving LGBTQ+ community infrastructure requirements with specialized trust-and-safety investment. These three entities represent divergent strategic archetypes: horizontal portfolio breadth, women-first messaging architecture, and identity-specific community focus respectively.
| Leading Market Players |
|---|
| Hinge |
| OkCupid |
| Match Group |
| Grindr |
| eHarmony |
| Meta Platforms |
| Tinder |
| Plenty of Fish |
| Bumble |
| Others |
Cost & Logistics Intelligence
EU AI Act transparency mandates on algorithmic decision-making now gate both qualified supplier partnerships and premium-tier pricing access for European operators, forcing platforms to absorb compliance costs or cede high-value segments to explainable-AI specialists.
Pricing Analysis
Cloud compute and AI inference cost pass-throughs intensify margin compression as real-time matching algorithms scale across user volumes. Three-tier pricing structure across premium, standard, and economy levels dominates, with subscription premiums justified by video dating features and biometric verification bundles. Price differentiation hinges on trust-assurance tier and geographic delivery cost for localized content moderation. Pricing pressure stems from outcome-based guarantee adoption in Nordic markets, where refund obligations compress recurring revenue stability. Casual dating segments exhibit highest price sensitivity, while silver singles in commitment-oriented tiers accept elevated subscription rates.
Supply Chain Analysis
GPU and specialized AI accelerator supply rests on Taiwanese foundry capacity, South Korean memory fabrication, and US cloud hyperscaler infrastructure. Raw material dependencies span rare earth elements for semiconductor manufacturing, optical components for video streaming hardware, and lithium-ion cells for mobile device power management. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical export controls threaten inference capacity expansion. Distribution runs through direct API integrations with cloud providers and device manufacturer pre-installation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The online dating market reads as a late-cycle quality story where user acquisition arbitrage has expired and sustainable economics now favor platforms delivering verified outcomes, with buyer preferences tilting toward premium specifications that guarantee connection success.
For Market Incumbents: Anchor defensive positioning through biometric verification infrastructure partnerships that preempt regulatory fragmentation costs, while consolidating machine learning engineering talent pools in Hyderabad and Berlin to offset compensation inflation. Social audio platforms and interest-based community apps pose substitution threats to casual connection revenue; counter through backward integration into video moderation technology.
For New Entrants and Emerging Players: Begin with underpenetrated silver singles segments in Germany, Japan, and Australia, where lifetime value profiles exceed younger demographics and competitive density remains lowest. Marriage prospecting features for South Asian diaspora communities offer the most penetrable application layer. Pursue employer-subsidized corporate wellness channels as a B2B2C go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional champions with localized language support and compliance infrastructure already deployed. Long-term viability across a 5-10 year window favors platforms with transparent algorithm architectures that satisfy emerging AI governance frameworks. Target acquisition archetype: video-first operators with real-time content moderation systems. The signal to watch is biometric verification mandate acceleration across multiple jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Verification Partnership | Preempts EU AI Act compliance costs while commanding premium subscription positioning. |
| Generative AI Feature Licensing | Differentiates user experience through conversation assistance and AR virtual date environments. |
| Regional Language Localization | Captures smartphone penetration waves in India, Brazil, and Southeast Asian markets. |
| Corporate Wellness Channel Entry | Opens employer-subsidized B2B2C revenue with employee retention justification. |
| Explainable Algorithm Retraining | Satisfies GDPR and EU AI Act transparency requirements without sacrificing matching efficacy. |
Research Approach
Direct dialogue with product managers at dating platforms, trust-and-safety engineering leads, regulatory affairs specialists, and mobile app monetization executives grounded the qualitative foundation. Secondary validation drew from SEC filings, App Annie mobile performance data, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up and top-down triangulation cross-checked user volume estimates against revenue disclosures and regional smartphone penetration benchmarks.
Analytical lenses alternated between bottom-up user cohort modeling and top-down addressable market sizing across the projection horizon. Segmentation dimensions spanned platform architecture, relationship intent tier, demographic cohort, and monetization model, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from historical subscription pricing trajectories and video feature penetration curves, with cloud infrastructure cost curves and privacy law implementation timelines as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen biometric verification mandate delays, social audio platform feature convergence, and macroeconomic shocks to discretionary subscription spending. Forecasts embed assumptions about regulatory implementation pace and GPU supply availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
API Management Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Data Extraction Market