
 Video Management System Market | 2026-2036
Video Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Video Management System Market Analytics
Enterprise security teams are reorganizing procurement priorities around cloud-native video architectures, displacing traditional IT-led hardware refresh cycles. Milestone Systems leverages its open-platform strategy to anchor large-scale government deployments across multiple continents. Genetec differentiates through unified security software that integrates access control with video analytics. Eagle Eye Networks competes on pure-cloud delivery, eliminating on-site server maintenance for mid-market retail chains.
A video management system is a software platform that aggregates, stores, and processes video feeds from distributed camera networks, typically supporting H.264/H.265 compression and ONVIF protocol interoperability for multi-vendor hardware integration. Its primary purpose is to enable real-time monitoring, forensic search, and automated alerting across security, operations, and compliance workflows. Cloud-based deployment is capturing the fastest expansion as organizations prioritize remote accessibility and elastic storage over capital-intensive server installations. The surveillance application segment dominates current revenue pools, though analytics solutions within the technology dimension are emerging as the highest-margin attach category. IP cameras anchor hardware connectivity standards, while hybrid architectures persist among buyers with legacy analog infrastructure and phased migration budgets.
FCC guidelines on data transmission integrity and the EU AI Act's provisions on biometric surveillance shape product development roadmaps for vendors serving North American and European buyers, respectively. BIS certification requirements in India and GDPR compliance obligations across Europe constrain market entry for platforms lacking localized data residency architectures. Stakeholders must weigh the pace of regulatory fragmentation against the cost of maintaining parallel compliance stacks as AI-enabled video analytics penetrate sensitive deployment environments.
Market Dynamics
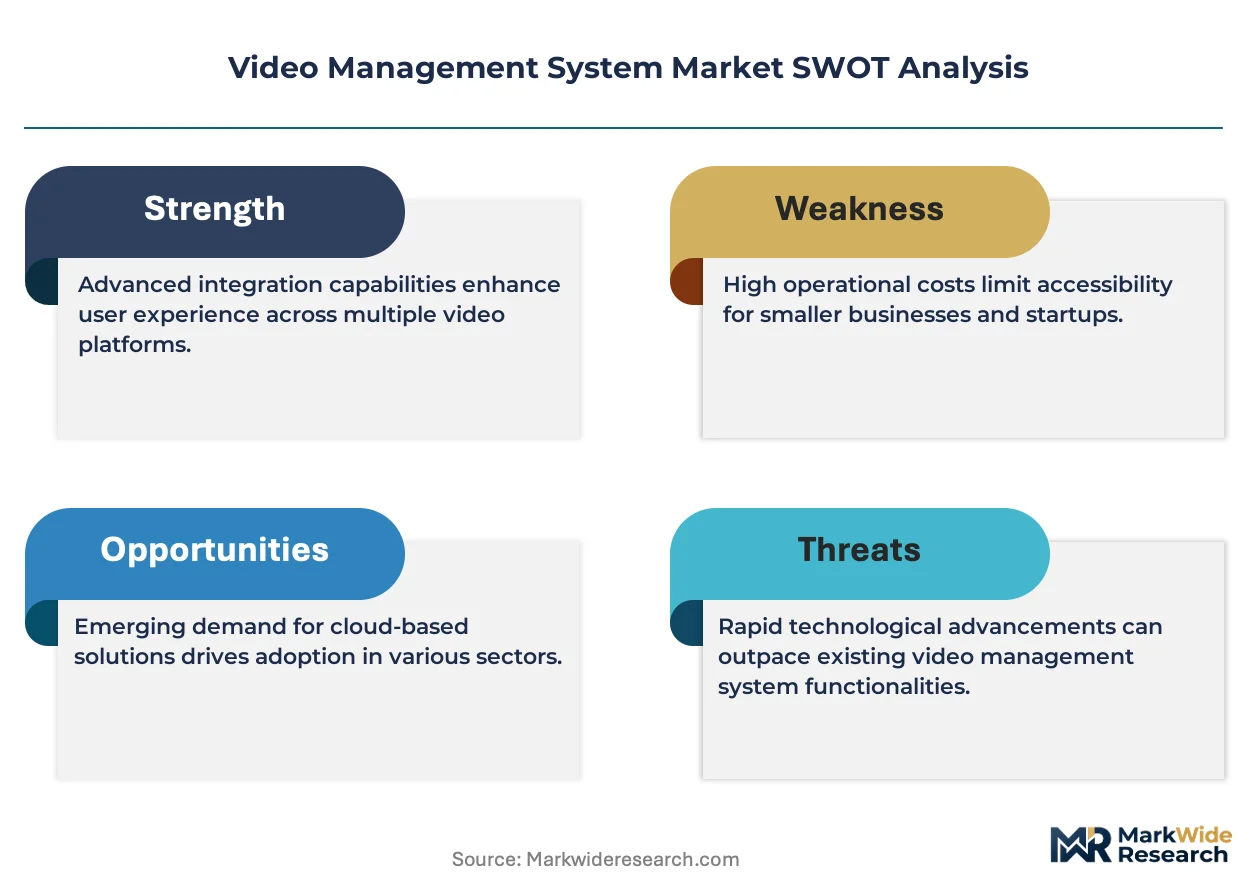
Cloud-native video architectures are compressing traditional hardware refresh cycles as municipal and enterprise buyers prioritize operational expenditure models over capital-intensive server installations. This structural shift redistributes value capture from on-premises integrators toward subscription-based platform providers.
Growth Catalysts
- Smart city infrastructure mandates:India's urban surveillance directives under national security frameworks are accelerating centralized video platform procurement across municipal corporations.
- EU AI Act biometric provisions:Compliance requirements for automated surveillance systems are driving replacement demand for analytics-capable platforms across European public sector deployments.
- ONVIF protocol standardization:Multi-vendor hardware interoperability reduces buyer lock-in and expands addressable market for open-platform software vendors.
Market Restraints
- Data residency compliance costs:GDPR localization requirements and India's BIS certification impose parallel architecture investments for vendors serving multiple geographies.
- Legacy analog infrastructure:Hybrid migration timelines among budget-constrained buyers delay full cloud transitions and compress near-term revenue per account.
- Edge compute hardware shortages:Semiconductor supply concentration in East Asian foundries creates deployment bottlenecks for on-premise analytics appliances.
Strategic Opportunities
- Underpenetrated mid-market retail:Pure-cloud delivery models eliminate server maintenance burdens for franchise chains with distributed footprints lacking IT staff.
- Convergence of access control and video:Unified security platforms integrating physical identity management command premium pricing in corporate campus deployments.
- Elastic storage economics:Consumption-based cloud retention models unlock forensic search capabilities for buyers previously constrained by fixed storage capacity.
Industry Challenges
- AI model training data scarcity:High-quality labeled surveillance footage for behavioral analytics remains concentrated among defense contractors and large municipal operators.
- Integration complexity with PSIM legacy:Physical security information management platforms from the 2010s require costly middleware development for API compatibility with modern cloud stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Management System Market |
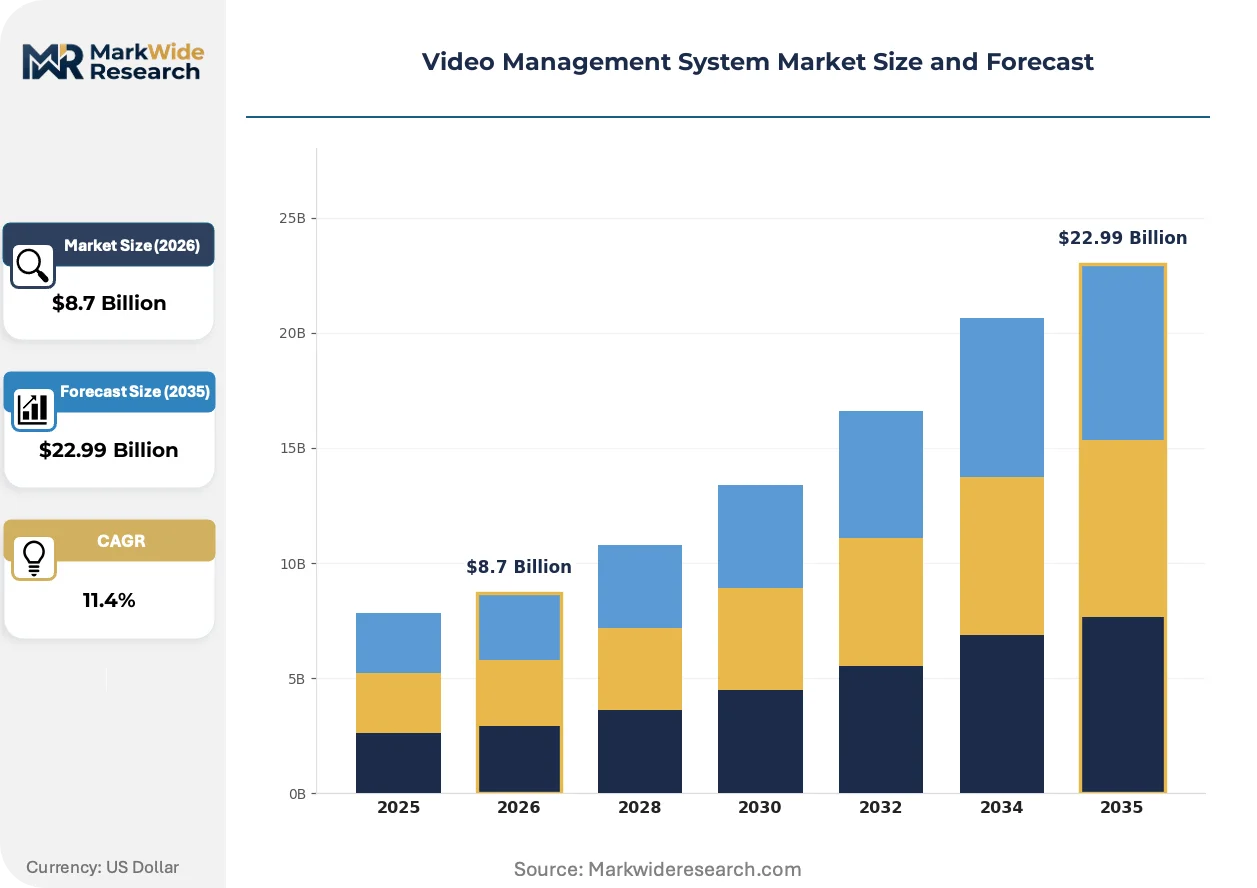
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Server-Based Application: Surveillance, Media Management, Broadcast Monitoring, Live Streaming End User: Government, Retail, Transportation, Education Technology: IP Cameras, Analog Cameras, Wireless Systems, Analytics Solutions |
| Companies Covered | Eagle Eye Networks, Avigilon, Milestone Systems, Gorilla Technology, Axis Communications, Genetec, Rhombus, Video Insight, Digital Watchdog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Management System Market Evolving Landscape
Video management platforms are pivoting from passive recording infrastructure toward active decision-support systems through embedded intelligence and consumption-based commercial models. This transformation redefines competitive differentiation around software capabilities rather than hardware scale.
Edge-based AI inference is displacing centralized server processing for real-time anomaly detection in bandwidth-constrained environments. Retail loss prevention teams and critical infrastructure operators are deploying GPU-enabled cameras to reduce latency for automated alerting. This architecture compresses reliance on high-availability data center infrastructure and shifts analytics value capture toward camera OEMs.
The EU AI Act's risk classification framework for biometric identification systems imposes conformity assessment obligations on vendors deploying facial recognition in public spaces. European police forces and transport authorities must document fundamental rights impact assessments before procurement. Platform providers are responding by modularizing analytics features to enable jurisdiction-specific feature activation.
Enterprise security directors now demand subscription pricing with elastic storage scaling rather than perpetual licenses with fixed retention periods. This preference restructures vendor cash flow profiles and accelerates customer lifetime value realization through annual recurring revenue models. North American Fortune 500 campuses and Asia-Pacific data center operators exhibit the fastest transition to consumption-based contracts.
Video Management System Market Segmentation
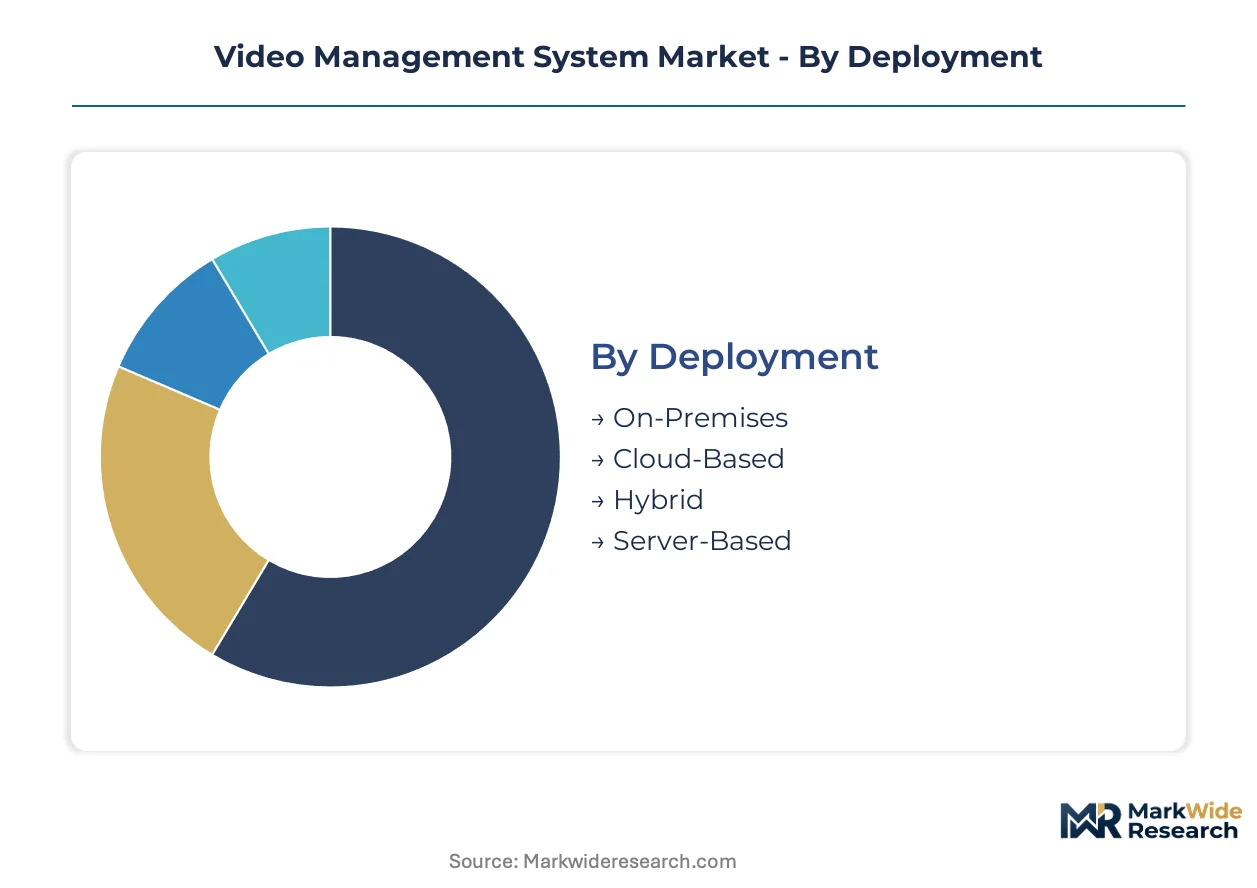
Video management system procurement channels diverge sharply by deployment architecture, with cloud-native platforms flowing through SaaS marketplaces while on-premises solutions remain captive to systems integrators. Understanding these channel dynamics reveals where vendor margin pools concentrate and which segments justify dedicated sales investment.
Deployment:
Channel economics split this category between capital expenditure cycles for hardware-heavy configurations and operational expenditure routes for subscription-delivered platforms.
- Cloud-Based:Multi-tenant architectures eliminate server procurement for buyers, with elastic storage scaling driving municipal and retail procurement through direct vendor relationships. India's smart city mandates accelerate centralized platform adoption among municipal corporations lacking data center infrastructure.
- Hybrid:Bridges legacy analog investments with cloud analytics, appealing to budget-constrained buyers in phased migration scenarios. European transport authorities favor this architecture to satisfy GDPR data residency requirements while accessing cloud-based forensic search.
- On-Premises:Retains dominance in defense and critical infrastructure deployments with air-gapped security requirements.
- Server-Based:Persists among buyers with existing data center investments and specialized compliance needs.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
Application:
Functional requirements determine integration complexity and pricing tier, with surveillance commanding premium analytics attach rates while media management competes on storage economics.
- Surveillance:Real-time monitoring and forensic search capabilities anchor municipal security budgets. EU AI Act biometric compliance requirements are driving platform replacements across European public sector deployments.
- Analytics Solutions:Behavioral detection and automated alerting command the highest software margins within technology portfolios. Edge-based GPU inference is displacing centralized processing in bandwidth-constrained retail environments.
- Media Management:Content indexing and retrieval workflows serve broadcast and enterprise training applications.
- Broadcast Monitoring:Quality assurance and regulatory compliance drive procurement among television networks.
- Live Streaming:Low-latency distribution requirements differentiate this segment from archival surveillance use cases.
Surveillance captures the largest revenue pool. Analytics Solutions within the technology dimension are climbing the fastest.
End User:
Buyer sophistication and procurement authority vary dramatically, with government tenders emphasizing interoperability certifications and retail chains prioritizing rapid deployment without IT staff.
- Government:National security frameworks mandate centralized video platforms with multi-vendor ONVIF compatibility. India's urban surveillance directives accelerate procurement across municipal corporations.
- Retail:Franchise operators with distributed footprints favor pure-cloud delivery to eliminate server maintenance burdens. Loss prevention teams deploy GPU-enabled edge cameras for real-time anomaly detection.
- Transportation:Critical infrastructure operators require high-availability architectures with redundant failover capabilities.
- Education:Campus security directors balance budget constraints with expanding coverage requirements for multi-building environments.
Government anchors procurement volume. Retail represents the steepest expansion trajectory for cloud-native platforms.
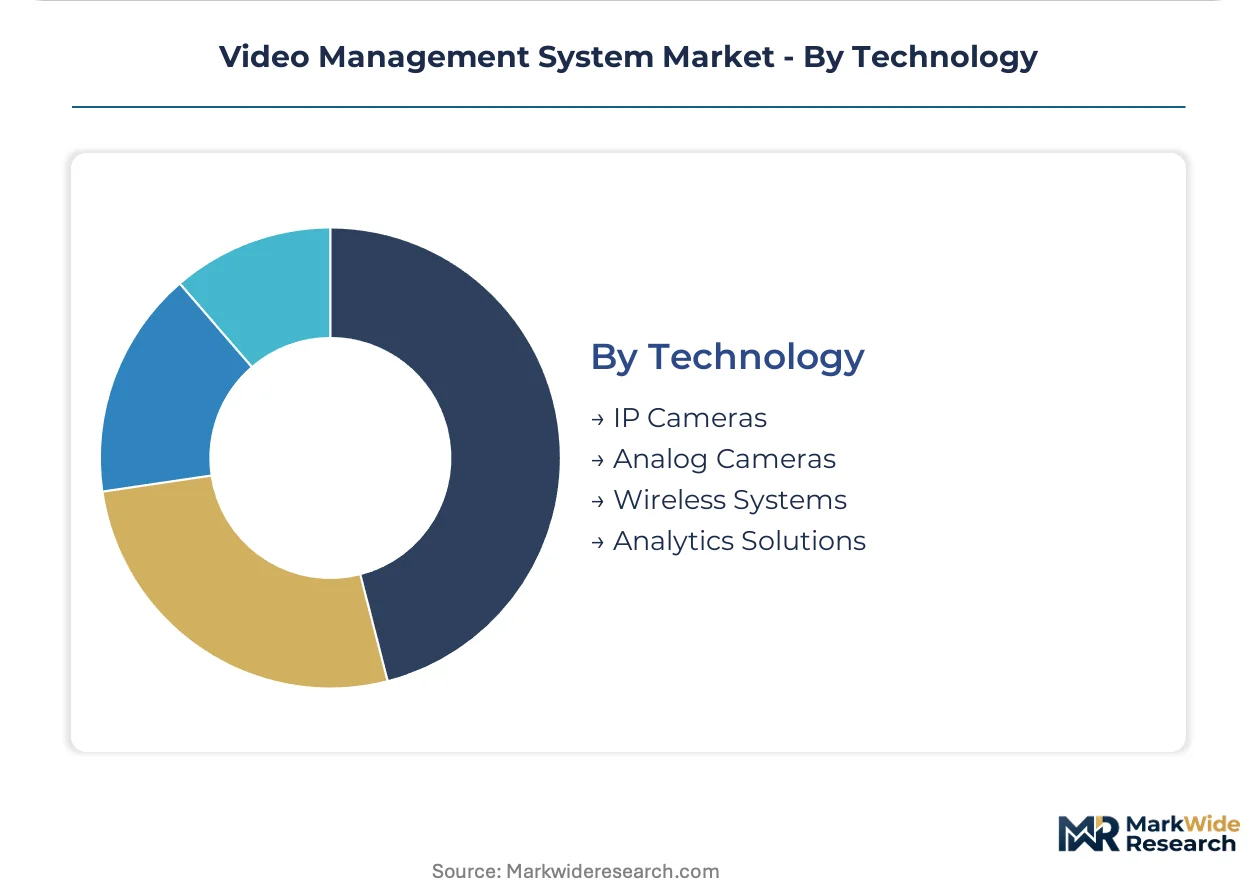
Technology:
Hardware connectivity standards determine integration cost and vendor lock-in exposure, with IP-based systems offering open-platform flexibility versus proprietary wireless configurations.
- IP Cameras:H.264/H.265 compression and ONVIF protocol interoperability enable multi-vendor software integration. ONVIF standardization reduces buyer lock-in and expands addressable market for open-platform vendors.
- Analytics Solutions:Embedded intelligence transforms passive recording into active decision-support, with behavioral analytics requiring scarce labeled training data concentrated among defense contractors.
- Analog Cameras:Legacy infrastructure persists in budget-constrained hybrid migration timelines.
- Wireless Systems:Deployment flexibility appeals to temporary installations and retrofit scenarios with cabling limitations.
IP Cameras anchor hardware standards. Analytics Solutions command premium pricing as the highest-margin attach category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli video analytics exporters supply European municipal buyers confronting EU AI Act biometric compliance deadlines. German integrators purchase cloud-native platforms for smart city deployments. Indian system vendors fulfill domestic urban surveillance mandates under national security frameworks.
United States
Fortune 500 campuses and data center operators drive consumption-based contract adoption for elastic storage scaling. FCC guidelines on data transmission integrity shape product development roadmaps for vendors serving federal buyers. Dallas-Fort Worth corridor hosts concentrated deployment of edge-based GPU inference for retail loss prevention.
Germany
Transport authorities favor hybrid architectures to satisfy GDPR data residency requirements while accessing cloud forensic search. The EU AI Act's risk classification framework for biometric identification imposes conformity assessment obligations on platform providers. Munich security clusters specialize in modular analytics features for jurisdiction-specific activation.
India
Urban surveillance mandates under national security directives accelerate centralized video platform procurement across municipal corporations. BIS certification requirements constrain market entry for platforms lacking localized data residency architectures. Mumbai and Delhi-NCR smart city projects anchor demand for multi-tenant architectures eliminating server procurement.
United Kingdom
Corporate campus deployments command premium pricing for unified security platforms integrating physical identity management. GDPR compliance obligations across Europe drive replacement demand for analytics-capable platforms. London metropolitan security tenders emphasize interoperability certifications for multi-vendor ONVIF compatibility.
Japan
Critical infrastructure operators deploy GPU-enabled cameras to reduce latency for automated alerting in bandwidth-constrained environments. METI industrial standards influence edge compute hardware specifications for manufacturing facility monitoring. Osaka-Kobe industrial corridor concentrates demand for high-availability architectures with redundant failover capabilities.
Video Management System Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native delivery models and open-platform architectures. The vendor base splits between subscription-based platform providers capturing recurring revenue and on-premises integrators defending hardware refresh cycles. Three archetypes dominate: pure-cloud specialists eliminating server maintenance, open-platform vendors anchoring government interoperability tenders, and unified security suites integrating access control with video analytics. M&A activity concentrates on analytics capability acquisition and geographic footprint expansion into underpenetrated mid-market retail.
Within the pure-cloud delivery tier, Eagle Eye Networks and Rhombus exemplify subscription models targeting franchise chains lacking IT staff. Milestone Systems occupies a position among open-platform specialists serving multi-continent government deployments with ONVIF interoperability. Genetec sits within the unified security archetype, representing vendors that bundle physical identity management with video workflows for corporate campus premiums.
| Leading Market Players |
|---|
| Eagle Eye Networks |
| Avigilon |
| Milestone Systems |
| Gorilla Technology |
| Axis Communications |
| Genetec |
| Rhombus |
| Video Insight |
| Digital Watchdog |
| Others |
Value Network & Pricing Analysis
Consumption-based capacity reservation contracts anchor enterprise procurement for cloud-native video platforms, locking in elastic storage access while stabilizing unit economics for municipal buyers navigating India's BIS certification timelines and Europe's GDPR localization mandates.
Pricing Analysis
Next-generation edge-AI camera pricing runs 40-60% above prior-generation IP hardware, while legacy analog-to-hybrid migration bundles occupy the economy tier. Three-tier pricing structure across premium analytics-enabled, standard cloud-native, and economy on-premises levels reflects certification grade differentiation and after-sales support bundling. Cost compression in the standard tier intensifies as pure-cloud specialists eliminate server maintenance overhead for mid-market retail chains. Franchise operators with distributed footprints exhibit highest price sensitivity; defense and critical infrastructure buyers with air-gapped requirements show lowest elasticity due to compliance-driven procurement authority.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo and Los Angeles-Long Beach trade lanes elevates inbound logistics costs for GPU-enabled edge compute hardware destined for North American retail deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while camera assembly and system integration cluster in Vietnam, Mexico, and India. Raw material dependencies span CMOS image sensors, high-bandwidth memory modules, and precision optical components. Single-source vulnerability in advanced node GPU supply creates deployment bottlenecks for real-time analytics appliances. Distribution runs through systems integrators for on-premises configurations and direct vendor relationships for SaaS-delivered platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video management platforms are crossing a platform-economics inflection as ONVIF interoperability transforms competitive moats from hardware scale toward software ecosystem density and developer network effects.
For Market Incumbents: Compound open-platform architecture investments to defend government tender positions against pure-cloud entrants, while accelerating backward integration into edge-AI chip design to capture analytics value migrating toward camera OEMs. Prioritize India BIS certification and EU AI Act conformity assessment capabilities as regulatory compliance becomes the primary procurement gate. For New Entrants and Emerging Players: Fast-track ONVIF Profile T certification to unlock municipal interoperability tenders in India's smart city corridor and Germany's transport authority segment. White-space concentration sits in mid-market retail franchise chains lacking IT staff for server maintenance, addressable through pure-cloud consumption models with elastic forensic search capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward analytics-specialist acquisition targets with scarce labeled training data repositories and modular AI feature architectures enabling jurisdiction-specific compliance activation. Long-term viability hinges on recurring revenue share expansion and customer lifetime value realization through consumption-based contracts. Monitor EU AI Act enforcement intensity as the primary demand inflection signal for compliance-driven platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified security suites bundling access control with video analytics command corporate campus premium pricing. |
| Acquisition of Specialist Firm | Analytics capability targets with behavioral detection IP address scarce training data concentration. |
| Geographic Expansion | India smart city mandates and BIS certification requirements favor localized data residency architectures. |
| Product Launch | Modular analytics features enable jurisdiction-specific activation for EU AI Act biometric compliance. |
| Strategic Partnership | Camera OEM alliances secure GPU-enabled edge inference supply for bandwidth-constrained retail environments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal security directors, enterprise IT procurement officers, systems integrators, and cloud platform engineers. Secondary validation drew from SEC filings of listed video technology vendors, hyperscaler capex disclosures for data center infrastructure, ONVIF interoperability certification databases, and EU regulatory impact assessments for biometric surveillance. Bottom-up deployment modeling across cloud, hybrid, and on-premises architectures was triangulated against top-down market sizing from vendor revenue disclosures and government tender aggregations.
Across the analysis window, the forecasting framework modeled deployment architecture, application function, end-user vertical, and technology connectivity standards as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves incorporating regulatory compliance deadlines, hardware refresh cycles, and cloud migration propensity by buyer archetype. Elastic storage economics and edge-AI inference penetration served as industry-specific demand drivers; data residency architecture investments and certification timelines shaped supply-side constraints.
Underlying assumptions cover regulatory enforcement continuity, semiconductor supply normalization, and cloud infrastructure capex trajectories, with deviation risk concentrated in EU AI Act implementation timing and India BIS certification processing backlogs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Data Integration Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Inventory Management Market
Digital Solutions
Service Mesh Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Ticket Admission Systems Market