
 Global Mobile Workforce Management Market | 2026-2036
Global Mobile Workforce Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Workforce Management Market Foresight
Utilities operators is pivoting toward integrated mobile platforms that unify scheduling, dispatch, and compliance verification for geographically dispersed technicians. UKG leverages deep workforce management heritage to anchor enterprise accounts with complex union rules and shift differentials. SAP AG competes through embedded ERP connectivity that extends workforce data into financial and supply chain planning modules. ServiceNow differentiates by layering IT service management workflows onto field operations, creating unified incident-to-resolution paths for infrastructure maintenance teams.
Mobile workforce management encompasses software systems that coordinate, track, and optimize employees operating outside centralized facilities through GPS-enabled devices, biometric verification, and real-time data synchronization with enterprise backends. These platforms typically integrate time tracking, route optimization, and compliance documentation to reduce administrative overhead and improve service-level adherence across distributed operations. Cloud-based deployment leads adoption as telecommunications providers and construction firms abandon on-premises infrastructure for scalable SaaS models with lower capital commitment. Scheduling and dispatch solutions capture disproportionate investment because field service applications require dynamic rerouting capabilities that respond to emergency breakdowns and weather disruptions. Analytics and reporting functions are gaining priority among public sector agencies seeking audit trails for taxpayer-funded projects and union-mandated overtime documentation.
FCC guidelines on data transmission reliability shape how Verizon Wireless and other carriers architect connectivity layers for mission-critical field communications, while OSHA record-keeping mandates push construction firms toward automated injury-reporting modules within mobile platforms. The EU AI Act introduces algorithmic transparency requirements that affect automated scheduling and performance-scoring features deployed across European operations. Stakeholders must monitor how emerging labor classification rules in multiple jurisdictions redefine contractor-versus-employee boundaries, since mobile tracking tools face heightened scrutiny when applied to gig-economy dispatch models.
Market Dynamics
Cloud-native workforce platforms are compressing deployment cycles from months to weeks, forcing legacy on-premise vendors to accelerate SaaS migrations or cede enterprise accounts to agile competitors. This architectural shift is restructuring vendor economics and customer lock-in mechanisms across field service industries.
Growth Catalysts
- GDPR audit mandates:European utilities and telecom operators must maintain granular workforce activity records, driving replacement of paper-based field logs with biometric-verified mobile systems that timestamp every dispatch decision.
- Telecommunications infrastructure buildouts:5G network densification requires coordinated technician deployments across overlapping coverage zones, creating demand for dynamic rerouting algorithms that respond to real-time tower maintenance alerts.
- India's PLI scheme for electronics manufacturing:Contract manufacturers establishing component assembly facilities in Gujarat and Tamil Nadu need multilingual workforce coordination platforms to manage inter-state technician rotations and compliance documentation.
Market Restraints
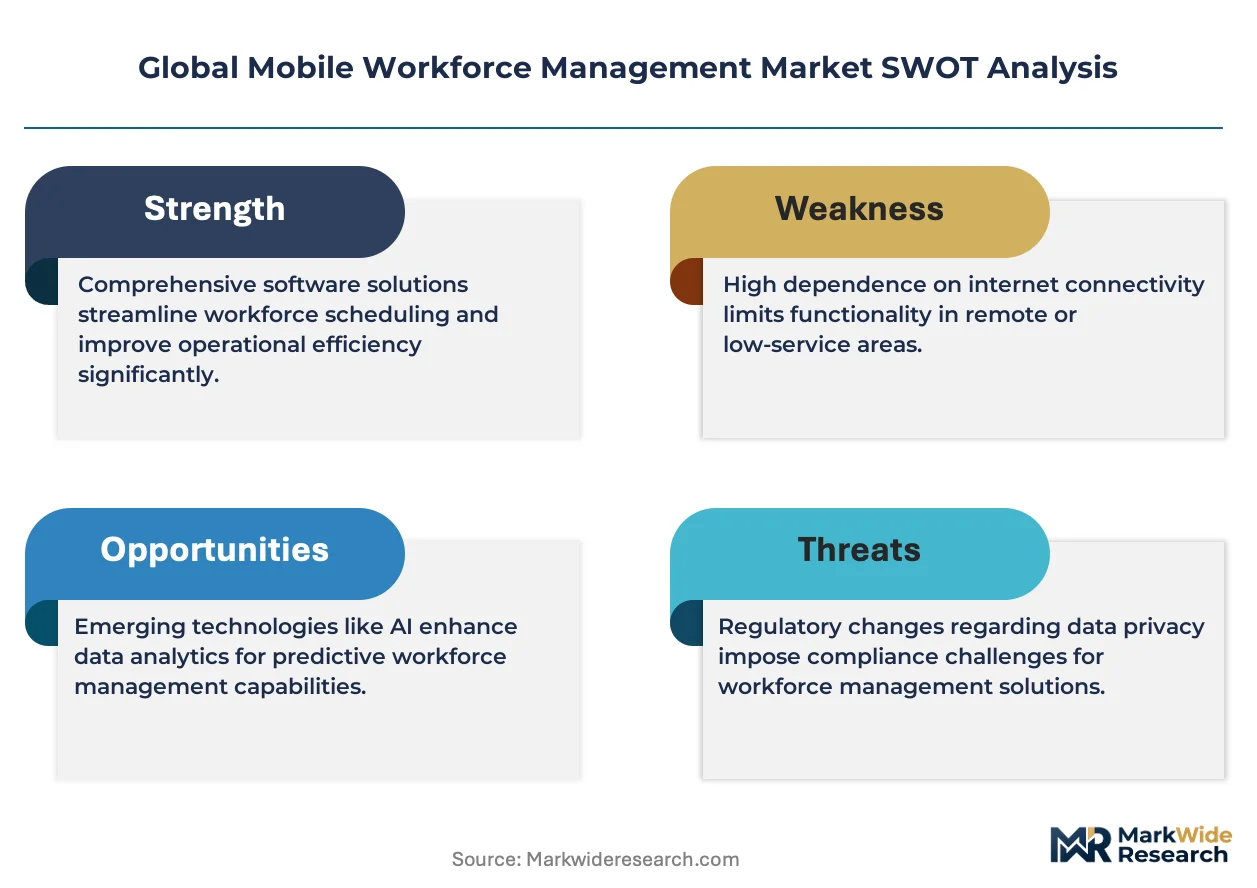
- Connectivity infrastructure gaps:Remote field sites in rural India and inland China lack reliable 4G coverage, forcing platform vendors to engineer expensive offline-sync architectures that degrade real-time dispatch responsiveness.
- Labor classification uncertainty:California's AB5-style contractor reclassification rules and similar pending legislation in Germany create legal exposure for gig-economy dispatch models that rely on algorithmic worker scoring.
- Biometric hardware supply concentration:Fingerprint and facial recognition sensors for ruggedized field devices depend on concentrated semiconductor fabrication in Taiwan, exposing procurement timelines to geopolitical disruption risks.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized mechanical engineering service firms with 200-800 field technicians still operate on spreadsheet-based scheduling, presenting white-space for verticalized SaaS offerings with embedded union tariff engines.
- EU AI Act transparency requirements:Automated performance scoring and predictive scheduling algorithms deployed across European operations must now provide explainable decision trails, creating consultancy and software module opportunities for compliance-native vendors.
- Augmented reality convergence:Overlaying remote expert guidance onto technician mobile screens during complex infrastructure repairs reduces first-visit resolution times and supports premium service tier differentiation.
Industry Challenges
- Legacy ERP integration complexity:Industrial customers running decades-old SAP R/3 or Oracle E-Business Suite instances require costly custom middleware to synchronize workforce data with financial and procurement modules.
- Union negotiation friction:Platform deployment in US utilities and German manufacturing services stalls when GPS tracking and automated productivity metrics trigger collective bargaining disputes over surveillance scope and overtime calculation methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Workforce Management Market |
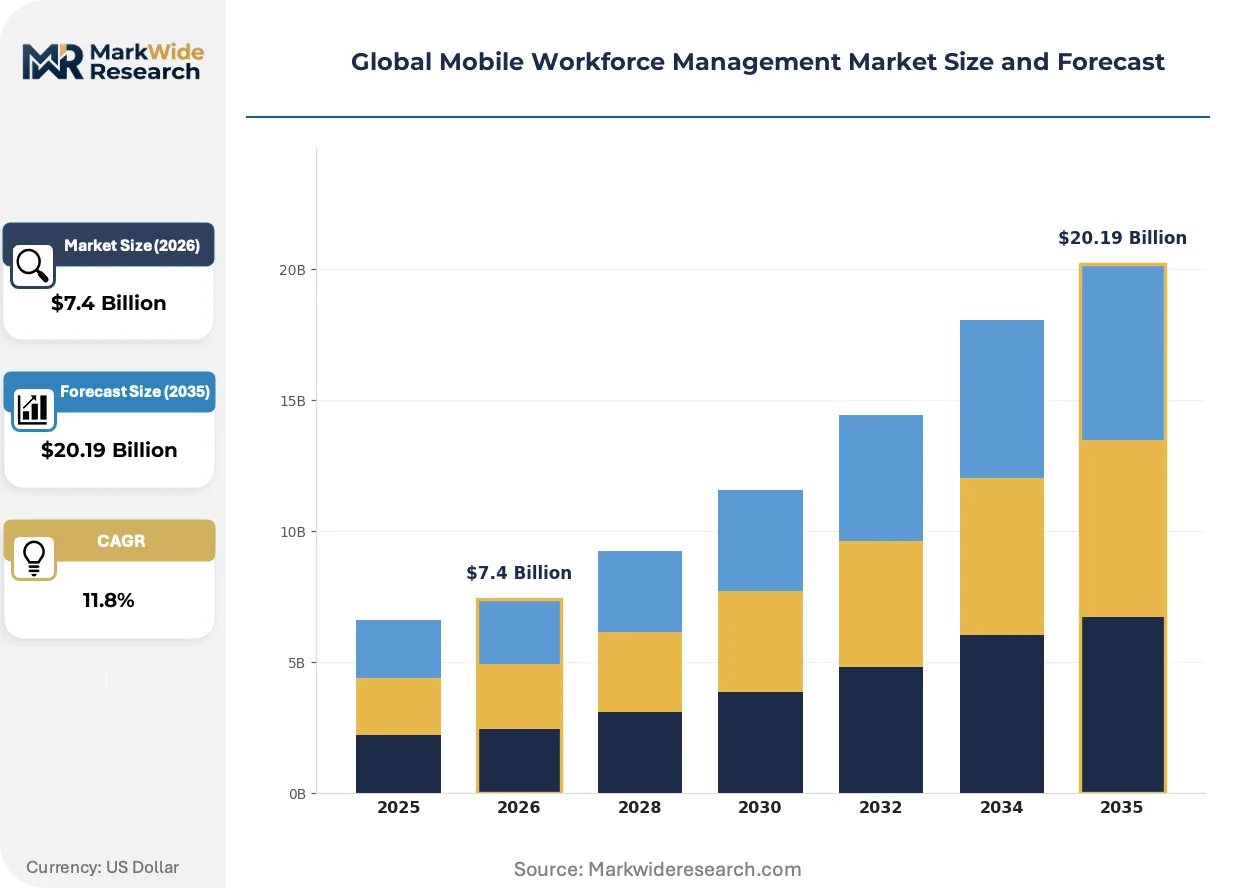
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $20.19 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution Type: Time Tracking, Scheduling & Dispatch, Analytics & Reporting, Compliance Management Application: Field Service, Sales Force Automation, Inspection & Auditing, Delivery & Logistics End User Industry: Construction Firms, Telecommunications Providers, Utilities Operators, Public Sector Agencies |
| Companies Covered | UKG, Verizon Wireless, ServiceNow, Workday, Trimble Inc., SAP AG, ADP, Infor, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Workforce Management Market Shifts & Advancements
Artificial intelligence is penetrating workforce coordination at three distinct layers: predictive scheduling engines, natural language field reporting, and automated compliance documentation. These capabilities are converging into unified platforms that compress administrative overhead while intensifying data governance requirements.
Edge-computing dispatch nodes are overtaking centralized cloud-only architectures for mission-critical infrastructure maintenance. These localized processing units enable sub-50-millisecond rerouting decisions during power grid failures or telecommunications outages. European utilities in Germany and France are deploying ruggedized edge servers at substations to maintain workforce coordination during wide-area network disruptions. This distributed topology is overtaking traditional hub-and-spoke cloud models where latency tolerance exceeded 200 milliseconds.
The EU AI Act's algorithmic transparency mandates are forcing vendors to reengineer automated scheduling systems deployed across European operations. Performance-scoring models must now generate human-readable decision logs that explain why specific technicians received priority dispatch assignments. German field service operators are conducting algorithmic impact assessments before deploying predictive overtime allocation tools. This regulatory pressure is accelerating investment in explainable AI frameworks that document scheduling logic for labor inspectorate audits.
Subscription-based platform procurement is displacing perpetual license purchases among North American construction and facilities management firms. Buyers now demand consumption-aligned pricing tied to active technician counts rather than upfront enterprise commitments. This shift compresses vendor cash conversion cycles while intensifying annual retention pressure. Texas-based oilfield service contractors and California solar installation firms are negotiating month-to-month SaaS terms with biometric verification modules billed per authenticated field session.
Global Mobile Workforce Management Market Segmentation
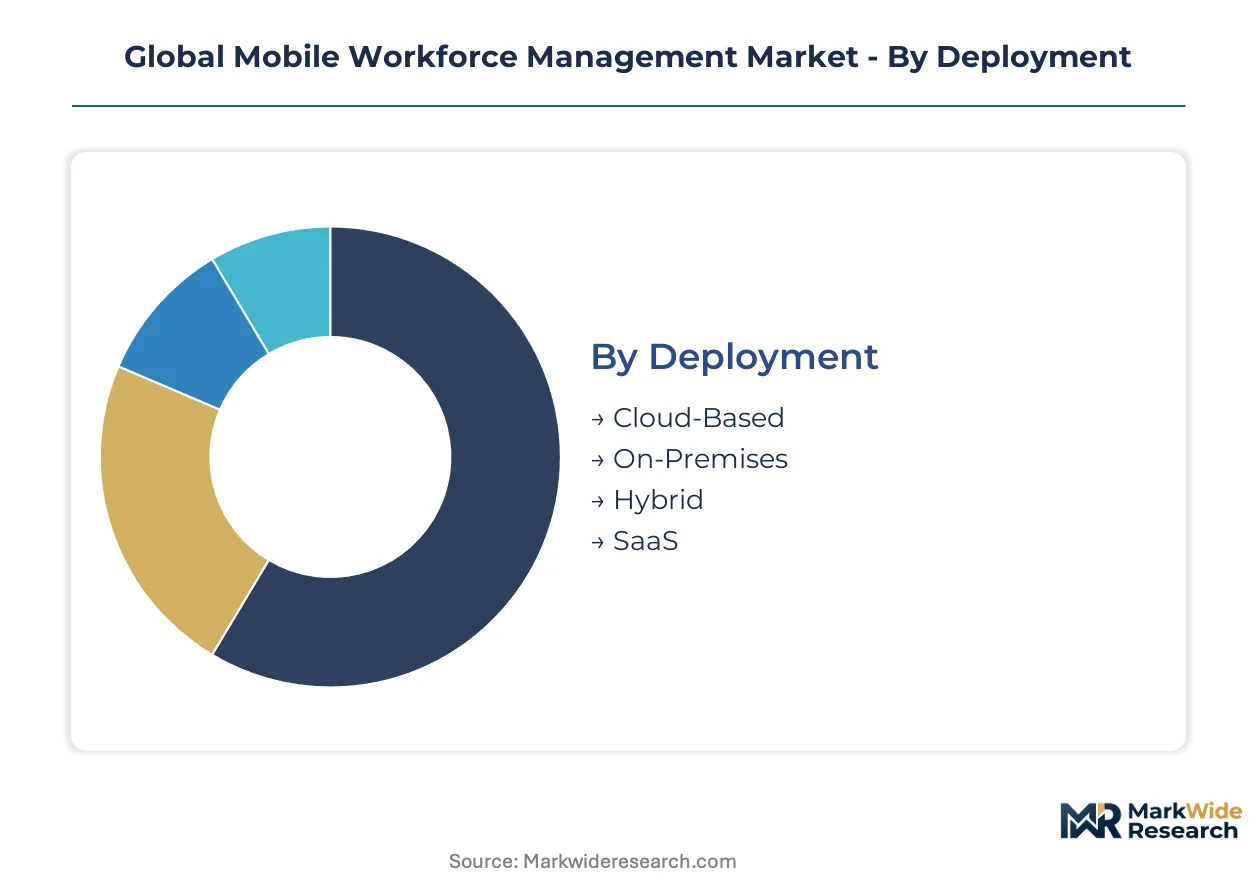
Mobile workforce management platforms serve divergent operational contexts that demand distinct technical architectures and integration depths. Segmentation reveals where standalone point solutions suffice versus where embedded enterprise systems dominate procurement decisions.
Deployment:
Standalone cloud deployments dominate mid-market field service operations with limited IT infrastructure, while embedded hybrid architectures prevail in regulated industries requiring air-gapped data sovereignty.
- Cloud-Based:Multi-tenant SaaS architectures with API-first design patterns enable rapid deployment for construction firms and regional telecommunications contractors. Demand concentrates in India and Germany among mid-sized service providers seeking zero-capital-expenditure scaling without on-site server maintenance.
- On-Premises:Dedicated hardware installations within customer data centers maintain complete data custody for defense contractors and nuclear utilities subject to national security clearance requirements. European water utilities in France and Germany favor this model to satisfy GDPR data-localization mandates for critical infrastructure protection.
- Hybrid:Split architectures process sensitive biometric data locally while syncing operational metrics to cloud analytics engines. US oilfield service firms deploy this configuration to maintain OSHA injury records on-site while enabling corporate visibility into fleet-wide safety trends.
- SaaS:Pure subscription models with consumption-based billing align vendor incentives with customer technician counts. California solar installation firms negotiate per-authenticated-session pricing to match seasonal workforce fluctuations.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Type:
Cost-tier stratification separates commodity time-capture modules from premium compliance engines that command implementation consulting fees.
- Time Tracking:GPS-stamped clock-in functionality with biometric verification prevents buddy-punching across dispersed construction crews. German mechanical engineering service firms embed union tariff engines to automate shift differential calculations.
- Scheduling & Dispatch:Dynamic optimization algorithms reroute technicians in response to emergency infrastructure failures. Telecommunications providers in the United States deploy these systems to coordinate 5G tower maintenance across overlapping coverage zones.
- Analytics & Reporting:Audit-ready dashboards document workforce activity for taxpayer-funded projects and union-mandated overtime disputes. Public sector agencies in India require granular activity logs to satisfy central government transparency mandates.
- Compliance Management:Automated documentation pipelines align field operations with evolving regulatory frameworks. European utilities integrate EU AI Act transparency modules to generate human-readable logs for algorithmic scheduling decisions.
Scheduling & Dispatch captures the largest deployment base; Compliance Management is climbing the fastest as regulatory pressure intensifies.
Application:
Customer-type differentiation separates asset-heavy infrastructure maintenance from transaction-oriented sales operations.
- Field Service:Unified platforms coordinate dispatch, parts inventory, and customer notification for utility repair crews. US electric utilities deploy these systems to maintain service-level agreements during storm recovery operations.
- Sales Force Automation:Route optimization and client history access accelerate pharmaceutical and industrial equipment sales cycles. Indian contract manufacturers leverage multilingual interfaces to coordinate inter-state sales engineer rotations.
- Inspection & Auditing:Structured data capture with photographic evidence chains supports regulatory compliance documentation. German TÜV inspection bodies require tamper-proof audit trails for pressure vessel certification.
- Delivery & Logistics:Real-time package tracking and proof-of-delivery verification reduce dispute resolution overhead. Last-mile operators in California integrate automated injury-reporting modules to satisfy OSHA record-keeping mandates.
Field Service maintains the deepest installed base; Inspection & Auditing is gaining share fastest as regulatory documentation requirements proliferate.
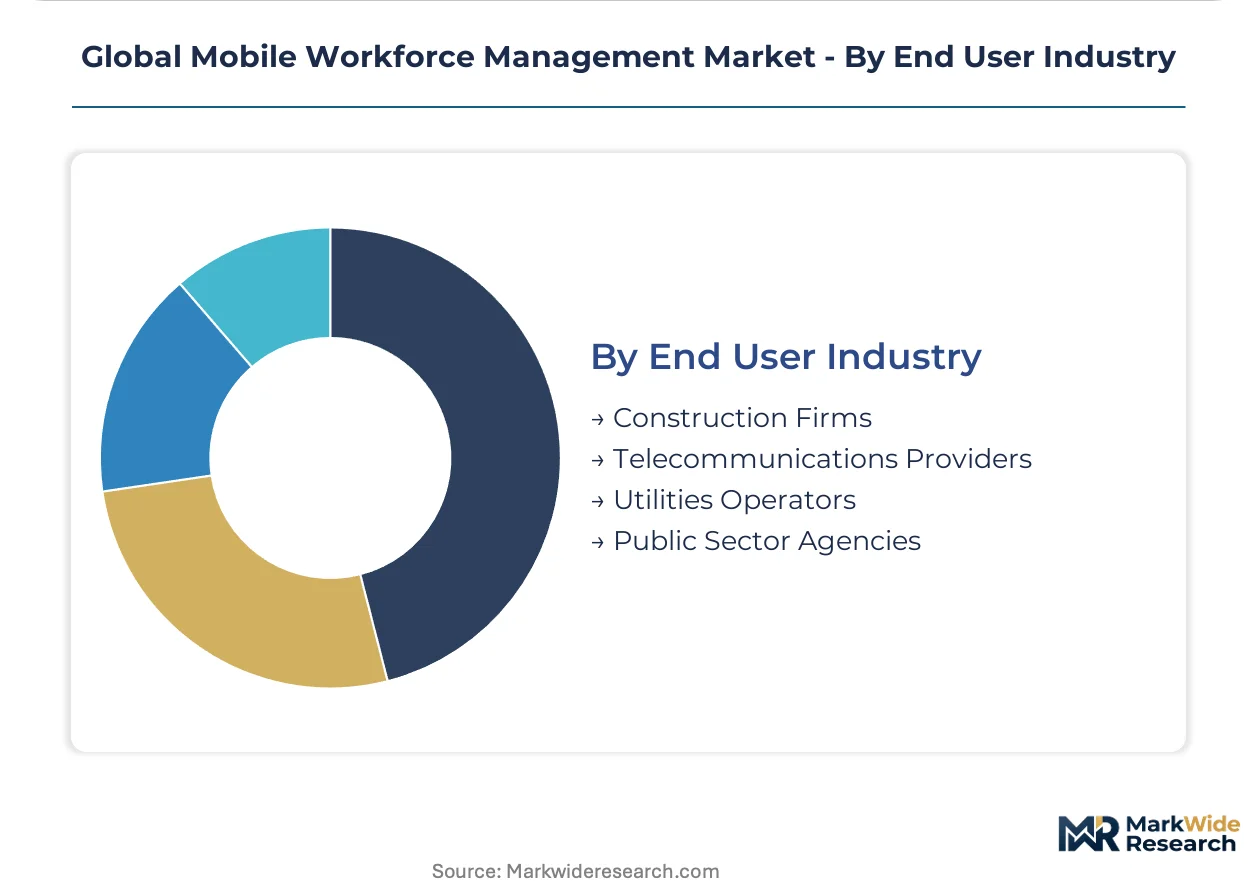
End User Industry:
Application-maturity variation separates digitally native telecommunications providers from laggard construction firms still migrating from paper logs.
- Construction Firms:Ruggedized devices with offline-sync capabilities maintain workforce coordination across remote job sites lacking reliable cellular coverage. OSHA mandates push automated injury-reporting adoption among US commercial contractors.
- Telecommunications Providers:5G network densification demands precise technician coordination across geographically dispersed cell towers. Verizon Wireless and peer carriers architect connectivity layers to FCC reliability guidelines for mission-critical field communications.
- Utilities Operators:Edge-computing dispatch nodes enable sub-50-millisecond rerouting decisions during power grid failures. German and French utilities deploy ruggedized servers at substations to maintain coordination during wide-area network disruptions.
- Public Sector Agencies:Audit-trail requirements for taxpayer-funded projects drive investment in biometric-verified activity logging. Indian state governments under PLI scheme implementation need multilingual platforms to manage electronics manufacturing workforce compliance.
Telecommunications Providers anchor current volume; Public Sector Agencies show the steepest expansion trajectory as government digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Germany, while deployment demand spreads across India and China where field service workforces digitize fastest. Consumption patterns diverge sharply between mature markets replacing legacy systems and emerging economies building mobile-first infrastructure.
United States
Telecommunications providers and utilities drive enterprise platform adoption as 5G densification and storm-recovery mandates intensify coordination requirements. FCC reliability guidelines shape carrier investment in mission-critical field connectivity layers. Texas-based oilfield contractors and California solar installers negotiate consumption-based SaaS terms with biometric verification modules.
Germany
Mechanical engineering service firms with 200-800 field technicians represent underpenetrated white-space for verticalized workforce platforms. The EU AI Act forces algorithmic transparency reengineering for automated scheduling systems deployed across European operations. Bavarian and Baden-Württemberg industrial clusters deploy edge-computing dispatch nodes at substations to maintain sub-50-millisecond rerouting during grid failures.
India
Electronics manufacturing contract facilities in Gujarat and Tamil Nadu need multilingual coordination platforms for inter-state technician rotations under the PLI scheme. TRAI mandates on data localization influence platform architecture decisions for telecom workforce deployments. Karnataka's tech corridor and Delhi-NCR service hubs anchor domestic software development while field operations digitize across manufacturing belts.
France
Water utilities favor on-premises installations to satisfy GDPR data-localization mandates for critical infrastructure protection. CNIL enforcement actions on workforce surveillance scope trigger collective bargaining negotiations over GPS tracking boundaries. Île-de-France and Auvergne-Rhône-Alpes utility operators conduct algorithmic impact assessments before deploying predictive overtime allocation tools.
United Kingdom
Field service operations pivot toward cloud-based scheduling platforms as remote work mandates and real-time compliance requirements intensify post-Brexit regulatory divergence. UKG leverages deep workforce management heritage to anchor enterprise accounts with complex union rules and shift differentials. London and Southeast England concentrate financial services adoption while Midlands manufacturing services lag in spreadsheet-based scheduling migration.
Global Mobile Workforce Management Market Competitive Landscape
Top-tier vendors anchor enterprise accounts with embedded ERP connectivity, while mid-market specialists compete on rapid SaaS deployment cycles. The vendor base stratifies across three functional tiers: workforce management heritage players, ERP-integrated platform providers, and IT service management extenders. Dominant competitive moves include strategic partnerships with telecommunications carriers and portfolio diversification into edge-computing dispatch architectures.
Within the workforce management heritage tier, UKG and ADP occupy positions anchored by union-rule engines and shift-differential automation. SAP AG exemplifies the ERP-integrated archetype through embedded connectivity extending workforce data into financial planning modules. ServiceNow sits within the IT service management extension category, layering incident-to-resolution workflows onto field operations for infrastructure maintenance teams.
| Leading Market Players |
|---|
| UKG |
| Verizon Wireless |
| ServiceNow |
| Workday |
| Trimble Inc. |
| SAP AG |
| ADP |
| Infor |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Biometric sensor costs originating from Taiwan semiconductor fabrication cascade through three distinct pricing tiers for ruggedized field devices, with premium modules commanding substantial markups over economy-grade alternatives as procurement timelines face geopolitical disruption risks.
Pricing Analysis
Margin tightening in SaaS subscription tiers reflects consumption-based billing models displacing perpetual licenses among North American construction and facilities management firms. Three-tier pricing structure across premium compliance engines, standard dispatch modules, and economy time-tracking tools differentiates by integration depth and union-rule engine sophistication. Cost compression accelerates in mid-market segments as agile cloud-native vendors force legacy on-premise providers into defensive discounting. Price sensitivity concentrates most acutely among mid-sized mechanical engineering service firms in Germany with 200-800 field technicians, while least sensitivity appears among defense contractors and nuclear utilities mandating air-gapped data sovereignty regardless of cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan semiconductor fabrication for fingerprint and facial recognition sensors essential to ruggedized field devices. Hardware assembly concentrates in China, Mexico, and Vietnam for device enclosure manufacturing and final integration. Raw material dependencies span rare earth elements for sensor magnetics, lithium-ion cells for extended battery operation, and reinforced polymers for impact-resistant casings. Tariff exposure on Chinese-manufactured components threatens procurement cost stability for North American platform vendors. Distribution runs through telecommunications carrier partnerships and direct enterprise sales forces, with carrier-integrated bundles gaining share among utilities and field service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as cloud-native deployment cycles compress from months to weeks, forcing legacy on-premise vendors into distressed exits or acquisition.
For Market Incumbents: Deploy edge-computing dispatch architectures to defend against cloud-native competitors attacking latency-sensitive utility accounts. Anchor enterprise relationships through embedded ERP connectivity extending workforce data into SAP and Oracle financial modules. Counter algorithmic transparency mandates from the EU AI Act by investing in explainable AI frameworks that document scheduling logic for labor inspectorate audits. For New Entrants and Emerging Players: Mid-sized German mechanical engineering service firms with spreadsheet-based scheduling present the most penetrable white-space for verticalized SaaS offerings with embedded union tariff engines. California solar installation firms negotiating month-to-month terms demonstrate appetite for consumption-aligned pricing among seasonal workforce operators. Pursue carrier-integrated go-to-market partnerships that bundle biometric verification modules with mission-critical field connectivity layers. For Investors and Strategic Acquirers: Distressed-cycle entries favor workforce management heritage platforms with complex union-rule engines and entrenched US utility accounts. Long-term viability hinges on regulatory compliance differentiation as GDPR audit mandates and EU AI Act transparency requirements intensify across European operations. Monitor algorithmic impact assessment adoption rates among German field service operators as the inflection signal for compliance-native vendor premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Dispatch Deployment | Sub-50-millisecond rerouting capabilities satisfy German utility requirements for grid failure response. |
| Union Tariff Engine Development | Embedded shift differential automation secures US utility accounts with complex collective bargaining agreements. |
| Biometric Hardware Supply Diversification | Multi-source sensor procurement mitigates Taiwan concentration risk for ruggedized device manufacturers. |
| EU AI Act Compliance Module Launch | Human-readable decision logs unlock European public sector procurement requiring algorithmic transparency. |
| Carrier Connectivity Partnership | FCC-guided reliability layers differentiate mission-critical field communications for telecommunications providers. |
Research Methodology
Document review covered SEC filings from workforce management vendors, EU regulatory impact assessments, and telecommunications infrastructure deployment databases, complemented by interviews with CTOs at field service operators, IT procurement officers at utilities, platform integration specialists, and union labor relations directors. Secondary validation drew from FCC reliability guidelines, GDPR enforcement actions by European data protection authorities, and India's PLI scheme implementation reports. Bottom-up technician deployment modeling and top-down enterprise software spending analysis provided triangulation across demand estimation approaches.
Market size outputs reflect segmentation across deployment models, solution types, end-user industries, and geographic adoption patterns throughout the forecast period. Modeled dimensions spanned cloud-based versus hybrid architectures, scheduling and dispatch versus compliance management solutions, and telecommunications versus utilities versus public sector verticals. CAGRs derived from historical enterprise SaaS transition rates and field service digitization intensity indices, with specific inputs including 5G network densification technician deployment schedules and EU AI Act implementation timelines.
Revisions become necessary when semiconductor supply disruptions extend procurement timelines, when labor classification rules in California or Germany restructure gig-economy dispatch legality, or when edge-computing hardware costs decline faster than modeled. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Australia ICT Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Digital Assurance Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Echo Reduction Software Market