
 Supply Side Platform (SSP) Market | 2026-2036
Supply Side Platform (SSP) Market Size, Share, and Industry Trends Forecast 2026-2036
Supply Side Platform (SSP) Market Analysis
Buyer concentration among large digital publishers is consolidating as premium media properties merge and centralize their ad inventory management. Magnite leverages its scale across connected television and display formats to sustain competitive positioning. PubMatic differentiates through specialized yield optimization tools for mobile and streaming publishers. Index Exchange anchors its presence in header bidding infrastructure for North American news and entertainment properties.
A Supply Side Platform is a programmatic advertising technology that enables digital publishers to manage, sell, and optimize their ad inventory through automated auctions, typically integrating with multiple demand sources via real-time bidding protocols and header bidding wrappers. Its primary commercial purpose is to maximize publisher revenue by exposing inventory to competing advertisers while maintaining control over pricing floors and audience data parameters. Cloud-based deployment dominates structural investment as publishers prioritize elastic infrastructure that scales with traffic spikes during live events and seasonal campaigns. Header bidding technology leads transaction volume growth by replacing sequential waterfall models with simultaneous demand source competition. Real-time bidding segments retain mature liquidity pools where established advertisers commit programmatic budgets through guaranteed deal structures.
The Federal Trade Commission enforces consumer protection standards that constrain data collection practices in US-based programmatic transactions, while the European Union's GDPR mandates explicit consent mechanisms for audience targeting across EU publisher inventory. The Federal Communications Commission oversees broadband infrastructure policies that indirectly shape streaming ad delivery capacity and latency requirements for SSP integrations. Stakeholders must monitor evolving state privacy legislation and platform self-regulation to anticipate compliance costs and inventory valuation shifts.
Market Dynamics
Header bidding infrastructure is displacing sequential waterfall ad serving across digital publisher stacks, compressing latency requirements while expanding simultaneous demand source competition. This architectural shift concentrates investment in elastic cloud infrastructure and real-time data processing capabilities.
Growth Catalysts
- Connected Television Expansion:Streaming publishers in the United States and Japan are deploying SSP integrations to monetize over-the-top inventory through programmatic pipes.
- GDPR Consent Frameworks:The European Union's explicit consent mechanisms are standardizing audience data protocols, reducing compliance fragmentation for cross-border inventory sales.
- Cloud Infrastructure Elasticity:Programmatic traffic spikes during live sporting events and seasonal retail windows are driving publisher migration from on-premise ad servers to auto-scaling deployments.
Market Restraints
- Identity Deprecation Costs:Third-party cookie phase-out in Chrome and Safari is forcing publishers to rebuild audience targeting infrastructure without standardized replacement identifiers.
- Supply Concentration Risk:Buyer consolidation among large holding companies and walled garden platforms concentrates pricing power in a handful of demand-side aggregators.
- Technical Latency Floors:Header bidding wrapper complexity introduces auction timeout constraints that cap the number of demand partners publishers can integrate profitably.
Strategic Opportunities
- Retail Media Networks:First-party commerce data from grocery and electronics retailers is creating closed-loop attribution capabilities that premium CPG advertisers will pay margin premiums to access.
- Privacy-Enhancing Technologies:Differential privacy and on-device processing are converging to enable cohort-based targeting without individual-level data transmission.
- State-Level Privacy Patchwork:The California Consumer Privacy Act and emerging state laws in Virginia and Colorado are creating compliance service demand from mid-market publishers lacking in-house legal technology teams.
Industry Challenges
- Ad Operations Talent Scarcity:Yield optimization engineering and programmatic direct sales functions require hybrid technical-commercial skill sets that command premium compensation in competitive labor markets.
- Legacy Integration Friction:Direct-sold insertion order workflows and programmatic guaranteed pipes operate on incompatible data standards, forcing publishers to maintain parallel operational teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supply Side Platform (SSP) Market |
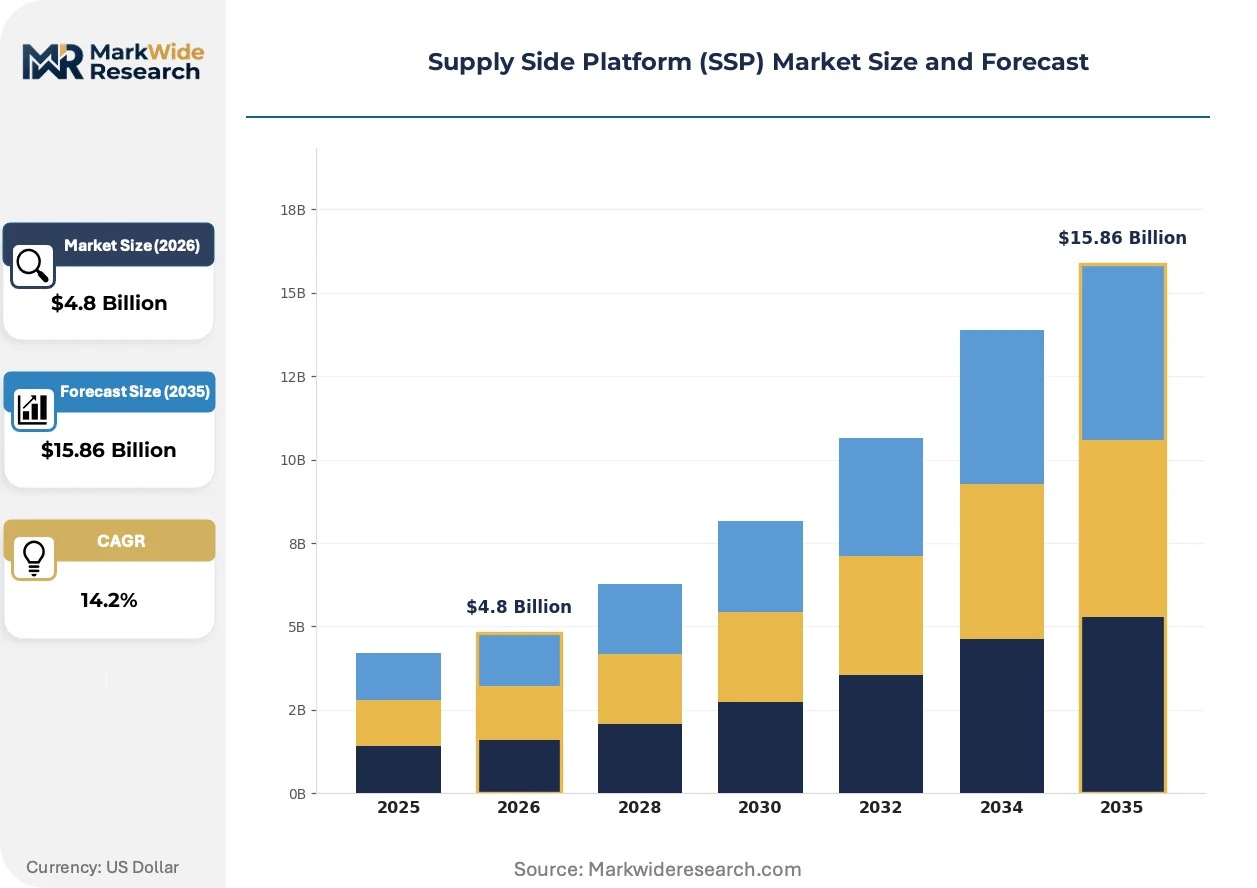
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Advertisers, Publishers, Agencies, Ad Networks Technology: Header Bidding, Real-Time Bidding, Programmatic Advertising, Data Management Platforms Payment Model: Cost Per Mille, Cost Per Click, Cost Per Action, Subscription |
| Companies Covered | Magnite, Sovrn, Google Ad Manager, FreeWheel, Equativ, OpenX, Index Exchange, Admixer, PubMatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Side Platform (SSP) Market Emerging Trajectories
Programmatic infrastructure is fragmenting into specialized components as publishers demand granular control over auction mechanics and data leakage prevention. This decomposition is accelerating vendor specialization and interoperability standardization efforts.
Server-side header bidding is modularizing publisher ad stack architecture by shifting auction computation from client browsers to cloud-hosted containers. Mid-sized news and entertainment properties are adopting this approach to reduce page load degradation. The technology is compressing the competitive advantage previously held by vendors with proprietary wrapper codebases.
The European Union's Digital Services Act is imposing transparency mandates on algorithmic content recommendation and ad targeting systems. Publishers serving EU audiences must now document automated decision-making logic for regulatory audit. News media properties with significant European traffic are responding by segregating inventory pools and consent flows by jurisdiction.
Buyer concentration among programmatic direct teams is compressing sales cycle timelines and unbundling traditional agency-of-record relationships. Large advertisers are building in-house trading desks that negotiate directly with publisher SSPs, bypassing media agency intermediaries. This pattern is most visible in the United States where Fortune 500 CPG and automotive brands have invested dedicated programmatic operations centers.
Supply Side Platform (SSP) Market Segmentation
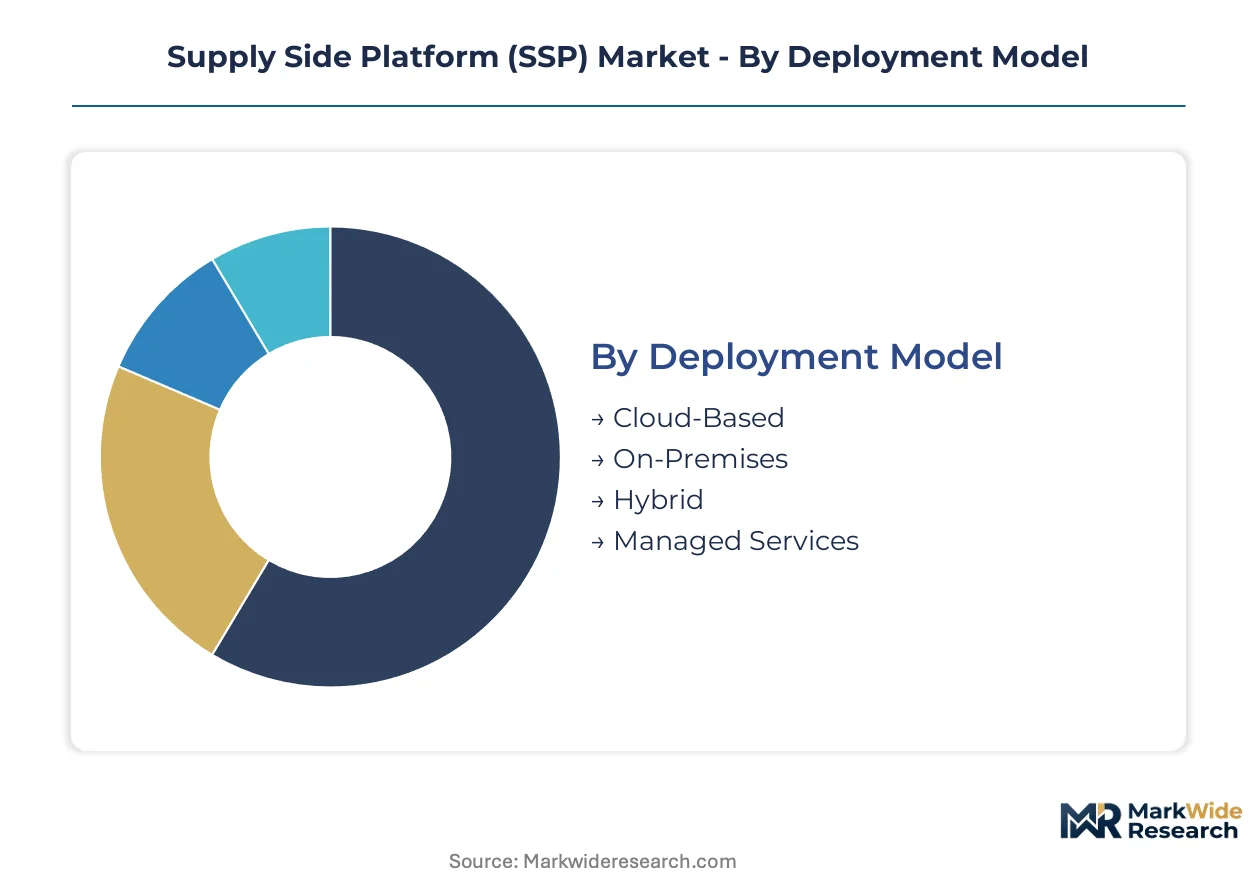
SSP architectures fragment across infrastructure choices, buyer types, auction mechanisms, and pricing structures. Each segmentation axis carries distinct margin profiles and technical requirements that reshape vendor competitive positioning.
Deployment Model:
Cloud-native infrastructure dominates publisher migration patterns as elastic compute replaces fixed-capacity ad serving.
- Cloud-Based:Auto-scaling container orchestration handles traffic spikes during live sports and retail events without pre-provisioned hardware. Mid-sized news publishers in the United States and Japan prioritize this model to avoid capital expenditure on peak-capacity infrastructure that sits idle between campaigns.
- On-Premises:Dedicated server clusters in publisher data centers maintain sub-millisecond auction latency for premium video inventory. Large broadcasters with existing infrastructure investments in the United Kingdom retain this deployment to preserve direct control over audience data residency.
- Hybrid:Split architectures route standard display through cloud pipes while reserving on-premise capacity for high-value connected television auctions.
- Managed Services:Third-party operations teams handle yield optimization and demand partner integration for publishers lacking programmatic expertise.
Cloud-Based leads on scale; Hybrid leads on momentum as publishers balance flexibility with control.
End User:
Buyer concentration among large inventory holders is compressing vendor pricing power and consolidating platform selection authority.
- Publishers:Digital media properties from news organizations to streaming services deploy SSPs to monetize display, video, and connected television inventory through unified auction layers. Publisher demand concentrates among mid-market properties in the United States seeking to replace legacy waterfall ad serving with header bidding infrastructure.
- Advertisers:Brand direct teams at Fortune 500 CPG and automotive companies build in-house trading desks that negotiate programmatic guaranteed deals directly with publisher platforms, bypassing agency intermediaries.
- Agencies:Media buying groups aggregate demand across multiple advertiser clients to secure preferred inventory access and volume-based rate discounts.
- Ad Networks:Intermediary aggregators pool remnant inventory from smaller publishers to achieve minimum viable scale for demand-side platform access.
Publishers lead on scale; Advertisers lead on momentum as direct procurement accelerates.
Technology:
Auction mechanism innovation is displacing sequential ad serving and concentrating investment in real-time data processing capabilities.
- Header Bidding:Simultaneous demand source competition replaces waterfall priority sequences, compressing latency requirements while expanding advertiser pool exposure. Header bidding adoption accelerates among United States news and entertainment properties seeking to maximize yield per impression through increased auction density.
- Real-Time Bidding:Millisecond-level auction protocols connect publisher inventory to demand-side platform bid streams through standardized OpenRTB specifications. Established liquidity pools in North American markets support guaranteed deal structures where committed advertiser budgets secure priority inventory access.
- Programmatic Advertising:Automated transaction layers integrate direct-sold campaigns with auction-based demand through unified workflow management.
- Data Management Platforms:Audience segmentation and activation tools enable first-party data monetization without third-party cookie dependencies.
Real-Time Bidding leads on scale; Header Bidding leads on momentum as infrastructure displacement accelerates.
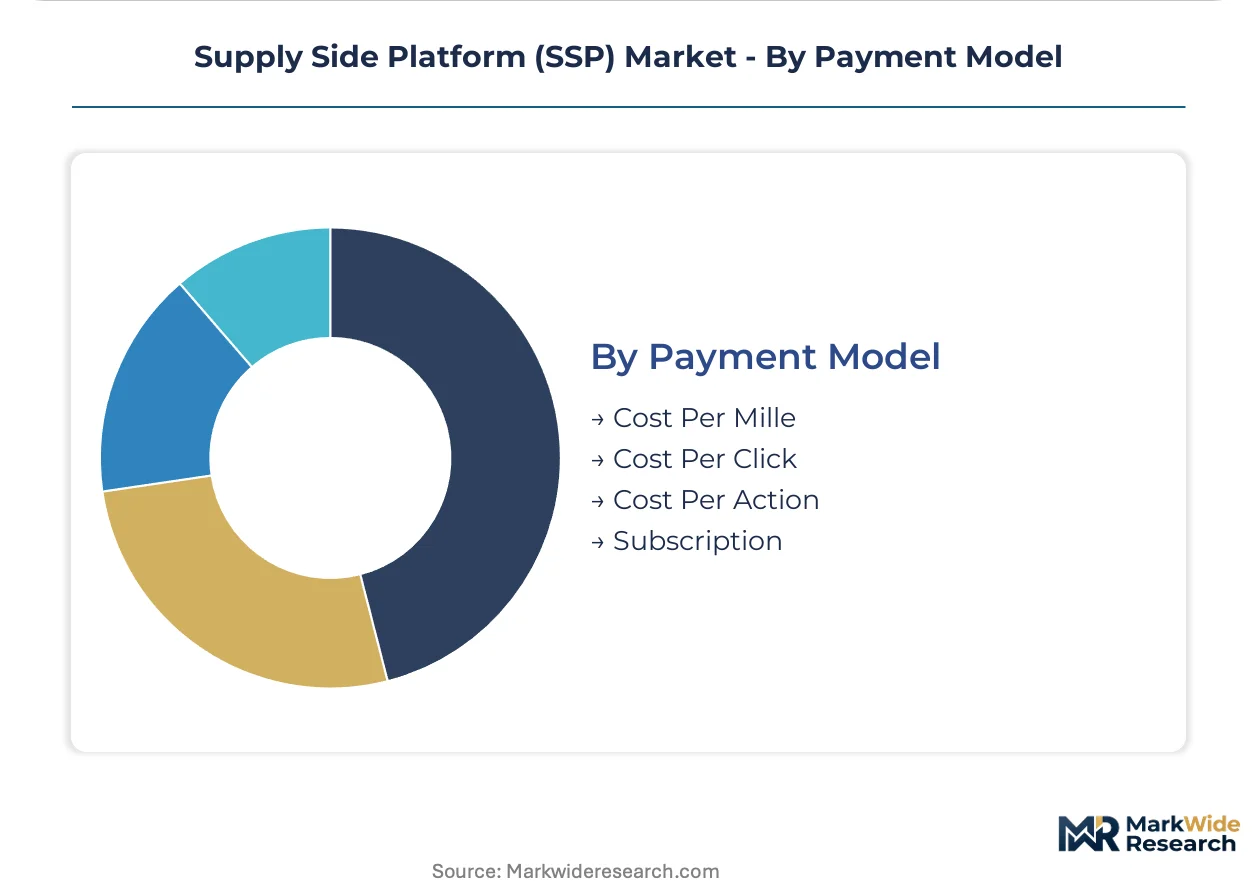
Payment Model:
Revenue calculation methods align platform incentives with advertiser outcome preferences and publisher risk tolerance.
- Cost Per Mille:Fixed-rate impression pricing dominates brand awareness campaigns where reach volume outweighs engagement depth. CPM structures prevail in United Kingdom and Japanese markets with mature brand advertising traditions and established viewability measurement standards.
- Cost Per Click:Performance-based pricing shifts inventory risk to publishers while aligning platform fees with documented user engagement. CPC models gain traction among direct-response advertisers in the United States seeking measurable downstream conversion signals.
- Cost Per Action:Outcome-contingent pricing ties platform compensation to verified conversions, registrations, or purchases.
- Subscription:Flat-rate SaaS fees replace transaction-based revenue for publishers prioritizing cost predictability over performance alignment.
Cost Per Mille leads on scale; Cost Per Action leads on momentum as attribution capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States publishers deploy header bidding infrastructure at faster rates than Japanese broadcasters, though Tokyo-based streaming services now match North American latency benchmarks for connected television auctions.
United States
Fortune 500 CPG brands and automotive manufacturers operate in-house trading desks that negotiate directly with publisher platforms. The Federal Trade Commission enforces consumer protection standards constraining data collection practices across programmatic transactions. New York and Los Angeles media clusters concentrate premium inventory pools where direct-sold insertion orders integrate with programmatic guaranteed pipes.
United Kingdom
News media properties with significant European traffic segregate inventory pools by jurisdiction to manage consent complexity. GDPR mandates explicit consent mechanisms for audience targeting across EU publisher inventory. London-based broadcasters retain on-premise infrastructure investments to preserve direct control over audience data residency for premium video auctions.
Japan
Streaming publishers deploy SSP integrations to monetize over-the-top inventory through programmatic pipes during live sporting events. The country's national telecommunications regulator oversees broadband infrastructure policies shaping streaming ad delivery capacity and latency requirements. Tokyo and Osaka metropolitan areas host concentrated demand from mid-market properties replacing legacy waterfall ad serving with header bidding infrastructure.
Germany
Industrial publishers prioritize elastic cloud infrastructure that scales with traffic spikes during seasonal manufacturing campaigns. GDPR standardizes audience data protocols, reducing compliance fragmentation for cross-border inventory sales. Munich and Hamburg media clusters develop sophisticated programmatic infrastructure for automotive and machinery sector advertising.
India
Mid-market digital publishers seek yield optimization tools as mobile advertising volumes expand across regional language content. The country's national telecommunications regulator governs data localization requirements affecting cross-border audience data transmission. Bangalore and Mumbai technology corridors concentrate vendor development centers supporting cloud-native SSP deployments for emerging market publishers.
Supply Side Platform (SSP) Market Vendor Landscape
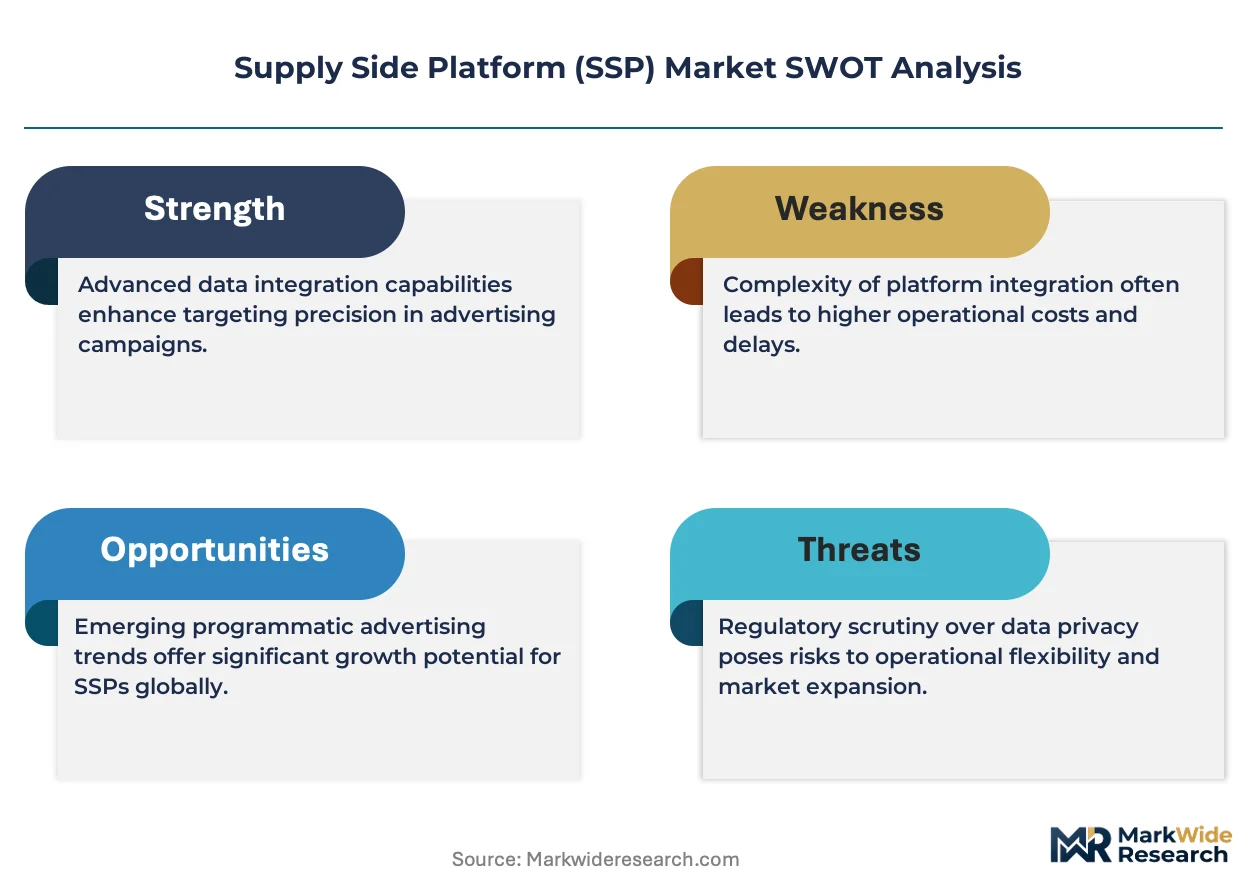
Diversified conglomerates compete with focused pure-play specialists across the SSP landscape, creating a tiered structure where scale advantages clash with vertical expertise. Large technology holding companies leverage cross-platform data assets to bundle advertising services, while independent platforms differentiate through specialized auction mechanics. Two strategic archetypes dominate: infrastructure-heavy vendors optimizing header bidding latency and yield-focused specialists maximizing revenue per impression. Competitive moves concentrate on strategic partnerships with demand-side platforms and geographic expansion into connected television markets.
Among independent specialists, Magnite and PubMatic occupy positions exemplifying divergent specialization paths, while Index Exchange anchors the header bidding infrastructure tier for North American publishers. These three represent distinct competitive postures within a vendor base that fragments across deployment models, auction mechanisms, and geographic footprints.
| Leading Market Players |
|---|
| Magnite |
| Sovrn |
| Google Ad Manager |
| FreeWheel |
| Equativ |
| OpenX |
| Index Exchange |
| Admixer |
| PubMatic |
| Others |
Supply Flow & Price Mechanics
Horizontal integration into cloud infrastructure partnerships anchors both supply resilience and pricing power for SSP vendors serving traffic-spike-dependent publishers. This structural choice feeds from elastic compute commitments in United States and Japanese data center clusters, where capacity pre-positioning against live sporting events and seasonal retail windows determines margin compression tolerance.
Pricing Analysis
Capacity additions in United States cloud regions are reshaping price floors for SaaS-tiered platform subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by auction volume throughput and dedicated yield engineering support. Cost compression in the mid-tier is intensifying because hyperscaler compute commoditization erodes infrastructure differentiation. Mid-market news publishers exhibit highest price sensitivity; large broadcasters with in-house trading desks demonstrate lowest.
Supply Chain Analysis
Freight costs for hardware components remain negligible given software-dominant delivery, yet cross-border data transmission tariffs between United States and European Union jurisdictions shape operational expenditure. Supply concentrates in United States, United Kingdom, and Japan for platform development talent and demand-side liquidity pools. Raw material dependencies center on semiconductor chips for server infrastructure, fiber optic capacity for latency-sensitive auctions, and renewable energy contracts for carbon-neutral data center operations. Single-source vulnerability runs through hyperscaler cloud concentration. Distribution runs through direct enterprise sales teams and self-serve onboarding portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States and European Union compliance costs creates margin expansion for vendors with modular consent architecture. The Federal Trade Commission enforcement intensity against data collection practices runs lower than GDPR penalty exposure, favoring US-domiciled infrastructure investments.
For Market Incumbents: Anchor competitive position through backward integration into proprietary identity resolution graphs as third-party cookie deprecation threatens targeting precision. Defend against emerging clean-room data collaborators by securing exclusive first-party data partnerships with Fortune 500 CPG brands. Capacity additions in Tokyo and London cloud regions should parallel demand-side platform integration investments. For New Entrants and Emerging Players: Launch via API-first distribution targeting mid-market Indian publishers replacing legacy waterfall ad serving with header bidding infrastructure. White-space concentrates in privacy-enhancing technology modules for state-level compliance patchwork across Virginia, Colorado, and emerging US jurisdictions. Retail media network adjacencies offer the most penetrable vertical given closed-loop attribution premiums. For Investors and Strategic Acquirers: Roll-up economics work for specialized yield optimization vendors because buyer concentration among large publishers creates procurement standardization pressure. Long-term viability over the next decade hinges on connected television auction infrastructure ownership. Watch server-side header bidding adoption velocity as inflection indicator for wrapper technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Header bidding wrapper consolidation with demand-side platform APIs reduces latency for United States news publishers. |
| Geographic Expansion | Tokyo and Osaka data center presence captures Japanese streaming publisher monetization during live sporting events. |
| Strategic Partnership | Retail media network alliances with grocery chains unlock closed-loop attribution for CPG advertisers. |
| Acquisition of Specialist Firm | Privacy-enhancing technology targets fill compliance gaps for mid-market publishers under state-level patchwork laws. |
| Product Launch | Server-side header bidding containers reduce page load degradation for mid-sized entertainment properties. |
Methodological Framework
Direct dialogue with yield optimization engineers, programmatic direct sales directors, cloud infrastructure procurement officers, and regulatory compliance counsel grounded the qualitative foundation. Secondary validation drew from SEC filings of publicly traded ad tech vendors, IAB technical specifications, GDPR enforcement decision databases, and hyperscaler capex disclosures. Bottom-up publisher adoption modeling and top-down programmatic spend aggregation provided triangulation.
Segmentation outputs across deployment model, end user archetype, auction mechanism technology, and payment structure fed into elasticity-adjusted projections over the analysis window. CAGRs derived from historical infrastructure investment patterns and regulatory compliance cost trajectories. Forecast inputs incorporated header bidding adoption curves and connected television inventory expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated third-party cookie deprecation or abrupt state privacy legislation cascades. A model refresh is warranted upon material change in identity resolution technology viability or demand-side platform consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Online Voting System Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Product Information Management Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Business As a Service Market