
 Semiconductor Sensor Market | 2026-2036
Semiconductor Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Sensor Market Intelligence
The migration from discrete sensing elements to system-in-package architectures is reconfiguring how semiconductor sensors integrate with edge computing modules. STMicroelectronics leverages its MEMS foundry scale to anchor supply for consumer and automotive inertial units. Bosch Sensortec dominates environmental and inertial portfolios through captive manufacturing in Reutlingen. Texas Instruments competes with precision signal-conditioning ICs that bridge analog front-ends to digital outputs.
Semiconductor sensors are solid-state transducers that convert physical quantities—temperature, pressure, light, or proximity—into electrical signals through piezoresistive, photodiode, or capacitive mechanisms, typically fabricated on silicon wafers using CMOS-compatible processes with feature nodes ranging from 180 nm to 40 nm depending on integration complexity. Their primary purpose is to enable real-time monitoring and closed-loop control in electromechanical systems. Pressure sensors and MEMS-based inertial units represent the most mature volume categories where pricing has compressed and margin pools have shifted toward calibration software and fusion algorithms. Optical sensing and digital temperature interfaces are expanding fastest in wearable devices and battery thermal management where resolution requirements tighten.
The EPA tailpipe standards and NHTSA safety mandates in the United States, alongside the EU Green Deal and REACH substance restrictions, are elevating sensor accuracy requirements for emissions monitoring and material traceability. Japan's METI energy-efficiency directives and China's GB standards for automotive electronics further fragment certification pathways, forcing suppliers to maintain multiple qualified product variants. Stakeholders must decide whether to absorb compliance costs across broad portfolios or concentrate R&D on jurisdictions with the most stringent and transferable standards.
Market Dynamics
The semiconductor sensor market is reconfiguring around system-in-package architectures that fuse MEMS elements with edge AI inference engines, compressing the traditional discrete component supply chain into vertically integrated module production.
Growth Catalysts
- EU Green Deal vehicle emissions mandates:OEMs in Germany and France must deploy high-precision NOx and particulate sensors to meet Euro 7 standards, accelerating replacement cycles for legacy exhaust monitoring hardware.
- Automotive battery thermal runaway detection:Cell-level temperature and pressure sensing is becoming mandatory in electric vehicle battery packs, pulling silicon carbide-based sensor interfaces into high-volume production.
- Japan METI energy-efficiency directives:Industrial motor systems must integrate real-time load sensing to qualify for subsidy programs, expanding demand for current and torque sensors in precision manufacturing clusters.
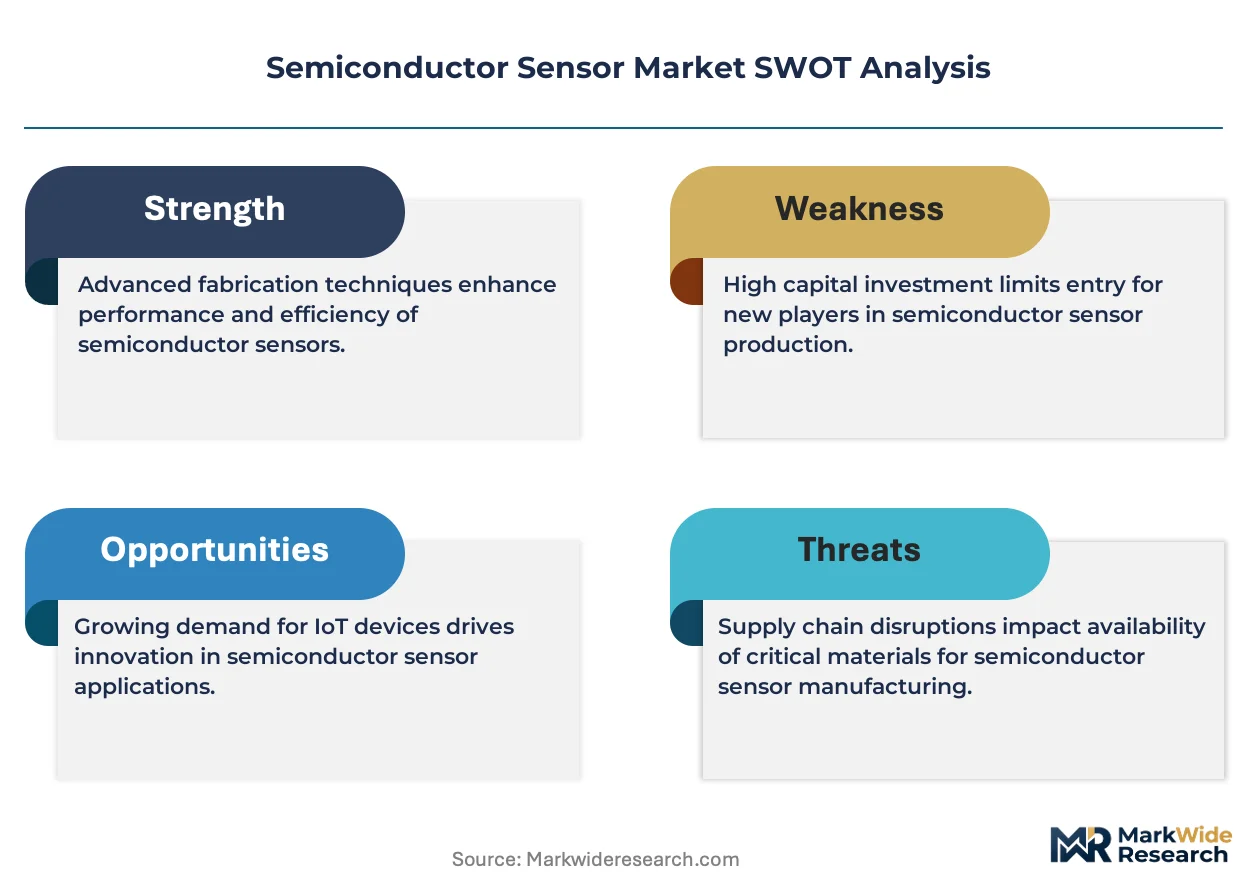
Market Restraints
- 200mm silicon wafer supply concentration:Foundry capacity for sensor-grade CMOS processes concentrates in Taiwan and South Korea, creating allocation risk during automotive demand surges.
- Palladium and platinum input volatility:Exhaust gas sensors require precious metal catalysts whose prices fluctuate with automotive production cycles and mining supply disruptions.
- REACH substance restrictions:ECHA limitations on lead-based piezoelectric materials force redesigns of mature pressure sensor architectures, extending qualification timelines for European automotive certifications.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component-level sensor production incentives are attracting MEMS packaging investments to serve domestic automotive and smartphone assembly.
- Sensor fusion with UWB and radar:Converging proximity sensing technologies are enabling new indoor positioning and occupancy detection applications in smart building infrastructure.
- China GB standards for autonomous driving:Mandatory LiDAR and camera redundancy requirements are creating certified supplier slots for environmental sensing modules in domestic EV platforms.
Industry Challenges
- Multi-jurisdiction certification backlogs:Simultaneous EPA, ECHA, and NMPA qualification timelines for automotive exhaust sensors extend product launch windows by 18-24 months.
- MEMS process engineer scarcity:Specialized expertise in wafer-level packaging and vacuum sealing concentrates in Reutlingen, Dresden, and Hsinchu, constraining foundry expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Sensor Market |
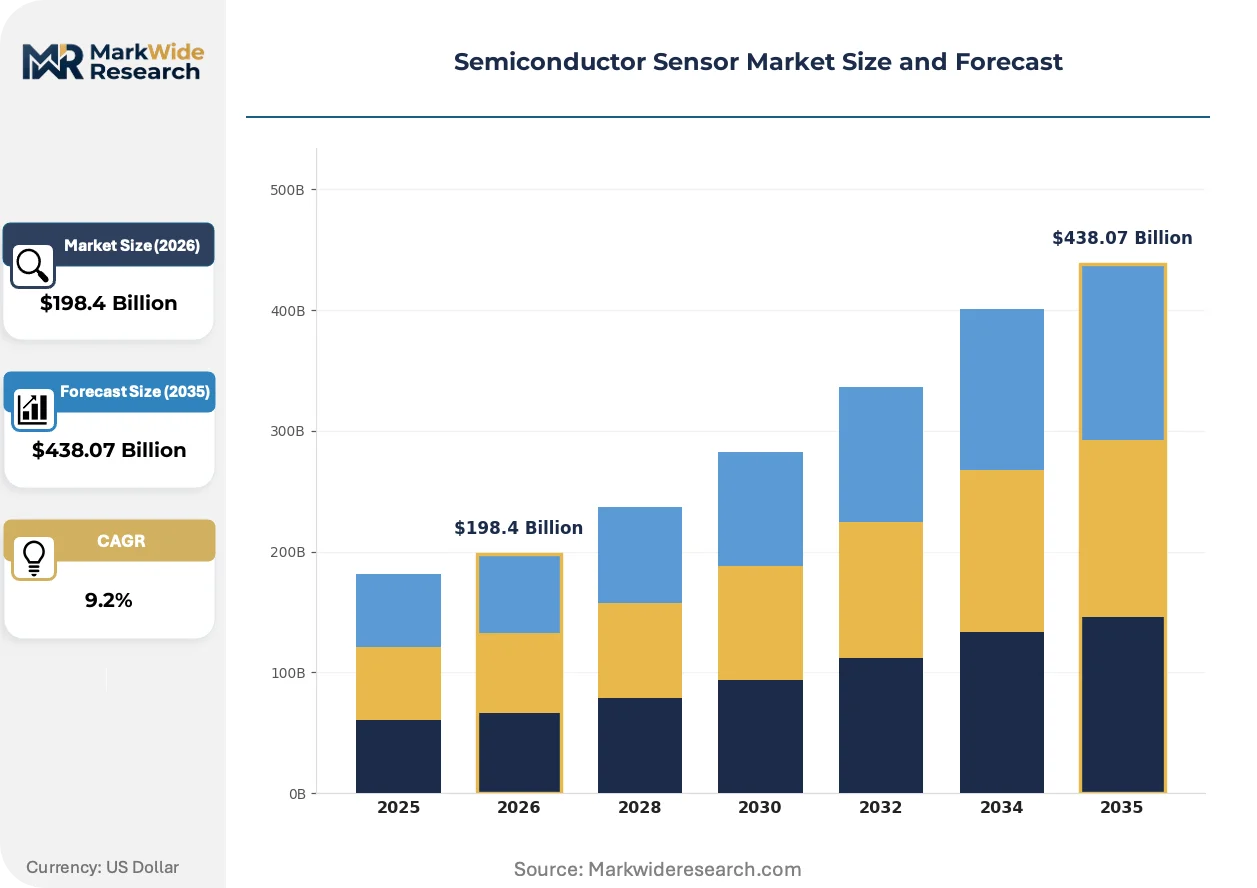
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $438.07 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Light Sensors, Proximity Sensors Technology: Analog, Digital, MEMS, Optical End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Application: Smart Homes, Wearable Devices, Robotics, Aerospace |
| Companies Covered | STMicroelectronics, Bosch Sensortec, Texas Instruments, OmniVision Technologies, Sony Semiconductor Solutions, NXP Semiconductors, Infineon, Advantest, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Sensor Market Strategic Shifts & Innovations
Integration density is accelerating as sensor modules absorb signal conditioning, calibration, and wireless connectivity functions that previously required separate board-level components. This consolidation is redrawing competitive boundaries between discrete suppliers and system architects.
Time-of-flight optical arrays are migrating from discrete photodiode assemblies to integrated SPAD-based modules with on-chip histogram processing. Smartphone camera autofocus and automotive in-cabin monitoring systems are adopting these devices at scale. The shift is compressing margins for standalone proximity sensor vendors while concentrating value in CMOS image sensor foundries with 3D stacking capabilities.
EPA tailpipe standards and NHTSA safety mandates are tightening allowable variance windows for emissions and crash detection sensors. Manufacturers must now demonstrate traceable calibration chains from wafer test to vehicle assembly. This regulatory pressure is favoring suppliers with captive metrology labs in Michigan and Stuttgart over fabless competitors dependent on third-party qualification.
Fleet operators and industrial asset managers are consolidating sensor procurement under long-term sensor-as-a-service contracts that bundle hardware, calibration, and predictive analytics. Oil and gas majors in Texas and the North Sea are piloting these arrangements for corrosion monitoring networks. The model shifts capital expenditure to operational budgets while locking in multi-year supplier relationships that disadvantage spot-market component vendors.
Semiconductor Sensor Market Segmentation
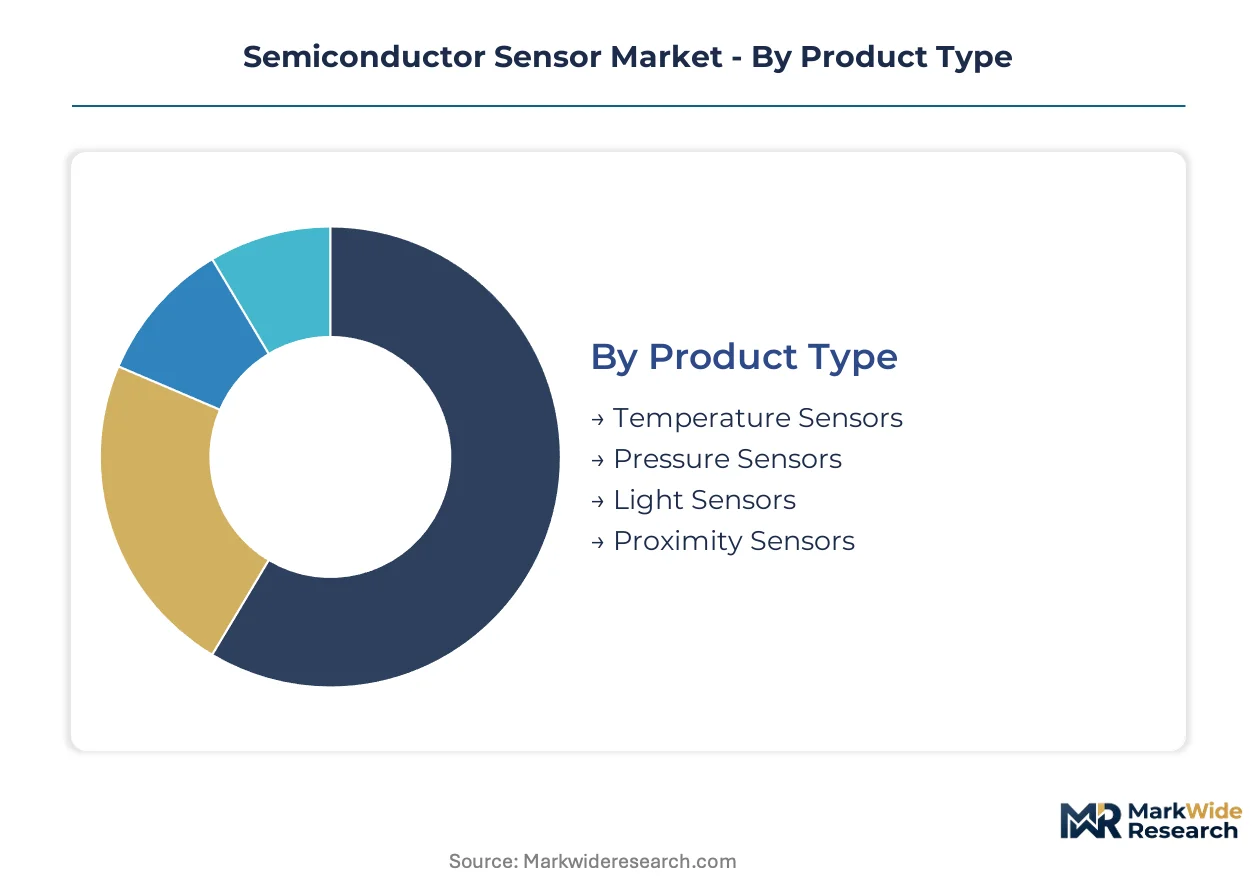
Semiconductor sensor architectures fragment across four intersecting dimensions that determine pricing power and qualification complexity. Product type and technology choices lock in manufacturing processes, while end-user concentration and application specificity dictate margin structures and certification pathways.
Product Type:
Mature categories dominate unit volumes while emerging variants capture design wins in next-generation platforms.
- Pressure Sensors:Piezoresistive and capacitive MEMS elements fabricated on 200mm silicon wafers measure absolute, differential, and gauge pressures. Automotive powertrain and industrial process control in Germany absorb the bulk of high-precision output, driven by Euro 7 emissions mandates requiring exhaust backpressure accuracy within 0.1% full scale.
- Temperature Sensors:Digital interfaces with I2C and SPI outputs displace legacy thermistor networks in battery management systems. South Korean EV manufacturers and Japanese industrial motor suppliers are pulling silicon-based temperature sensing into high-voltage isolation architectures.
- Light Sensors:Ambient light and color sensors integrate photodiode arrays with on-chip ADC conversion for display backlight control.
- Proximity Sensors:Capacitive and inductive proximity detection serves industrial safety interlocks and consumer gesture recognition.
Pressure sensors handle the majority of throughput; temperature sensors are the fastest mover on share.
Technology:
Cost tier stratification separates commodity analog from premium digital and optical integration.
- MEMS:Microelectromechanical systems fuse mechanical sensing structures with CMOS readout circuits through wafer-level bonding processes. Bosch Sensortec's captive Reutlingen foundry and STMicroelectronics' Agrate Brianza facility anchor supply for automotive inertial and pressure units, with Taiwan packaging houses handling final test and calibration.
- Optical:SPAD arrays and time-of-flight photonic front-ends require 40nm CMOS image sensor foundry access with 3D stacking capabilities. Smartphone camera modules and automotive LiDAR in China are pulling optical sensing into the fastest-expanding technology tier.
- Analog:Voltage-output transducers with external signal conditioning persist in cost-sensitive industrial applications.
- Digital:Pre-calibrated sensors with embedded compensation algorithms reduce host processor overhead in wearable and IoT endpoints.
MEMS technology commands the dominant revenue position; optical platforms are expanding most quickly in design-win velocity.
End User:
Application concentration determines margin structure, with automotive qualification commanding premium pricing over consumer volume plays.
- Automotive:Battery thermal runaway detection, exhaust gas monitoring, and ADAS inertial units require AEC-Q100 qualification and PPAP documentation. German OEMs and Chinese EV platforms are mandating cell-level temperature and pressure sensing, pulling silicon carbide interfaces into high-volume production.
- Consumer Electronics:Smartphone inertial measurement units, wearable biometric monitors, and hearable proximity detection prioritize miniaturization and power efficiency over absolute accuracy.
- Industrial Automation:Motor current sensors, pneumatic pressure monitors, and machine vibration accelerometers serve predictive maintenance networks.
- Healthcare:Continuous glucose monitors, pulse oximeters, and diagnostic imaging sensors face FDA and NMPA biocompatibility requirements.
Automotive end-use captures the steepest margin tier; consumer electronics delivers the highest unit velocity.
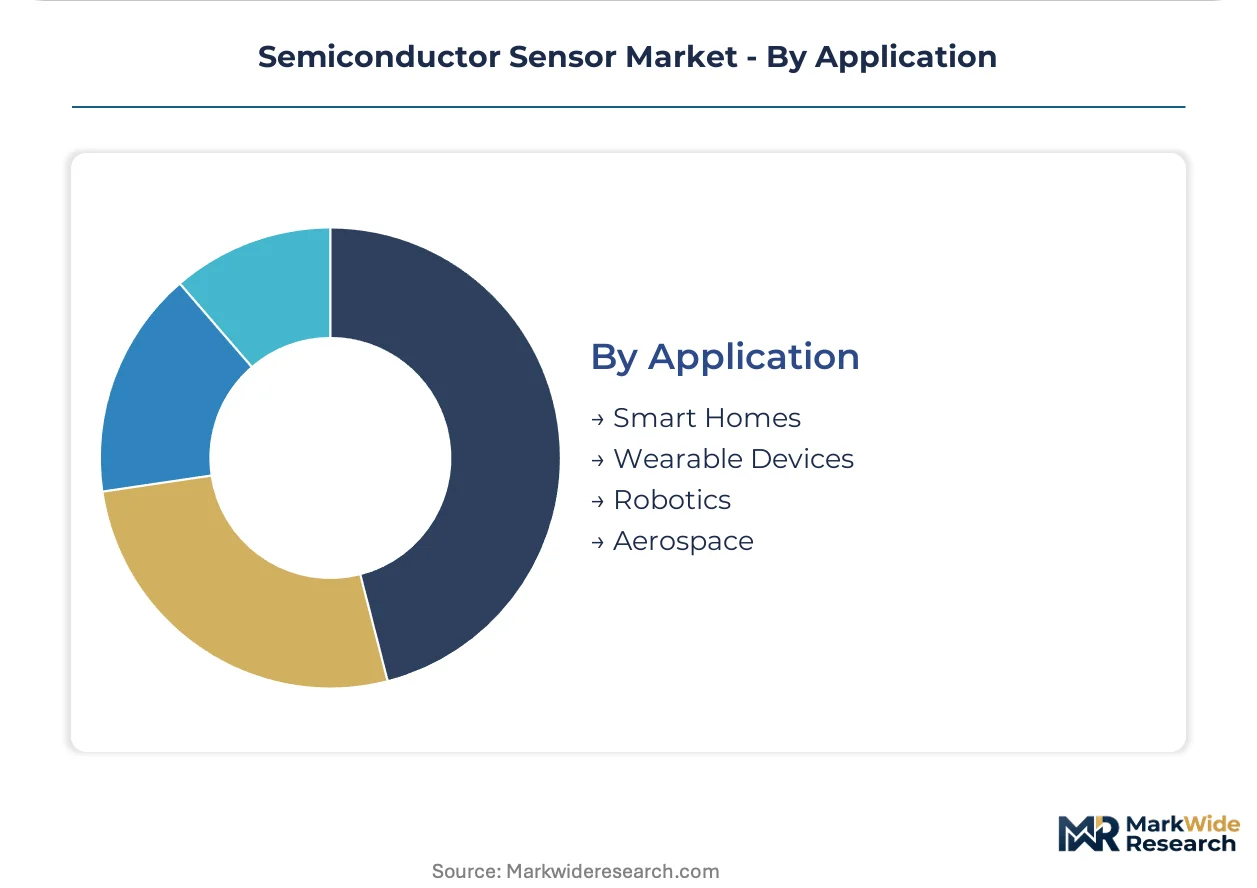
Application:
Geography-specific deployment patterns separate established smart home markets from emerging robotics and aerospace qualification tracks.
- Wearable Devices:Skin temperature, SpO2, and accelerometer fusion in fitness bands and smartwatches demands sub-milliwatt power budgets. Apple and Samsung supplier ecosystems in South Korea and Taiwan are driving optical heart-rate module integration.
- Smart Homes:Occupancy detection, air quality monitoring, and HVAC control sensors connect through Matter and Zigbee protocols.
- Robotics:Force-torque sensors, LiDAR navigation, and tactile skin arrays serve collaborative robot arms and autonomous mobile platforms.
- Aerospace:High-reliability pressure and inertial units for flight control and environmental monitoring require DO-178C and DO-254 certification.
Wearable devices anchor current volume deployment; robotics applications are climbing the fastest on new project initiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and precision manufacturers cluster demand in Germany, Japan, South Korea, China, and the United States. Each geography anchors distinct sensor applications through regulatory mandates and industrial specialization.
Germany
Exhaust gas monitoring and battery management systems drive sensor procurement from BMW, Volkswagen, and Mercedes-Benz. Euro 7 standards mandate NOx and particulate detection accuracy within tight variance windows. The Stuttgart-Reutlingen corridor hosts captive MEMS foundries serving both automotive and industrial automation.
Japan
Industrial motor efficiency programs and automotive electrification pull current sensors and inertial units into volume production. METI energy-efficiency directives require real-time load sensing for subsidy qualification. The Nagoya-Toyota industrial belt concentrates precision pressure sensor manufacturing for hybrid powertrains.
South Korea
EV battery thermal management and smartphone optical modules absorb the majority of domestic sensor output. GB standards alignment for automotive exports to China forces dual certification investments. The Gyeonggi-do cluster around Samsung and LG anchors display-integrated ambient light sensor production.
China
Domestic EV platforms and autonomous driving mandates create certified supplier slots for LiDAR and camera modules. NMPA and MIIT GB standards require redundancy in environmental sensing for Level 3+ automation. The Yangtze River Delta around Shanghai concentrates optical sensor packaging for both automotive and consumer applications.
United States
Fleet sensor-as-a-service contracts and aerospace qualification tracks sustain premium pricing for high-reliability units. EPA tailpipe standards and NHTSA safety mandates tighten calibration requirements for emissions and crash detection. Michigan's automotive testing corridors and Texas energy monitoring networks pull divergent sensor specifications.
Semiconductor Sensor Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. Captive foundry operators and fabless design houses split the market between integrated module supply and discrete component distribution. Scale-driven MEMS manufacturers, optical sensor specialists, and precision signal-conditioning providers constitute the dominant archetypes. Consolidation through backward integration into wafer-level packaging and strategic partnerships for fusion algorithm licensing represent the primary competitive vectors.
Within the captive-foundry tier, STMicroelectronics and Bosch Sensortec exemplify vertically integrated production models. Texas Instruments occupies a position bridging analog front-end expertise with digital interface standardization. These three anchors represent divergent approaches to margin capture—foundry scale, automotive qualification depth, and precision signal processing—rather than direct product competition.
| Leading Market Players |
|---|
| STMicroelectronics |
| Bosch Sensortec |
| Texas Instruments |
| OmniVision Technologies |
| Sony Semiconductor Solutions |
| NXP Semiconductors |
| Infineon |
| Advantest |
| ON Semiconductor |
| Others |
Cost & Logistics Intelligence
200mm wafer undercapacity in Taiwan and South Korea is forcing automotive sensor buyers into 18-month allocation commitments, compressing spot-market liquidity and shifting pricing power toward foundries with captive capacity. This utilization squeeze rewards suppliers with backward integration into wafer-level packaging while penalizing fabless competitors dependent on merchant foundry access.
Pricing Analysis
Cost-plus contracts indexed to palladium and platinum spot prices dominate exhaust gas sensor procurement, with German OEMs locking in 36-month offtake agreements to hedge catalyst volatility. Price differentiation rests on AEC-Q100 certification grade and calibration traceability depth, with automotive-grade units commanding substantial premiums over industrial variants. Cost compression in consumer MEMS accelerates as STMicroelectronics and Bosch Sensortec scale 200mm foundry output. Fleet operators exhibit lowest price sensitivity due to sensor-as-a-service bundling, while smartphone manufacturers drive hardest unit-cost negotiations.
Supply Chain Analysis
Extended 90-day payment terms and supply-chain finance facilities from Taiwanese packaging houses are easing working-capital pressure for European fabless sensor designers. Manufacturing concentrates in Taiwan, South Korea, and Germany, with Reutlingen and Dresden anchoring MEMS wafer production and Hsinchu handling final test. The chain draws from silicon wafers, palladium catalysts, and ceramic packaging substrates. Single-source vulnerability in 200mm CMOS foundry capacity presents structural risk. Distribution runs through Tier 1 automotive suppliers and direct OEM contracts rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration-as-a-service and predictive analytics subscriptions are expanding faster than hardware unit shipments, transforming capital expenditure into recurring operational budgets for fleet and industrial buyers. This service-attach dynamic favors suppliers with embedded software capabilities and captive metrology infrastructure.
For Market Incumbents: Insulate automotive qualification moats by accelerating investment in multi-jurisdiction certification pipelines, particularly simultaneous EPA and ECHA track qualification. Captive 200mm foundry capacity in Germany or Taiwan provides defensive leverage against allocation risk during demand surges. Prioritize backward integration into wafer-level vacuum sealing to offset MEMS process engineer scarcity in Reutlingen and Dresden.
For New Entrants and Emerging Players: Mid-market industrial motor retrofit programs in India under the PLI scheme represent the most penetrable entry point, with BIS certification requirements less stringent than automotive AEC-Q100. Battery thermal runaway detection for two-wheeler electrification in Southeast Asia offers second white-space target. Lead with digital temperature interface modules featuring embedded compensation algorithms to reduce host processor overhead and accelerate design wins.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-as-a-service providers with fleet operator contracts spanning predictive analytics and calibration management. Long-term viability over a 5-10 year horizon favors acquisition targets with captive metrology labs and multi-jurisdiction certification depth rather than pure-play component vendors. Monitor EPA tailpipe standard variance windows as the critical inflection signal—tightening thresholds accelerate replacement cycles for legacy exhaust monitoring hardware.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 200mm Foundry Capacity | Captive wafer supply insulates against Taiwan allocation risk during automotive demand surges. |
| Multi-Jurisdiction Certification Pipeline Investment | Simultaneous EPA and ECHA tracks compress 18-24 month launch windows for exhaust sensors. |
| Sensor-as-a-Service Contract Expansion | Recurring analytics subscriptions transform capital expenditure into operational budgets for fleet operators. |
| MEMS Process Engineer Talent Acquisition | Specialized wafer-level packaging expertise concentrates in Reutlingen, Dresden, and Hsinchu. |
| Optical Sensor SPAD Array Development | 40nm CMOS image sensor foundry access with 3D stacking captures smartphone and automotive LiDAR demand. |
Research Approach
Initial hypotheses were tested against primary input from MEMS foundry operations directors, Tier 1 automotive supplier procurement leads, and industrial fleet asset managers, then refined through secondary validation against SEC 10-K filings, EPA certification databases, ECHA REACH registration data, and IHS Markit vehicle production statistics. Bottom-up unit demand modeling across pressure, temperature, and optical sensor categories was triangulated with top-down market sizing from foundry capacity utilization reports.
Demand-supply balance dynamics anchored the analytical framework, with segmentation across product type, technology node, end-use industry, and regional regulatory cluster modeled throughout the forecast period. CAGRs were derived from installed base growth rates, replacement cycle compression, and content-per-vehicle expansion in battery thermal management. Industry-specific inputs included Euro 7 emissions mandate implementation timelines and China GB standard certification velocity for autonomous driving platforms.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, precious metal mining supply, or 200mm wafer capital expenditure would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry yield improvements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Refrigeration Gauge Market