
 Microelectromechanical System (MEMS) Market | 2026-2036
Microelectromechanical System (MEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Microelectromechanical System (MEMS) Market Foresight
MEMS engineering talent scarcity is bifurcating competitive advantage between integrated device manufacturers and fabless design houses. Robert Bosch GmbH leverages captive wafer fabrication in Reutlingen to sustain process control across pressure and inertial sensor lines. STMicroelectronics anchors high-volume MEMS microphone production through partnerships with consumer electronics OEMs. Texas Instruments Incorporated differentiates by extending its analog front-end expertise into integrated sensor-plus-signal-conditioning solutions.
Microelectromechanical systems integrate mechanical elements, sensors, actuators, and electronics on a common silicon substrate through processes such as deep reactive-ion etching, with typical feature sizes ranging from one micron to several millimeters and operational purposes spanning motion detection, pressure measurement, acoustic capture, and environmental sensing. Pressure sensors and accelerometers occupy mature, high-volume positions where unit economics favor established foundry partnerships, while gyroscopes command premium positioning in stabilization and navigation systems requiring tighter tolerance control. Surface micromachining leads in consumer-facing applications due to CMOS compatibility and die-size efficiency, whereas bulk micromachining sustains dominance in automotive and industrial channels where structural robustness and hermetic sealing prove critical.
FDA scrutiny of MEMS-based implantable devices shapes biocompatibility and reliability testing protocols for healthcare applications, while REACH and RoHS frameworks in Europe restrict hazardous substance use in sensor packaging and interconnect materials. FCC emissions standards in the United States govern RF MEMS components deployed in telecommunications infrastructure, creating compliance thresholds that filter market access. Stakeholders must monitor foundry utilization rates, packaging substrate availability, and evolving automotive functional-safety certifications as determinants of supply security and margin trajectory.
Market Dynamics
Foundry capacity constraints in East Asian fabrication clusters are forcing MEMS designers toward deeper foundry partnerships and process co-development agreements, compressing margins for fabless houses while rewarding integrated manufacturers with captive wafer supply.
Growth Catalysts
- EU Green Deal vehicle mandates:Tightened emissions standards in Europe are accelerating sensor miniaturization requirements across powertrain and exhaust monitoring systems, pulling MEMS pressure and gas sensors into high-volume automotive platforms.
- Advanced driver-assistance systems:Automotive manufacturers in Germany and Japan are scaling MEMS deployment for LiDAR stabilization, inertial navigation, and cabin monitoring, creating sustained demand for gyroscopes and accelerometers with automotive-grade reliability.
- Deep reactive-ion etching:Process refinements in surface micromachining are expanding CMOS-compatible MEMS into consumer audio and wearable form factors where die-size efficiency determines unit economics.
Market Restraints
- Foundry concentration risk:Taiwan and South Korea control the majority of 200mm MEMS wafer capacity, exposing fabless designers to allocation constraints and price volatility during demand surges.
- Hermetic packaging cost structure:Automotive and industrial applications require ceramic or metal hermetic seals that add 30-40% to final sensor cost, limiting penetration in price-sensitive consumer segments.
- Optical sensor substitution:Fiber optic gyroscopes and solid-state lidar are displacing MEMS gyroscopes in precision navigation applications where drift tolerance below 0.1 degrees per hour is mandatory.
Strategic Opportunities
- Implantable healthcare devices:FDA scrutiny of MEMS-based pacemakers and drug delivery systems is creating first-mover advantages for suppliers who master biocompatibility testing protocols and long-term reliability validation.
- RF MEMS telecommunications infrastructure:FCC emissions standards for 5G and 6G base stations are opening design wins for tunable capacitors and switches that outperform solid-state alternatives in insertion loss and linearity.
- Environmental sensing convergence:Integration of MEMS with CMOS image sensors and edge AI processors is enabling distributed air quality monitoring networks in urban China and India where regulatory enforcement is tightening.
Industry Challenges
- Multi-physics simulation expertise:The scarcity of engineers proficient in coupled electro-mechanical-thermal finite element analysis is extending product development cycles and inflating R&D headcount costs for fabless design houses.
- Automotive functional-safety certification:ISO 26262 ASIL-D compliance for inertial sensors requires 18-24 month validation timelines and specialized fault-injection testing infrastructure that strains mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microelectromechanical System (MEMS) Market |
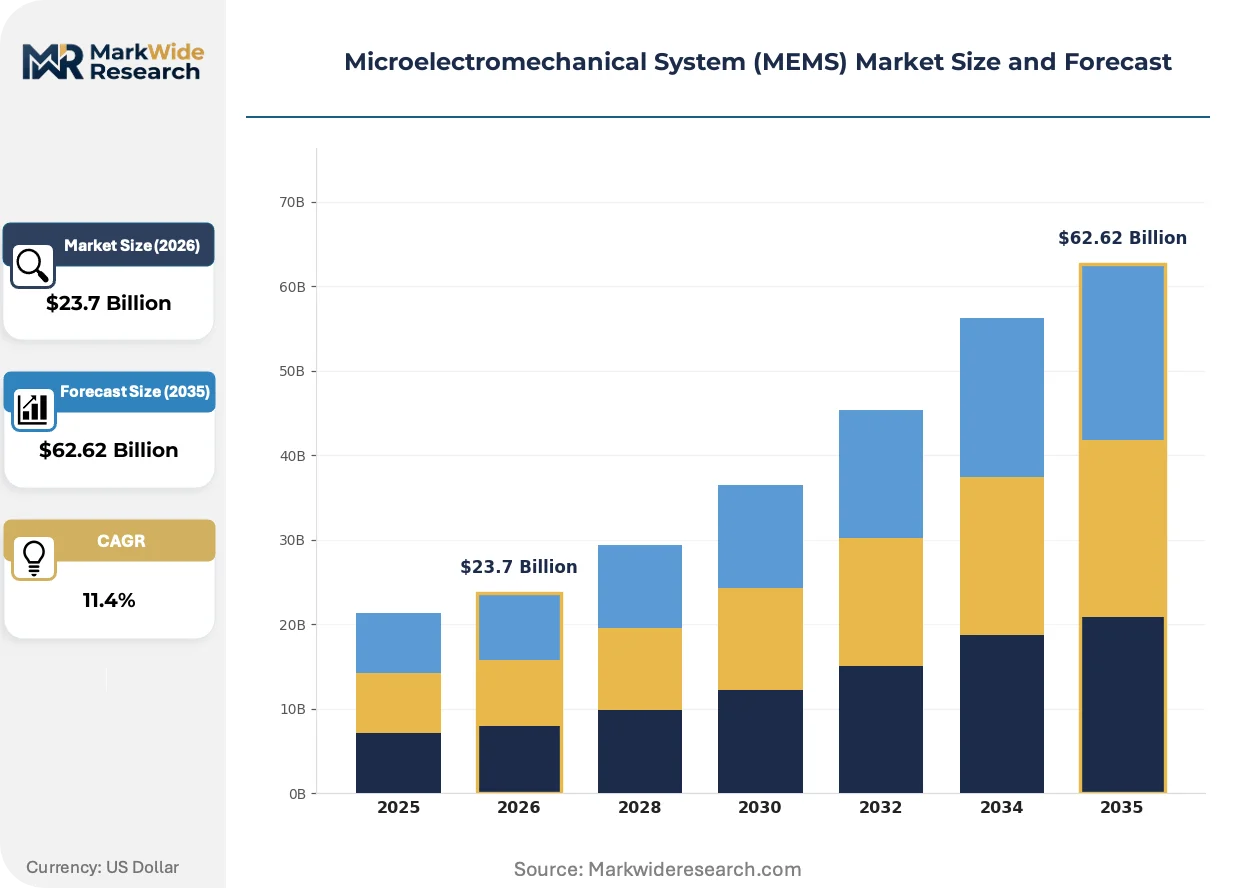
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Microphones, Pressure Sensors Application: Automotive, Consumer Electronics, Healthcare, Industrial Automation Technology: Surface Micromachining, Bulk Micromachining, LIGA, Wafer Bonding End User: Aerospace, Defense, Telecommunications, Robotics |
| Companies Covered | Robert Bosch GmbH, Broadcom, STMicroelectronics, Texas Instruments Incorporated, Qorvo, Inc., TDK Corporation, Analog Devices, Inc., Infineon Technologies AG, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microelectromechanical System (MEMS) Market Shifts & Advancements
Process convergence between MEMS and CMOS fabrication is collapsing traditional boundaries between sensor design and signal conditioning, enabling single-die integration that redefines cost structures across consumer and automotive tiers.
Piezoelectric aluminum nitride thin films are supplanting capacitive transduction in microphone and ultrasonic applications. Smartphone OEMs in South Korea and China are adopting piezo-MEMS for water-resistant audio ports and gesture recognition. This transition is compressing the addressable market for traditional capacitive MEMS microphone suppliers while opening premium positioning for piezo specialists with RF sputtering expertise.
REACH and RoHS frameworks in Europe are restricting hazardous substance use in sensor packaging and interconnect materials. The industrial consequence is a forced migration from lead-based solder joints and hexavalent chromium coatings to tin-silver-copper alloys and compliant surface finishes. Healthcare and automotive MEMS suppliers with European revenue exposure are absorbing 12-18 month qualification cycles to maintain market access.
Fleet operators and industrial asset managers are consolidating sensor procurement around platform vendors who bundle MEMS hardware with predictive analytics software. This behavior is displacing component distributors in factory automation and logistics verticals. The shift is most visible in Germany and Japan where automotive and precision manufacturing end-users are negotiating enterprise-wide sensor contracts with integrated solution providers rather than catalog distributors.
Microelectromechanical System (MEMS) Market Segmentation
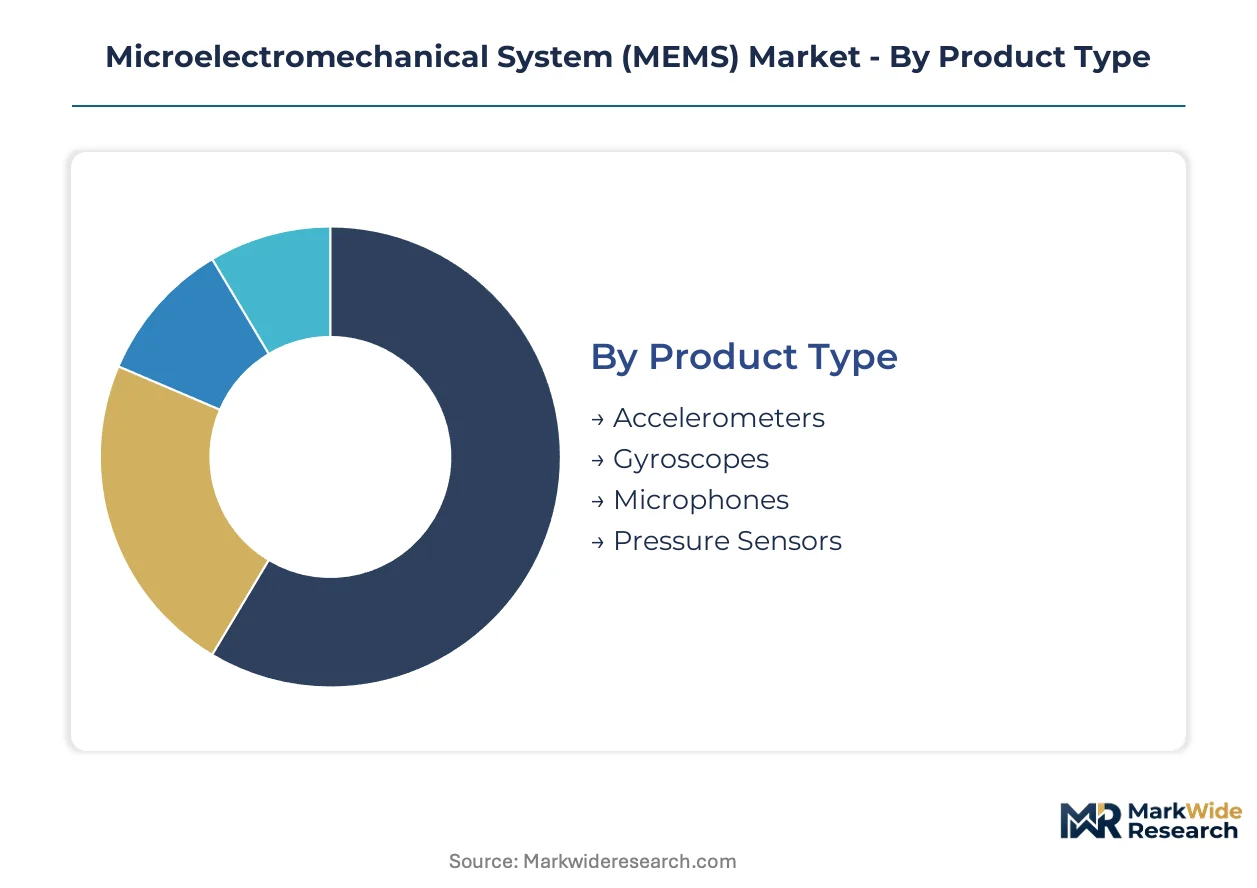
MEMS market segmentation reveals distinct vulnerability profiles across product categories. Substitution pressures from solid-state alternatives and optical technologies fragment competitive positioning unevenly across accelerometers, gyroscopes, pressure sensors, and microphones.
Product Type:
Accelerometers face the most acute substitution threat from piezoelectric and piezoresistive alternatives in industrial vibration monitoring, while gyroscopes confront fiber optic displacement in precision navigation.
- Accelerometers:Capacitive and piezoelectric transduction architectures measure linear acceleration across single to tri-axial configurations. Automotive crash detection in Germany and Japan consumes high-g units for airbag deployment, though low-cost alternatives from Chinese suppliers compress margin structures in consumer wearables.
- Gyroscopes:Coriolis-force-based rotational rate sensors achieve drift tolerances between 1-10 degrees per hour in MEMS implementations. Stabilization systems for LiDAR modules in German automotive platforms sustain premium pricing, yet fiber optic gyroscopes capture precision navigation above 0.1 degrees per hour tolerance thresholds.
- Microphones:Capacitive MEMS dominate smartphone audio capture with SNR specifications exceeding 65 dB.
- Pressure Sensors:Piezoresistive and capacitive designs span 1-1000 bar ranges for automotive manifold and medical applications.
Pressure sensors anchor the volume base while gyroscopes gain share at the steepest rate.
Application:
Cost tier stratification separates automotive qualification requirements from consumer electronics volume economics.
- Automotive:ASIL-D functional safety certification mandates fault-tolerant architectures for braking and steering sensors. Exhaust aftertreatment systems under EU Green Deal mandates pull pressure and NOx sensors into high-volume deployment across German and French OEM platforms.
- Consumer Electronics:Die-size efficiency and CMOS compatibility drive unit economics below one dollar for motion and audio sensors. South Korean smartphone OEMs specify water-resistant piezoelectric microphones for flagship devices.
- Healthcare:FDA biocompatibility protocols govern implantable pressure sensors and drug delivery actuators.
- Industrial Automation:Hermetic packaging and extended temperature ranges distinguish factory floor deployments.
Consumer electronics delivers the highest shipment volumes while healthcare applications expand most quickly.
Technology:
Process maturity gradients separate volume-proven surface micromachining from specialized bulk and LIGA alternatives.
- Surface Micromachining:Sacrificial oxide layers enable CMOS-compatible fabrication with sub-micron feature control. Consumer audio and motion sensing in Taiwan foundries exploit die-size efficiency for smartphone and wearable integration.
- Bulk Micromachining:Deep reactive-ion etching creates three-dimensional mechanical structures with superior structural robustness. Automotive pressure and inertial sensors in Reutlingen and Grenoble rely on hermetic glass-silicon anodic bonding for 15-year reliability.
- LIGA:Lithography and electroforming achieve aspect ratios exceeding 100:1 for precision mechanical components.
- Wafer Bonding:Silicon fusion and anodic techniques create vacuum-sealed cavities for resonant structures.
Surface micromachining dominates wafer starts while bulk processes command premium positioning.
End User:
Customer procurement concentration separates defense long-cycle contracts from telecommunications infrastructure refresh timelines.
- Aerospace:FAA certification timelines and DO-178C software standards extend development cycles to 36-48 months for inertial navigation units. Commercial aircraft platforms in Toulouse and Seattle specify MEMS-based attitude heading reference systems for backup navigation.
- Defense:ITAR export controls and radiation-hardening requirements restrict supplier pools for munitions guidance and platform stabilization. Northrop Grumman and Raytheon procurement specifications favor domestic wafer fabrication.
- Telecommunications:FCC emissions standards for 5G infrastructure create design wins for RF MEMS tunable filters and switches.
- Robotics:Collaborative robot force-torque sensors and drone stabilization systems drive mid-volume demand.
Aerospace sustains the longest contract cycles while telecommunications infrastructure refreshes climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy MEMS pressure sensors for exhaust aftertreatment, while South Korean smartphone manufacturers specify piezoelectric microphones for flagship devices. This consumption-mix differential separates automotive-grade reliability requirements from consumer electronics die-size efficiency priorities.
Germany
Robert Bosch GmbH operates captive wafer fabrication in Reutlingen for pressure and inertial sensor lines. The EU Green Deal mandates tightened vehicle emissions standards that accelerate sensor miniaturization across powertrain systems. Stuttgart and Munich anchor automotive MEMS demand through BMW and Mercedes-Benz procurement specifications for LiDAR stabilization modules.
United States
Texas Instruments Incorporated extends analog front-end expertise into integrated sensor-plus-signal-conditioning solutions for industrial automation. FDA scrutiny shapes biocompatibility testing protocols for implantable healthcare devices. Greater Boston and Austin clusters concentrate RF MEMS development for 5G telecommunications infrastructure under FCC emissions standards.
South Korea
Samsung Electronics and LG Electronics drive high-volume MEMS microphone procurement for water-resistant smartphone audio ports. Foundry capacity constraints in Taiwanese fabrication clusters expose fabless designers to allocation volatility. Seoul Capital Area anchors consumer electronics MEMS demand with specifications migrating toward piezoelectric aluminum nitride thin films.
Japan
Murata Manufacturing and TDK Corporation sustain dominance in automotive-grade inertial sensors for advanced driver-assistance systems. METI industrial policy supports domestic MEMS supply chain resilience for precision manufacturing equipment. Kyoto-Osaka and Nagoya industrial corridors concentrate gyroscope production for vehicle stabilization systems requiring drift tolerance below 10 degrees per hour.
Taiwan
TSMC and United Microelectronics Corporation foundries control the majority of 200mm MEMS wafer capacity for global fabless design houses. Surface micromachining processes achieve CMOS-compatible die-size efficiency for smartphone and wearable integration. Hsinchu Science Park anchors fabrication clusters where foundry utilization rates determine supply security for consumer audio and motion sensing applications.
Microelectromechanical System (MEMS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive wafer fabrication conferring supply security during foundry allocation constraints. The upper tier combines process control across deep reactive-ion etching with automotive functional-safety certification infrastructure. Three archetypes dominate: integrated device manufacturers with captive fabrication, fabless design houses dependent on foundry partnerships, and analog semiconductor specialists extending signal-conditioning expertise into sensor integration. Competitive moves concentrate on foundry co-development agreements and ISO 26262 ASIL-D certification timelines.
Among German-based integrated manufacturers, Robert Bosch GmbH and Infineon Technologies AG exemplify the captive-fabrication archetype. STMicroelectronics anchors the European fabless tier through high-volume MEMS microphone production partnerships. Texas Instruments Incorporated occupies a position bridging analog signal-conditioning heritage with sensor-plus-frontend integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Broadcom |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Qorvo, Inc. |
| TDK Corporation |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Long-term foundry capacity reservation agreements lock in wafer supply visibility for automotive-grade MEMS producers while exposing fabless designers to spot-market volatility when Taiwanese utilization rates tighten. German OEM procurement specifications for ASIL-D certified inertial sensors embed multi-year pricing floors that insulate captive fabricators from consumer-tier margin erosion.
Pricing Analysis
Contract-based long-term offtake dominates automotive and industrial tiers where ISO 26262 certification and hermetic packaging requirements create steep supplier qualification barriers. Price differentiation separates ASIL-D certified units from consumer-grade alternatives, with volume scale and automotive functional-safety tier as primary drivers. Cost compression in smartphone-facing microphones intensifies as Chinese suppliers expand 200mm wafer capacity. Consumer electronics OEMs exhibit highest price sensitivity, while medical implant buyers prioritize biocompatibility validation over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for European MEMS packaging houses sourcing ceramic substrates from Japanese suppliers. Taiwan, South Korea, and Germany anchor global supply, with Hsinchu and Reutlingen clusters controlling critical process steps. The chain draws from silicon wafer feedstock, specialty glass for anodic bonding, and aluminum nitride sputtering targets. Single-source vulnerability concentrates in 200mm MEMS-capable foundry capacity. Distribution runs through Tier 1 automotive suppliers and consumer electronics ODMs rather than catalog distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA biocompatibility protocols and ISO 26262 ASIL-D certification creates defensive moats that compound with each validation cycle completed. Switching costs for qualified automotive sensors exceed eighteen months, locking OEM relationships.
For Market Incumbents: Compound captive fabrication advantages by deepening process co-development with Taiwanese foundries for next-generation piezoelectric transduction. Prioritize ASIL-D certification expansion into brake-by-wire and steering torque sensors where fiber optic gyroscope substitution threatens precision navigation positioning. Extend backward integration into specialty glass substrate supply to offset ceramic hermetic seal cost inflation. For New Entrants and Emerging Players: Predictive analytics software bundling gaps in factory automation verticals present white-space entry points where incumbent hardware vendors under-serve industrial asset managers. Target environmental sensing convergence applications in urban China and India where regulatory enforcement tightening outpaces established supplier response. Pursue RF MEMS design wins for 5G infrastructure through FCC pre-certification investment that accelerates base station OEM procurement timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated device manufacturers with captive wafer supply and automotive certification infrastructure already deployed. Five-to-ten year viability favors archetypes combining Reutlingen or Grenoble process heritage with software-layer acquisition capability. Watch foundry utilization rate inflections in Taiwanese 200mm capacity as early signal of margin expansion or compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Co-Development Agreement | Process partnerships with TSMC or UMC secure 200mm MEMS capacity allocation during demand surges. |
| ASIL-D Certification Investment | ISO 26262 compliance opens German and Japanese OEM braking and steering sensor procurement specifications. |
| Piezoelectric Transduction Transition | Aluminum nitride thin-film expertise captures South Korean smartphone OEM water-resistant audio port demand. |
| Predictive Analytics Platform Launch | Software bundling displaces component distributors in German factory automation procurement consolidation. |
| Biocompatibility Protocol Mastery | FDA validation infrastructure creates first-mover advantage in implantable pacemaker and drug delivery MEMS. |
Research Methodology
The analysis maps surface micromachining, bulk micromachining, LIGA, and wafer bonding process tiers, each validated through MEMS process engineers, automotive Tier 1 procurement directors, foundry operations managers, and FDA regulatory consultants. Primary interviews with fabless design house executives and captive fabrication specialists combine with secondary validation against SEC 10-K filings, SEMI equipment billings data, and EU Green Deal regulatory filings. Bottom-up wafer start estimates and top-down OEM content-per-vehicle analysis triangulate market sizing.
Consistency checks against SEMI capacity forecasts and automotive production databases validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application tier, fabrication technology, and end-user procurement concentration. CAGRs derive from foundry utilization trend extrapolation and OEM platform content analysis, with EU emissions mandate enforcement timelines and smartphone OEM specification migration as key forecast inputs.
Material uncertainties — foundry allocation volatility, REACH substance restriction expansion, and solid-state lidar displacement acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around certification timeline stability and Taiwanese capacity expansion schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Radio Dot System (RDS) Market