
 Bioacoustics Sensing Market | 2026-2036
Bioacoustics Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Bioacoustics Sensing Market Analysis
Healthcare providers is bifurcating from traditional research institutions as the dominant buyer archetype in bioacoustics sensing. Wildlife Acoustics anchors its position through specialized hardware for ecological monitoring. IBM Corporation leverages its cloud infrastructure to process large-scale acoustic datasets. Med-Acoustics differentiates through clinical-grade signal processing for diagnostic applications.
Bioacoustics sensing captures, digitizes, and analyzes acoustic signatures from biological sources using transducers with frequency responses typically spanning infrasonic to ultrasonic ranges. The technology serves industrial and commercial purposes including wildlife population tracking, environmental health assessment, and remote physiological monitoring. Microphones dominate hardware revenue due to their deployment across terrestrial and clinical settings, while cloud-based processing architectures capture expanding margin pools as data volumes scale. Wireless technology segments show accelerated uptake where field deployments require real-time telemetry without tethered infrastructure.
The FDA governs clinical bioacoustic devices under software-as-a-medical-device frameworks, while the EPA shapes environmental monitoring standards for acoustic data collection protocols. ISO standards for measurement microphones ensure cross-border equipment interoperability. Stakeholders must weigh regulatory pathway complexity against addressable market breadth when prioritizing product development investments.
Market Dynamics
The FDA's software-as-a-medical-device framework is compressing clearance timelines for acoustic biomarker platforms, pulling healthcare providers ahead of research institutions as the primary demand source and forcing hardware vendors to rearchitect products for clinical validation pathways.
Growth Catalysts
- Clinical workflow integration:Hospital systems in the United States are embedding bioacoustic monitoring into remote patient care protocols, creating pull-through for FDA-cleared diagnostic devices.
- EMA's Medical Device Regulation:The MDR's clarified classification rules for software-driven diagnostics are accelerating market entry for European acoustic biomarker developers.
- Edge AI processing:On-device inference chips are reducing telemetry bandwidth requirements, enabling real-time wildlife monitoring in bandwidth-constrained field deployments.
Market Restraints
- MEMS microphone supply concentration:Taiwan-based foundries control critical fabrication capacity for clinical-grade acoustic transducers, exposing vendors to geopolitical supply disruption.
- Validation cost structure:Prospective clinical trials for acoustic biomarkers require multi-site data collection that consumes 18-24 months and seven-figure investment before FDA submission.
- Optical sensing substitution:Photoplethysmography and radar-based vital sign monitoring are capturing budget share in remote patient monitoring contracts where acoustic methods previously held technical advantage.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives are attracting contract manufacturers to establish acoustic sensor assembly capacity for export to Southeast Asian and Middle Eastern markets.
- EU AI Act compliance services:The Act's risk classification requirements for diagnostic algorithms are creating advisory and validation service revenue pools adjacent to hardware sales.
- Convergence with digital therapeutics:Bioacoustic respiratory monitoring paired with prescription digital therapeutic platforms is opening reimbursement pathways previously closed to standalone sensor vendors.
Industry Challenges
- Signal processing talent scarcity:The intersection of biomedical engineering and machine learning specialization commands premium compensation that mid-size vendors struggle to match against cloud computing recruiters.
- ISO 81060-2 compliance timelines:Blood pressure measurement validation protocols for acoustic cuffless devices extend development cycles by 12-18 months versus pressure-based alternatives.
- Legacy EHR integration friction:Hospital IT departments face middleware complexity when connecting novel acoustic data streams to entrenched electronic health record architectures from Epic and Cerner.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioacoustics Sensing Market |
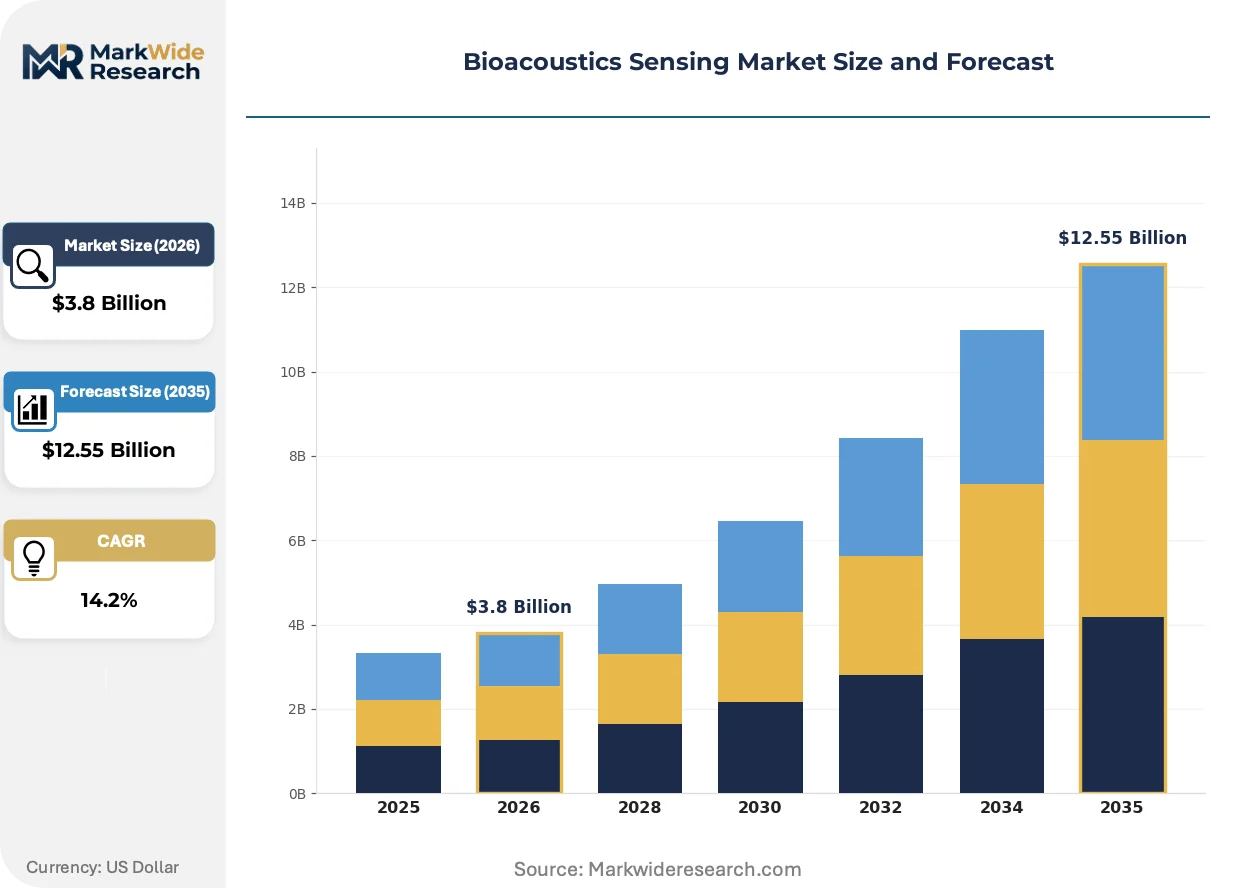
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Hydrophones, Sensors, Processing Units Application: Wildlife Monitoring, Environmental Assessment, Marine Research, Smart Cities Technology: Analog, Digital, Wireless, Cloud-Based End User: Research Institutions, Government Agencies, Conservation Organizations, Enterprises |
| Companies Covered | IBM Corporation, AT&T Inc., Panasonic Corporation, Honeywell International Inc., Avisoft Bioacoustics, Wildlife Acoustics, Inc., Med-Acoustics, Remon Medical Technologies, Bioacoustics Research Program, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioacoustics Sensing Market Emerging Trajectories
Computational acoustic analysis is migrating from centralized cloud clusters toward edge-deployable neural networks, compressing latency for real-time clinical alerts and enabling autonomous field operation where connectivity is intermittent or absent.
Neural audio codecs are decomposing the tradeoff between compression ratio and diagnostic fidelity that has constrained wireless bioacoustic telemetry. Medtronic and Philips are piloting these algorithms in cardiac auscultation remote monitoring programs, where 10x bandwidth reduction is enabling continuous streaming over cellular networks previously limited to snapshot transmission. This compression is decomposing the hardware cost structure for ambulatory monitoring by reducing required radio power and data plan expenditure.
REACH regulation amendments targeting persistent organic pollutants are restricting certain polymer formulations used in microphone housings for environmental monitoring equipment. Manufacturers serving European ecological research consortia are reformulating enclosure materials to maintain IP ratings while eliminating restricted substances. The compliance burden falls heaviest on small-batch hardware vendors supplying biodiversity monitoring networks, which lack economies of scale for parallel material qualification.
Hospital procurement committees are unbundling sensor hardware from data analytics subscriptions, reversing the integrated SaaS pricing that dominated early bioacoustic platform commercialization. Academic medical centers in Germany and the Netherlands are leading this disaggregation, negotiating separate contracts for device acquisition and algorithm access. The shift is most pronounced in pulmonary acoustic monitoring, where institutions seek to avoid vendor lock-in across multi-year research collaborations spanning several technology refresh cycles.
Bioacoustics Sensing Market Segmentation
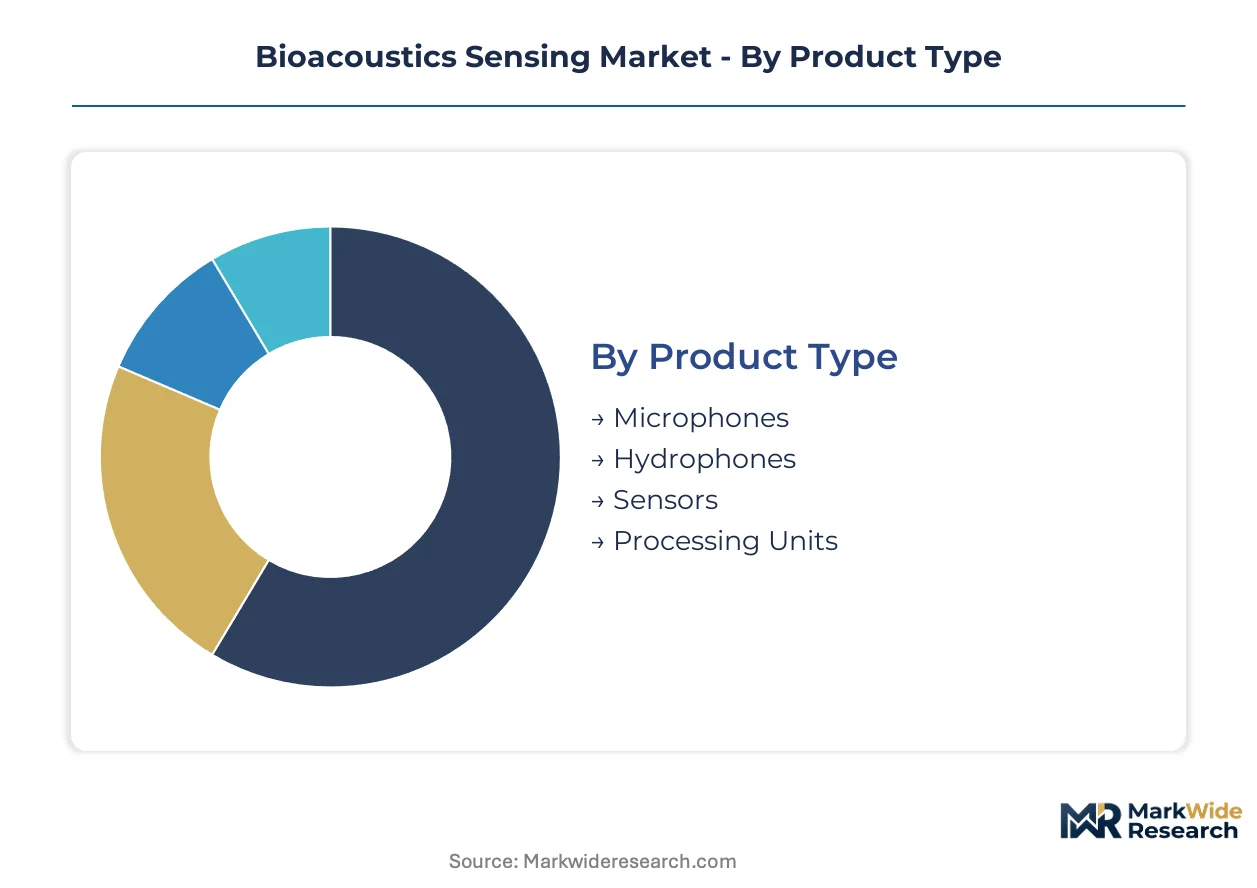
Segmentation in bioacoustics sensing reveals divergent margin architectures across hardware and software layers. Product type and technology choices determine whether vendors capture value through sensor fabrication or algorithmic processing.
Product Type:
Margin pools concentrate in acoustic transducers where MEMS fabrication expertise creates supply scarcity, while processing units capture recurring revenue through firmware licensing.
- Microphones:Electret and MEMS variants dominate terrestrial deployments with frequency responses tailored to infrasonic wildlife calls or cardiopulmonary auscultation. Hospital systems in the United States specify clinical-grade units with IEC 60601-1-8 compliance for patient monitoring, while ecological researchers prioritize weatherproofing and extended battery operation.
- Sensors:Multi-modal arrays combining acoustic with accelerometric or thermal channels command premium pricing in diagnostic applications. CDSCO-cleared versions for the Indian market are emerging through PLI scheme beneficiaries targeting export to Southeast Asian telemedicine networks.
- Hydrophones:Piezoelectric transducers optimized for marine mammal vocalization studies and submarine pipeline monitoring.
- Processing Units:Edge AI accelerators enabling on-device inference without cloud dependency.
Microphones hold installed capacity. Sensors are rotating up the share rankings.
Application:
Volume concentration follows funding flows from government research budgets and municipal smart infrastructure programs rather than commercial end-users.
- Wildlife Monitoring:Autonomous recording units with solar power and cellular backhaul track population dynamics in remote reserves. The EPA shapes environmental monitoring standards for acoustic data collection protocols in federally managed lands, while European biodiversity directives drive procurement by research consortia in Germany and the Netherlands.
- Environmental Assessment:Continuous noise monitoring for regulatory compliance in industrial zones and transportation corridors. Smart city deployments in Singapore and Dubai integrate acoustic sensors with air quality networks for unified environmental dashboards.
- Marine Research:Deep-ocean hydrophone arrays for cetacean communication studies and seismic survey impact assessment.
- Smart Cities:Gunshot detection and traffic flow optimization through urban acoustic surveillance.
Wildlife Monitoring holds installed capacity. Smart Cities is climbing the fastest.
Technology:
Customer type determines technology selection, with research institutions tolerating analog complexity while government agencies mandate wireless interoperability.
- Wireless:LoRaWAN and cellular LTE-M modules eliminate cabling costs in field deployments spanning hundreds of square kilometers. Conservation organizations operating in bandwidth-constrained African reserves specify Store-and-Forward architectures with satellite uplink, while Japanese METI-funded projects leverage proprietary low-power wide-area protocols.
- Cloud-Based:Scalable storage and GPU-accelerated analysis pipelines attract enterprises managing multi-site sensor fleets. EMA's Medical Device Regulation clarifies classification rules for software-driven diagnostics, accelerating European healthcare provider adoption of cloud-hosted cardiac auscultation platforms.
- Analog:Direct voltage-output transducers for laboratory-grade spectrographic analysis.
- Digital:Integrated ADC and preprocessing for reduced telemetry bandwidth.
Cloud-Based holds installed capacity. Wireless is gaining share fastest.
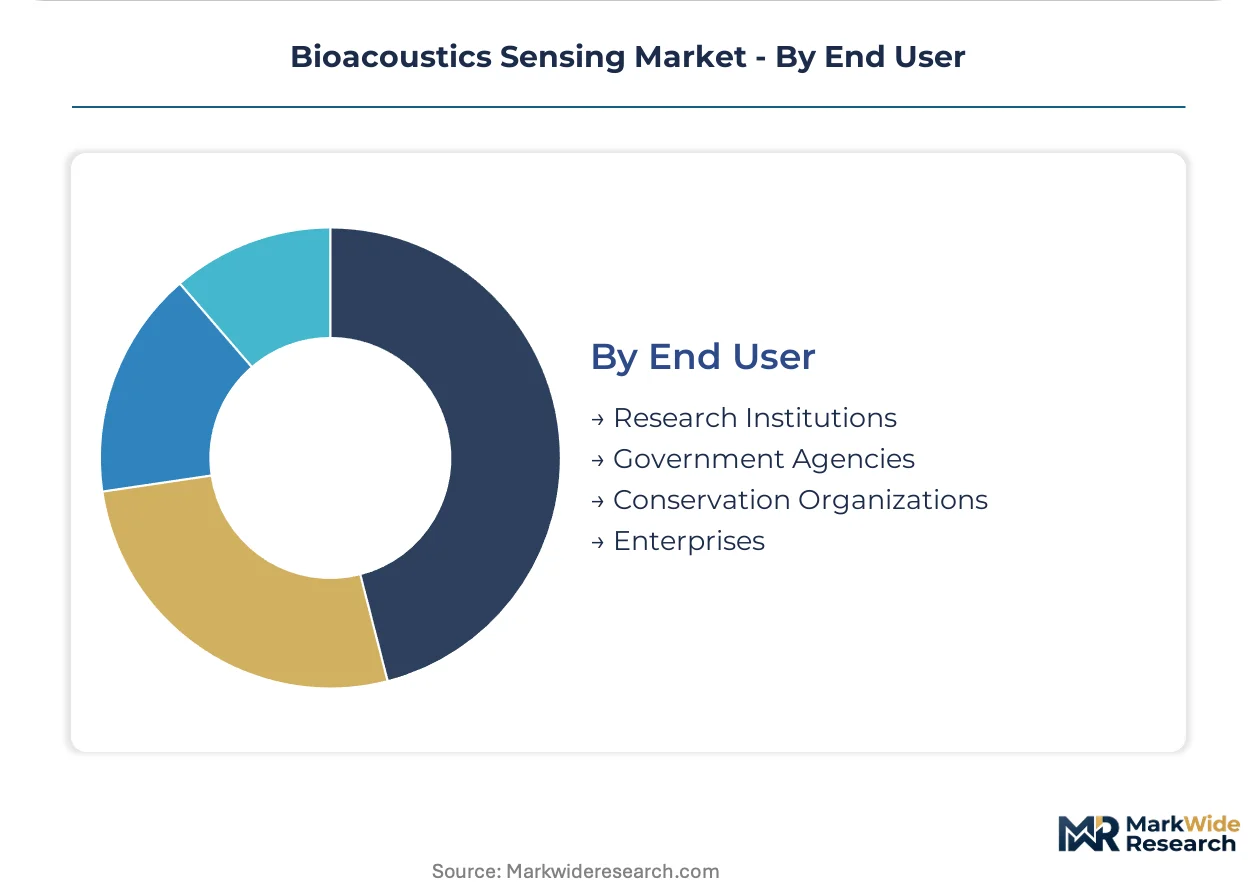
End User:
Procurement authority separates segments, with government agencies controlling multi-year funded programs while conservation organizations depend on grant cycles.
- Government Agencies:National parks services and environmental protection ministries deploy standardized equipment across jurisdictional boundaries. The EPA and its state-level counterparts specify interoperability protocols, while India's Ministry of Environment funds acoustic monitoring under National Mission on Himalayan Studies grants.
- Research Institutions:University laboratories drive innovation in algorithm development but represent fragmented demand. German academic medical centers are unbundling sensor hardware from data analytics subscriptions, negotiating separate contracts for device acquisition and algorithm access.
- Conservation Organizations:NGOs managing protected area networks with donor-restricted capital budgets.
- Enterprises:Industrial operators monitoring equipment health through acoustic signature analysis.
Government Agencies hold installed capacity. Enterprises are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export clinical-grade bioacoustic systems to German hospital networks and Indian telemedicine operators, establishing transatlantic and transpacific trade corridors that concentrate procurement authority in research medical centers and government-funded conservation programs.
United States
Hospital systems in Massachusetts and California embed acoustic monitoring into remote patient protocols, while the FDA's software-as-a-medical-device framework compresses clearance timelines for biomarker platforms. The National Institutes of Health funds multi-site acoustic research consortia in the Boston-Cambridge cluster, where academic medical centers negotiate unbundled hardware and algorithm contracts.
Germany
Academic medical centers in Berlin and Munich lead procurement of disaggregated sensor-analytics systems, avoiding vendor lock-in across multi-year research collaborations. The EMA's Medical Device Regulation clarifies classification rules for software-driven diagnostics, accelerating market entry for acoustic biomarker developers serving Dutch and Belgian hospital networks through Rhine-Ruhr distribution channels.
India
Contract manufacturers in Karnataka and Tamil Nadu establish acoustic sensor assembly capacity under the PLI scheme for medical electronics, targeting export to Southeast Asian and Middle Eastern telemedicine markets. CDSCO-cleared multi-modal sensor arrays emerge through PLI beneficiaries, with Delhi-NCR research hospitals piloting cuffless blood pressure validation protocols.
Japan
METI-funded projects leverage proprietary low-power wide-area protocols for conservation deployments, while Osaka-based electronics fabricators supply MEMS transducers to clinical device makers. The Kanto region hosts pilot programs pairing bioacoustic respiratory monitoring with prescription digital therapeutic platforms, opening reimbursement pathways previously closed to standalone sensor vendors.
Singapore
Smart city deployments integrate acoustic sensors with air quality networks for unified environmental dashboards, sourcing hardware from Malaysian contract manufacturers. Government procurement mandates for wireless interoperability shape vendor selection, with research consortia in the one-north technology cluster developing edge AI accelerators for bandwidth-constrained field telemetry.
Bioacoustics Sensing Market Vendor Landscape
Listed leaders compete with private specialists across regulatory validation capability, creating tiered competition where public company scale advantages clash with private firm agility in navigating FDA and EMA clearance pathways. The vendor base separates into three archetypes: diversified technology conglomerates leveraging cloud infrastructure, specialized acoustic hardware fabricators focused on ecological monitoring, and clinical-grade signal processing boutiques serving hospital procurement committees. Consolidation pressure operates through M&A activity targeting edge AI talent, while geographic expansion into India's PLI scheme beneficiary network represents a parallel competitive move.
Within the diversified technology tier, IBM Corporation and Panasonic Corporation exemplify scale-driven positioning, while Wildlife Acoustics, Inc. and Med-Acoustics occupy specialist niches. AT&T Inc. represents telecommunications infrastructure leverage into acoustic data transmission, and Avisoft Bioacoustics anchors the European research equipment segment. Honeywell International Inc. sits within the industrial diversification archetype, with Remon Medical Technologies and Bioacoustics Research Program representing private and institutional research configurations respectively.
| Leading Market Players |
|---|
| IBM Corporation |
| AT&T Inc. |
| Panasonic Corporation |
| Honeywell International Inc. |
| Avisoft Bioacoustics |
| Wildlife Acoustics, Inc. |
| Med-Acoustics |
| Remon Medical Technologies |
| Bioacoustics Research Program |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan-based MEMS foundries lock in wafer access for clinical-grade acoustic transducers while capping price volatility for hardware vendors serving FDA-cleared diagnostic markets. These arrangements tether procurement committees at Massachusetts hospital systems to fixed cost structures even as spot-market silicon fluctuates.
Pricing Analysis
Next-generation edge AI accelerators command 40-60% premiums over prior-generation cloud-dependent processing units, while legacy analog microphone arrays face steep discounts in research procurement. Three-tier pricing structure across clinical-grade, industrial-grade, and field-research equipment levels separates FDA-cleared devices with IEC 60601-1-8 compliance from uncertified ecological monitoring hardware. Price differentiation hinges on ISO 81060-2 validation status and MEMS fabrication node sophistication. Cost compression in mid-tier sensor arrays is intensifying because Indian PLI scheme beneficiaries are undercutting established vendors on assembly labor. Conservation organizations operating African wildlife reserves exhibit highest price sensitivity, while German academic medical centers prioritize certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of MEMS wafers and piezoelectric ceramics dominates inventory strategy among clinical device manufacturers anticipating Taiwan foundry disruption. Supply concentrates in Taiwan for MEMS transducer fabrication, Japan for precision analog components, and India for PLI-scheme assembly capacity. Raw material dependencies include silicon wafers, rare-earth elements in piezoelectric formulations, and specialized polymers for IP-rated enclosures. Single-source vulnerability in Taiwan-based MEMS foundry capacity exposes vendors to geopolitical supply disruption. Distribution runs through authorized medical device distributors for hospital procurement, direct-to-researcher channels for ecological equipment, and government tender processes for conservation agency deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioacoustics sensing is recovering from a cyclical trough driven by deferred hospital capital expenditure during reimbursement uncertainty, with procurement committees now releasing pent-up demand for remote patient monitoring infrastructure.
For Market Incumbents: Consolidate edge AI talent through targeted acquisition of signal processing boutiques before cloud computing recruiters capture the limited pool of biomedical engineering-machine learning specialists. Deepen backward integration into MEMS fabrication partnerships with Taiwan foundries to defend against supply disruption threatening FDA-cleared device production. Prioritize ISO 81060-2 compliance investment to maintain premium positioning as optical sensing substitution threatens acoustic methods in remote patient monitoring contracts. For New Entrants and Emerging Players: Lead with CDSCO-cleared multi-modal sensor arrays targeting Southeast Asian telemedicine networks where established vendors lack regulatory footprint. India's PLI scheme beneficiary network represents the most penetrable manufacturing base for export-oriented assembly capacity. Pursue hospital system partnerships in the Netherlands and Belgium through Rhine-Ruhr distribution channels, leveraging EMA MDR clarity on software-driven diagnostic classification to accelerate market entry. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-grade signal processing boutiques with FDA submission-ready acoustic biomarker platforms and existing hospital procurement relationships. Long-term viability over the next decade hinges on convergence with prescription digital therapeutic reimbursement pathways rather than standalone sensor hardware margins. Watch for inflection when Japanese METI-funded projects achieve reimbursement integration for bioacoustic respiratory monitoring paired with digital therapeutic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Software-as-a-medical-device framework compresses clearance timelines for acoustic biomarker platforms. |
| CE Marking Pathway | EMA MDR clarified classification rules accelerate European acoustic biomarker developer market entry. |
| Hospital System Partnership | German academic medical centers unbundle hardware from analytics to avoid vendor lock-in. |
| Software Companion Development | Neural audio codecs enable 10x bandwidth reduction for cardiac auscultation remote monitoring. |
| Reimbursement Strategy | Convergence with prescription digital therapeutics opens pathways closed to standalone sensor vendors. |
Methodological Framework
A spread of perspectives from biomedical engineers at academic medical centers, hospital procurement committee members, MEMS foundry operations managers, conservation technology program officers, and FDA regulatory consultants converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR guidance documents, CDSCO device registration databases, and Indian PLI scheme beneficiary disclosures. Bottom-up sensor shipment estimates triangulated against top-down healthcare IT expenditure projections.
Segmentation dimensions modeled include product type, application, technology, and end user across the analysis window. Hardware revenue splits between microphones, sensors, hydrophones, and processing units combined with software and services layering to derive total addressable value. CAGRs emerged from regression against hospital remote patient monitoring adoption curves, wildlife conservation funding cycles, and smart city infrastructure deployment schedules. Edge AI processing penetration and neural audio codec adoption served as technology-specific forecast inputs.
Forecasts assume regulatory continuity in FDA software-as-a-medical-device frameworks, EMA MDR implementation, and Indian PLI scheme extension; material policy shifts would require re-modeling. Supply disruption in Taiwan MEMS foundries or REACH restriction expansion targeting microphone housing polymers represent specific revision triggers. Revision becomes warranted when optical sensing substitution rates in remote patient monitoring contracts cross thresholds that displace acoustic method technical advantage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Barometer Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Thin Film Sensor Market