
 Digital Thermometer Market | 2026-2036
Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Thermometer Market Analysis
Multi-source component procurement is expanding across the digital thermometer supply chain as manufacturers diversify sensor and chipset suppliers to mitigate semiconductor volatility. OMRON Healthcare Inc. leverages its established distribution networks across Asia and Europe to sustain brand presence in both professional and consumer channels. Terumo Corporation anchors its position through specialized hospital-grade calibration protocols that differentiate its clinical offerings. Microlife competes aggressively on price in the home-user segment while extending its portfolio into connected wellness ecosystems.
A digital thermometer is an electronic temperature measurement instrument employing thermistors, thermocouples, or infrared sensors to convert thermal energy into digital readings with typical accuracy within 0.1°C. These devices serve primary diagnostic and monitoring functions across clinical settings, industrial processes, and residential health management. Infrared units dominate volume in non-contact screening applications, while forehead and in-ear designs capture premium positioning through faster read times and pediatric suitability. Smart connectivity functionality represents the fastest-expanding margin pool as Bluetooth-enabled models integrate with telehealth platforms and electronic health record systems.
FDA 510(k) clearance requirements and EMA Medical Device Regulation standards enforce strict clinical accuracy thresholds that filter marginal entrants from professional channels. CE marking under EU MDR and ISO 13485 quality management certifications further shape market access for manufacturers targeting European healthcare procurement. WHO prequalification protocols influence tender eligibility across emerging market national health systems. Stakeholders must monitor evolving cybersecurity frameworks for connected devices as regulatory scope broadens beyond physical safety into data integrity and patient privacy domains.
Market Dynamics
Hospital procurement reforms in China and tightening FDA accuracy thresholds are compressing margins for undifferentiated manufacturers while rewarding calibrated, connected-device specialists with premium channel access.
Growth Catalysts
- Home Healthcare Migration:Aging populations in Japan and Germany are relocating chronic disease monitoring from clinics to residential settings, expanding the addressable base for consumer-grade infrared units with clinical-grade precision.
- FDA 510(k) Pathway Consolidation:Streamlined clearance for Bluetooth-enabled thermometers with predicate device alignment is accelerating connected wellness ecosystem integration in the US professional channel.
- Semiconductor Diversification:Multi-source procurement strategies for thermistor and MEMS sensor supply are stabilizing production schedules for manufacturers with qualified secondary vendors.
Market Restraints
- Input Cost Volatility:Rare earth element price swings for infrared sensor substrates are compressing gross margins for non-integrated manufacturers lacking captive material supply.
- Supply Concentration Risk:Foundry capacity for precision analog-to-digital converter chips clusters in Taiwan, exposing order fulfillment to geopolitical disruption and allocation rationing.
- Substitution Pressure:Continuous wearable temperature patches from consumer electronics entrants are displacing episodic measurement occasions in pediatric and athletic monitoring segments.
Strategic Opportunities
- Telehealth Platform Integration:API-standardized data exchange with Epic and Cerner systems is opening enterprise procurement pathways for FDA-cleared connected thermometers in US hospital-at-home programs.
- EU MDR Certification Arbitrage:Early CE marking under strengthened Medical Device Regulation standards is creating first-mover positioning in European tender processes ahead of 2027 compliance deadlines.
- Rural India Penetration:ASHA worker distribution networks and Jan Aushadhi scheme subsidies are unlocking volume demand for sub-$5 digital units in underserved district health systems.
Industry Challenges
- Cybersecurity Compliance Burden:FDA guidance on connected device software validation and EU GDPR health data processing requirements are extending product development timelines by 8-14 months.
- Calibration Workforce Scarcity:ISO 17025-accredited temperature metrology technicians are concentrated in legacy industrial regions, constraining geographic expansion of hospital-grade service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Thermometer Market |
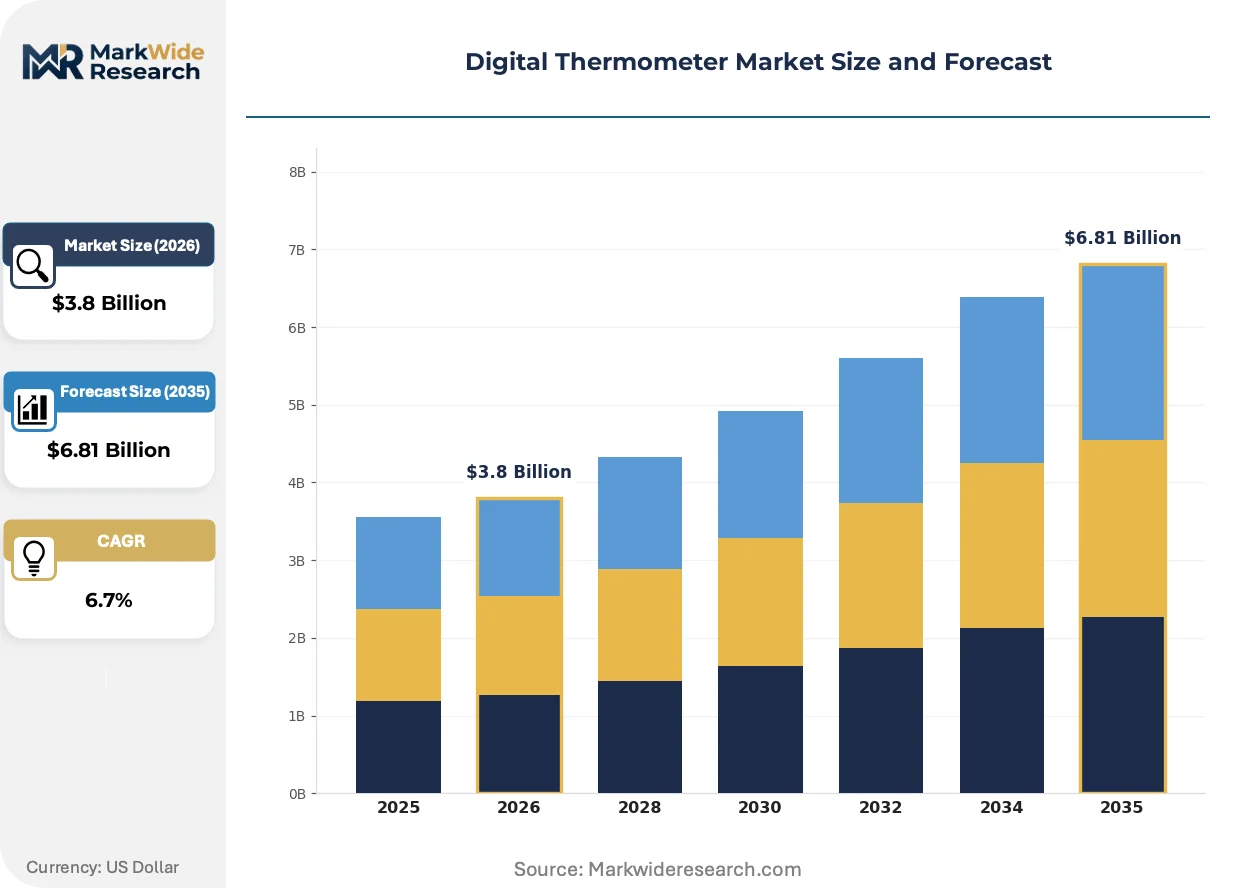
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Pen Type, In-ear, Forehead End User: Home Users, Healthcare Professionals, Hospitals, Clinics Technology: Digital, Analog, Wireless, Smart Functionality: Fever Detection, Body Temperature, Surface Temperature, Liquid Temperature |
| Companies Covered | AMETEK Land, Actherm Inc., OMRON Healthcare Inc., EXTECH, RG Medical Diagnostics, Terumo Corporation, Omega Engineering Inc., Microlife, A&D Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Thermometer Market Emerging Trajectories
Sensor fusion architectures and cloud-native validation protocols are compressing the gap between consumer convenience and clinical reliability, forcing incumbents to rebuild software competencies.
Infrared thermopile arrays with on-chip ambient temperature compensation are unifying non-contact screening accuracy across variable environmental conditions. Airport and school district buyers in Singapore and South Korea are specifying these units for fever detection gateways. The technology is unifying previously separate industrial and medical supply chains under common semiconductor fabrication nodes.
EMA Medical Device Regulation Annex XVI expansion is capturing previously exempt wellness devices with diagnostic claims under notified body supervision. Manufacturers targeting European hospital procurement must now submit clinical evidence packages for infrared forehead units previously sold as consumer goods. German and French distributors are consolidating supplier lists to favor MDR-certified portfolios, squeezing non-compliant Asian exporters toward retail-only channels.
Direct-to-clinic e-commerce platforms are disintermediating traditional medical device distributors for replacement unit purchases. US urgent care chains and independent pediatric practices are sourcing calibrated probes through specialized B2B marketplaces with lot-traceable certificates. This channel migration is most pronounced in Texas and Florida, where practice consolidation has centralized purchasing authority and standardized device specifications across clinic networks.
Digital Thermometer Market Segmentation
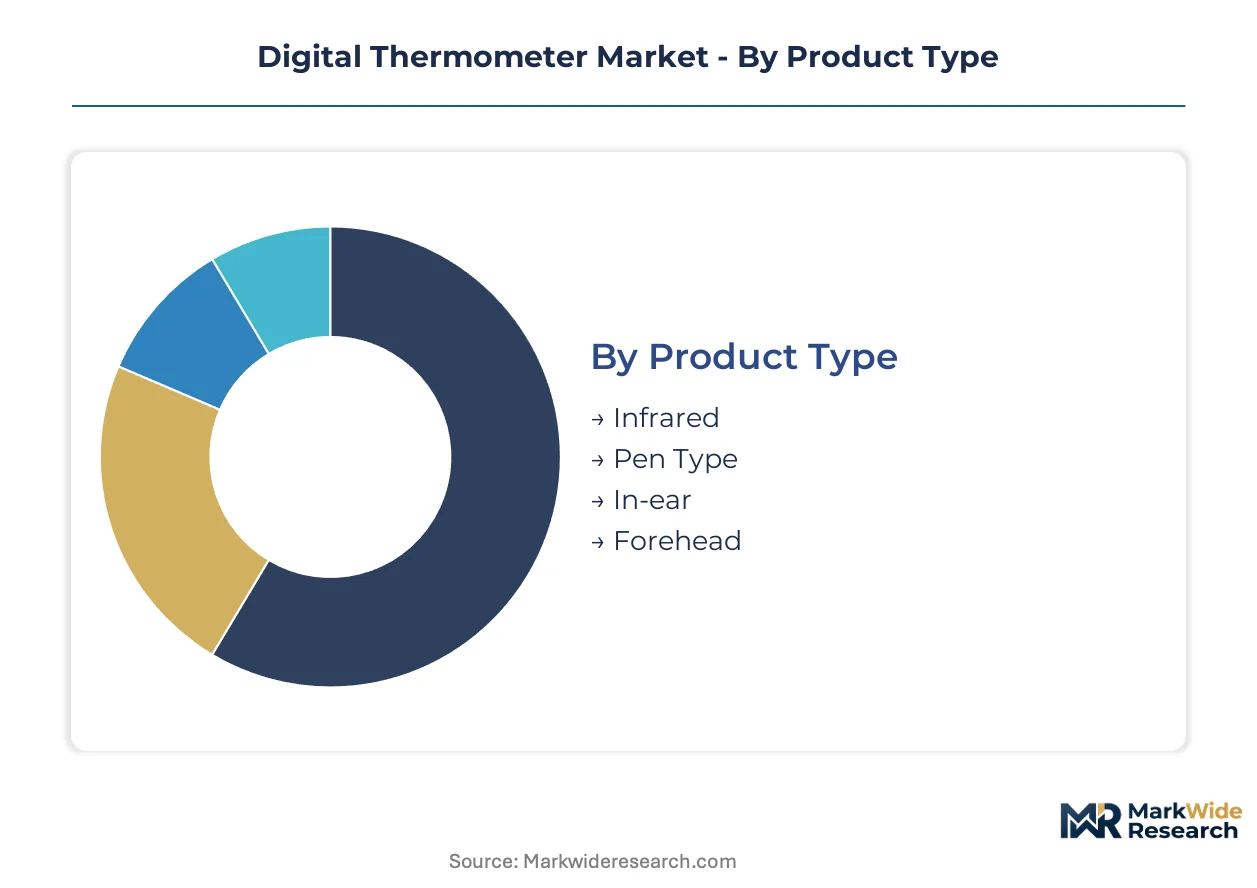
Digital thermometer segmentation reflects divergent supply chain requirements across contact and non-contact architectures. Manufacturers configure sensor sourcing, calibration protocols, and distribution channels differently for each product category.
Product Type:
Component sourcing for infrared sensors concentrates among specialized thermopile foundries, while pen-type units rely on standardized thermistor supply.
- Infrared:Non-contact thermopile arrays with ambient temperature compensation enable rapid screening across variable environmental conditions. Airport and school procurement in Singapore and South Korea specifies these units for fever detection gateways.
- Pen Type:Traditional thermistor-based oral/rectal designs with ±0.1°C accuracy serve pediatric and geriatric home monitoring where contact measurement remains preferred. Demand clusters in Japan and Germany as aging populations relocate chronic care to residential settings.
- In-ear:Tympanic membrane measurement via infrared sensors captures core body temperature with 1-3 second read times. Clinical-grade calibration requirements filter marginal suppliers from hospital procurement channels.
- Forehead:Temporal artery scanning balances speed with non-invasive appeal for pediatric applications. FDA 510(k) predicate alignment accelerates clearance timelines for connected variants.
Infrared absorbs the bulk of installed capacity; forehead designs are expanding most quickly.
End User:
Channel economics diverge sharply between direct hospital procurement and retail consumer distribution.
- Home Users:Price-sensitive demand for sub-$15 units dominates volume, with Bluetooth connectivity emerging as a margin differentiator in North American and European markets.
- Healthcare Professionals:Clinical-grade calibration certificates and ISO 13485 traceability requirements constrain supplier eligibility. German and French distributors consolidate vendor lists toward MDR-certified portfolios.
- Hospitals:Enterprise procurement specifications mandate FDA-cleared or CE-marked devices with EHR integration capability. US hospital-at-home programs specify API-standardized data exchange with Epic and Cerner systems.
- Clinics:Replacement unit purchasing migrates toward direct-to-clinic B2B marketplaces with lot-traceable certificates. Texas and Florida practice consolidation drives specification standardization across clinic networks.
Hospitals command the highest unit economics; home users deliver steepest volume expansion.
Technology:
Semiconductor content and software validation burdens scale with connectivity sophistication.
- Digital:Solid-state thermistor or thermocouple conversion with LCD display dominates baseline manufacturing. Multi-source procurement strategies stabilize production schedules against foundry allocation volatility.
- Analog:Legacy mercury-alternative designs with limited semiconductor content serve cost-constrained emerging markets. Indian Jan Aushadhi scheme subsidies target this tier for rural ASHA worker distribution.
- Wireless:Bluetooth Low Energy transmission to smartphone apps enables telehealth platform integration. FDA guidance on connected device software validation extends development timelines by 8-14 months.
- Smart:Cloud-native firmware with predictive fever algorithms and multi-user household profiles. Cybersecurity compliance under EU GDPR and FDA data integrity requirements reshapes competitive entry barriers.
Digital platforms anchor current manufacturing scale; smart connectivity gains share fastest.
Functionality:
Calibration protocols and sensor packaging differ materially across measurement targets.
- Fever Detection:Algorithmic thresholds with color-coded alerts for home screening applications. WHO prequalification protocols influence tender eligibility across emerging market national health systems.
- Body Temperature:Core temperature correlation methods vary by anatomical site—oral, rectal, tympanic, or temporal. Clinical accuracy standards under FDA 510(k) and EMA MDR enforce strict predicate alignment.
- Surface Temperature:Industrial-process thermopile applications with wider measurement ranges share fabrication nodes with medical variants. Airport fever gateways in South Korea specify cross-calibrated surface-body modes.
- Liquid Temperature:Food safety and laboratory applications with immersion-rated probe assemblies. Distinct supply chains from medical-grade units reduce semiconductor input cost exposure.
Body temperature measurement retains dominant revenue share; fever detection climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of digital thermometer procurement volume, with hospital procurement reforms and domestic manufacturing scale reshaping competitive dynamics across Asia and export markets.
China
Hospital procurement reforms concentrate demand for connected thermometers with EHR integration capability. NMPA device classification rules enforce accuracy standards that filter marginal domestic manufacturers from professional channels. Shenzhen and Dongguan manufacturing clusters dominate thermopile sensor assembly for infrared units.
United States
Hospital-at-home programs expand the addressable base for FDA-cleared Bluetooth-enabled devices with Epic and Cerner API compatibility. FDA 510(k) clearance requirements enforce strict clinical accuracy thresholds for professional channel access. Texas and Florida practice consolidation drives specification standardization across urgent care networks.
Germany
Aging population migration of chronic disease monitoring to residential settings expands demand for clinical-grade home units. EMA Medical Device Regulation standards and ISO 13485 quality management certifications shape hospital procurement eligibility. Bavaria-based distributors consolidate vendor lists toward MDR-certified portfolios.
India
ASHA worker distribution networks and Jan Aushadhi scheme subsidies unlock volume demand for sub-$5 digital units in rural district health systems. CDSCO medical device regulations tighten import standards for clinical-grade thermometers. Maharashtra and Gujarat manufacturing hubs scale thermistor-based pen-type production for domestic and African export markets.
Japan
Super-aged demographic structure relocates temperature monitoring from clinics to residential settings at accelerating rates. PMDA medical device standards and JIS quality certifications maintain high barriers to professional channel entry. Osaka and Nagoya industrial corridors concentrate precision calibration service capabilities.
Digital Thermometer Market Vendor Landscape
Multi-source component procurement dominates the current landscape as manufacturers diversify sensor and chipset suppliers to mitigate semiconductor volatility. The vendor base fragments across integrated healthcare conglomerates, specialized temperature measurement firms, and emerging connected-device entrants. Three strategic archetypes define positioning: calibrated clinical-grade specialists, price-competitive home-user suppliers, and smart connectivity platform builders. Portfolio diversification into telehealth ecosystems and geographic expansion through distributor consolidation represent the dominant competitive moves.
Among Japanese healthcare conglomerates, OMRON Healthcare Inc. and Terumo Corporation exemplify contrasting archetypes—one leveraging established distribution networks across Asia and Europe, the other anchoring position through specialized hospital-grade calibration protocols. Microlife occupies a position within the price-competitive tier while extending portfolio presence into connected wellness ecosystems. These three entities represent the spectrum from premium clinical positioning to volume home-user penetration.
| Leading Market Players |
|---|
| AMETEK Land |
| Actherm Inc. |
| OMRON Healthcare Inc. |
| EXTECH |
| RG Medical Diagnostics |
| Terumo Corporation |
| Omega Engineering Inc. |
| Microlife |
| A&D Medical |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FDA-cleared clinical units and unmarked consumer devices manifests in divergent pricing power and sourcing strategies across the digital thermometer landscape. Premium hospital-grade suppliers command three-to-five-fold unit economics over retail-channel competitors, while supply chain configurations split between precision-calibration service networks and high-volume thermistor assembly lines.
Pricing Analysis
Volume-mass home-user segments absorb sub-$15 price points with minimal margin protection, while clinical-grade hospital procurement sustains premium positioning through ISO 13485 traceability and FDA 510(k) predicate alignment. Price differentiation rests on calibration certificate validity and Bluetooth connectivity bundling. Cost compression in the infrared sensor tier is intensifying because rare earth substrate volatility feeds through thermopile foundry quotations. Retail consumers exhibit extreme price sensitivity; hospital purchasing committees prioritize accuracy certification over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's hospital procurement reforms are reshaping sourcing patterns for NMPA-registered manufacturers. Thermopile sensor fabrication concentrates in Taiwan, South Korea, and mainland China; precision analog-to-digital converter chips draw from Taiwanese foundry capacity. Rare earth elements for infrared substrates and MEMS sensor wafers constitute critical input dependencies. Single-source vulnerability in Taiwan semiconductor fabrication exposes order fulfillment to geopolitical disruption. Distribution runs through specialized medical device distributors in professional channels and mass retail in consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited calibration technician scarcity props pricing for hospital-grade service capabilities, constraining geographic expansion and sustaining margin pools for qualified incumbents.
For Market Incumbents: Cement channel control through backward integration into precision temperature metrology services, offsetting workforce scarcity in calibration capabilities. Defend against wearable temperature patch substitution by accelerating FDA clearance for continuous monitoring companions. Prioritize captive supply of thermopile sensors through qualified secondary vendor qualification programs. For New Entrants and Emerging Players: Capture rural India volume through Jan Aushadhi scheme subsidy alignment and ASHA worker distribution network partnerships. Target the telehealth platform integration white space with API-standardized Epic and Cerner compatibility. Lead with direct-to-clinic B2B marketplace positioning in Texas and Florida consolidated practice networks. For Investors and Strategic Acquirers: Re-rating potential sits with MDR-certified mid-tier specialists given EMA Annex XVI expansion capturing previously exempt wellness devices under notified body supervision. Five-to-ten year viability favors manufacturers with early CE marking completion and cloud-native firmware competencies. Watch FDA cybersecurity guidance enforcement as inflection indicator for connected-device competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined predicate alignment opens US hospital-at-home procurement pathways for Bluetooth-enabled units. |
| EU MDR Certification Completion | Early CE marking creates first-mover positioning in German and French tender consolidation ahead of compliance deadlines. |
| Telehealth Platform Integration | API-standardized Epic and Cerner data exchange unlocks enterprise procurement in US hospital-at-home programs. |
| Multi-Source Sensor Procurement | Qualified secondary thermistor and MEMS vendors stabilize production schedules against Taiwan foundry allocation volatility. |
| Calibration Service Network Expansion | ISO 17025-accredited technician training programs extend hospital-grade service capabilities into underserved geographic markets. |
Methodological Framework
FDA 510(k) filings, EMA MDR submission databases, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and infrared sensor procurement leads at thermopile foundries validated demand-side assumptions. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product type, end user, and technology segmentation dimensions.
Bottom-up modeling anchored volume projections while top-down macro checks bounded the analytical envelope across the projection horizon. Segmentation dimensions spanned contact versus non-contact architectures, home user versus healthcare professional versus hospital versus clinic channels, and digital versus analog versus wireless versus smart connectivity tiers. CAGR derivation incorporated semiconductor input cost trajectories, regulatory compliance timeline assumptions, and telehealth platform adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan geopolitical disruption, wearable temperature patch substitution velocity, and FDA cybersecurity guidance implementation timing. Forecasts reflect documented assumptions regarding foundry capacity allocation, rare earth element price stability, and EMA MDR enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market