
 Touchless Sensing Market | 2026-2036
Touchless Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Touchless Sensing Market Outlook
ISO/IEC 30107-3 liveness detection certification is redrawing competitive boundaries in biometric sensing. Infineon Technologies leverages its sensor fabrication expertise to anchor European automotive programs. Qualcomm Incorporated dominates mobile gesture platforms through integrated RF and AI processing.
Touchless sensing encompasses non-contact detection technologies that capture proximity, motion, or physiological signals through infrared, ultrasonic, optical, or electromagnetic modalities, typically operating at detection ranges from millimeters to several meters with response latencies under 50 milliseconds. These systems serve industrial and commercial purposes by enabling hygienic human-machine interfaces, automated access control, and predictive equipment monitoring without physical contact. Infrared sensors lead commercial deployments due to mature supply chains and cost scalability, while ultrasonic systems capture expanding share in automotive parking assistance and industrial proximity applications where environmental robustness commands premium positioning. Optical sensors concentrate margin pools in healthcare authentication and consumer biometric devices, though RFID systems sustain steady industrial tracking volumes.
FDA device classification rules govern clinical touchless monitoring systems, while the EU AI Act imposes conformity obligations on biometric inference engines deployed in European smart infrastructure. The FCC regulates spectrum allocation for ultrasonic and RF sensing arrays in the United States, directly constraining product architecture for cross-border vendors. Stakeholders must monitor evolving liveness detection mandates and spectrum harmonization negotiations to preserve market access across major deployment zones.
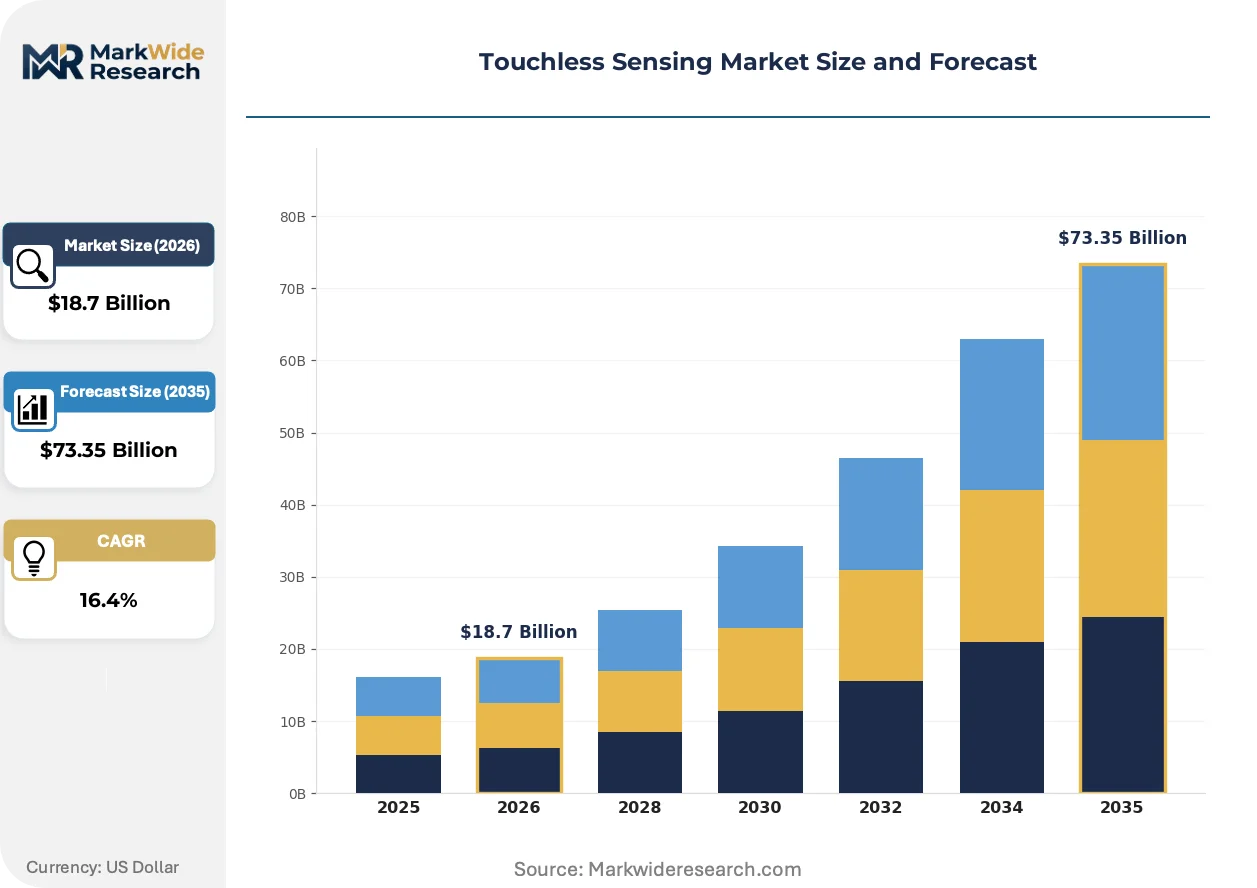
Market Dynamics
ISO/IEC 30107-3 liveness detection mandates are restructuring competitive entry barriers across biometric sensing deployments, forcing hardware vendors to recertify optical and infrared modules while healthcare and automotive buyers consolidate supplier bases around certified platforms.
Growth Catalysts
- EU AI Act Conformity Obligations:Biometric inference engines deployed in European smart infrastructure must achieve third-party audit certification, creating replacement demand for legacy access control systems in Germany and France.
- Automotive Parking Assistance:Ultrasonic proximity arrays are capturing expanding specification share in connected vehicle platforms as Tier-1 suppliers integrate multi-modal sensing for automated maneuvering.
- Infection Control Protocols:Healthcare providers in Japan and the United States are mandating touchless interfaces for patient-facing equipment, accelerating infrared and capacitive proximity retrofits in clinical settings.
Market Restraints
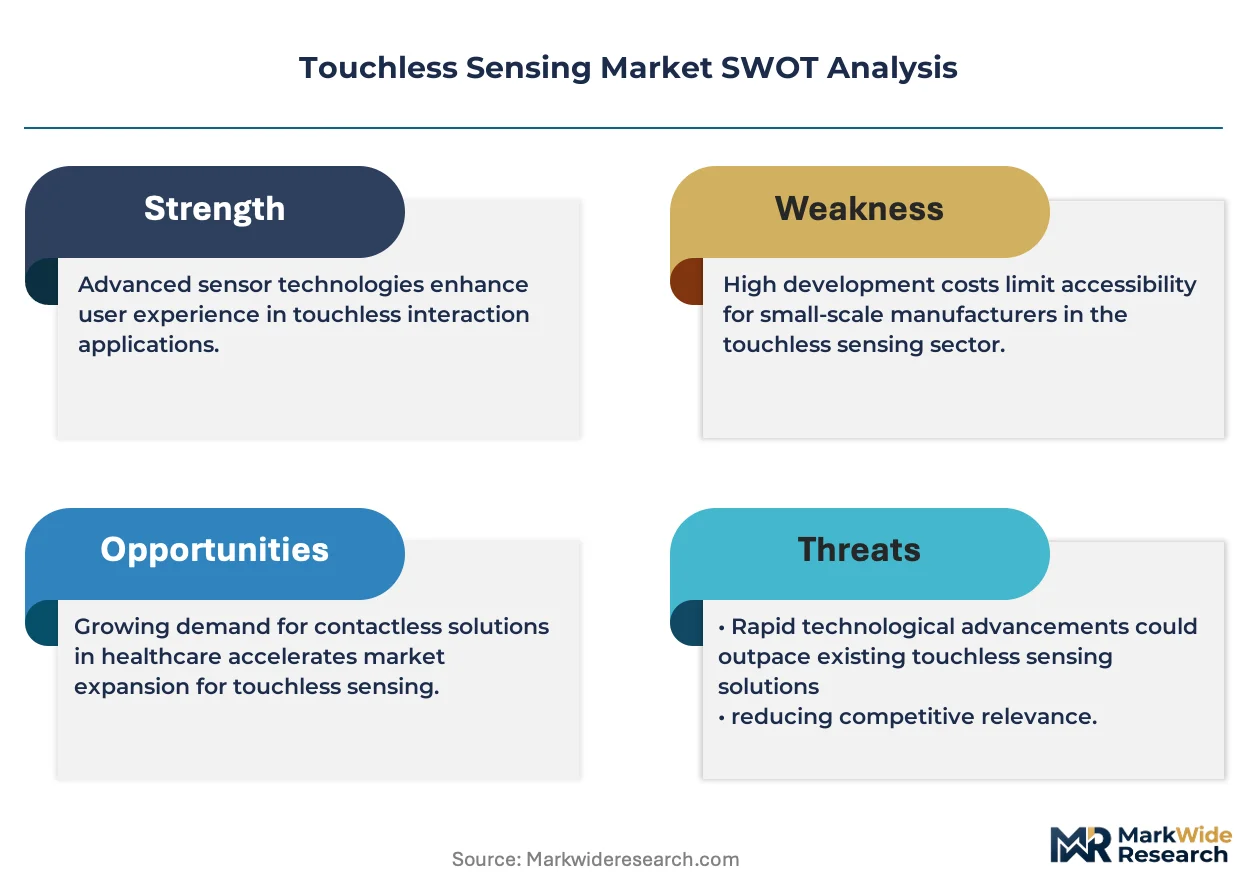
- Indium Gallium Arsenide Cost Volatility:Near-infrared detector substrates face supply concentration from single-source epitaxy vendors, compressing margins for optical biometric module producers.
- FCC Spectrum Allocation Constraints:Ultrasonic and RF sensing arrays face transmit power restrictions in the United States, forcing architectural compromises for cross-border product platforms.
- Ambient Light Interference:Optical time-of-flight systems suffer performance degradation under direct sunlight, limiting outdoor deployment viability for facial authentication terminals.
Strategic Opportunities
- India Smart City Infrastructure:Municipal touchless transit and access systems remain underpenetrated, with BIS certification pathways opening for infrared and RFID platform vendors.
- Convergence of mmWave Radar and AI Edge Processing:Integrated RF sensing with on-device inference is enabling new gesture recognition categories in industrial human-machine interfaces.
- Japan METI Carbon-Neutral Building Codes:Touchless HVAC and lighting control systems qualify for subsidy allocation, redirecting demand toward occupancy sensing with energy management integration.
Industry Challenges
- ISO/IEC 30107-3 Certification Timelines:Liveness detection validation requires 12-18 month laboratory testing cycles, delaying product launches for biometric sensor vendors.
- Legacy Building Management System Integration:Touchless retrofit deployments face protocol fragmentation across BACnet, Modbus, and proprietary automation networks, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touchless Sensing Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared Sensors, Ultrasonic Sensors, RFID Systems, Optical Sensors Application: Healthcare Equipment, Smart Home Devices, Automotive Systems, Industrial Automation End User: Consumers, OEMs, Healthcare Providers, Retailers Market Segment: Commercial, Residential, Industrial, Transportation |
| Companies Covered | Microsoft Corporation, Microchip Technology Inc., Intel Corporation, Google LLC, Apple Inc., Infineon Technologies, Qualcomm Incorporated, Texas Instruments, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touchless Sensing Market Strategic Shifts
Software-defined sensing architectures are unbundling hardware from algorithmic processing, enabling modular upgrades without full system replacement while compressing product lifecycles across industrial and consumer segments.
Time-of-flight depth sensing is decomposing traditional stereo camera architectures in automotive cabin monitoring and industrial safety systems. Tier-1 automotive suppliers in Germany are adopting solid-state lidar-on-chip platforms for occupant detection and gesture control. This technology shift is decomposing the incumbent supply chain for discrete photodiode arrays and lens assemblies, consolidating value capture within semiconductor foundries.
The EU AI Act's biometric identification classification rules are imposing conformity assessment obligations on inference engines processing physiological signals. European smart infrastructure procurements now require documented algorithmic audit trails and bias testing protocols. Healthcare authentication vendors targeting EU hospital networks are restructuring product roadmaps to embed explainability features and third-party certification before 2025 deployment windows.
Hospital procurement committees are consolidating vendor selection around integrated platform providers capable of delivering hardware, software, and compliance documentation through single-source contracts. This behavior shift is displacing point-solution specialists in North American and European healthcare markets. Integrated platform vendors with captive certification capabilities are capturing expanding specification share in radiology and surgical suite deployments.
Touchless Sensing Market Segmentation
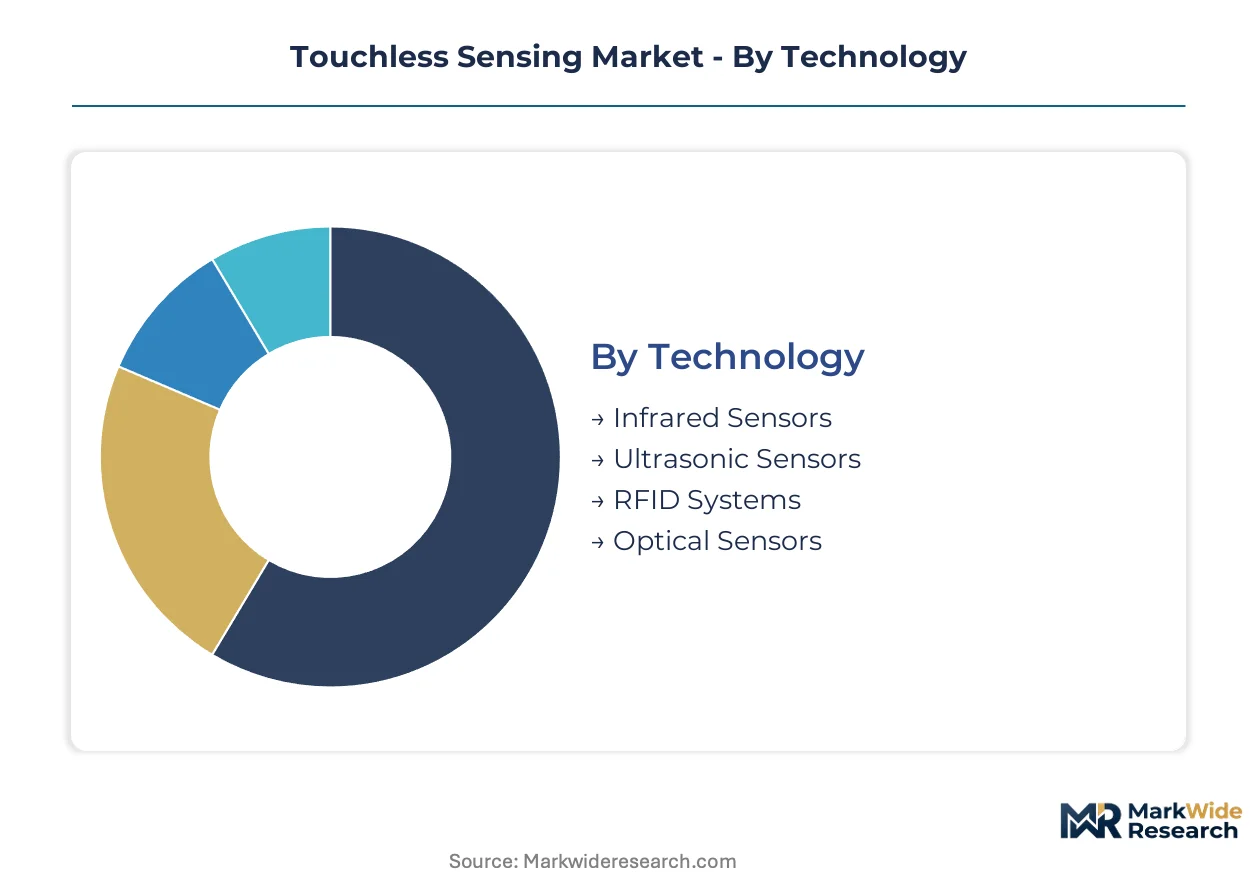
Technology modality determines cost structure and environmental robustness in touchless sensing deployments. Application context governs regulatory pathway and certification burden. End-user concentration shapes procurement scale and integration complexity.
Technology:
Ultrasonic and mmWave modalities exert substitution pressure on legacy infrared architectures in automotive and industrial settings where moisture tolerance and precision ranging command specification priority.
- Infrared Sensors:These devices detect thermal radiation emitted by objects within their field of view, typically operating at wavelengths between 700 nanometers and 1 millimeter. Healthcare providers in Germany and Japan specify infrared proximity modules for patient-facing equipment where infection control protocols mandate contactless interfaces. Indium gallium arsenide substrate costs compress margins for near-infrared biometric variants.
- Ultrasonic Sensors:Piezoelectric transducers emit high-frequency sound pulses and calculate distance through time-of-flight measurement, achieving centimeter-level accuracy in parking assistance and liquid-level monitoring. Tier-1 automotive suppliers in the United States integrate multi-element arrays for automated maneuvering systems, though FCC transmit power restrictions constrain cross-border platform designs.
- RFID Systems:Radio-frequency identification enables passive or active tag detection through electromagnetic coupling, sustaining steady volumes in industrial asset tracking and supply chain logistics.
- Optical Sensors:Structured light and time-of-flight cameras capture depth maps for facial authentication and gesture recognition, facing performance degradation under direct sunlight in outdoor deployments.
Infrared sensors anchor the volume base while ultrasonic configurations gain share at the steepest rate.
Application:
Healthcare equipment carries the heaviest compliance burden, with FDA device classification and EU AI Act conformity obligations filtering vendor participation.
- Healthcare Equipment:Touchless patient monitoring, surgical interface control, and clinical access systems require ISO/IEC 30107-3 liveness detection certification for biometric deployments. Hospital procurement committees in France and the United States consolidate supplier selection around integrated platform providers capable of delivering hardware, software, and audit documentation through single-source contracts.
- Automotive Systems:Cabin occupancy detection, gesture-controlled infotainment, and exterior parking assistance drive specification of solid-state lidar-on-chip and ultrasonic proximity arrays. German OEMs anchor European demand for multi-modal sensing platforms in connected vehicle architectures.
- Smart Home Devices:Voice-activated assistants, occupancy-responsive climate control, and security authentication systems integrate infrared and optical proximity modules for consumer convenience.
- Industrial Automation:Predictive equipment monitoring, safety zone enforcement, and hygienic machine interfaces deploy ultrasonic and capacitive sensing in manufacturing environments.
Healthcare equipment commands the steepest pricing tiers while automotive systems expand most quickly.
End User:
OEM procurement scale dwarfs direct consumer purchasing, with automotive and healthcare device manufacturers dictating specification roadmaps.
- OEMs:Automotive Tier-1 suppliers and medical device manufacturers source touchless sensing modules at volume scale, embedding liveness detection and RF processing into integrated subsystems. These buyers negotiate multi-year supply agreements with certification guarantees.
- Healthcare Providers:Hospital networks and clinical operators mandate touchless retrofits for infection control, consolidating vendor bases around platforms with captive FDA and EU AI Act documentation capabilities.
- Consumers:Individual purchasers acquire smart home devices and biometric peripherals through retail channels, showing price sensitivity and feature-driven selection behavior.
- Retailers:Big-box and specialty electronics distributors curate touchless product assortments, influencing brand visibility without direct technology specification authority.
OEMs dominate procurement volume while healthcare providers drive compliance-intensive premium segments.
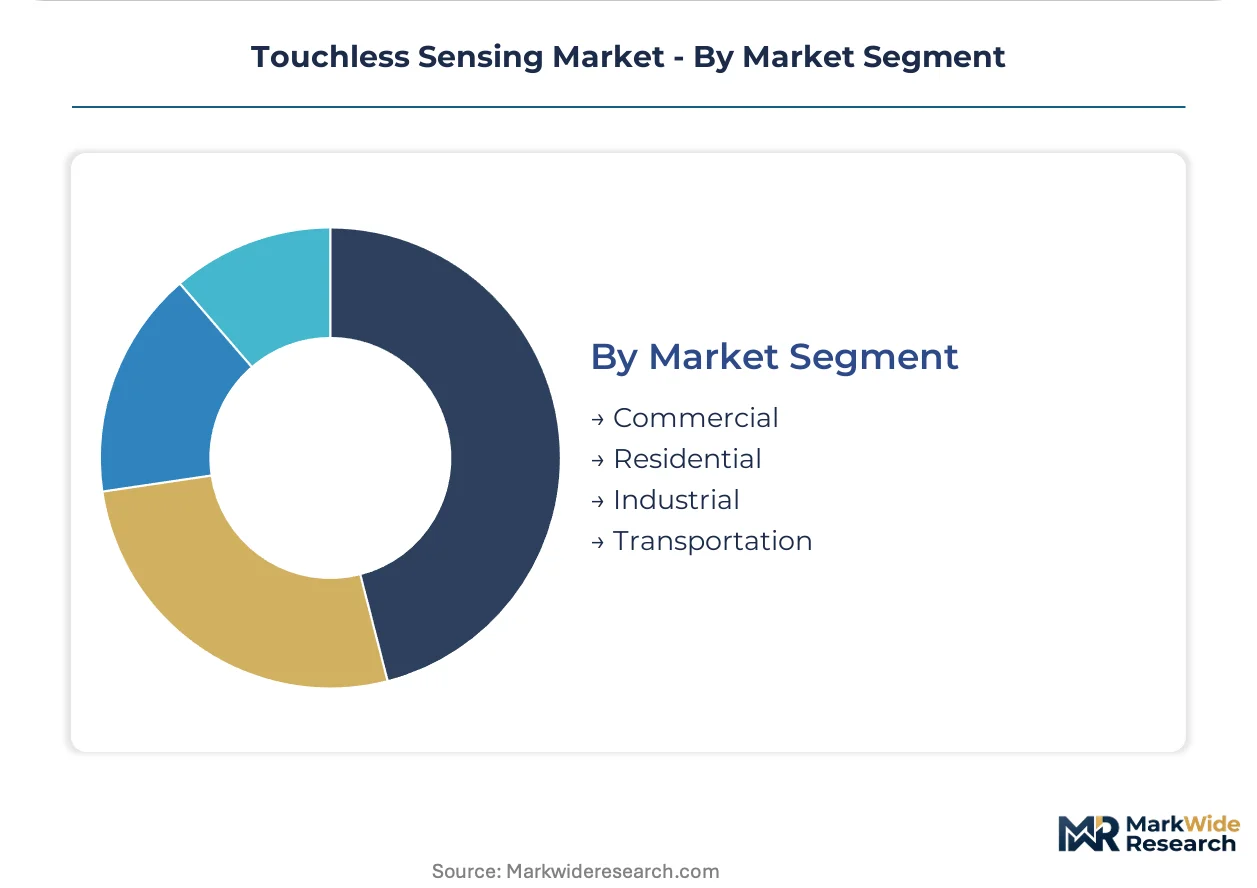
Market Segment:
Industrial deployments prioritize environmental robustness over aesthetic refinement, accepting higher unit costs for reliability certification.
- Industrial:Manufacturing facilities, warehouses, and process plants deploy touchless sensing for equipment monitoring, safety interlocks, and hygienic operator interfaces. Japan METI carbon-neutral building codes subsidize occupancy-based HVAC and lighting control in industrial facilities.
- Transportation:Connected vehicles, smart transit infrastructure, and logistics hubs integrate multi-modal sensing for automated maneuvering and passenger authentication. India municipal transit systems present underpenetrated demand for touchless fare collection and access control.
- Commercial:Office buildings, retail environments, and hospitality venues specify touchless access and climate control for occupant convenience and energy management.
- Residential:Single-family and multi-unit dwellings adopt smart home sensing for security, convenience, and utility optimization at consumer price points.
Industrial installations anchor the revenue base while transportation applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems and automotive OEMs concentrate procurement authority in Germany, the United States, and Japan, with smart infrastructure investments in India creating parallel demand channels for certified touchless sensing platforms.
United States
Hospital networks mandate touchless retrofits for infection control while Tier-1 automotive suppliers integrate multi-modal sensing arrays. FCC transmit power restrictions constrain ultrasonic and RF sensing architectures for cross-border platforms. Detroit-area automotive clusters and Boston-Washington healthcare corridors anchor specification activity.
Germany
OEMs specify solid-state lidar-on-chip platforms for connected vehicle architectures while municipal smart infrastructure procurements accelerate. EU AI Act conformity obligations filter vendor participation in biometric inference engine deployments. Bavarian automotive engineering centers and North Rhine-Westphalian industrial automation clusters concentrate development activity.
Japan
METI carbon-neutral building codes subsidize occupancy-based HVAC and lighting control systems in industrial and commercial facilities. Healthcare providers mandate touchless interfaces for patient-facing equipment in clinical settings. Kanto region electronics manufacturers and Kansai industrial automation specialists drive module specification.
India
Municipal transit systems present underpenetrated demand for touchless fare collection and access control infrastructure. BIS certification pathways open for infrared and RFID platform vendors targeting smart city deployments. Maharashtra and Karnataka state governments anchor pilot program procurement for urban sensing networks.
France
Hospital procurement committees consolidate supplier selection around integrated platform providers with EU AI Act documentation capabilities. Smart building retrofits in commercial districts drive demand for occupancy sensing with energy management integration. Paris-Saclay technology cluster and Lyon healthcare corridor concentrate vendor qualification activity.
Touchless Sensing Market Competitive Environment
Player mix skews toward diversified semiconductor conglomerates with captive sensor fabrication capabilities. Market structure concentrates specification authority among Tier-1 automotive suppliers and healthcare device OEMs who negotiate multi-year supply agreements. Three archetypes dominate: integrated platform providers with certification capabilities, specialized sensor module vendors, and software-defined sensing stack suppliers. Competitive moves center on liveness detection certification acquisition and software-hardware unbundling for modular upgrade pathways.
Among diversified semiconductor conglomerates, Infineon Technologies, Qualcomm Incorporated, and Texas Instruments occupy positions spanning automotive, mobile, and industrial sensing verticals. These entities exemplify the integrated archetype through captive fabrication capabilities and multi-modal technology portfolios. Specialized module vendors sit within a fragmented mid-tier serving point-solution requirements. Software-defined sensing specialists represent an emerging competitive vector unbundling algorithmic processing from hardware substrates.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Microchip Technology Inc. |
| Intel Corporation |
| Google LLC |
| Apple Inc. |
| Infineon Technologies |
| Qualcomm Incorporated |
| Texas Instruments |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Multi-year capacity reservation agreements with indium gallium arsenide epitaxy vendors lock in both substrate supply access and near-infrared detector pricing visibility for optical biometric module producers serving FDA-regulated healthcare deployments.
Pricing Analysis
Cost-plus contracts indexed to indium and gallium metal exchanges dominate raw material procurement for near-infrared optical sensors. Three-tier pricing structure across medical-grade ISO/IEC 30107-3 certified, industrial-grade, and consumer-grade modules separates buyers by compliance burden and volume scale. Price differentiation hinges on certification grade and captive fabrication capabilities. Cost compression in consumer infrared modules is intensifying because Chinese module vendors are expanding 8-inch MEMS foundry capacity. Healthcare OEMs exhibit lowest price sensitivity due to regulatory compliance requirements, while smart home device manufacturers face acute margin pressure.
Supply Chain Analysis
Germany and Japan anchor precision sensor fabrication for automotive and healthcare applications, while Taiwan concentrates wafer-level optical packaging capacity. Supply draws from indium phosphide substrates, piezoelectric ceramics for ultrasonic transducers, and RF front-end components for mmWave arrays. Single-source vulnerability concentrates in indium gallium arsenide epitaxy equipment. Distribution runs through Tier-1 automotive supplier direct procurement and hospital GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO/IEC 30107-3 certification fragmentation is creating specialist niches as hospital procurement committees abandon point-solution vendors for integrated platform providers.
For Market Incumbents: Secure liveness detection certification lock-in by acquiring third-party audit laboratories or exclusive testing partnerships before EU AI Act enforcement windows tighten. Expand captive indium gallium arsenide substrate production through backward integration into epitaxy equipment to offset margin compression from single-source supply concentration. For New Entrants and Emerging Players: ISO/IEC 30107-3 fast-track certification through European notified body partnerships enables qualification for German and French hospital procurement cycles. India municipal transit systems present the most penetrable geography for RFID and infrared platform vendors. Target BIS certification pathways as the primary go-to-market angle for smart city infrastructure tenders. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined sensing stack specialists with modular algorithm-hardware unbundling capabilities. Long-term viability over the next decade rests on owning inference engine intellectual property independent of sensor hardware commoditization. Watch FDA device classification rule expansions into AI-enabled physiological monitoring as the inflection signal for healthcare authentication valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Acquisition | Unlocks EU hospital procurement and automotive biometric deployment specifications. |
| Backward Integration into Epitaxy Equipment | Captures margin pool from indium gallium arsenide substrate supply concentration. |
| Software-Defined Sensing Architecture Launch | Enables modular algorithm upgrades without full hardware replacement cycles. |
| India BIS Certification Pathway Investment | Positions vendors for Maharashtra and Karnataka smart city pilot procurements. |
| EU AI Act Conformity Documentation Buildout | Creates single-source contract eligibility for French and German infrastructure buyers. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers at German and Japanese hospital networks, Tier-1 automotive supplier procurement leads, and BIS certification consultants in India, then refined against secondary validation from FDA 510(k) filings, EU AI Act implementation guidance, SEC 10-K sensor segment disclosures, and IHS Markit vehicle production databases. Bottom-up module shipment estimates were triangulated with top-down healthcare capital expenditure tracking.
Variance decomposition across technology modality, application regulatory pathway, and end-user procurement scale shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic healthcare and automotive production indicators. Modeled inputs included ISO/IEC 30107-3 certification adoption curves and India smart city infrastructure budget allocations.
Underlying assumptions cover EU AI Act enforcement timing and indium gallium arsenide supply expansion, with deviation risk concentrated in FCC spectrum reallocation decisions and Japan METI subsidy program modifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Acoustic Breathing Sensor Market