
 Instaprint Camera Market | 2026-2036
Instaprint Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Instaprint Camera Market Foresight
Market Context
Specialized optical engineering talent is reorganizing competitive dynamics as legacy film expertise becomes scarce and digital-print hybrid skills command premium wages. FUJIFILM Holdings Corporation leverages its vertical integration across film chemistry and lens manufacturing to sustain margin control from raw materials to retail. Polaroid International B.V. anchors brand nostalgia through licensed partnerships and direct-to-consumer channels. Canon Inc. competes on sensor miniaturization and color science IP transferred from its professional camera division.
Technical Definition and Segment Structure
An instaprint camera is a self-contained imaging device that captures photographs and produces physical prints within seconds through integrated thermal, chemical, or zero-ink (Zink) sublimation mechanisms, typically operating at resolutions between 300 and 600 DPI for wallet-sized outputs. These devices serve commercial event documentation, personal memorabilia creation, and retail kiosk applications where immediate tangible output carries higher perceived value than digital-only distribution. The product type dimension shows instant film retaining the largest revenue pool due to consumable replenishment cycles, while hybrid instant-digital models represent the fastest expansion as users seek simultaneous social sharing and physical keepsakes. Among end users, event planners command the highest per-unit spend and recurring bulk orders, whereas retail consumers drive volume through seasonal gifting patterns concentrated in fourth-quarter retail windows.
Regulatory Framework and Outlook
The US EPA regulates chemical waste streams from thermal development processes, while the EU REACH framework governs substrate coatings and adhesive compounds used in instant film packs; Japan's METI enforces JIS standards on electromagnetic compatibility and battery safety for portable electronics. Compliance with these overlapping regimes elevates R&D overhead for new entrants but also creates defensible moats for incumbents with established testing protocols and regional certification relationships. Stakeholders must monitor evolving restrictions on perfluorinated compounds in paper substrates, as regulatory tightening in Europe and North America could force reformulation of core consumable lines within the forecast window.
Market Dynamics
Specialized optical engineering talent is reorganizing competitive dynamics as legacy film expertise becomes scarce and digital-print hybrid skills command premium wages. This structural constraint on human capital availability is forcing manufacturers to redesign production workflows and accelerate automated assembly investments.
Growth Catalysts
- Experiential Marketing Budget Expansion:Event planners in North America and Western Europe are allocating larger shares of client budgets to interactive photo activations, driving bulk hardware procurement and recurring consumable orders.
- EU RoHS Directive Compliance:Restrictions on hazardous substances in electronics are accelerating reformulation of thermal transfer ribbons and adhesive substrates, creating first-mover advantages for suppliers with certified alternative chemistries.
- Heritage Manufacturing Clusters:Domestic production networks in Japan sustain premium positioning through controlled scarcity and artisanal quality signaling that commands price premiums in Asian luxury retail channels.
Market Restraints
- Silver Halide Supply Concentration:Instant film chemistry depends on refined silver compounds sourced from a narrowing base of specialty chemical processors, exposing margins to commodity volatility and geopolitical supply disruptions.
- Zero-Ink Substrate Cost Structure:Zink paper manufacturing requires proprietary dye-crystal embedding processes with limited qualified substrate suppliers, constraining cost-down trajectories for entry-tier product lines.
- Smartphone Camera Substitution:Computational photography and instant digital sharing platforms reduce the perceived utility of dedicated single-function devices among casual users, compressing addressable market breadth.
Strategic Opportunities
- India Wedding Industry Penetration:The country's unorganized event photography sector presents white-space potential for rental-based instaprint kiosk deployment at mass-market price points.
- US IRA Green Manufacturing Incentives:Domestic battery production tax credits and clean energy manufacturing provisions could subsidize localized assembly of rechargeable hybrid models.
- Social Commerce Channel Convergence:TikTok Shop and Instagram Checkout integration enables direct-to-consumer bundling of hardware with consumable subscription programs, bypassing traditional retail margin stacking.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:The hybrid skill set combining analog photochemistry, thermal engineering, and embedded firmware development is concentrated among aging specialists with limited pipeline replenishment.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of FCC electromagnetic approvals, CE marking under RED and RoHS, and METI battery safety testing extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instaprint Camera Market |
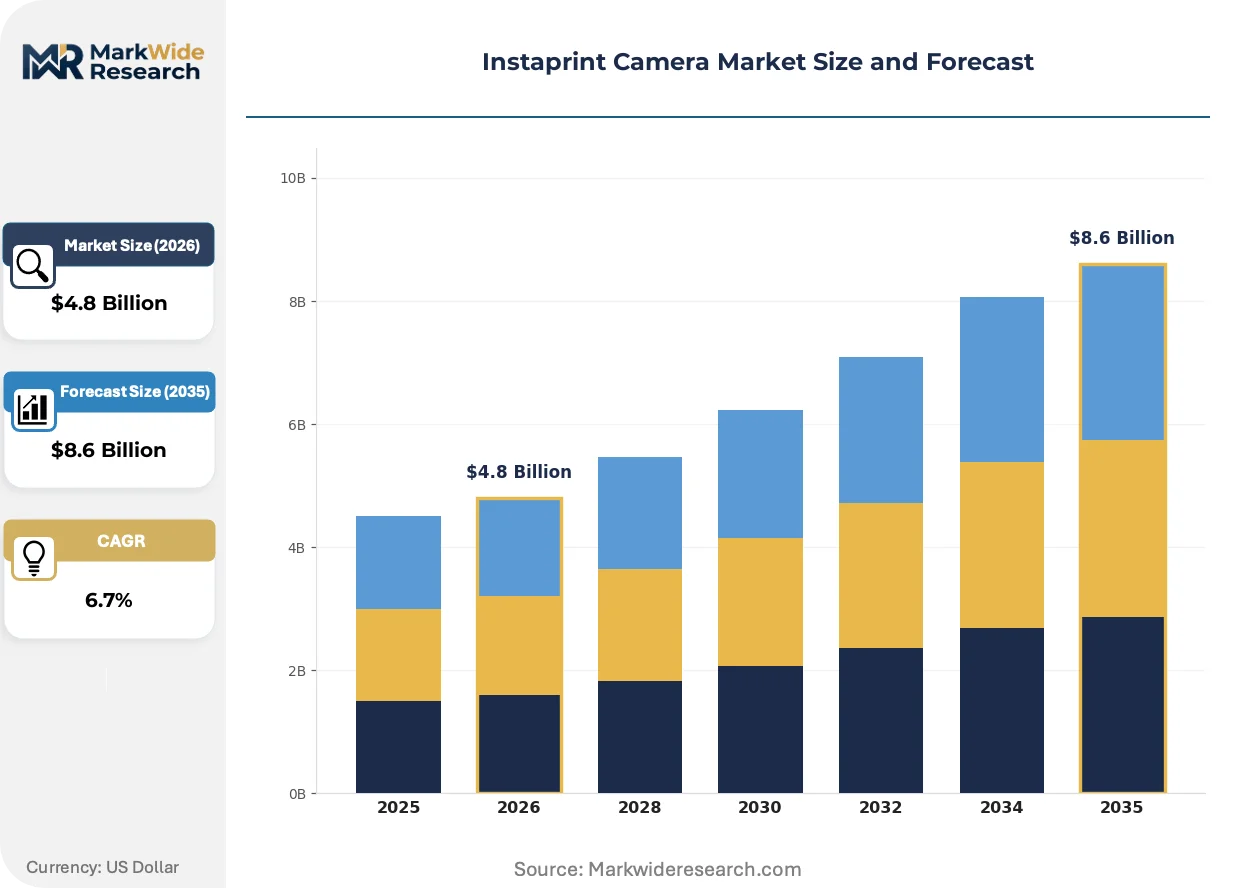
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Film, Instant Digital, Hybrid, Accessories End User: Millennials, Photographers, Retail Consumers, Event Planners Distribution Channel: Online Retail, Specialty Stores, Photography Shops, Mass Merchants Technology: Zink, Thermal, Chemical, Optical |
| Companies Covered | FUJIFILM Holdings Corporation, Polaroid International B.V., Eastman Kodak Company, Canon Inc., Leica Camera AG, MiNT Camera, Lomographische GmbH, HP Inc., RICOH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instaprint Camera Market Shifts & Advancements
Three intersecting developments are compressing product lifecycles and redrawing competitive boundaries: thermal printing architectures are displacing chemical development, regulatory chemistry mandates are forcing substrate reinvention, and rental-service models are fragmenting traditional ownership patterns.
Thermal dye-sublimation engines with embedded color calibration profiles are supplanting traditional silver halide instant film packs in mid-tier consumer segments. Wedding photographers and corporate event agencies are adopting these systems at accelerating rates due to lower per-print costs and elimination of cold-chain storage requirements. This transition is compressing the addressable market for chemical film while expanding margins for hardware vendors through reduced consumable dependency.
EU REACH restrictions on perfluorinated compounds in paper coatings are forcing reformulation of instant film base substrates and adhesive layers. Manufacturers with established testing relationships at ECHA-notified bodies are securing faster authorization pathways for replacement chemistries. Japanese and German suppliers with legacy certification infrastructure are capturing disproportionate share of reformulation-driven procurement cycles.
Corporate procurement teams are unbundling hardware ownership from event service delivery, favoring full-service rental agreements with guaranteed print volumes and on-site technical support. This model is displacing direct equipment sales to hospitality and entertainment venues across the United States and United Kingdom. Event technology integrators in Los Angeles and London are consolidating vendor relationships to secure preferential pricing and priority equipment allocation during peak season windows.
Instaprint Camera Market Segmentation
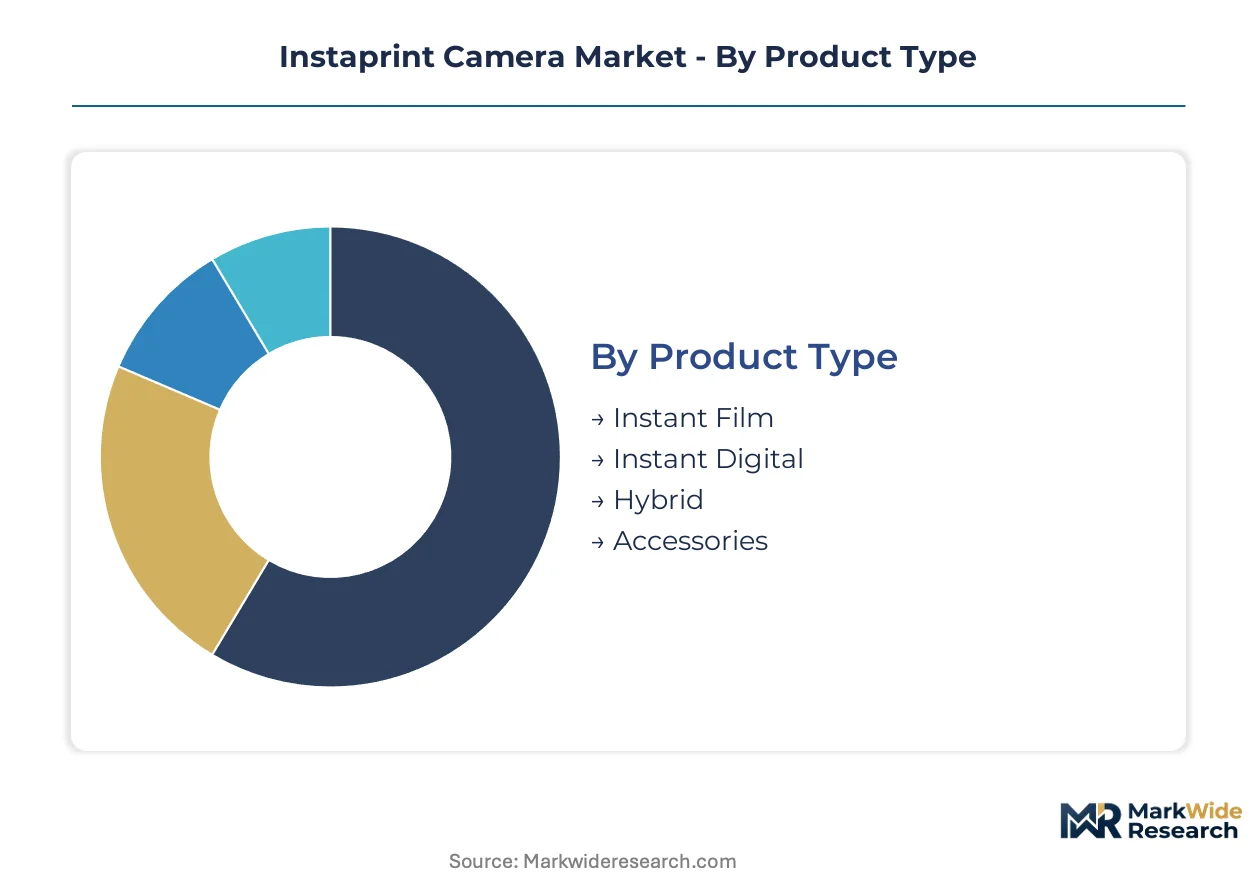
Segmentation in instaprint cameras reveals divergent margin profiles across hardware-versus-consumable business models and distinct channel economics between impulse retail and planned professional procurement. Understanding these splits enables targeted resource allocation for product development and go-to-market investments.
Product Type:
Channel mix varies sharply: instant film dominates specialty retail and photography shops with recurring consumable replenishment, while hybrid models concentrate in online direct-to-consumer and mass merchant channels where bundled digital-physical value propositions resonate.
- Instant Film:Silver halide chemistry embedded in self-contained film packs produces archival-quality prints through controlled chemical diffusion. Wedding photographers in Japan and heritage collectors in Germany sustain premium pricing through brand loyalty and image permanence requirements. By volume, instant film leads. By growth pace, hybrid instant-digital is ahead.
- Instant Digital:Integrated CMOS sensors capture digital files for simultaneous screen review and optional print output, eliminating per-shot cost anxiety. Event planners in Los Angeles and London deploy these for corporate activations where immediate social media upload plus physical takeaway drives client satisfaction metrics. This segment is expanding most quickly as dual-output functionality commands price premiums in experiential marketing budgets.
- Hybrid:Combines optical viewfinder capture with digital storage and instant print output through selectable thermal or Zink engines. Retail consumers in fourth-quarter gifting windows favor these for flexibility across indoor and outdoor shooting conditions.
- Accessories:Carrying cases, album kits, and specialty film borders extend per-customer lifetime value through emotional customization options.
Pricing power concentrates in instant film through proprietary chemistry lock-in, while hybrid architectures capture volume expansion through reduced consumable dependency.
End User:
Cost tier stratification separates professional service providers with equipment depreciation schedules from discretionary purchasers with seasonal spending patterns.
- Event Planners:Corporate and wedding specialists with recurring hardware refresh cycles and bulk consumable contracts. Procurement teams negotiate service-level agreements with guaranteed print volumes and on-site technical support, concentrating demand in Los Angeles, London, and Tokyo metropolitan corridors.
- Photographers:Independent professionals and studio operators selecting equipment based on color accuracy certification and lens compatibility with existing DSLR systems. This segment commands the highest per-unit specification requirements and drives feature roadmap prioritization for manual exposure controls.
- Millennials:Nostalgia-motivated purchasers aged 28-43 seeking tangible outputs from travel and social experiences. Purchase timing clusters around holiday periods and destination wedding attendance.
- Retail Consumers:Gift purchasers and casual users with low brand loyalty and high price elasticity, driving volume through mass merchant promotional cycles.
Event planners generate the highest recurring revenue per account; millennials show the steepest adoption trajectory among consumer cohorts.
Distribution Channel:
Volume concentration follows seasonal retail calendars, while margin retention favors direct channels with subscription attach rates.
- Online Retail:Brand-controlled storefronts and marketplace presence enabling bundling of hardware with consumable subscription programs. TikTok Shop and Instagram Checkout integration bypasses traditional retail margin stacking for manufacturers with direct fulfillment capabilities.
- Specialty Stores:Curated photography retailers in Tokyo's Shinjuku and New York's B&H Photo providing hands-on demonstration and technical consultation. These outlets sustain premium positioning through knowledgeable sales staff and immediate product availability.
- Photography Shops:Independent local operators serving event professionals with rental equipment and emergency consumable resupply during peak wedding season.
- Mass Merchants:Big-box retailers capturing seasonal gifting volume through prominent end-cap placement and promotional pricing during fourth-quarter retail windows.
Mass merchants move the highest unit volumes; online retail channels are climbing fastest through social commerce integration.
Technology:
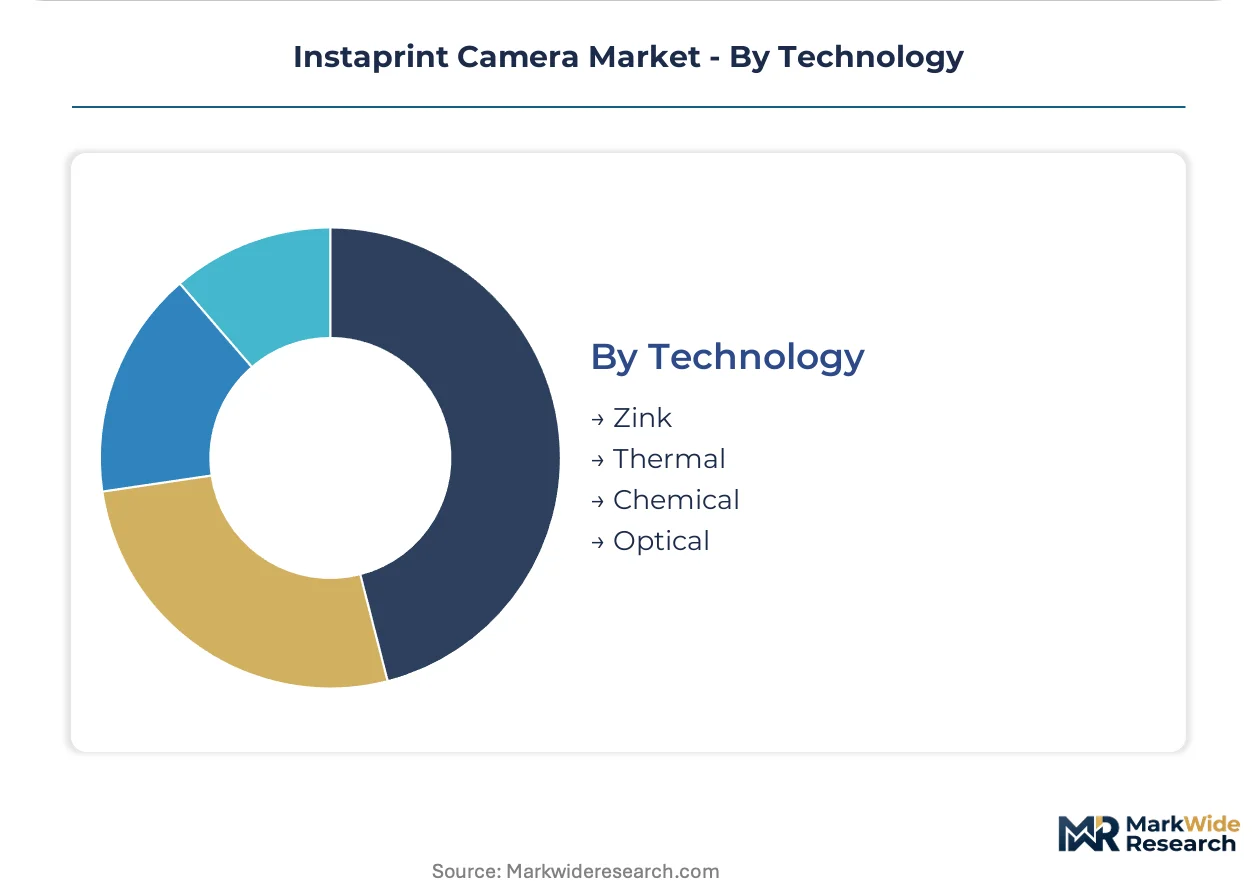
Application requirements dictate technology selection: archival permanence demands chemical development, while field portability favors thermal architectures.
- Thermal:Dye-sublimation engines with embedded color calibration profiles produce smudge-resistant prints without chemical processing. Corporate event agencies adopt these for indoor activations where cold-chain storage elimination reduces logistics complexity.
- Zink:Zero-ink substrates with embedded dye crystals activated by thermal print heads, enabling compact form factors and reduced mechanical complexity. Entry-tier consumer products leverage this for cost-sensitive gifting segments.
- Chemical:Traditional silver halide diffusion transfer chemistry delivering tonal range and permanence standards required by fine art and heritage documentation applications.
- Optical:Lens and viewfinder systems adapted from legacy film camera architectures, sustaining brand differentiation through mechanical refinement and haptic quality.
Thermal technology leads in new product introductions; Zink substrates are gaining share fastest in sub-premium price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's enforcement of JIS battery safety and electromagnetic standards anchors Japan's premium instaprint camera positioning. Regulatory fragmentation across major economies elevates compliance costs while reinforcing incumbent advantages in established certification networks.
United States
Corporate event planners in Los Angeles and New York drive bulk procurement of hybrid instant-digital systems for experiential marketing activations. The EPA regulates chemical waste streams from thermal development processes, constraining service provider operations. Austin and Nashville emerging as secondary hubs for rental-service model deployment at music and technology conferences.
Japan
Heritage collectors and wedding specialists sustain demand for silver halide instant film through brand loyalty and archival permanence requirements. METI enforces JIS standards on electromagnetic compatibility and battery safety for portable electronics. Tokyo's Shinjuku district hosts concentrated specialty retail networks providing technical consultation and immediate product availability.
Germany
Photography enthusiasts and fine art documentarians prioritize tonal range and chemical development quality in procurement decisions. ECHA governs substrate coatings and adhesive compounds under the REACH framework, forcing reformulation timelines. Dresden and Munich manufacturing clusters maintain precision optical component production for premium tier supply.
United Kingdom
Event technology integrators in London consolidate vendor relationships for preferential pricing and priority equipment allocation. RoHS directive compliance on hazardous substance restrictions reshapes component sourcing and ink chemistry formulations. Manchester and Birmingham emerge as rental-service logistics nodes for hospitality sector deployment.
India
The unorganized wedding photography sector presents expansion potential for rental-based instaprint kiosk deployment at mass-market price points. BIS standards govern electronics safety and electromagnetic emissions for imported devices. Mumbai and Delhi-NCR metropolitan corridors concentrate event planner procurement activity and corporate activation budgets.
Instaprint Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale hybrid players occupying intermediate positions. The upper tier commands margin control through captive chemistry and lens manufacturing. Three archetypes define competitive positioning: vertically integrated conglomerates with film heritage, licensed brand operators leveraging nostalgia equity, and precision optical specialists transferring professional camera IP. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing substrate supply agreements and certification relationships.
Among heritage-integrated conglomerates, FUJIFILM Holdings Corporation exemplifies backward integration across film chemistry and lens manufacturing. Polaroid International B.V. occupies a position within the licensed brand operator archetype, anchoring nostalgia-driven direct-to-consumer channels. Canon Inc. represents the precision optical specialist tier, with sensor miniaturization capabilities drawn from professional camera divisions.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Polaroid International B.V. |
| Eastman Kodak Company |
| Canon Inc. |
| Leica Camera AG |
| MiNT Camera |
| Lomographische GmbH |
| HP Inc. |
| RICOH |
| Others |
Supply & Pricing Matrix
EU REACH compliance on perfluorinated compounds gates both substrate supplier qualification and premium tier pricing power simultaneously. Manufacturers with ECHA-notified body relationships command price premiums while uncertified competitors face margin compression from reformulation delays.
Pricing Analysis
Long-term offtake contracts dominate professional procurement, with event planners securing volume-locked pricing for consumables across multi-year service agreements. Three-tier pricing structure across premium, standard, and economy levels separates archival silver halide systems from thermal dye-sublimation mid-tier and Zink-based entry products. Cost compression in the economy tier is intensifying because proprietary substrate suppliers limit qualified competition. Retail consumers show highest price sensitivity, while wedding photographers demonstrate lowest elasticity due to permanence requirements.
Supply Chain Analysis
Japan and Germany anchor precision optical component production, with Dresden and Tokyo manufacturing clusters feeding lens assemblies to premium tier assemblers. Silver halide chemistry draws from a narrowing base of specialty chemical processors in Belgium and Japan. Single-source vulnerability in dye-crystal embedding substrates for Zink paper creates chokepoint exposure. Distribution runs through specialty retail networks in metropolitan corridors and direct-to-consumer channels with subscription attach programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from smartphone substitution troughs as experiential marketing budgets cyclically expand. Event photography's return to in-person formats drives hardware refresh demand.
For Market Incumbents: Shield proprietary chemistry positions through accelerated ECHA pre-registration for reformulated substrates before competitor authorization windows close. Deepen backward integration into lens grinding capacity in Japanese manufacturing clusters to defend against precision optical specialists entering from professional camera divisions. Lock event planner accounts with guaranteed print volume service agreements that raise switching costs.
For New Entrants and Emerging Players: Anchor in India's unorganized wedding photography sector through rental kiosk deployment at mass-market price points below heritage brand positioning. Target corporate event agencies in Austin and Nashville secondary hubs where vendor consolidation has not yet concentrated. Pursue social commerce direct fulfillment partnerships that bypass traditional retail margin stacking.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with licensed brand operators lacking captive chemistry infrastructure. Long-term viability favors targets with dual thermal-chemical technology portfolios spanning archival and convenience use cases. Watch ECHA authorization timelines for perfluorinated compound replacements as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Chemistry Reformulation | ECHA pre-registration accelerates market access ahead of REACH enforcement deadlines. |
| Specialty Retail Network Expansion | Tokyo Shinjuku and New York B&H Photo clusters sustain premium positioning through demonstration. |
| Direct-to-Consumer Subscription Launch | TikTok Shop integration bypasses mass merchant margin extraction for consumable replenishment. |
| Event Technology Integrator Partnership | London and Los Angeles consolidators secure priority equipment allocation during peak seasons. |
| Thermal Engine Platform Standardization | Dye-sublimation architecture displacement of silver halide reduces cold-chain logistics burden. |
Research Methodology
Cross-validation between executive interviews and customs trade data anchors the qualitative findings in observable procurement patterns. Primary fieldwork engaged product managers at heritage camera manufacturers, event technology integrators in Los Angeles and London, specialty retail buyers in Tokyo's Shinjuku district, and procurement leads at corporate event agencies. Secondary sources included METI electromagnetic compliance filings, ECHA substance authorization databases, EPA chemical waste stream reports, and SEC 10-K disclosures from listed optical equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down experiential marketing budget allocations.
Sensitivity analysis tested forecast outputs against alternative scenarios for silver halide supply concentration and smartphone substitution rates across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement pattern, distribution channel format, and technology type. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in adjacent imaging hardware categories. Industry-specific inputs incorporated wedding industry seasonality patterns and fourth-quarter retail gifting concentration.
Decision-makers should treat outputs as directional under sustained experiential marketing budget expansion; material deviation would warrant model refresh. Specific risk factors include accelerated REACH restriction timelines, silver compound price volatility, and rental-service model displacement of equipment ownership. Recalibration cycles align with material shifts in regulatory authorization timelines and event industry procurement consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Industrial Camera Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Digital X-Ray Technology Market
Imaging
Global in Ceiling Camera Market
Imaging
Thermal Imaging Systems Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Global 3D Camera Market
Imaging
Global Digital Photo Frame Market
Imaging
Computer Aided Detection Market
Imaging
Chemiluminescence Imaging Market
Imaging
Global Microbolometer Market
Imaging
Photoconductor Drums Market
Imaging
SWIR Camera Market
Imaging
Global Automotive Imaging Market
Imaging
Hyperspectral Cameras Market
Imaging
Global Acoustic Cameras Market