
 Piezoelectric MEMS Resonators Market | 2026-2036
Piezoelectric MEMS Resonators Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric MEMS Resonators Market Outlook
Modular packaging of resonator arrays with integrated oscillator circuits is restructuring procurement patterns for telecom infrastructure buyers. Bosch leverages in-house MEMS fabrication to sustain captive supply chains for automotive timing modules. STMicroelectronics anchors European demand through specialized production of temperature-compensated resonators for industrial IoT gateways. SiTime Corporation competes aggressively in programmable MEMS oscillators, differentiating via software-configurable frequency outputs that reduce SKU proliferation for OEM customers.
Piezoelectric MEMS resonators are micro-electromechanical structures that exploit the inverse piezoelectric effect in thin-film aluminum nitride or scandium-doped aluminum nitride layers, typically vibrating at frequencies from 1 MHz to several GHz with quality factors exceeding 10,000. These devices replace quartz crystals in applications requiring compact footprint, shock immunity, and compatibility with semiconductor batch fabrication. Bulk acoustic wave technology dominates volume production due to established foundry infrastructure, while surface acoustic wave variants capture premium positioning in filter-bank applications where electromechanical coupling coefficient governs insertion loss performance. Multi-mode resonators represent the fastest-expanding product category as 5G carrier aggregation architectures demand simultaneous excitation of multiple vibration modes within single die footprints.
FCC Part 15 emissions standards and NHTSA functional safety requirements shape product qualification pathways for automotive and wireless deployments in the United States. ETSI EN 303 413 and CE marking directives govern mmWave equipment certification across European telecom supply chains, constraining frequency tolerance specifications that resonator vendors must meet. FDA electromagnetic compatibility standards for implantable medical devices create additional compliance layers for manufacturers serving cardiac monitoring and neuromodulation applications. Stakeholders must monitor evolving spectrum allocation decisions and material restriction lists to anticipate which resonator architectures will secure design wins in next-generation connected systems.
Market Dynamics
5G carrier aggregation architectures and mmWave spectrum deployment are forcing resonator manufacturers to engineer multi-mode vibration structures that fit within shrinking RF front-end footprints while maintaining frequency stability under thermal stress.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbons is accelerating manufacturer migration toward lead-free piezoelectric formulations and alternative dopant chemistries in thin-film deposition processes.
- Automotive timing modules:NHTSA functional safety requirements for autonomous driving systems are mandating MEMS-based timing redundancy in sensor fusion architectures, displacing legacy quartz in safety-critical signal chains.
- Scandium-doped aluminum nitride:Enhanced electromechanical coupling coefficients in doped AlN films are enabling filter-bank miniaturization for sub-6 GHz 5G architectures without sacrificing insertion loss performance.
Market Restraints
- Foundry concentration in South Korea:Samsung and SK Hynix captive integration of MEMS resonators into RF modules limits merchant market access and creates supply bottlenecks for second-tier OEMs.
- High-purity precursor costs:Trimethylaluminum and ammonia feedstock price volatility compresses gross margins for aluminum nitride deposition specialists operating at sub-scale volumes.
- Quartz crystal substitution resilience:Established quartz oscillator supply chains in Japanese and Taiwanese manufacturing clusters retain cost advantages in sub-50 MHz applications where size constraints are less severe.
Strategic Opportunities
- Industrial IoT gateways:Temperature-compensated resonator demand from European factory automation deployments is outpacing supply from specialized European foundries, creating white space for qualified entrants.
- Programmable frequency outputs:Software-configurable MEMS oscillators reduce SKU proliferation for smartphone OEMs managing multiple carrier band configurations across regional variants.
- Cardiac monitoring devices:FDA electromagnetic compatibility standards for implantable neuromodulation systems are opening qualified supplier positions for hermetically packaged resonator modules.
Industry Challenges
- Piezoelectric thin-film process engineers:Scarcity of specialists trained in sputter deposition of c-axis oriented aluminum nitride constrains foundry expansion timelines.
- Multi-mode resonator design verification:Simultaneous excitation of multiple vibration modes requires finite element modeling expertise that resides in a handful of academic and corporate research labs.
- REACH compliance documentation:Supply chain reconfiguration to eliminate lead-based piezoelectric materials demands extensive substance testing and regulatory filing timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric MEMS Resonators Market |
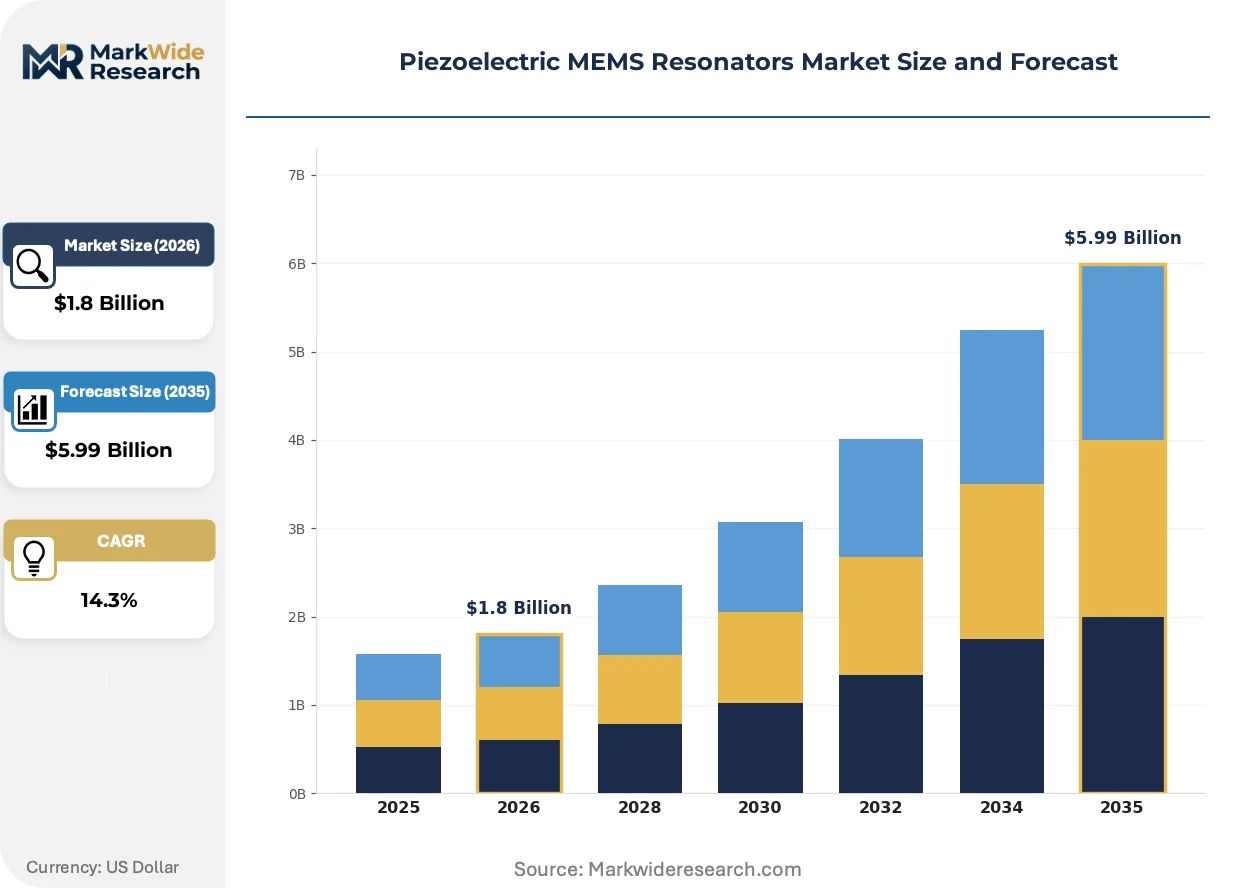
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Phase Resonators, Out-of-Phase Resonators, Multi-Mode Resonators, Frequency Selective Resonators Application: Telecommunications, Consumer Electronics, Automotive Electronics, Medical Devices Technology: Bulk Acoustic Wave, Surface Acoustic Wave, Quartz, Ceramic End User: Telecom Providers, OEMs, Research Institutions, Aerospace Manufacturers |
| Companies Covered | Bosch, STMicroelectronics, ROHM, SiTime Corporation, Murata Manufacturing, Teledyne DALSA, Qorvo, Realmagicsemi, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric MEMS Resonators Market Strategic Shifts
Thin-film bulk acoustic wave technology is absorbing capital and engineering talent from surface acoustic wave development programs as RF filter architectures consolidate around higher-frequency operation.
Scandium-doped aluminum nitride is absorbing research investment from defense and telecommunications contractors seeking enhanced coupling coefficients for mmWave filter applications. Smartphone OEMs in South Korea and the United States are qualifying scandium-doped resonator designs for 2024-2025 flagship releases. The material shift is absorbing development resources from legacy undoped AlN process optimization, consolidating supplier differentiation around doping concentration control.
REACH substance restrictions and the EU F-Gas Regulation are tightening material compliance frameworks for piezoelectric ceramics and thin-film precursors. Manufacturers must reformulate lead-free compositions and document alternative dopant safety profiles across extended supply chains. European industrial IoT and automotive timing segments are responding by consolidating procurement around suppliers with pre-certified material libraries.
Telecom infrastructure buyers are consolidating oscillator procurement around vendors offering software-configurable frequency outputs with integrated temperature compensation. Direct RF module integration by South Korean semiconductor foundries is compressing the merchant resonator market for discrete components. The procurement consolidation is most visible in 5G base station deployments across Germany, Japan, and the United States, where carrier aggregation complexity favors programmable timing solutions over fixed-frequency quartz alternatives.
Piezoelectric MEMS Resonators Market Segmentation
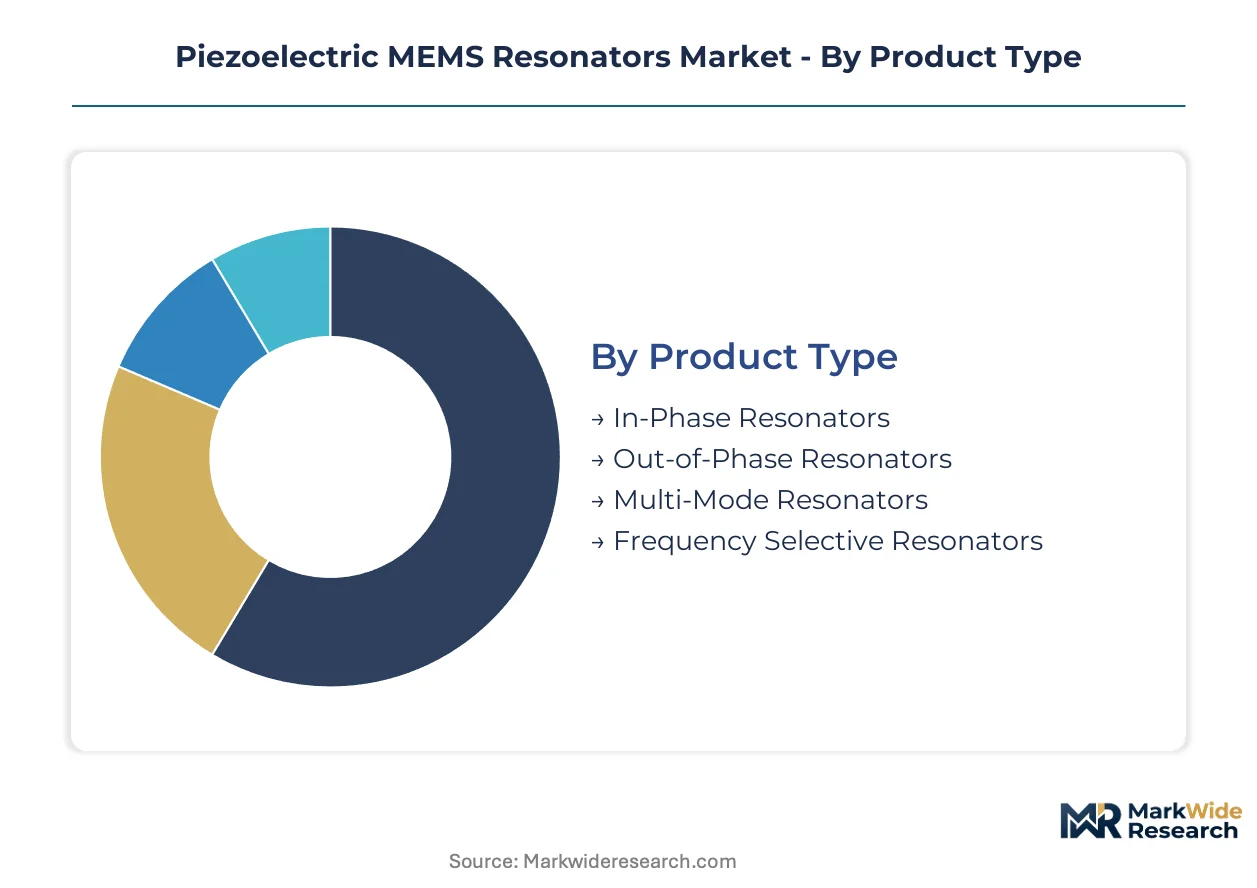
Piezoelectric MEMS resonators serve divergent integration depths across the electronics stack. Standalone timing modules demand precision packaging, while embedded RF front-end integration prioritizes footprint miniaturization and thermal co-design.
Product Type:
Integration depth varies sharply—some variants ship as discrete components, others embed directly into system-in-package architectures.
- Multi-Mode Resonators:These structures excite simultaneous vibration modes within single die footprints, enabling 5G carrier aggregation without multiplying component count. South Korean smartphone OEMs specify these for sub-6 GHz and mmWave architectures where board space constraints are severe. NHTSA functional safety requirements for autonomous driving sensor fusion are accelerating automotive qualification timelines.
- In-Phase Resonators:Operating with synchronized mechanical displacement across resonant elements, these devices deliver phase-coherent outputs for precision clock distribution. Telecom infrastructure deployments in Germany and Japan favor in-phase arrays for base station synchronization where phase noise specifications are tight. FCC Part 15 emissions standards constrain spurious output levels in US wireless applications.
- Out-of-Phase Resonators:Antiphase vibration modes cancel common-mode thermal drift in differential oscillator circuits.
- Frequency Selective Resonators:Sharp resonance profiles enable filter-bank applications with minimal insertion loss penalty.
Volume placements concentrate in Multi-Mode Resonators; the faster expansion belongs to Frequency Selective Resonators.
Application:
Cost tier stratification separates premium-certified segments from price-sensitive consumer volumes.
- Telecommunications:5G infrastructure and smartphone RF modules absorb the highest unit volumes. mmWave spectrum deployment and carrier aggregation complexity are forcing resonator vendors toward programmable architectures with software-configurable outputs. ETSI EN 303 413 certification requirements in European telecom supply chains constrain frequency tolerance specifications.
- Consumer Electronics:Wearables and IoT edge devices prioritize footprint reduction over absolute stability. South Korean foundry integration of MEMS resonators into RF modules compresses merchant market access for discrete component suppliers. REACH compliance documentation for lead-free materials extends procurement lead times.
- Automotive Electronics:Safety-critical timing redundancy in sensor fusion architectures displaces legacy quartz.
- Medical Devices:FDA electromagnetic compatibility standards for implantable cardiac monitoring and neuromodulation systems create qualified supplier positions.
Revenue concentration sits with Telecommunications; Medical Devices are climbing the fastest.
Technology:
Maturity gradients separate established foundry processes from emerging material platforms.
- Bulk Acoustic Wave:Thin-film aluminum nitride and scandium-doped variants dominate volume production through established semiconductor batch fabrication. The technology captures smartphone timing and RF filter applications where quality factors exceeding 10,000 are required. EU F-Gas Regulation phasedown is accelerating migration toward lead-free piezoelectric formulations.
- Surface Acoustic Wave:Interdigital transducer architectures retain premium positioning in filter-bank applications where electromechanical coupling coefficient governs insertion loss. Defense and telecommunications contractors are absorbing research investment for mmWave filter development. Process engineers trained in sputter deposition of c-axis oriented films remain scarce.
- Quartz:Established Japanese and Taiwanese manufacturing clusters retain cost advantages in sub-50 MHz applications.
- Ceramic:Thick-film formulations serve industrial IoT gateways with relaxed stability requirements.
Foundry output concentrates in Bulk Acoustic Wave; scandium-doped material variants are gaining share fastest.
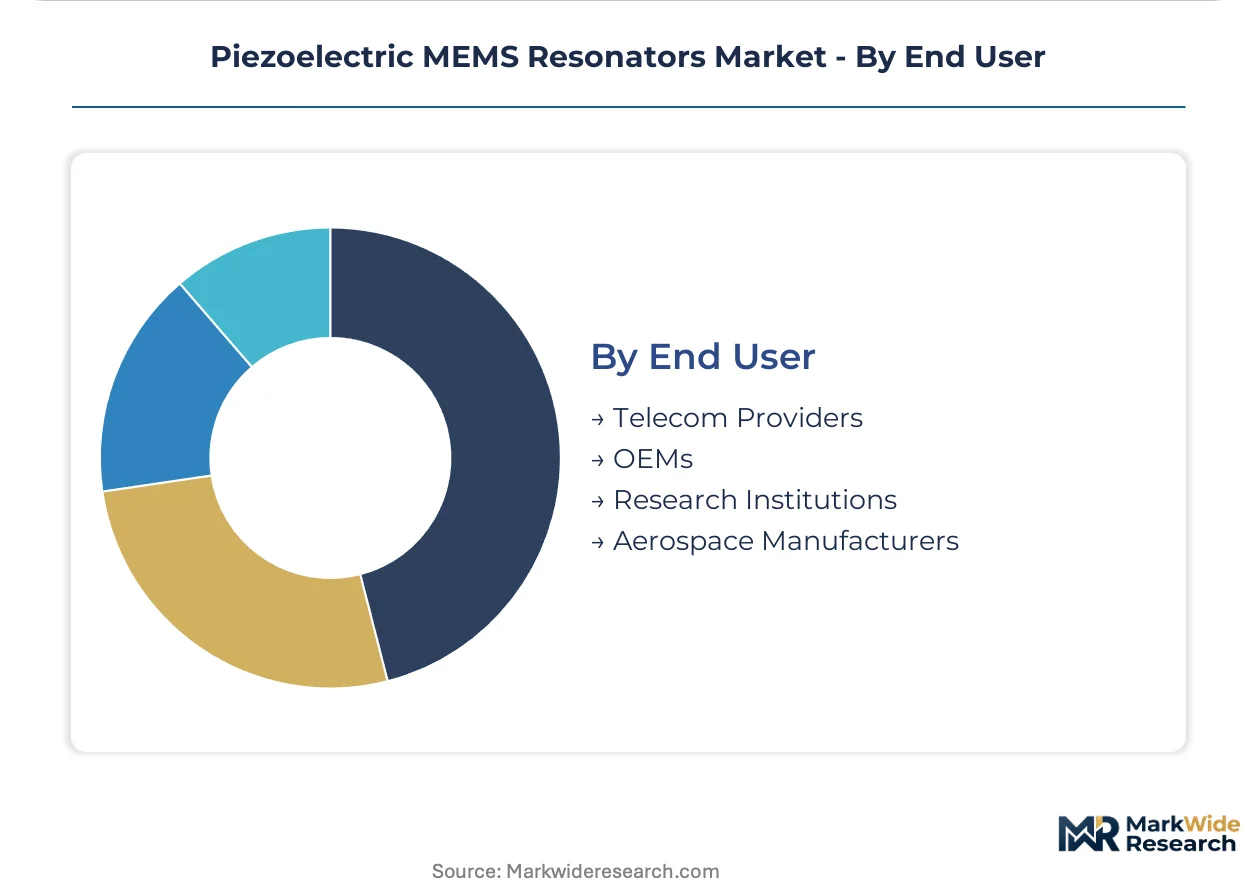
End User:
Customer type determines specification stringency and contract structure—captive integration versus merchant supply.
- OEMs:Smartphone and automotive manufacturers drive specification evolution through direct foundry partnerships. Samsung and SK Hynix captive integration of MEMS resonators into RF front-end modules limits merchant market access. Software-configurable frequency outputs reduce SKU proliferation across regional carrier band variants.
- Telecom Providers:Infrastructure operators consolidate oscillator procurement around vendors offering integrated temperature compensation. Carrier aggregation complexity in 5G base station deployments across Germany, Japan, and the United States favors programmable timing solutions. ETSI EN 303 413 and FCC Part 15 standards shape qualification pathways.
- Research Institutions:Finite element modeling expertise for multi-mode resonator design verification resides in limited academic and corporate labs.
- Aerospace Manufacturers:Hermetic packaging requirements for high-reliability applications extend development cycles.
Contract volume concentrates with OEMs; Research Institutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Korean semiconductor fabs, while consumption spreads across German automotive clusters, US telecom infrastructure, and Japanese precision timing markets. This geographic split shapes trade flows and captive supply strategies.
United States
FCC Part 15 emissions standards and NHTSA functional safety requirements drive qualification complexity for automotive and wireless deployments. The IRA clean energy incentives indirectly support domestic semiconductor fabrication investments. Silicon Valley and Austin host design centers where fabless resonator companies prototype multi-mode architectures.
Germany
ETSI EN 303 413 certification requirements constrain frequency tolerance specifications for mmWave equipment in European telecom supply chains. The EU F-Gas Regulation accelerates manufacturer migration toward lead-free piezoelectric formulations. Stuttgart and Munich anchor automotive timing module demand from Bosch and Continental sensor fusion programs.
South Korea
Samsung and SK Hynix fabs integrate MEMS resonators directly into RF front-end modules, limiting merchant market access for discrete component suppliers. MFDS medical device standards create parallel compliance pathways for implantable applications. Seoul Capital Area concentration produces supply bottlenecks for second-tier OEMs seeking alternative sources.
Japan
METI industrial standards and JIS certification frameworks govern precision timing specifications for factory automation and telecommunications. Established quartz oscillator supply chains in Tokyo-Osaka manufacturing clusters retain cost advantages in sub-50 MHz applications. Murata Manufacturing anchors domestic bulk acoustic wave production for smartphone filter banks.
China
MIIT spectrum allocation decisions shape mmWave resonator design requirements for domestic 5G base station deployments. GB standards and dual carbon goals pressure manufacturers toward alternative dopant chemistries in thin-film deposition. Yangtze River Delta fabs absorb capital for aluminum nitride sputtering capacity expansion.
Piezoelectric MEMS Resonators Market Competitive Environment
The competitive structure tilts toward vertically integrated semiconductor conglomerates with captive MEMS fabrication capabilities. Bosch and STMicroelectronics sustain in-house production of automotive timing modules, compressing opportunities for merchant foundries. Three archetypes dominate: diversified industrial conglomerates with MEMS divisions, specialized fabless resonator designers, and RF front-end integrators absorbing resonators into system-in-package architectures. Capacity expansion and strategic partnerships represent the primary competitive moves, with foundry slot allocation becoming a critical bottleneck.
Among diversified European-based semiconductor manufacturers, STMicroelectronics occupies a position exemplifying temperature-compensated resonator specialization for industrial IoT gateways. Bosch represents the captive supply archetype through in-house MEMS fabrication serving automotive timing redundancy requirements. SiTime Corporation sits within the fabless programmable oscillator tier, differentiating via software-configurable frequency outputs that reduce SKU proliferation for smartphone OEMs managing multiple carrier band configurations.
| Leading Market Players |
|---|
| Bosch |
| STMicroelectronics |
| ROHM |
| SiTime Corporation |
| Murata Manufacturing |
| Teledyne DALSA |
| Qorvo |
| Realmagicsemi |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Telecom infrastructure procurement consolidation around programmable timing solutions is forcing resonator vendors to absorb R&D costs for software-configurable architectures, compressing margins on fixed-frequency products while elevating pricing power for qualified multi-mode suppliers. EU F-Gas Regulation compliance timelines and REACH substance documentation requirements extend product qualification cycles, embedding regulatory cost premiums into lead-free piezoelectric formulations.
Pricing Analysis
Margin tightening in standard-grade resonators traces to foundry slot competition from South Korean smartphone OEMs captive-integrating MEMS into RF modules. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-tier resonators separates NHTSA-certified safety modules from temperature-compensated IoT gateways and price-sensitive wearables. Pricing pressure intensifies in sub-50 MHz segments as Japanese and Taiwanese quartz supply chains retain cost advantages where size constraints relax. Medical device OEMs show least price sensitivity given FDA electromagnetic compatibility certification barriers.
Supply Chain Analysis
Returns and refurbishment flows for hermetically packaged automotive timing modules remain minimal given NHTSA functional safety prohibitions on component reuse in sensor fusion architectures. Supply concentrates in South Korea, Japan, and Germany, with Samsung and SK Hynix fabs, Murata Manufacturing clusters, and Bosch captive operations anchoring geographic output. Aluminum nitride sputtering capacity draws from trimethylaluminum and ammonia feedstock streams vulnerable to precursor price volatility. Single-source vulnerability sits with scandium-doped AlN deposition specialists trained in c-axis orientation control. Distribution runs through RF front-end module integrators and direct telecom infrastructure procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry slot allocation bottlenecks for piezoelectric thin-film deposition are propping pricing premiums for qualified suppliers, creating a supply-constrained market structure favoring incumbents with captive capacity or pre-certified material libraries.
For Market Incumbents: Anchor automotive timing module positions through backward integration into aluminum nitride sputtering capacity and NHTSA functional safety certification maintenance. Defend against quartz substitution resilience in sub-50 MHz industrial applications by accelerating temperature-compensated resonator cost reduction programs. Prioritize scandium-doped AlN process yield improvement to sustain filter-bank margin premiums against undoped AlN commoditization. For New Entrants and Emerging Players: Begin with industrial IoT gateway supply gaps in European factory automation deployments, where temperature-compensated resonator demand outstrips specialized foundry output. Target cardiac monitoring and neuromodulation device segments where FDA electromagnetic compatibility standards create qualified supplier vacancies. Pursue fabless programmable oscillator architectures with software-configurable frequency outputs to bypass South Korean captive integration barriers. For Investors and Strategic Acquirers: Re-rating potential sits with fabless resonator designers possessing finite element modeling expertise for multi-mode vibration structures, given 5G carrier aggregation complexity and academic lab concentration of design verification talent. Long-term viability hinges on material compliance pre-positioning for REACH substance restrictions and EU F-Gas Regulation phasedown timelines. Monitor scandium-doped AlN qualification decisions at South Korean smartphone OEMs as inflection signals for doped versus undoped material platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Scandium-Doped AlN Process Scale-Up | Enhanced electromechanical coupling coefficients enable mmWave filter miniaturization for sub-6 GHz 5G architectures. |
| Lead-Free Piezoelectric Material Transition | REACH and EU F-Gas Regulation compliance secures European automotive and industrial IoT procurement access. |
| Programmable MEMS Oscillator Development | Software-configurable frequency outputs reduce SKU proliferation for smartphone OEMs managing regional carrier variants. |
| Temperature-Compensated Resonator Specialization | Industrial IoT gateway demand from German factory automation clusters outpaces European foundry supply. |
| Hermetic Packaging Capability Investment | FDA electromagnetic compatibility standards for implantable medical devices create qualified supplier positions. |
Study Parameters
Multi-period observation of resonator foundry capacity utilization, precursor feedstock pricing, and smartphone OEM design qualification timelines anchored the trend analysis, supplemented by interviews with piezoelectric thin-film process engineers, RF front-end module procurement managers, automotive timing system architects, and medical device regulatory affairs specialists. Primary fieldwork drew from SEC 10-K filings of MEMS component suppliers, ETSI EN 303 413 certification databases, FDA 510(k) premarket notification records, and EU REACH substance restriction updates. Bottom-up unit shipment estimates across product categories triangulated against top-down semiconductor capital equipment spending patterns.
Input-output matrices mapping aluminum nitride deposition capacity to downstream application demand across telecommunications, automotive electronics, consumer devices, and medical equipment generated volume and value trajectories over the projection horizon. Segmentation dimensions encompassed resonator product type, integration depth, technology platform, and end-user category. CAGRs derived from fitted growth curves incorporating foundry expansion timelines, regulatory compliance phase-in schedules, and substitution elasticity estimates for quartz versus MEMS timing architectures.
Underlying measurement precision varies by segment; automotive-qualified and medical-device-certified resonators carry tighter precision than consumer-grade volumes given NHTSA and FDA documentation requirements. Forecasts embed assumptions regarding scandium-doped AlN yield maturation and EU F-Gas Regulation enforcement intensity that could shift materially. Practitioners should monitor South Korean smartphone OEM design win announcements and REACH substance restriction list revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Barometer Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Digestible Sensors Market