
 Thailand Data Center Processor Market | 2026-2036
Thailand Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Processor Market Insights
Thai cloud service provider demand is consolidating as the dominant end-use vertical, displacing traditional enterprise on-premises procurement. Intel Corporation leverages its established foundry partnerships to sustain supply continuity across Southeast Asian distribution channels. NVIDIA Corporation anchors the GPU acceleration segment through deep engagement with Thai AI and machine learning deployments. Advanced Micro Devices Inc. competes aggressively on price-performance metrics for general-purpose server workloads.
Data center processors are integrated circuits engineered to execute computational workloads in centralized server facilities, typically fabricated on advanced process nodes below seven nanometers with thermal design power ratings exceeding 150 watts for high-performance variants. Their primary commercial purpose is enabling scalable transaction processing, virtualization, and artificial intelligence training or inference across clustered server architectures. CPU deployments retain the largest installed base among processor types, though GPU segments command premium pricing for parallel compute-intensive applications. Cloud service providers represent the fastest-growing end user category as hyperscale operators expand Bangkok-region capacity. Hybrid deployment models are gaining traction where enterprises retain sensitive workloads locally while bursting peak demand to colocation facilities.
Thailand's Board of Investment coordinates digital infrastructure incentives alongside the National Broadcasting and Telecommunications Commission, which governs telecommunications-linked data center certifications. These frameworks shape processor procurement by mandating local content thresholds and energy efficiency standards for qualifying investments. Stakeholders must monitor evolving power allocation policies and carbon disclosure requirements that will determine viable deployment locations and processor selection criteria.
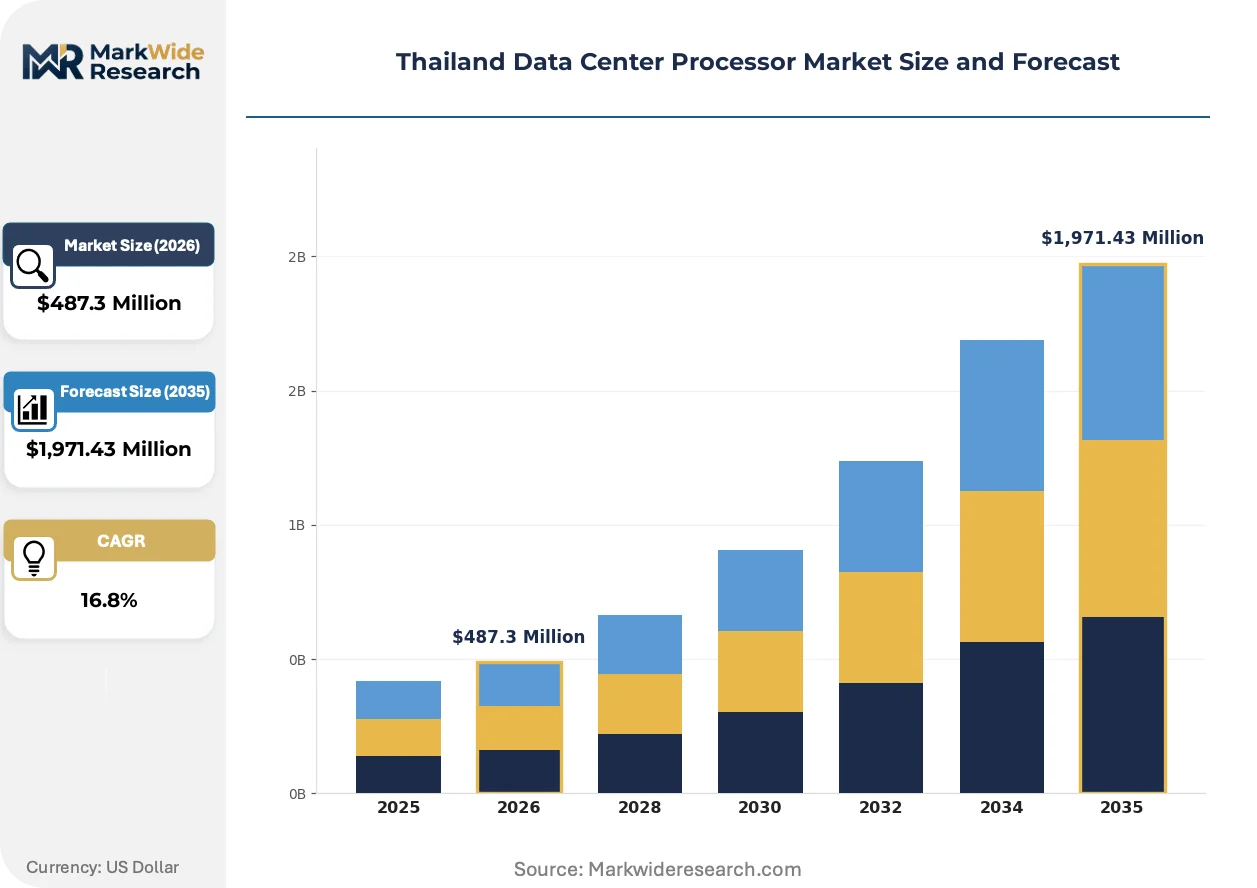
Market Dynamics
Thailand's data center processor market is being reshaped by the Board of Investment's digital infrastructure incentives, which are accelerating hyperscale facility construction in Bangkok and the Eastern Economic Corridor while mandating local content thresholds and energy efficiency standards for qualifying investments.
Growth Catalysts
- BOI Incentive Framework:Thailand's Board of Investment offers tax holidays and duty exemptions for digital infrastructure projects, directly stimulating processor procurement for qualifying data center investments.
- AI Inference Workload Expansion:Cloud service providers are deploying GPU-intensive architectures to serve Thai enterprise demand for machine learning inference at the edge.
- Eastern Economic Corridor Concentration:Chonburi and Rayong provinces are attracting clustered high-performance compute deployments through coordinated land allocation and power grid upgrades.
Market Restraints
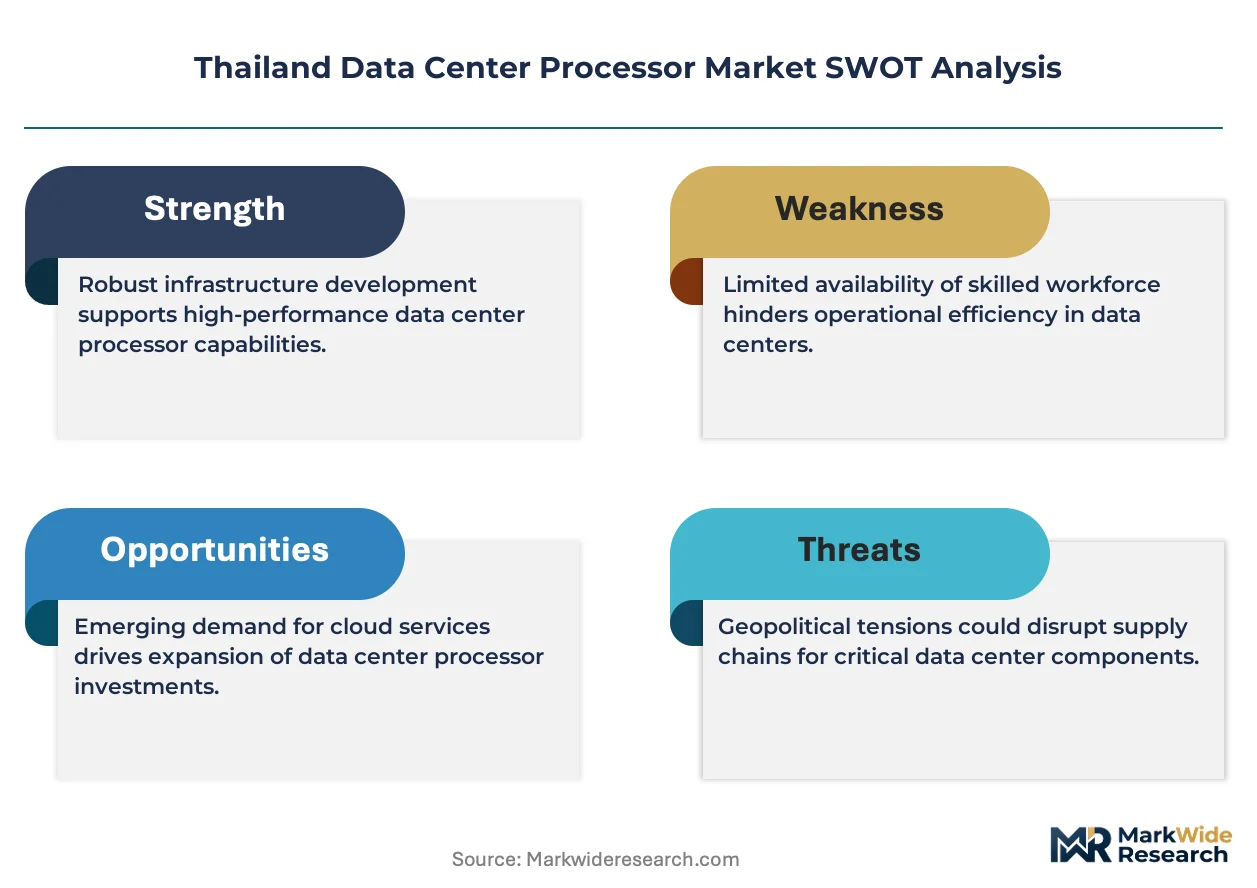
- Advanced Node Supply Concentration:Fabrication capacity for sub-7nm processors remains concentrated among Taiwanese and Korean foundries, creating geographic supply risk for Thai deployments.
- Power Infrastructure Bottlenecks:Provincial power allocation policies in Thailand limit viable deployment locations for high thermal design power processors exceeding 150 watts.
- Carbon Disclosure Compliance Costs:Emerging carbon reporting requirements under Thailand's climate commitments are adding certification overhead to processor selection criteria.
Strategic Opportunities
- Chiang Mai Secondary Hub Development:Northern Thailand's cooler climate offers natural cooling advantages for sustainable data center expansion outside Bangkok's saturated market.
- Hybrid Cloud Integration Services:Local system integrators can capture value by architecting workload orchestration between on-premises Thai enterprise servers and colocation burst capacity.
- Chips-to-Cloud Incentive Alignment:Thailand's coordinated BOI and NBTC frameworks create regulatory tailwinds for vertically integrated digital infrastructure investments.
Industry Challenges
- Specialized Thermal Engineering Talent Gap:Thai universities produce insufficient graduates in advanced liquid cooling and power distribution design for next-generation processor deployments.
- Legacy Enterprise Integration Complexity:Domestic banks and manufacturers face extended migration timelines when retrofitting existing server farms for heterogeneous CPU-GPU architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Processor Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,971.43 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: FPGA, ASIC, CPU, GPU End User: Telecommunications, Cloud Service Providers, Large Enterprises, SMEs Deployment Model: On-Premises, Managed, Hybrid, Colocation Processing Power: 64-bit, Multi-Core, High-Performance, Low-Power |
| Companies Covered | Intel Corporation, Advanced Micro Devices Inc., NVIDIA Corporation, IBM Corporation, Arm Ltd., Ampere Computing, Huawei Technologies, Qualcomm Incorporated, MediaTek Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Processor Market Trends and Innovations
Processor architectures serving Thai data centers are undergoing fundamental redesign as artificial intelligence workloads reshape compute requirements and regulatory pressure intensifies around energy consumption transparency.
Arm-based server processors are overtaking x86 dominance in Thai cloud deployments focused on inference efficiency. Hyperscale operators in Bangkok are adopting Neoverse-derived chips for power-constrained facilities. This architecture is overtaking legacy Intel and AMD sockets in new-build capacity, compressing the addressable market for general-purpose CPUs in AI-optimized racks.
Thailand's Board of Investment has tightened energy efficiency certification requirements for data center tax incentive eligibility. Facilities must now demonstrate power usage effectiveness ratios below industry baselines to qualify for extended holidays. Thai operators are responding by specifying processors with dedicated power management silicon and dynamic voltage-frequency scaling capabilities.
Thai enterprise buyers are consolidating vendor relationships around full-stack solution providers rather than component distributors. Domestic manufacturers and financial institutions now expect firmware optimization, local spare pooling, and Thai-language technical support bundled with processor procurement. This behavior is most visible among mid-market enterprises in the Eastern Economic Corridor transitioning from self-managed server rooms to managed colocation services.
Thailand Data Center Processor Market Segmentation
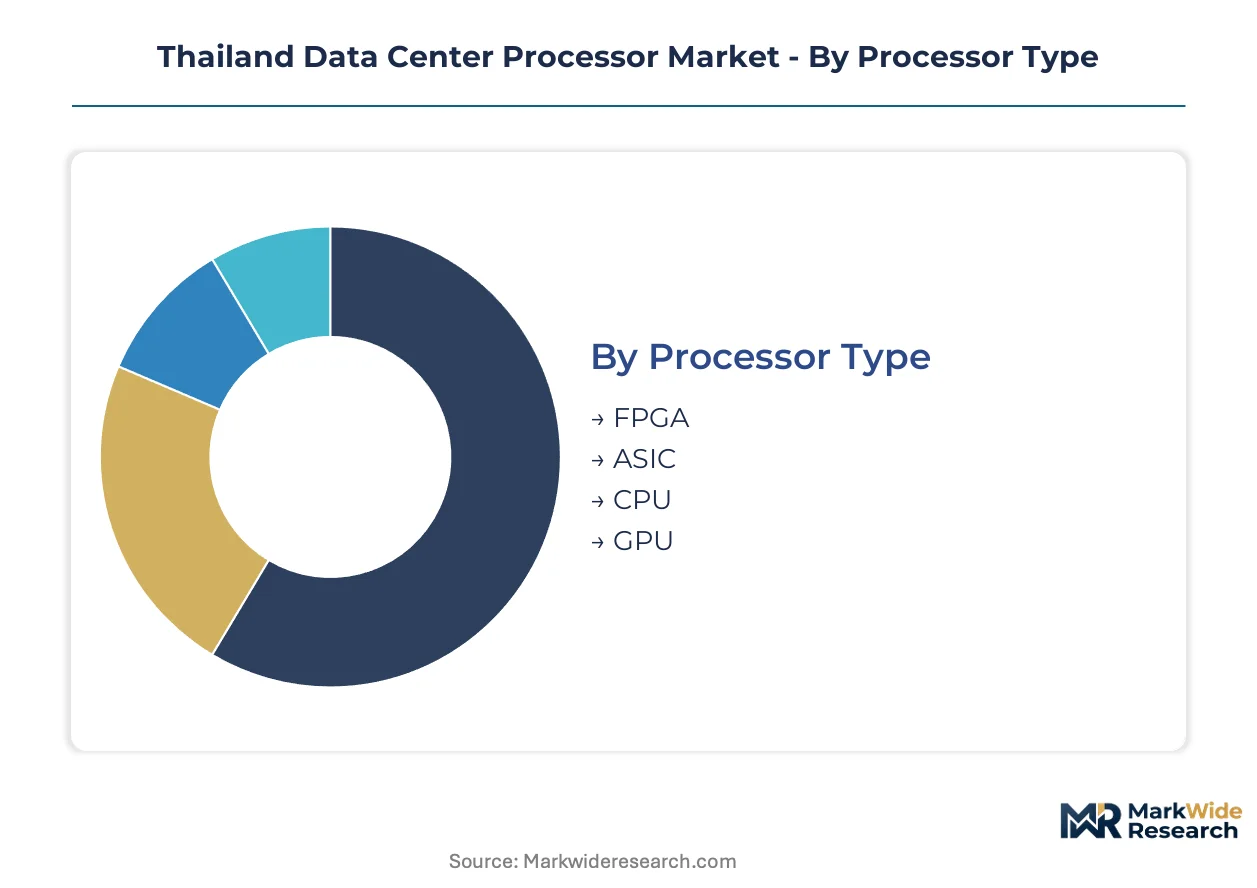
Thailand's data center processor market exhibits distinct procurement patterns across processor architectures, buyer categories, and deployment configurations. Understanding these segment boundaries reveals where pricing power concentrates and which technology transitions will reshape competitive dynamics.
Processor Type:
Buyers differentiate primarily by workload parallelism requirements and thermal constraints rather than upfront unit cost.
- CPU:General-purpose x86 and Arm-based processors handle transaction processing and virtualization across Thai enterprise racks. Bangkok's legacy financial institutions continue procuring high-core-count CPUs for core banking systems despite GPU encroachment in adjacent racks.
- GPU:Parallel compute engines with dedicated tensor cores accelerate AI training and inference pipelines. Cloud service providers in the Eastern Economic Corridor are deploying GPU-intensive clusters for Thai manufacturing clients' predictive maintenance workloads.
- FPGA:Field-programmable gate arrays enable customized acceleration for specific Thai telecommunications protocols. National Broadcasting and Telecommunications Commission certification requirements drive FPGA adoption for signal processing in domestic telecom edge facilities.
- ASIC:Application-specific integrated circuits deliver maximum efficiency for standardized inference tasks. Thai cryptocurrency mining operations historically consumed ASIC volumes; AI inference is now displacing that demand concentration.
CPU leads volumes today; GPU is gaining share fastest.
End User:
Procurement scale and technical sophistication create four distinct buyer tiers with incompatible purchasing processes.
- Cloud Service Providers:Hyperscale operators negotiate direct foundry allocations and custom silicon configurations. These buyers dominate Bangkok-region processor procurement volumes through multi-year supply agreements with Intel, NVIDIA, and AMD.
- Telecommunications:Domestic carriers and tower operators deploy processors at network edge locations for latency-sensitive applications. True Corporation and AIS are expanding processor procurement for 5G core infrastructure across provincial Thailand.
- Large Enterprises:Thai banks, automotive manufacturers, and petrochemical conglomerates maintain captive data centers with heterogeneous processor estates. Siam Commercial Bank and PTT Group represent concentrated demand for high-availability CPU deployments.
- SMEs:Small and medium enterprises access processor capacity through managed service providers rather than direct procurement. These buyers exert minimal influence on processor specification trends.
Cloud service providers command the steepest expansion trajectory; telecommunications maintains stable replacement demand.
Deployment Model:
Infrastructure control preferences and data residency requirements segment buyers across four architectural approaches.
- Colocation:Third-party facilities provide power, cooling, and physical security while tenants supply own servers. ST Telemedia Global Data Centres and SUPERNAP Thailand are expanding colocation processor hosting capacity in Bangkok and Chonburi.
- Hybrid:Workload orchestration across on-premises and off-premises infrastructure demands processor compatibility across environments. Thai manufacturers in the Eastern Economic Corridor favor hybrid deployments for production data sovereignty with burst capacity.
- Managed:Outsourced infrastructure operations include processor procurement and lifecycle management as a service. Domestic system integrators are capturing managed deployment growth among mid-market Thai enterprises.
- On-Premises:Self-operated server rooms retain sensitive workloads within corporate facilities. Legacy Thai financial institutions maintain on-premises processor deployments for regulatory compliance despite higher total cost of ownership.
Colocation leads volumes today; hybrid is climbing the fastest.
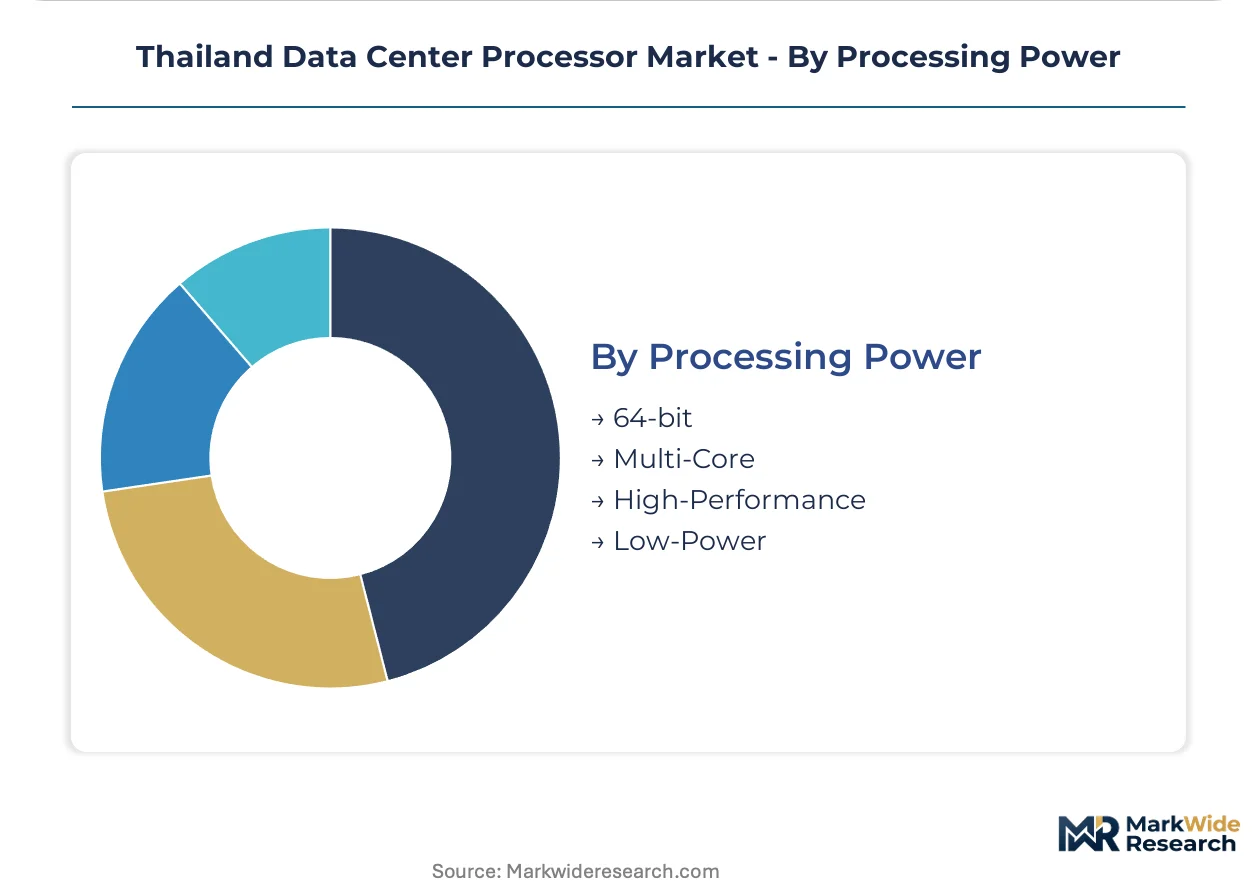
Processing Power:
Thermal design power and instruction set architecture create four performance tiers with distinct supply chains.
- Multi-Core:Processors with 32 to 128 cores address mainstream virtualization and containerized workloads. Thai cloud providers specify multi-core AMD EPYC and Intel Xeon configurations for general-purpose compute nodes.
- High-Performance:Extreme core counts and elevated thermal envelopes serve HPC and AI training clusters. Chonburi's emerging hyperscale campuses are specifying high-performance variants with liquid cooling infrastructure.
- 64-bit:Standard instruction set width dominates server-class processor procurement across all Thai deployment categories. This baseline capability no longer differentiates competitive positioning.
- Low-Power:Reduced thermal design power processors serve edge locations with constrained cooling and power availability. Northern Thailand's Chiang Mai province attracts low-power deployments exploiting ambient cooling advantages.
Multi-Core leads volumes today; high-performance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment tax holidays create a cost-of-compliance arbitrage that redirects data center investment from Singapore and Hong Kong toward Bangkok and the Eastern Economic Corridor. Provincial power allocation policies and carbon disclosure requirements now determine viable processor deployment locations.
Bangkok Metropolitan Region
Hyperscale cloud operators dominate processor procurement through direct foundry allocations with Intel and NVIDIA. The National Broadcasting and Telecommunications Commission certifies telecommunications-linked facilities under tightened energy efficiency standards. Latthaphakdee and Ratchada districts concentrate colocation capacity expansion for financial services workloads.
Eastern Economic Corridor
Chonburi and Rayong provinces attract GPU-intensive clusters for Thai manufacturing predictive maintenance. Board of Investment incentives mandate local content thresholds for qualifying digital infrastructure investments. Amata City and WHA Industrial Estates host liquid-cooled high-performance compute deployments exceeding 150-watt thermal design power.
Chiang Mai Province
Northern Thailand's cooler climate offers natural cooling advantages for sustainable data center expansion. Provincial authorities promote low-power processor deployments exploiting ambient temperature differentials. Mae Rim and Hang Dong districts emerge as secondary hubs for edge computing facilities serving northern ASEAN markets.
Rayong Province
Petrochemical conglomerates maintain captive high-availability CPU estates for operational technology integration. Eastern Seaboard power grid upgrades enable processor deployments previously constrained by infrastructure bottlenecks. Map Ta Phut industrial zone concentrates demand from PTT Group and affiliated energy sector operators.
Chonburi Province
Automotive manufacturers in the Eastern Seaboard favor hybrid deployment models for production data sovereignty. ST Telemedia Global Data Centres and SUPERNAP Thailand expand colocation processor hosting capacity. Laem Chabang port proximity facilitates rapid equipment import for time-sensitive hyperscale buildouts.
Thailand Data Center Processor Market Competitive Landscape
Capacity expansion dominates the current landscape as hyperscale operators secure multi-year supply agreements ahead of fabrication constraints. The vendor base concentrates around three processor architecture camps: x86 incumbents, GPU acceleration specialists, and Arm-based challengers. Strategic archetypes include full-stack solution providers bundling firmware optimization with hardware, component distributors serving mid-market enterprises, and vertically integrated cloud operators designing custom silicon. Geographic expansion and technology licensing represent the dominant competitive moves as players navigate Thai regulatory frameworks.
Within the x86 incumbent tier, Intel Corporation and Advanced Micro Devices Inc. occupy positions defined by established foundry partnerships and general-purpose server workload heritage. NVIDIA Corporation anchors the GPU acceleration segment through deep engagement with Thai AI and machine learning deployments. These three entities exemplify contrasting approaches to the Thai market: Intel leverages supply continuity across Southeast Asian distribution channels, AMD competes aggressively on price-performance metrics, and NVIDIA commands premium positioning for parallel compute-intensive applications. Arm Ltd. and Ampere Computing represent the emerging architecture challenge, particularly in power-constrained Bangkok facilities where Neoverse-derived chips displace legacy sockets.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices Inc. |
| NVIDIA Corporation |
| IBM Corporation |
| Arm Ltd. |
| Ampere Computing |
| Huawei Technologies |
| Qualcomm Incorporated |
| MediaTek Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud procurement consolidation in Bangkok and the Eastern Economic Corridor is compressing distributor margins and forcing foundry-direct supply negotiations that reshape pricing power across Thai processor channels. Board of Investment energy efficiency mandates add certification cost layers that filter through to end-user pricing, particularly for high thermal design power GPU clusters.
Pricing Analysis
Distributor markups in Thai processor channels are narrowing as cloud service providers negotiate direct foundry allocations with Intel, NVIDIA, and AMD. Pricing stratifies across premium AI-accelerated tiers, standard enterprise CPU configurations, and economy-grade legacy server replacements, with differentiation driven by thermal envelope compliance and local firmware support bundling. Cost compression in standard CPU tiers is intensifying because Arm-based Neoverse alternatives are displacing x86 sockets in power-constrained Bangkok facilities. Mid-market Thai enterprises exhibit the highest price sensitivity, while hyperscale operators prioritize supply continuity over unit cost.
Supply Chain Analysis
Freight costs from Taiwanese and Korean foundries to Laem Chabang port constitute a material landed cost component for Thai data center processor deployments. Fabrication capacity concentrates in Taiwan, South Korea, and the United States, with advanced node supply drawing from TSMC and Samsung Foundry operations. Raw material dependencies span silicon wafers, advanced packaging substrates, and specialized cooling fluids. Single-source vulnerability around sub-7nm EUV lithography capacity represents the dominant structural risk. Distribution runs through Southeast Asian logistics hubs into Bangkok-region integration facilities serving colocation and enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's data center processor market compounds steadily as AI inference workload expansion across Bangkok and Eastern Economic Corridor facilities sustains procurement momentum regardless of near-term enterprise capex cycles.
For Market Incumbents: Lock in multi-year foundry allocations with TSMC and Samsung Foundry to defend supply continuity commitments against Arm-based challenger encroachment in Thai cloud deployments. Prioritize certification investment for Board of Investment energy efficiency compliance to maintain tax incentive eligibility for processor-equipped facilities. Deepen firmware optimization partnerships with Thai system integrators to preserve socket share amid enterprise consolidation around full-stack solution providers.
For New Entrants and Emerging Players: Northern Thailand's edge computing buyers represent an underserved archetype with minimal hyperscale vendor penetration and ambient cooling advantages that favor low-power Arm deployments. Target Chiang Mai province for secondary hub development where established incumbents lack direct sales presence. Capture share through managed deployment services bundling processor procurement with Thai-language technical support for provincial manufacturing clients.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated cloud operators designing custom silicon for Thai AI inference workloads, capturing margin that currently flows to NVIDIA and AMD. The five-to-ten year viability window favors acquisitions of local system integrators with established Board of Investment certification relationships and hyperscale channel access. Watch for Board of Investment power allocation policy revisions as the inflection signal determining viable deployment locations for high-performance compute clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Direct TSMC and Samsung Foundry agreements secure sub-7nm allocation priority for Thai hyperscale buildouts. |
| Liquid Cooling Infrastructure Investment | Chonburi and Rayong facilities deploy advanced thermal systems to qualify for extended BOI tax holidays. |
| Arm Architecture Migration | Neoverse-based server adoption displaces legacy x86 sockets in Bangkok power-constrained colocation racks. |
| Local Content Compliance Program | BOI-mandated thresholds drive Thai system integrator partnerships for qualifying digital infrastructure investments. |
| Hybrid Cloud Orchestration Services | Eastern Economic Corridor manufacturers adopt workload bursting between on-premises and colocation processor capacity. |
Research Methodology
Coverage spans Thailand's Bangkok Metropolitan Region, Eastern Economic Corridor provinces, and northern secondary hubs, with primary inputs from each. The research combines structured interviews with data center procurement officers, cloud platform engineers, Board of Investment incentive specialists, and thermal infrastructure contractors alongside secondary validation through National Broadcasting and Telecommunications Commission certification filings, Board of Investment project approval databases, and hyperscaler capital expenditure disclosures. Bottom-up processor shipment estimates triangulate against top-down facility capacity buildout tracking.
Rate-of-change decomposition separates volume expansion from unit value migration across the projection horizon. The analytical framework models segmentation across processor architecture, end-user category, deployment model, and thermal design power tier, with regional clustering by provincial power allocation status. CAGRs derive from facility pipeline tracking and foundry allocation announcements. Forecast inputs incorporate Board of Investment incentive policy evolution and National Broadcasting and Telecommunications Commission energy efficiency certification trajectory.
Inputs from Board of Investment project registries and hyperscaler facility announcements were available through the study window; gaps in provincial power grid upgrade timelines introduce uncertainty bands around high-performance compute deployment pacing. Forecasts reflect assumptions about sustained AI inference demand expansion and continued BOI policy support. Stakeholders should weight assumptions against their own operating context and monitor regulatory developments for revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
PC Processor Market