
 Touch Sensor Market | 2026-2036
Touch Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Sensor Market Intelligence
Semiconductor fabrication talent scarcity is bifurcating the touch sensor competitive landscape into capital-rich integrated manufacturers and fabless design specialists. NXP Semiconductor N.V. leverages its automotive-qualified MCU portfolio to dominate in-vehicle touch controller sockets. Samsung Display Co., Ltd. anchors high-volume projected capacitive supply through captive vertical integration from glass to module. Synaptics Incorporated differentiates via algorithm-intensive force-sensing firmware for premium notebook trackpads.
A touch sensor detects and locates physical contact on a surface through capacitive, resistive, acoustic, or optical transduction mechanisms, typically resolving position within sub-millimeter accuracy across active areas from one inch to eighty-five inches diagonal. These devices translate human intent into machine-readable coordinates for displays, control panels, and human-machine interfaces spanning consumer, industrial, and mobility applications. Capacitive products lead volume shipments due to multi-touch capability and optical clarity, while force-sensing variants capture expanding margin pools in automotive haptic feedback and medical sterilization environments. Infrared and surface acoustic wave technologies sustain niche industrial positions where glove operation and environmental durability override cost sensitivity.
FCC equipment authorization rules govern electromagnetic emissions for touch controllers sold into US consumer electronics, while REACH substance restrictions constrain adhesive and coating chemistries for European-bound modules. China's GB standards and MIIT certification requirements shape local product testing protocols for domestic smartphone and automotive deployments. Stakeholders must monitor evolving automotive functional-safety grades and display-integrated touch stack consolidation to anticipate which technology architectures will absorb next-generation design wins.
Market Dynamics
Automotive electrification mandates are compressing design cycles for in-vehicle human-machine interfaces, forcing touch controller suppliers to pre-qualify stacks against ASIL functional-safety grades before platform lock-in. This regulatory pull is reshaping R&D allocation across the supply base.
Growth Catalysts
- EU automotive CO2 mandates:Zero-emission vehicle deadlines in Germany, France, and Italy are accelerating digital cockpit deployments that embed multi-touch displays as standard equipment.
- Foldable display stack thinning:Capacitive film-on-film architectures are capturing design wins in premium smartphone form factors where mechanical hinge durability demands flexible sensor layers.
- China MIIT certification pathways:Streamlined type-approval for domestic automotive modules is shortening time-to-revenue for locally manufactured touch controllers.
Market Restraints
- Indium tin oxide supply concentration:Sputtering target fabrication for transparent conductive layers depends on Chinese rare earth processing, exposing cost volatility.
- Dual-source qualification timelines:Automotive OEMs require 18-24 month validation cycles for secondary touch controller suppliers, freezing incumbent positions.
- Optical bonding yield loss:Lamination defects in direct-bonded display stacks scrap 8-12% of finished modules at current manufacturing maturity.
Strategic Opportunities
- India PLI scheme for electronics:Component-level incentives are attracting touch module assembly investments to serve domestic smartphone and appliance demand.
- Medical sterilization-grade force sensing:Haptic feedback systems that survive autoclave cycles are opening surgical equipment replacement cycles.
- ISO 26262 ASIL-B pre-certification:Pre-validated touch controller firmware is creating attach-rate premiums in mid-tier automotive platforms.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromagnetic-capacitive coupling modeling for large-format automotive displays requires specialized finite-element expertise concentrated in South Korea and Taiwan.
- Legacy LIN bus integration:Touch controllers must bridge to 20-year-old vehicle network architectures without latency degradation, complicating firmware architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Sensor Market |
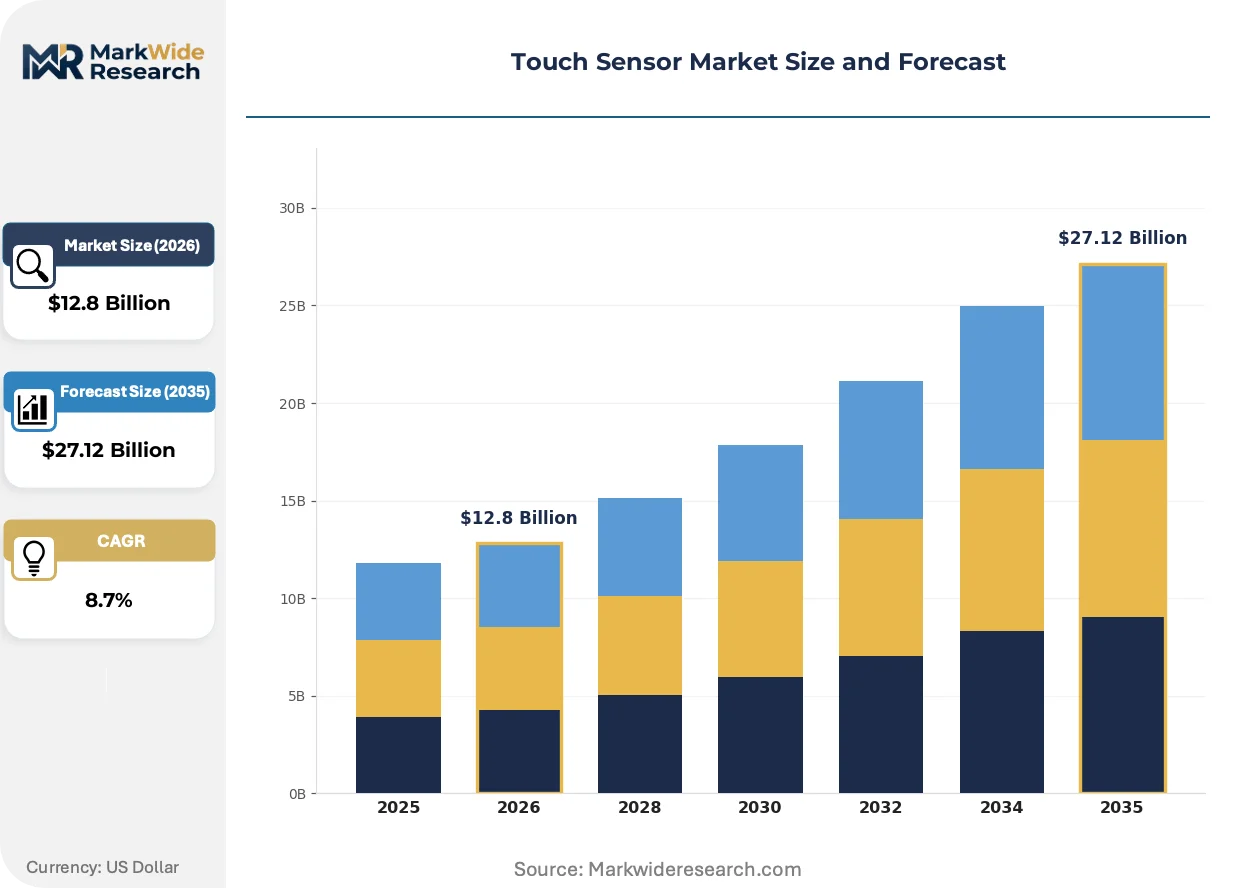
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Surface Acoustic Wave, Optical, Force Sensing Technology: Projected Capacitive, Dispersive Signal, Mutual Capacitance, Self Capacitance, Infrared Touch, Acoustic Wave Application: Consumer Electronics, Industrial Controls, Automotive Interfaces, Gaming Devices, Medical Instruments, Smart Home End User: Smartphone Manufacturers, Industrial Equipment Makers, Vehicle System Providers, Medical Device Companies, Gaming Hardware Firms, Home Automation Developers |
| Companies Covered | NXP Semiconductor N.V., Samsung Display Co., Ltd., Synaptics Incorporated, BOE Technology Group Co., Ltd., LG Display Co., Ltd., Infineon Technologies AG, STMicroelectronics N.V., TPK Holding, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Sensor Market Strategic Shifts & Innovations
Touch sensor architectures are fragmenting along application-specific performance axes, with automotive safety grades and consumer foldable durability requirements diverging material and process roadmaps. Suppliers are forced to maintain parallel technology tracks rather than universal platform strategies.
Self-capacitive force-sensing arrays with integrated strain-gauge compensation are supplanting traditional mutual-capacitive stacks in automotive center console applications. Tier 1 cockpit integrators in Germany and Japan are adopting these for haptic feedback compliance with NHTSA distraction guidelines. The shift is compressing margins for legacy two-chip touch-plus-force solutions.
REACH substance restrictions on perfluorinated compounds are eliminating legacy hydrophobic coatings used in outdoor industrial touch panels. ECHA's 2023 amendment to Annex XVII is forcing reformulation of oleophobic surface treatments for European-bound kiosks and marine equipment. Module suppliers are qualifying plasma-enhanced chemical vapor deposition alternatives with 18-month requalification cycles.
Fleet operators and industrial OEMs are consolidating touch controller procurement through long-term supply agreements that bundle firmware customization and field failure analysis. Direct contracting with fabless design houses is displacing distribution-channel purchasing for volumes above 500,000 units annually. This concentration is most visible in North American agricultural and construction equipment where Deere and Caterpillar procurement teams negotiate multi-year controller supply.
Touch Sensor Market Segmentation
Touch sensor architectures fragment along performance-cost axes, with automotive safety grades and consumer foldable durability requirements diverging material roadmaps. Suppliers must maintain parallel technology tracks rather than universal platforms, as substitution pressure varies sharply by end-use environment and regulatory exposure.
Product Type:
Capacitive variants face intense substitution pressure from force-sensing arrays in automotive haptic applications, while resistive technologies cede ground to optical alternatives in industrial glove-operation scenarios.
- Capacitive:Projected capacitive arrays dominate smartphone and tablet stacks through multi-touch capability and optical clarity. Demand concentrates in foldable display modules manufactured in South Korea and Taiwan, where mechanical hinge durability requirements favor film-on-film architectures over glass substrates.
- Force Sensing:Strain-gauge compensation circuits integrated with self-capacitive arrays enable pressure-variable input detection. Automotive center console deployments in Germany and Japan are absorbing volumes as Tier 1 integrators comply with NHTSA distraction guidelines through haptic feedback systems.
- Resistive:Pressure-activated membrane stacks persist in cost-constrained industrial panels and legacy medical equipment where stylus precision outweighs multi-touch functionality.
- Infrared:LED emitter-detector arrays around display perimeters sustain niche positions in outdoor kiosks and marine equipment where glove operation and environmental durability override cost sensitivity.
- Surface Acoustic Wave:Piezoelectric transducer grids on glass substrates serve high-transparency applications in museum exhibits and clean-room environments.
- Optical:Camera-based or infrared imaging systems capture emerging demand for large-format interactive surfaces in education and corporate collaboration spaces.
Capacitive retains volume leadership; force sensing holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium projected capacitive controllers from commodity mutual capacitance solutions, with automotive-grade ASIL certification creating a distinct pricing band.
- Projected Capacitive:XY electrode matrices etched on flexible substrates enable sub-millimeter accuracy across diagonal dimensions exceeding eighty inches. Samsung Display anchors high-volume supply through captive integration from glass to module, capturing premium smartphone and automotive display sockets.
- Self Capacitance:Single-electrode measurement circuits with integrated force-sensing compensation are supplanting two-chip solutions in automotive center consoles. German and Japanese Tier 1 integrators specify these for haptic feedback compliance, compressing margins for legacy discrete implementations.
- Mutual Capacitance:Transmitter-receiver electrode pairs dominate consumer electronics volume through established manufacturing economics and mature controller firmware ecosystems.
- Dispersive Signal:Piezoelectric substrate bending detection enables large-format touch recognition without electrode patterning, serving cost-sensitive digital signage deployments.
- Infrared Touch:Frame-mounted emitter-detector arrays persist in industrial applications requiring glove operation and chemical resistance.
- Acoustic Wave:Surface or bulk wave propagation detection maintains position in high-clarity medical and laboratory equipment.
Projected capacitive commands the premium tier; self capacitance is gaining share fastest in automotive-qualified implementations.
Application:
Volume concentration in consumer electronics contrasts with margin expansion in medical and automotive segments, where sterilization-grade and functional-safety requirements create defensible pricing power.
- Consumer Electronics:Smartphones, tablets, wearables, and notebook trackpads absorb the majority of projected capacitive volume. Foldable form factors are driving film-on-film sensor adoption as mechanical hinge durability demands flexible stack architectures.
- Automotive Interfaces:Center consoles, instrument clusters, and rear-seat entertainment systems embed multi-touch displays as standard equipment under tightening EU CO2 mandates. ASIL-B pre-certified controllers from NXP Semiconductor capture design wins through automotive-qualified MCU portfolios.
- Industrial Controls:Manufacturing equipment, process automation panels, and outdoor kiosks specify resistive or infrared technologies where environmental durability and glove operation take precedence over optical clarity.
- Medical Instruments:Surgical equipment, diagnostic devices, and sterilizable interfaces demand force-sensing arrays that survive autoclave cycles. ECHA REACH restrictions on perfluorinated compounds are forcing coating reformulation with eighteen-month requalification timelines.
- Gaming Devices:Arcade machines, handheld consoles, and VR controllers prioritize low-latency response and pressure-sensitive input for immersive interaction.
- Smart Home:Thermostats, appliance control panels, and security interfaces integrate capacitive touch as differentiation features in premium product tiers.
Consumer electronics retains volume leadership; medical instruments hold the steepest margin expansion trajectory.
End User:
Procurement concentration among vehicle system providers and medical device companies is displacing distribution-channel purchasing, with direct long-term supply agreements bundling firmware customization and field failure analysis.
- Smartphone Manufacturers:Apple, Samsung, and Chinese OEMs consolidate display-module procurement through captive suppliers and strategic controller partnerships. China, South Korea, and Taiwan concentrate manufacturing and design activity.
- Vehicle System Providers:Continental, Bosch, and Denso specify touch controllers eighteen to twenty-four months ahead of platform launch, freezing incumbent positions through dual-source qualification timelines. MIIT certification pathways in China are shortening time-to-revenue for locally manufactured modules.
- Medical Device Companies:Surgical equipment OEMs negotiate multi-year supply agreements for sterilization-grade force-sensing controllers with integrated haptic feedback.
- Industrial Equipment Makers:Agricultural and construction OEMs including Deere and Caterpillar consolidate procurement through direct fabless design house contracts above five hundred thousand annual units.
- Gaming Hardware Firms:Console manufacturers and peripheral suppliers prioritize controller latency and pressure sensitivity specifications for competitive gaming applications.
- Home Automation Developers:Smart appliance and security system integrators specify capacitive interfaces as premium tier differentiators in residential markets.
Smartphone manufacturers retain volume leadership; vehicle system providers hold the steepest procurement concentration curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification requirements and GB standards anchor China's regulatory framework for touch sensor deployments across automotive and consumer electronics sectors. National regulators in Germany, South Korea, Japan, and the United States shape parallel compliance pathways that fragment procurement specifications by destination market.
China
Domestic smartphone OEMs and EV manufacturers drive capacitive controller demand through MIIT streamlined type-approval processes. GB standards mandate electromagnetic compatibility testing for automotive modules before domestic platform integration. Display-module manufacturing concentrates in Shenzhen and Dongguan, where BOE Technology and TPK Holding operate high-volume film-on-film assembly lines for foldable devices.
Germany
Continental and Bosch procurement teams specify ASIL-B pre-certified touch controllers eighteen to twenty-four months ahead of SOP for EU CO2-compliant vehicle platforms. KBA homologation rules enforce functional-safety validation for center console interfaces in zero-emission vehicle mandates. Bavaria's automotive Tier 1 ecosystem in Ingolstadt and Munich anchors cockpit integration engineering for force-sensing haptic systems.
South Korea
Samsung Display's captive vertical integration from glass substrate to finished module dominates projected capacitive supply for premium smartphone form factors. MFDS medical device regulations shape sterilization-grade force-sensing requirements for surgical equipment exports. Seoul and Suwon host concentrated touch-controller design activity alongside display-panel fabrication in Gumi and Asan.
Japan
Denso and Panasonic procurement patterns prioritize LIN bus-compatible firmware architectures for legacy vehicle network integration. METI industrial standards govern outdoor kiosk deployments requiring infrared alternatives to capacitive stacks. Nagoya's automotive electronics corridor and Osaka's industrial automation cluster sustain specialized demand for acoustic wave and resistive technologies.
United States
NHTSA distraction guidelines push Tier 1 integrators toward haptic feedback systems with integrated force-sensing arrays. FCC equipment authorization rules govern electromagnetic emissions for consumer electronics controllers sold into domestic retail channels. Austin and Dallas anchor Texas Instruments' touch controller design activity, while California's EV startup ecosystem sources automotive-qualified modules through direct fabless contracts.
Touch Sensor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive display manufacturers and automotive-qualified semiconductor suppliers occupying distinct competitive positions. The market structure reflects bifurcation between capital-intensive fabrication and algorithm-intensive firmware design. Three archetypes dominate: vertically integrated display-module producers, automotive-functional-safety specialists, and fabless force-sensing algorithm developers. Competitive moves concentrate on ASIL pre-certification investments and film-on-film process qualification for foldable stacks.
Within the automotive-qualified tier, NXP Semiconductor N.V. and Infineon Technologies AG occupy positions defined by MCU portfolio breadth and functional-safety pedigree. Samsung Display Co., Ltd. exemplifies captive integration advantages in high-volume projected capacitive supply. Synaptics Incorporated represents the fabless algorithm-intensive archetype, with force-sensing firmware differentiation for premium notebook and automotive haptic applications.
| Leading Market Players |
|---|
| NXP Semiconductor N.V. |
| Samsung Display Co., Ltd. |
| Synaptics Incorporated |
| BOE Technology Group Co., Ltd. |
| LG Display Co., Ltd. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| TPK Holding |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Indium tin oxide sputtering target substitution by silver nanowire and metal mesh alternatives is simultaneously shifting transparent conductor procurement toward South Korean and Japanese specialty chemical suppliers and compressing pricing premiums for legacy ITO-dependent module stacks. This materials transition feeds directly into automotive-qualified controller sourcing decisions, as Tier 1 integrators weigh coating uniformity guarantees against rare earth supply exposure from Chinese processing concentration.
Pricing Analysis
Geographic price spreads between automotive-grade ASIL-B certified controllers and consumer electronics commodity solutions span approximately three-to-one ratios, with German and Japanese cockpit integration programs absorbing premium positioning. Price differentiation hinges on ISO 26262 certification tier and firmware customization depth, while cost compression in mutual-capacitive smartphone stacks intensifies from foldable display yield challenges. Automotive OEMs demonstrate lowest price sensitivity due to eighteen-month dual-source qualification lock-in, whereas white-label tablet manufacturers operate at highest margin pressure.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time consumables for high-volume smartphone assembly in Shenzhen and Dongguan, versus strategic six-month indium and rare earth stockpiles among automotive-qualified semiconductor fabricators. Supply concentrates in China, South Korea, and Taiwan for display-module finishing, with sputtering target fabrication drawing from Chinese rare earth processing and Japanese specialty glass substrates. Single-source vulnerability in ITO precursor supply creates tariff exposure risk. Distribution runs through direct long-term agreements above five hundred thousand units, displacing channel purchasing for Tier 1 automotive and agricultural equipment OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where automotive functional-safety certification creates regulatory entrenchment. Switching costs for validated touch controller stacks exceed eighteen months, freezing incumbent positions against unqualified challengers.
For Market Incumbents: Consolidate ASIL-B pre-certification portfolios through firmware library expansion and captive film-on-film process qualification in South Korea. Threats from self-capacitive force-sensing substitution demand accelerated haptic feedback algorithm investment. Leverage vertical integration into strain-gauge compensation IC design to defend controller attach rates in German and Japanese Tier 1 programs. For New Entrants and Emerging Players: Differentiate on medical sterilization-grade force sensing where autoclave survivability requirements and eighteen-month ECHA coating requalification cycles create specialist entry barriers. White-space concentrates in Indian PLI scheme module assembly for domestic appliance demand, with surgical equipment OEMs in Bavaria and Osaka offering direct contracting pathways bypassing distribution channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automotive-functional-safety specialists with captive algorithm IP over commodity controller vendors. Long-term viability across the next decade hinges on film-on-film process mastery for foldable display attach expansion. Acquisition targets should demonstrate MIIT certification track records and multi-physics simulation talent concentration. Watch for NHTSA distraction guideline enforcement tightening as haptic feedback mandate inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-B Pre-Certification Investment | Automotive OEM procurement teams lock eighteen-month validation cycles around pre-qualified firmware stacks. |
| Film-on-Film Process Qualification | Samsung Display and BOE Technology anchor foldable module supply through captive flexible substrate integration. |
| Force-Sensing Algorithm Development | NHTSA distraction guideline compliance in German and Japanese center console programs demands haptic feedback integration. |
| India PLI Scheme Module Assembly | Domestic smartphone and appliance demand attracts component-level manufacturing investment away from China concentration. |
| Sterilization-Grade Coating Reformulation | ECHA REACH Annex XVII amendments force eighteen-month requalification for European-bound medical equipment. |
Research Approach
Cross-validation between primary interviews with touch controller design engineers, Tier 1 automotive procurement directors, display-module manufacturing operations heads, and medical device regulatory affairs specialists anchors the qualitative findings against secondary validation from MIIT certification databases, ECHA REACH substance restriction filings, FCC equipment authorization records, and automotive platform production schedules. Bottom-up unit demand modeling triangulates against top-down semiconductor consumption estimates across the analysis window.
Sensitivity analysis around foldable display adoption curves and automotive electrification mandate enforcement timelines shapes the analytical framework. Segmentation dimensions span product type, technology tier, application environment, and end-user procurement concentration, with regional regulatory cluster effects layered across the projection horizon. CAGR derivation rests on historical controller attach rate trajectories and content-per-vehicle expansion in digital cockpit architectures, incorporating indium price volatility and rare earth supply disruption scenarios as scenario inputs.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification policy enforcement or foldable display yield recovery trajectories would require recalibration. Forecasts reflect documented assumptions around certification timeline standardization and coating chemistry substitution rates. Revision becomes warranted when ECHA substance restriction scope or NHTSA haptic feedback mandate thresholds cross implementation triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market