
 Humidity Sensor Market | 2026-2036
Humidity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Humidity Sensor Market Intelligence
ISO/IEC 17025 calibration accreditation is redrawing competitive boundaries in humidity sensing. Bosch Sensortec GmbH leverages MEMS fabrication scale to dominate consumer electronics supply chains. Sensirion AG anchors its position through proprietary CMOSens technology platforms. Texas Instruments Incorporated competes by integrating humidity sensing with broader environmental sensor portfolios.
A humidity sensor measures water vapor concentration in air or gas, typically operating across 0% to 100% relative humidity with accuracy thresholds of ±2% RH in industrial-grade units. These devices convert moisture-induced physical changes into electrical signals for process control and environmental management. Digital humidity sensors now lead product type demand due to direct microcontroller compatibility and elimination of analog signal conditioning. Capacitive technology captures the dominant technology share, while resistive variants retain niche positions in cost-sensitive agricultural deployments. Indoor air quality applications are outpacing weather monitoring in growth velocity, reflecting post-pandemic building ventilation upgrades.
The EPA's Clean Air Act enforcement and the EU F-Gas Regulation are tightening environmental monitoring compliance, directly expanding sensor deployment in HVAC and industrial refrigeration systems. REACH chemical restrictions are altering polymer choices in capacitive sensor substrates, forcing reformulation cycles among European suppliers. FDA 21 CFR Part 11 guidelines for pharmaceutical environmental records are mandating calibrated humidity documentation in drug manufacturing. Stakeholders must weigh certification costs against the margin premiums available in regulated end uses.
Market Dynamics
The EU Green Deal's building efficiency mandates are compressing HVAC upgrade cycles, forcing sensor suppliers to recalibrate production toward calibrated digital units with embedded traceability features.
Growth Catalysts
- Pharmaceutical cold chain expansion:FDA 21 CFR Part 11 documentation requirements for environmental monitoring are mandating calibrated humidity sensors in drug manufacturing facilities across the United States.
- REACH substrate reformulation:ECHA restrictions on polymer chemistries are accelerating European supplier investment in alternative capacitive materials with equivalent moisture sensitivity.
- Industrial automation corridor concentration:Germany's Ruhr-to-Bavaria manufacturing belt is deploying networked humidity sensors for predictive maintenance in precision machining environments.
Market Restraints
- MEMS fabrication concentration:Consumer-grade sensor supply depends on a limited number of high-volume foundries in East Asia, creating vulnerability to regional disruption.
- Calibration accreditation cost escalation:ISO/IEC 17025 certification requirements are raising fixed costs for smaller European suppliers serving regulated pharmaceutical and food processing end uses.
- Resistive technology substitution ceiling:Capacitive sensors dominate precision applications, but cost-sensitive agricultural monitoring in developing markets retains legacy resistive architectures that limit average selling price recovery.
Strategic Opportunities
- Indoor air quality retrofit wave:Post-pandemic building ventilation upgrades in commercial real estate across France and Italy are outpacing new construction sensor deployment.
- Sensor-to-cloud integration:Convergence of humidity sensing with LoRaWAN and NB-IoT protocols is enabling unstaffed environmental monitoring in remote agricultural and warehouse applications.
- F-Gas Regulation enforcement:The EU's tightened industrial refrigeration monitoring requirements are expanding sensor deployment in supermarket cold chains and food processing facilities.
Industry Challenges
- Multi-physics simulation talent scarcity:CMOS-MEMS co-design for humidity sensors requires expertise spanning semiconductor fabrication and polymer science that concentrates in specialized research clusters.
- Legacy system integration friction:Digital humidity sensors with I2C and SPI outputs face adoption barriers in industrial plants running 4-20mA analog control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humidity Sensor Market |
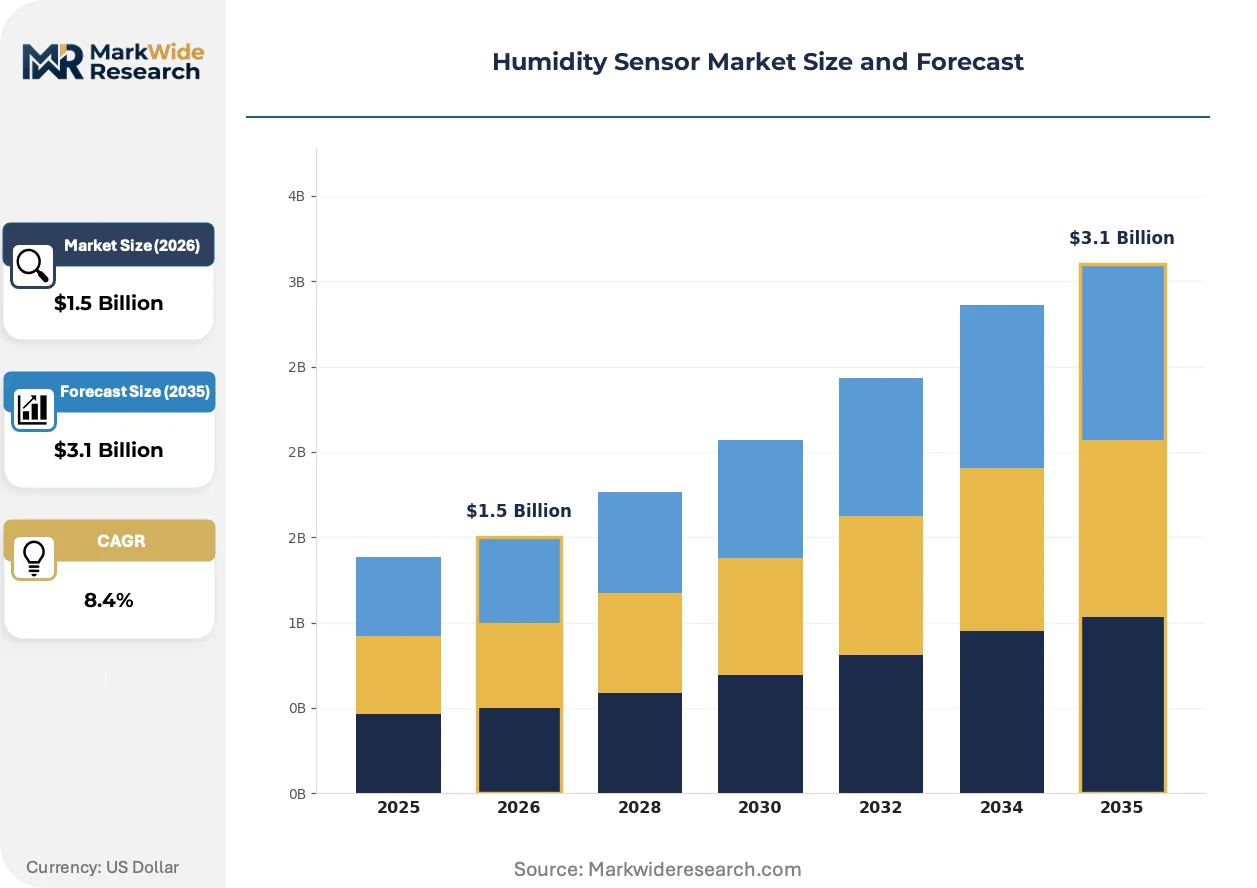
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $3.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Humidity Sensors, Digital Humidity Sensors, Capacitive Humidity Sensors, Resistive Humidity Sensors End User: Manufacturing, Agriculture, HVAC, Automotive Technology: Thermal, Capacitive, Resistive, Optical Application: Weather Monitoring, Indoor Air Quality, Industrial Automation, Pharmaceutical |
| Companies Covered | Honeywell International Inc., Sensirion AG, Texas Instruments Incorporated, TE Connectivity, Bosch Sensortec GmbH, Amphenol Advanced Sensors, Siemens AG, STMicroelectronics, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humidity Sensor Market Strategic Shifts & Innovations
MEMS-based humidity sensing is compressing form factors while raising accuracy thresholds, forcing a recalibration of how suppliers segment between consumer electronics and industrial-grade portfolios.
Polymer-based capacitive sensing is miniaturizing through wafer-level packaging advances that embed the humidity-sensitive layer directly atop CMOS readout circuits. Wearable device manufacturers in South Korea and Japan are absorbing these components at volumes that outpace traditional industrial demand. The technology is miniaturizing sensor footprints below 2mm x 2mm, collapsing the historical separation between environmental and inertial sensor supply chains.
The EPA's Clean Air Act enforcement is tightening particulate and moisture monitoring requirements in commercial building ventilation systems. Facility managers in the United States must now document continuous humidity control as part of indoor air quality compliance. HVAC OEMs are responding by specifying calibrated digital sensors with onboard temperature compensation rather than discrete analog components.
Certification-driven procurement is consolidating buyer preference around suppliers with documented ISO/IEC 17025 traceability. Pharmaceutical and food processing facilities in Germany and Switzerland are unbundling sensor supply from system integrator contracts to direct relationships with accredited component vendors. This pattern is most visible in Basel's pharmaceutical manufacturing cluster and Munich's food processing equipment supply chain.
Humidity Sensor Market Segmentation
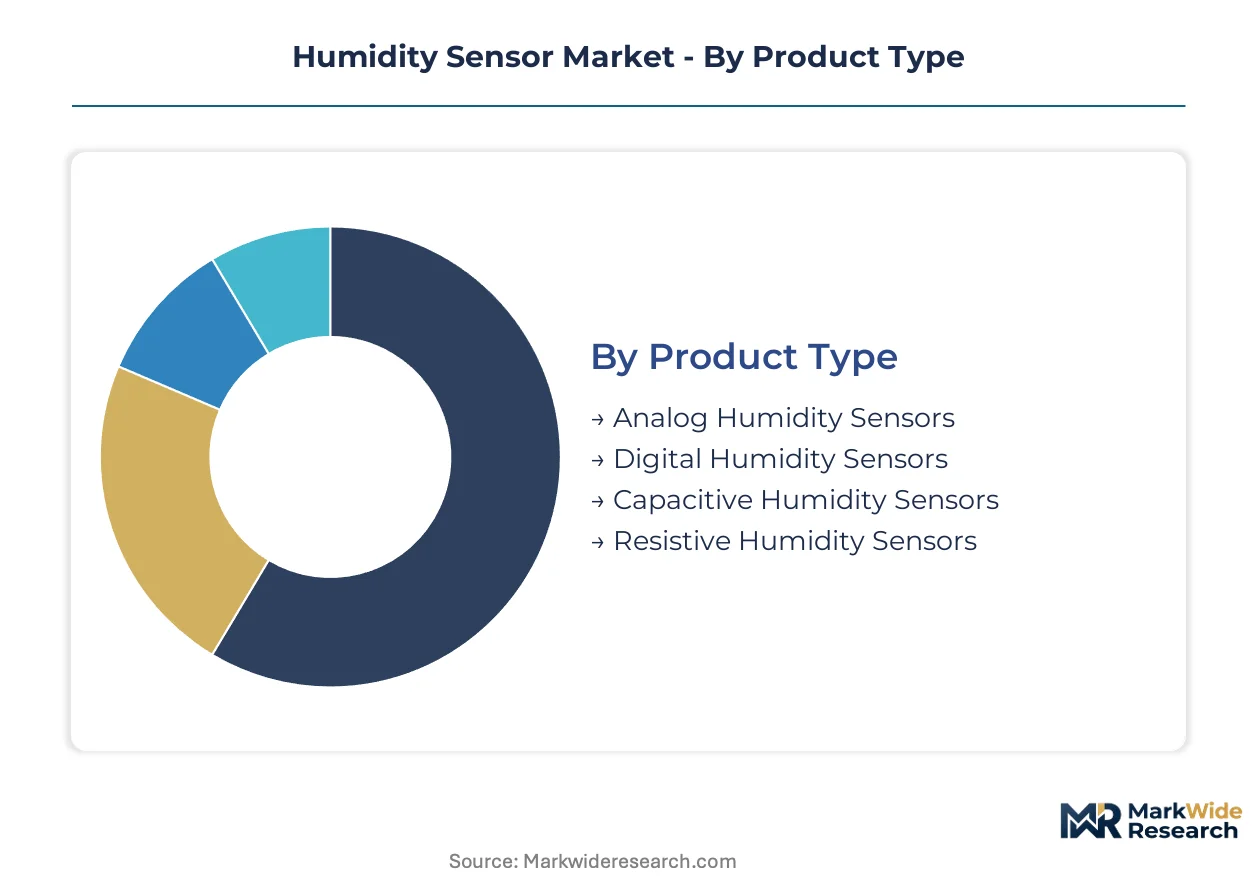
Humidity sensor procurement patterns diverge sharply between regulated industries demanding calibrated traceability and cost-driven sectors tolerating wider accuracy tolerances. Understanding these segment boundaries clarifies where premium pricing commands sustained premiums versus commodity substitution threats.
Product Type:
Resistive architectures face the most acute substitution pressure as capacitive and digital alternatives capture precision applications while MEMS scale economies erode their cost advantage.
- Digital Humidity Sensors:These devices integrate analog-to-digital conversion with I2C or SPI output protocols, eliminating external signal conditioning components. Demand concentrates in pharmaceutical manufacturing facilities across Germany and Switzerland where FDA 21 CFR Part 11 documentation requirements mandate calibrated digital outputs with embedded traceability features.
- Capacitive Humidity Sensors:Polymer-based dielectric layers between conductive plates yield ±2% RH accuracy with superior long-term stability. HVAC OEMs in France and Italy specify these units for post-pandemic building ventilation retrofits requiring continuous moisture monitoring under EPA Clean Air Act enforcement.
- Analog Humidity Sensors:Voltage or current output variants persist in legacy industrial control systems with 4-20mA architectures.
- Resistive Humidity Sensors:Ceramic or polymer resistance-change mechanisms retain niche positions in cost-sensitive agricultural deployments across developing markets.
Digital humidity sensors anchor the volume base while capacitive variants gain share at the steepest rate in regulated end uses.
End User:
Margin structures vary dramatically across this dimension, with certification-heavy segments commanding triple the component pricing of unregulated volume applications.
- Pharmaceutical:Cold chain monitoring and cleanroom environmental control require ISO/IEC 17025 calibrated sensors with documented traceability chains. Basel's manufacturing cluster and Munich's processing equipment supply chain are unbundling sensor procurement from system integrator contracts to direct accredited vendor relationships.
- HVAC:Building automation systems integrate humidity sensing with temperature and CO2 monitoring for demand-controlled ventilation. The EU Green Deal's efficiency mandates are compressing upgrade cycles toward calibrated digital units with embedded diagnostics.
- Manufacturing:Precision machining environments in Germany's Ruhr-to-Bavaria corridor deploy networked sensors for predictive maintenance and corrosion prevention.
- Agriculture:Greenhouse and grain storage monitoring in developing markets retains legacy resistive architectures that limit average selling price recovery.
Pharmaceutical applications extract the highest margins per unit while HVAC delivers the steepest volume expansion trajectory.
Technology:
Wafer-level packaging advances are collapsing the historical separation between sensing technologies and CMOS readout circuits, reshaping competitive boundaries.
- Capacitive:Polymer dielectric humidity absorption alters capacitance between interdigitated electrodes, achieving ±2% RH accuracy with minimal drift. MEMS fabrication scale in East Asian foundries is compressing form factors below 2mm x 2mm for wearable device integration.
- Thermal:Absolute humidity measurement through thermal conductivity differential between dry and humid air references offers intrinsic calibration stability. Niche deployment persists in meteorological stations and laboratory reference applications.
- Resistive:Impedance changes in hygroscopic materials provide cost-minimized solutions where ±5% RH tolerance suffices.
- Optical:Fiber-optic or infrared absorption techniques enable intrinsic safety in explosive atmospheres and electromagnetic interference immunity.
Capacitive technology dominates precision applications while thermal methods retain defensible positions in calibration-critical reference deployments.
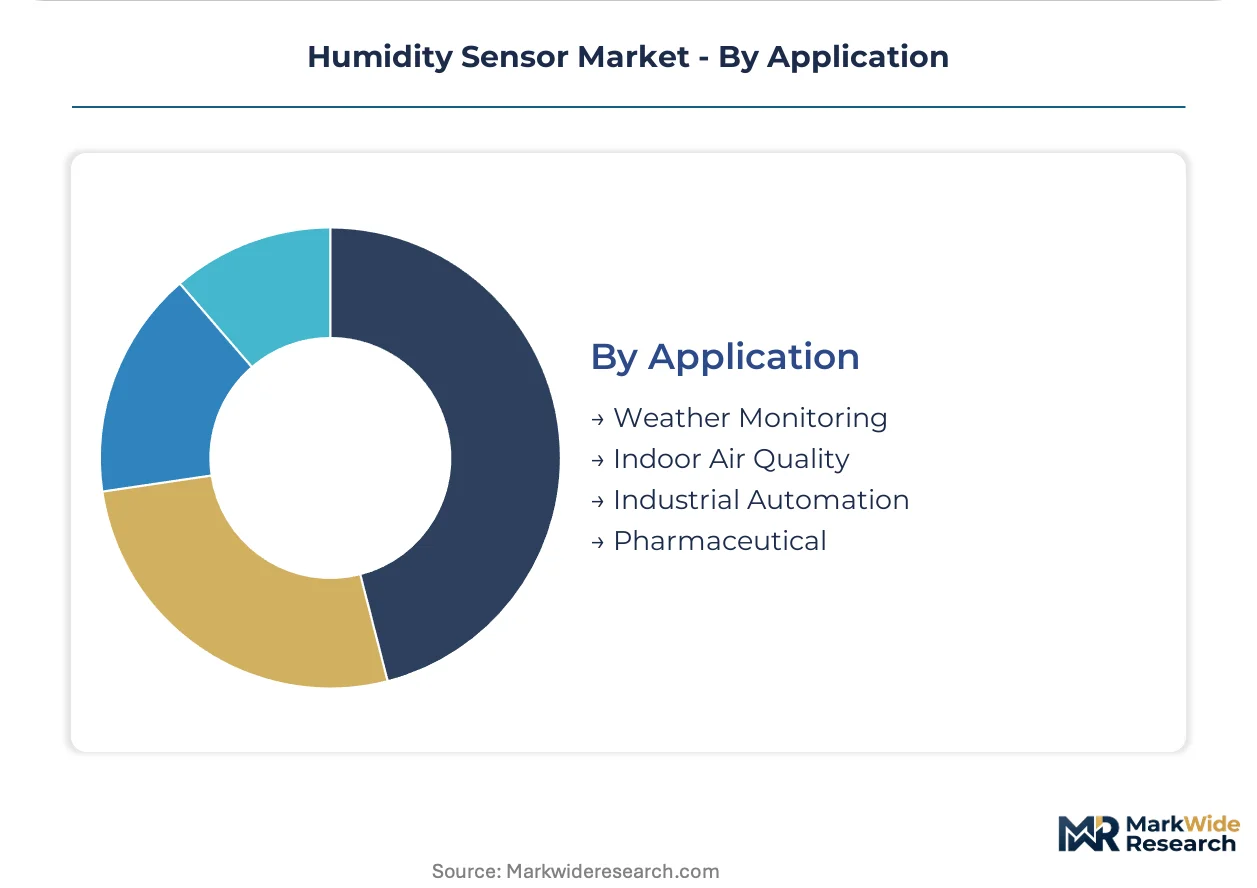
Application:
Post-pandemic building ventilation upgrades have inverted the historical priority ranking of environmental monitoring use cases.
- Indoor Air Quality:Continuous humidity control documentation is now mandatory under EPA Clean Air Act enforcement for commercial building compliance. Facility managers specify calibrated digital sensors with onboard temperature compensation rather than discrete analog components.
- Pharmaceutical:Drug manufacturing environmental records under FDA 21 CFR Part 11 guidelines mandate calibrated humidity documentation with audit trail capabilities. This segment exhibits the most inelastic demand for premium-tier sensor specifications.
- Industrial Automation:Predictive maintenance algorithms in precision machining environments integrate humidity data with vibration and thermal monitoring.
- Weather Monitoring:Meteorological station networks and agricultural forecasting systems retain steady but slower-expanding demand profiles.
Indoor air quality applications now lead volume growth while pharmaceutical maintains the most stringent specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and HVAC integrators concentrate procurement authority in calibrated sensor suppliers with documented traceability chains. FDA and EU Green Deal enforcement compress upgrade cycles in regulated facilities. Industrial automation corridors in Germany, cold chain networks in the United States, and building retrofit programs in France anchor regional demand patterns.
United States
Pharmaceutical cold chain expansion and commercial building ventilation upgrades drive sensor deployment. EPA Clean Air Act enforcement mandates continuous humidity documentation for indoor air quality compliance. Facility managers in Greater Boston and the Research Triangle specify calibrated digital units with embedded temperature compensation.
Germany
Industrial automation corridors and pharmaceutical manufacturing clusters generate concentrated demand for precision-grade units. EU F-Gas Regulation enforcement tightens industrial refrigeration monitoring requirements. The Ruhr-to-Bavaria manufacturing belt deploys networked humidity sensors for predictive maintenance in precision machining environments.
Switzerland
Pharmaceutical environmental monitoring requirements under FDA 21 CFR Part 11 guidelines mandate calibrated sensor procurement with audit trail capabilities. Swissmedic oversight reinforces documentation standards for drug manufacturing facilities. Basel's pharmaceutical manufacturing cluster unbundles sensor supply from system integrator contracts to direct accredited vendor relationships.
France
Post-pandemic building ventilation retrofits in commercial real estate outpace new construction sensor deployment. EU Green Deal building efficiency mandates compress HVAC upgrade cycles toward calibrated digital units. Facility managers in Île-de-France and Auvergne-Rhône-Alpes specify continuous moisture monitoring for compliance documentation.
Japan
Wearable device manufacturers absorb miniaturized MEMS humidity sensors at volumes that outpace traditional industrial demand. METI industrial standards guide environmental sensor integration in precision manufacturing. South Korean and Japanese consumer electronics supply chains compress form factors below 2mm x 2mm for next-generation device integration.
Humidity Sensor Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive semiconductor fabrication capabilities and specialized sensor technology firms with proprietary CMOS-MEMS platforms. The vendor base concentrates around three strategic archetypes: MEMS-scale consumer electronics suppliers, calibration-accredited pharmaceutical specialists, and diversified environmental sensor portfolio vendors. Competitive dynamics center on ISO/IEC 17025 accreditation acquisition and wafer-level packaging scale economies.
Within the diversified industrial tier, Honeywell International Inc. and Siemens AG exemplify conglomerate-backed market presence spanning building automation and pharmaceutical applications. Sensirion AG anchors the specialized technology tier through Swiss-based CMOSens platform development. Bosch Sensortec GmbH represents the MEMS-scale fabrication archetype with German automotive and consumer electronics supply chain integration. These three archetypes occupy distinct competitive positions based on certification depth, manufacturing scale, and end-use concentration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sensirion AG |
| Texas Instruments Incorporated |
| TE Connectivity |
| Bosch Sensortec GmbH |
| Amphenol Advanced Sensors |
| Siemens AG |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Others |
Cost & Logistics Intelligence
ISO/IEC 17025 accreditation gates both supply qualification and price differentiation simultaneously, bifurcating the market between certified pharmaceutical suppliers commanding premium positioning and uncertified volume producers competing on unit economics. This regulatory threshold forces buyers to unbundle procurement from system integrators, creating direct contracting relationships that transmit certification costs into end-user pricing while compressing margins for non-accredited vendors.
Pricing Analysis
Cost-plus contracts with polymer substrate indexation dominate pharmaceutical and HVAC procurement, insulating accredited suppliers from raw material volatility while locking in margin premiums. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified units with embedded traceability from digital sensors lacking calibration documentation and legacy resistive architectures. Pricing pressure stems from MEMS fabrication scale economies in consumer electronics eroding industrial-grade average selling prices. Agricultural monitoring in developing markets exhibits highest price sensitivity, while pharmaceutical cleanroom applications show least elasticity due to FDA 21 CFR Part 11 compliance mandates.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for MEMS humidity sensors, with Germany and Switzerland hosting precision packaging and calibration operations. Polymer dielectric materials, CMOS readout circuits, and ceramic substrates constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundries serving consumer-grade volume production. Distribution runs through direct OEM relationships for pharmaceutical and HVAC segments, with distributor networks covering agricultural and industrial automation applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as post-pandemic building ventilation upgrades create niche demand for calibrated digital sensors with embedded diagnostics, splintering procurement authority away from consolidated system integrators toward specialized component vendors.
For Market Incumbents: Shield market position by deepening backward integration into polymer substrate production to offset REACH reformulation costs, while accelerating ISO/IEC 17025 accreditation acquisition to capture pharmaceutical procurement unbundling. Prioritize capacity expansion in Germany's industrial automation corridor to serve predictive maintenance demand from precision machining environments.
For New Entrants and Emerging Players: Anchor in sensor-to-cloud integration architectures combining LoRaWAN and NB-IoT protocols for unstaffed agricultural and warehouse monitoring, where legacy resistive substitution creates white-space opportunity. Target France and Italy's post-pandemic building retrofit wave with calibrated digital units priced below incumbent pharmaceutical tiers. Pursue direct facility manager relationships bypassing HVAC OEM specification control.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across MEMS-based humidity sensing as wafer-level packaging scale economies mature, compressing returns for undifferentiated volume producers. Long-term viability favors acquisition targets with captive CMOS-MEMS co-design capabilities and established ISO/IEC 17025 traceability infrastructure. Watch for inflection signals in ECHA polymer restriction enforcement accelerating European supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 17025 Accreditation Acquisition | Pharmaceutical procurement unbundling in Basel and Munich mandates certified supplier relationships. |
| Wafer-Level Packaging Scale-Up | East Asian foundry partnerships enable sub-2mm form factors for wearable device integration. |
| Sensor-to-Cloud Platform Integration | LoRaWAN and NB-IoT convergence opens unstaffed monitoring in remote agricultural applications. |
| Polymer Substrate Backward Integration | REACH compliance requirements force reformulation investment or captive material supply. |
| Direct Facility Manager Relationships | Post-pandemic HVAC retrofits in France and Italy bypass traditional OEM specification channels. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with HVAC procurement officers, pharmaceutical facility managers, MEMS fabrication engineers, and industrial automation maintenance directors; and secondary validation through SEC filings, ECHA restriction updates, FDA 21 CFR guidance documents, and EU Green Deal implementation tracking. Bottom-up sensor shipment estimates by application and technology triangulated against top-down market value reconstruction.
Across the projection horizon, the analytical framework modeled segmentation by product type, end user, technology, and application with regional regulatory cluster overlays. CAGRs derived from volume trajectory analysis calibrated against pricing tier evolution and certification penetration rates. Forecast inputs incorporated MEMS fabrication capacity expansion timelines and REACH polymer restriction implementation schedules.
Decision-makers should treat outputs as directional under sustained EPA Clean Air Act enforcement and EU F-Gas Regulation tightening; material deviation in regulatory implementation velocity or MEMS foundry regional disruption would warrant model refresh. Recalibration cycles align with material shifts in pharmaceutical procurement unbundling patterns and ECHA substrate reformulation completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market